
 Liquid Propellants Market | 2026-2036
Liquid Propellants Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Propellants Market Analytics
A shift from single-source government procurement to multi-source commercial contracting is decoupling propellant supply chains from traditional defense primes. SpaceX leverages vertical integration to control its own kerosene and liquid oxygen supply for Falcon operations. Northrop Grumman sustains long-standing hydrazine production dominance through captive manufacturing for strategic missile programs. ArianeGroup competes on cryogenic propellant logistics across European launch infrastructure.
Liquid propellants comprise energetic chemical formulations—typically oxidizers such as liquid oxygen paired with fuels including RP-1 kerosene or hydrazine derivatives—that combust under controlled conditions to generate thrust via expulsion through a converging-diverging nozzle. These formulations require precise mixture ratios, typically near 2.5:1 for LOX/kerosene systems, and function as the primary energy source for launch vehicles, orbital maneuvering, and missile propulsion. Cryogenic storage methods dominate high-performance applications where boil-off management and insulated tank design determine mission feasibility. Aerospace applications lead volume consumption, while commercial spaceflight represents the fastest-expanding demand pool as reusable launch architectures proliferate. Government agencies anchor the mature end-user segment through sustained defense and civil space budgets.
FAA launch licensing requirements and EPA hazardous waste regulations govern propellant transport, storage, and disposal practices across the United States. OSHA process safety management standards enforce handling protocols for toxic formulations including hydrazine and nitrogen tetroxide. Stakeholders must monitor evolving commercial space traffic management rules and environmental compliance thresholds as launch frequency scales.
Market Dynamics
Reusable launch architectures are compressing propellant consumption cycles, forcing suppliers to retool for rapid-turnaround logistics rather than batch-production for expendable vehicles. This shift from single-use to flight-proven hardware demands cryogenic storage systems capable of minimizing boil-off between rapid relaunches.
Growth Catalysts
- Commercial launch cadence:SpaceX, Blue Origin, and United Launch Alliance are scaling flight frequency, creating sustained pull for storable and cryogenic propellants. Reusable first stages require faster ground processing and replenishment cycles.
- EPA hazardous waste frameworks:Stricter disposal protocols for toxic formulations are consolidating handling expertise among certified operators, raising barriers that protect incumbent suppliers with established compliance infrastructure.
- Orbital refueling architectures:NASA and commercial operators are developing cryogenic transfer capabilities for lunar and deep-space missions, extending propellant demand beyond launch into on-orbit servicing.
Market Restraints
- Input cost volatility:Hydrazine and nitrogen tetroxide feedstock prices swing with specialty chemical supply chains concentrated in Texas and Louisiana petrochemical corridors.
- Supply concentration risk:Domestic liquid oxygen production clusters near Gulf Coast air separation facilities, exposing launch operators to hurricane-disruption vulnerabilities.
- Technical limitation:Long-duration cryogenic storage without boil-off remains unproven for Mars transit architectures, capping mission design flexibility.
Strategic Opportunities
- Underpenetrated geography:Alaska's Pacific Spaceport Complex offers polar launch trajectories with minimal air traffic conflicts, creating demand for localized propellant storage infrastructure.
- Regulatory tailwind:The FAA's streamlined Part 450 launch licensing reduces approval timelines for new entrants, accelerating propellant qualification cycles for emerging vehicle developers.
- Technology convergence:Additive manufacturing of regeneratively cooled thrust chambers is integrating with in-situ propellant production concepts for lunar surface operations.
Industry Challenges
- Toxic materials handling expertise:Hydrazine fueling operations require specialized technician certification that outpaces training pipeline capacity at Cape Canaveral and Vandenberg.
- Capex intensity:Cryogenic test stands and insulated transport trailers demand eight-figure capital commitments before first revenue flight.
- Integration complexity:Legacy missile programs using nitrogen tetroxide/MMH face obsolescence pressure as commercial launchers shift to LOX/methane architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Propellants Market |
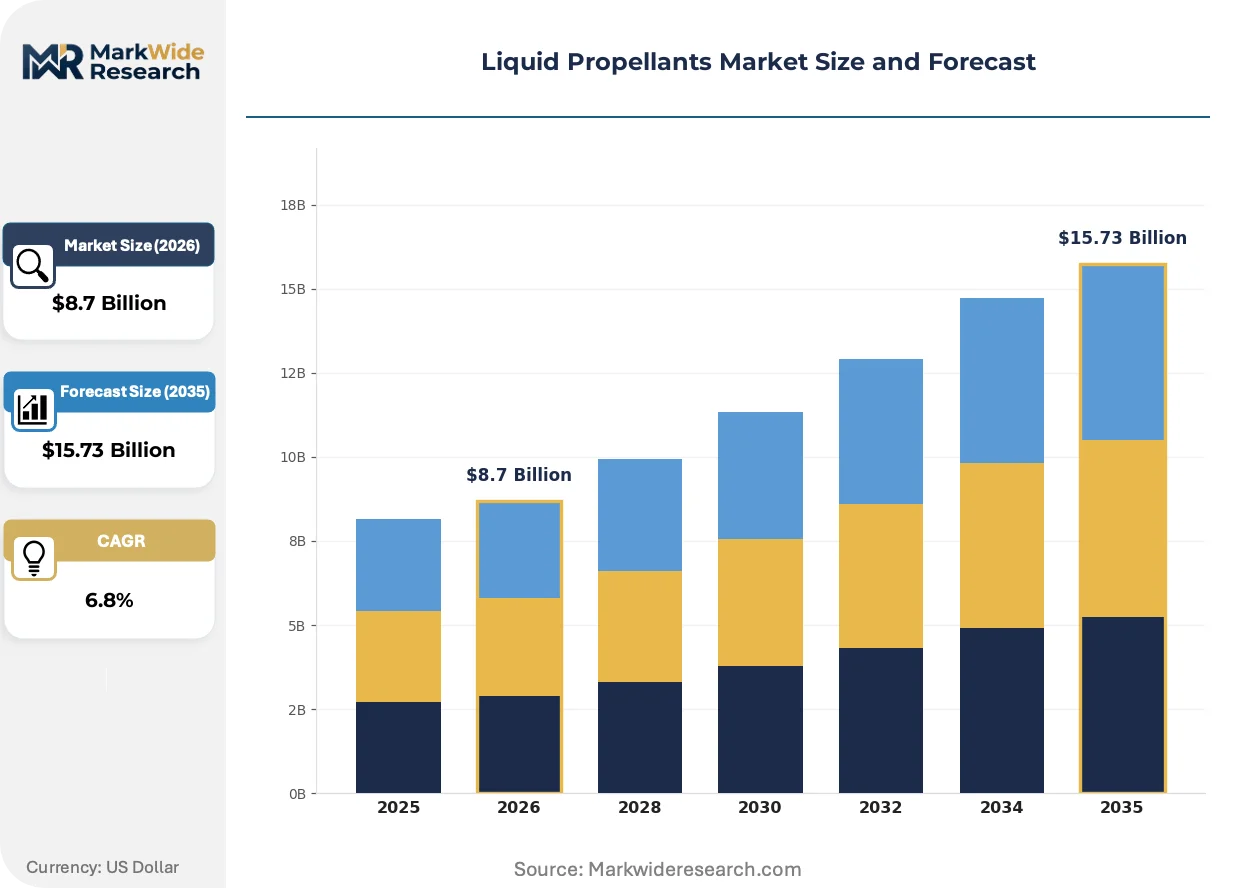
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propellant Type: Liquid Oxygen, Rocket Propellant-1, Hydrazine, Kerosene Application: Aerospace, Defense, Commercial Spaceflight, Satellite Launching End User: Government Agencies, Private Contractors, Research Institutions, Space Agencies Storage Method: Cryogenic Storage, Ambient Storage, Pressurized Tanks, Tank Farms |
| Companies Covered | SpaceX, Northrop Grumman, L3Harris Technologies, Blue Origin, ArianeGroup, Safran, Airbus, Lockheed Martin, Mitsubishi Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Propellants Market Evolving Landscape
Propellant supply chains are fragmenting from centralized government stockpiles toward distributed commercial networks serving multiple launch operators. This reconfiguration demands new storage modalities and logistics partnerships.
Methane liquefaction and densification technology is decentralizing propellant sourcing for next-generation launch vehicles. SpaceX's Raptor and Blue Origin's BE-4 engines both burn liquid methane, and coastal spaceports are installing modular liquefaction units to reduce transport distances. This distributed production model compresses dependency on Gulf Coast natural gas pipelines and enables launch-site fuel generation.
EPA's Risk Management Plan amendments for highly hazardous chemicals are tightening secondary containment and emergency response requirements for hydrazine storage facilities. Operators near populated areas face relocation pressure toward remote sites like White Sands Missile Range. Defense contractors with existing remote infrastructure are consolidating toxic propellant handling away from coastal launch complexes.
Long-term propellant purchase agreements are displacing spot-market procurement as launch operators seek supply security for manifest commitments. SpaceX and United Launch Alliance are negotiating multi-year offtake contracts with industrial gas suppliers, locking in volume and pricing for cryogenic commodities. This contractual shift is most visible in Texas, where SpaceX's Starbase operations anchor regional liquid oxygen demand.
Liquid Propellants Market Segmentation
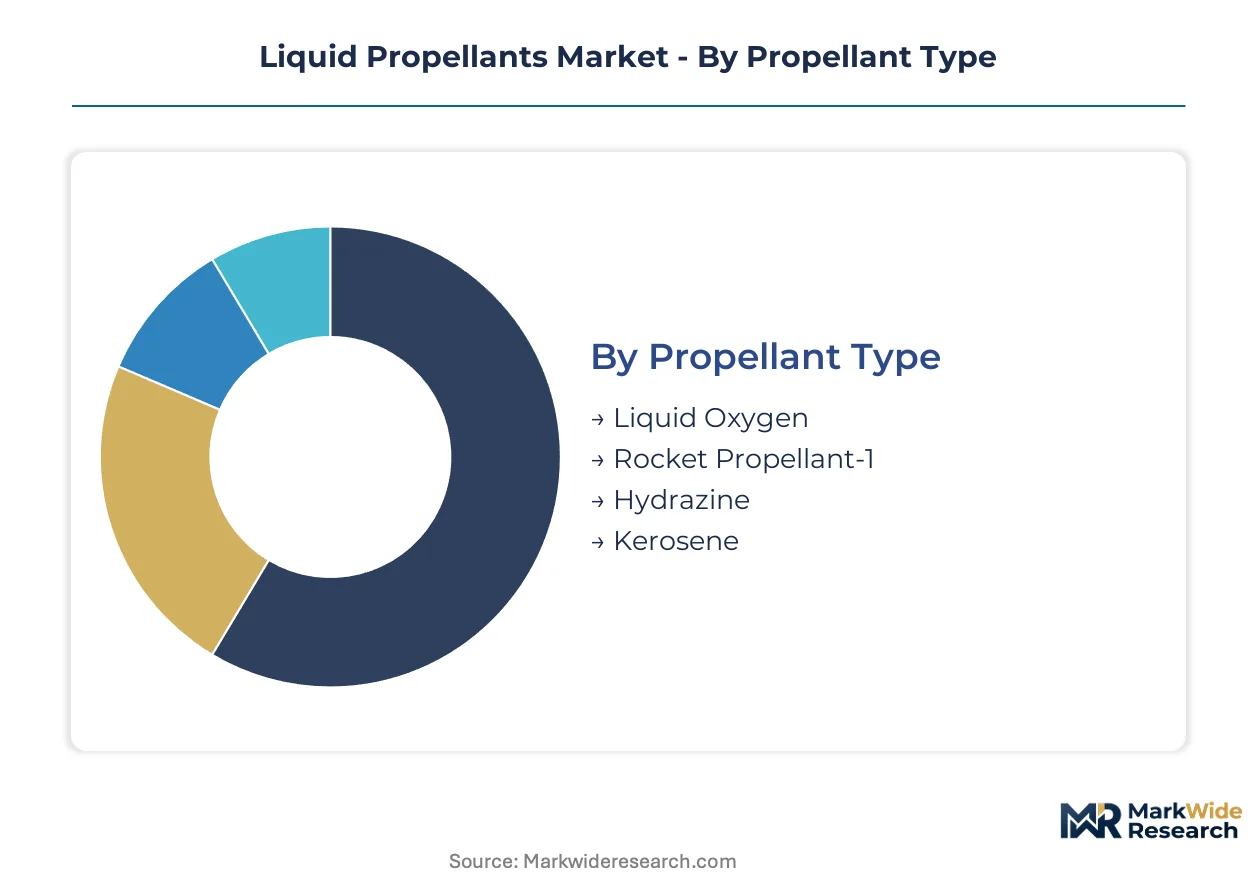
Liquid propellant suppliers configure production assets around distinct chemical families, each demanding specialized handling infrastructure and certification regimes. Segmentation by propellant chemistry, application vertical, end-user procurement patterns, and storage modality determines capital allocation and margin structure across the value chain.
Propellant Type:
Supply concentration clusters around cryogenic and storable formulations, with production assets anchored near Gulf Coast petrochemical corridors and coastal launch infrastructure.
- Liquid Oxygen:Cryogenic oxidizer produced via air separation units, stored at minus 183 degrees Celsius in vacuum-insulated vessels. Demand concentrates at SpaceX's Starbase operations in Texas, where rapid reusability cycles consume thousands of tons monthly. Boil-off management and transport logistics constrain supply radius to approximately 500 kilometers from production facilities.
- Rocket Propellant-1:Highly refined kerosene meeting stringent sulfur and aromatic specifications for regenerative cooling compatibility. United Launch Alliance's Delta and Atlas programs in Florida anchor procurement volumes, though SpaceX's Falcon family has shifted toward densified RP-1 formulations requiring subcooled storage systems.
- Hydrazine:Toxic monopropellant and fuel component for orbital maneuvering systems. Northrop Grumman's Redstone Arsenal operations in Alabama sustain domestic production dominance for strategic missile programs.
- Kerosene:Commercial aviation-grade fuel occasionally substituted for RP-1 in lower-performance applications. Refineries in Louisiana supply blended stocks to coastal spaceports lacking dedicated RP-1 infrastructure.
Liquid oxygen absorbs the bulk of installed capacity; cryogenic densification for reusable architectures is expanding most quickly.
Application:
Cost tier stratification separates high-volume commercial launch from mission-critical defense programs with stringent qualification requirements.
- Aerospace:Broad category encompassing crewed spacecraft, upper stages, and in-space propulsion. NASA's Artemis program drives demand for large-volume cryogenic transfers at Marshall Space Flight Center in Alabama.
- Defense:Strategic missile systems and tactical launch vehicles requiring storable propellants for rapid response. Minuteman III modernization and next-generation ICBM programs sustain hydrazine and nitrogen tetroxide procurement through established defense primes.
- Commercial Spaceflight:Reusable launch vehicles and suborbital tourism platforms. Blue Origin's New Shepard operations in West Texas consume liquid hydrogen and oxygen for each passenger flight, with refurbishment cycles compressing from months to weeks.
- Satellite Launching:Dedicated small-lift vehicles and rideshare missions. Rocket Lab's Electron operations at Wallops Island, Virginia, utilize RP-1 and liquid oxygen for frequent microsatellite deployments.
Defense applications absorb the bulk of long-term procurement commitments; commercial spaceflight is gaining share fastest.
End User:
Customer type determines contract structure, with government agencies favoring cost-plus arrangements and private operators negotiating fixed-price offtake agreements.
- Government Agencies:Department of Defense and NASA procure through multi-year indefinite-delivery contracts. Cape Canaveral's 45th Space Wing coordinates consolidated propellant purchasing for military launch manifests.
- Private Contractors:SpaceX, Blue Origin, and United Launch Alliance negotiate directly with industrial gas suppliers. SpaceX's vertical integration extends to captive liquid oxygen production at Boca Chica, reducing third-party dependency.
- Research Institutions:Universities and national laboratories operating suborbital sounding rockets and experimental propulsion test stands. White Sands Missile Range in New Mexico accommodates hazardous propellant research with remote-site advantages.
- Space Agencies:International partners including ESA and JAXA procuring through bilateral agreements or domestic suppliers. European launch operations at Kourou, French Guiana, source cryogenic propellants via ArianeGroup's dedicated logistics network.
Government agencies anchor the majority of contractual volume; private contractors are driving procurement innovation fastest.
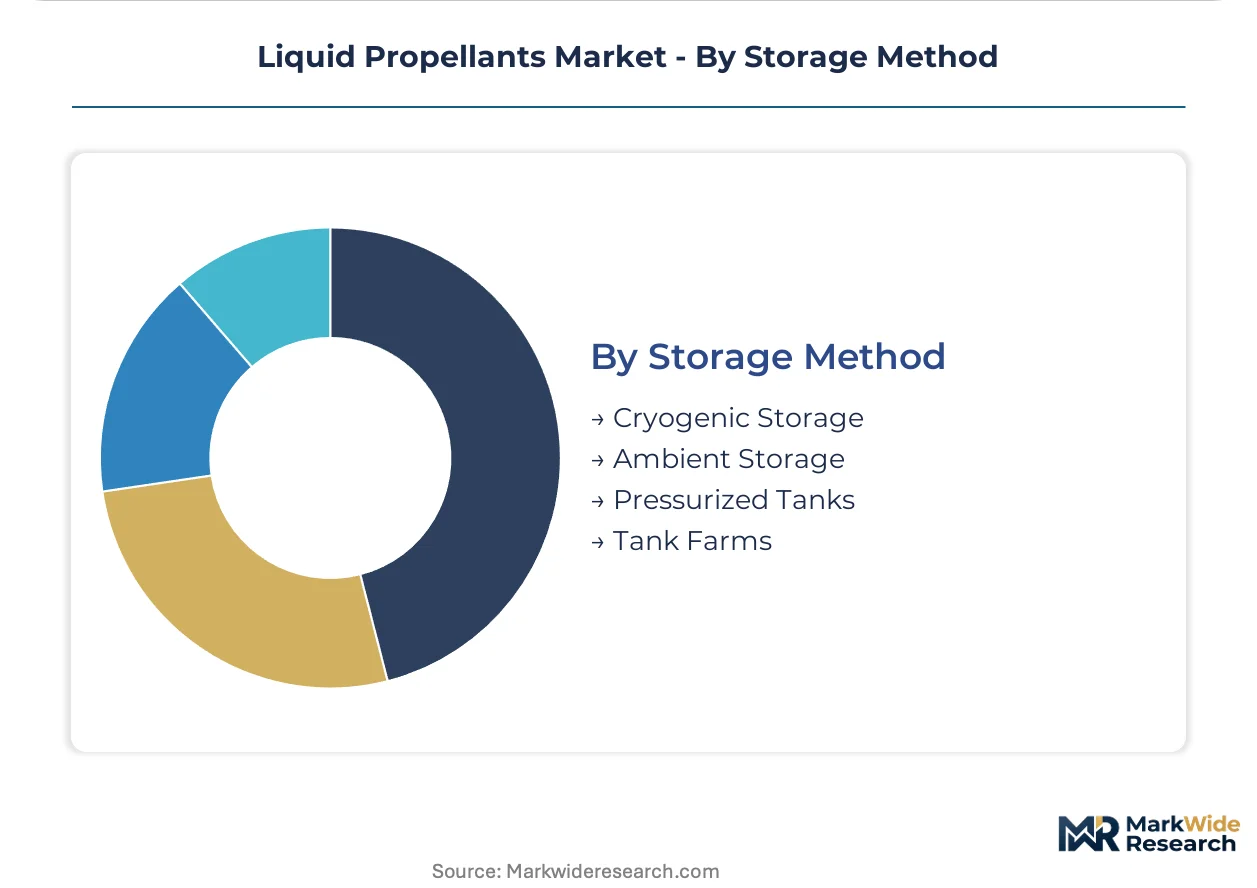
Storage Method:
Storage modality selection hinges on propellant volatility, mission timeline, and infrastructure investment capacity.
- Cryogenic Storage:Vacuum-insulated tanks with active cooling systems for liquid oxygen, hydrogen, and methane. SpaceX's Starbase features the largest commercial cryogenic farm in the United States, supporting same-day propellant loading for Falcon and Starship operations.
- Ambient Storage:Above-ground tanks for hydrazine, nitrogen tetroxide, and RP-1 at standard temperatures. Vandenberg Space Force Base maintains redundant ambient storage for polar launch manifests.
- Pressurized Tanks:Mobile and fixed vessels for hypergolic propellants requiring inert gas blankets. Kennedy Space Center's Launch Complex 39B employs pressurized systems for Orion service module fueling.
- Tank Farms:Consolidated storage complexes serving multiple launch operators. The Louisiana Offshore Oil Port corridor hosts emerging tank farm developments for methane liquefaction and coastal distribution.
Cryogenic storage commands the majority of capital deployment; methane liquefaction infrastructure is scaling most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Coast petrochemical corridors anchor liquid propellant feedstock availability, with air separation facilities clustering near Houston and Lake Charles to supply cryogenic oxidizers. Launch infrastructure concentrates along coastal spaceports where transport logistics minimize boil-off losses.
United States
SpaceX's Starbase operations in Texas consume thousands of tons of liquid oxygen monthly for rapid reusability cycles. FAA Part 450 launch licensing streamlines approval timelines for emerging vehicle developers at Cape Canaveral and Vandenberg. The Louisiana Offshore Oil Port corridor hosts emerging methane liquefaction infrastructure serving coastal distribution networks.
France
ArianeGroup maintains cryogenic propellant logistics dominance across European launch infrastructure at Kourou, French Guiana. ESA procurement frameworks govern bilateral supply agreements with international partners. The Paris-Saclay cluster anchors specialized handling expertise for nitrogen tetroxide storage systems.
Japan
Mitsubishi Heavy Industries sustains H3 launch vehicle propellant demand through Tanegashima Space Center operations. METI industrial policy supports domestic air separation capacity expansion for reduced import dependency. The Kyushu region concentrates launch infrastructure with specialized cryogenic handling protocols.
India
ISRO's Satish Dhawan Space Centre drives storable propellant procurement for PSLV and GSLV programs. BIS certification requirements govern hydrazine handling standards for strategic missile applications. The Sriharikota island facility maintains redundant ambient storage for polar and geostationary launch manifests.
United Arab Emirates
Mohammed bin Rashid Space Centre procurement is expanding for suborbital tourism and small satellite launch services. UAE Space Agency regulations are crystallizing propellant transport protocols for Al Dhafra Air Base operations. Dubai's logistics hub status attracts cryogenic commodity traders serving emerging Middle Eastern launch markets.
Liquid Propellants Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers retool for rapid-turnaround logistics rather than batch-production for expendable vehicles. The vendor base stratifies between defense primes with captive toxic propellant infrastructure and commercial operators pursuing vertical integration. Three archetypes prevail: vertically integrated launch operators controlling upstream supply, industrial gas majors with cryogenic distribution networks, and specialty chemical houses maintaining hydrazine production dominance. Geographic expansion and strategic partnerships represent the primary competitive vectors as launch cadence rises across multiple spaceports.
Within the defense prime tier, Northrop Grumman and Lockheed Martin exemplify established handling infrastructure for strategic missile programs. SpaceX occupies a distinct position through backward integration into liquid oxygen and kerosene supply for Falcon and Starship operations. Among European-based consortia, ArianeGroup anchors cryogenic logistics capabilities across French Guiana launch infrastructure.
| Leading Market Players |
|---|
| SpaceX |
| Northrop Grumman |
| L3Harris Technologies |
| Blue Origin |
| ArianeGroup |
| Safran |
| Airbus |
| Lockheed Martin |
| Mitsubishi Heavy Industries |
| Others |
Value Network & Pricing Analysis
EPA Risk Management Plan amendments for highly hazardous chemicals gate qualified supply access and premium-tier pricing for hydrazine and nitrogen tetroxide handlers. Facilities lacking secondary containment infrastructure face exclusion from defense prime procurement pools, compressing margins for uncertified operators while incumbents with remote-site capabilities capture pricing premiums.
Pricing Analysis
Warranty and service bundling separates long-term offtake contracts from spot-market transactions, with multi-year agreements from SpaceX and United Launch Alliance incorporating dedicated storage, transport, and boil-off guarantees. Price differentiation rests on certification tier—OSHA process safety management compliance versus standard handling protocols—and volume scale, with thousand-ton monthly consumers commanding leverage over small-lift operators. Cost compression in cryogenic commodities intensifies as SpaceX's captive liquid oxygen production at Starbase reduces third-party dependency. Small satellite launchers exhibit highest price sensitivity due to irregular manifest cadence, while defense primes with strategic missile programs demonstrate lowest sensitivity given mission-critical qualification requirements.
Supply Chain Analysis
Reverse-logistics flows for reusable launch architectures demand rapid-turnaround refurbishment cycles, with cryogenic storage systems recovered and redeployed between same-day relaunches at coastal spaceports. Production gravity centers on United States Gulf Coast air separation facilities, French Guiana cryogenic logistics networks, and Japanese Tanegashima infrastructure. Feedstock dependencies draw from natural gas pipelines for methane liquefaction, petroleum refining corridors for RP-1 kerosene, and specialty chemical plants for hydrazine precursors. Single-source vulnerability concentrates in Texas and Louisiana petrochemical corridors exposed to hurricane disruption. Distribution runs through consolidated tank farms serving multiple launch operators at Cape Canaveral, Vandenberg, and Starbase.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EPA hazardous waste frameworks raise compliance barriers that force smaller handlers without certified infrastructure toward exit or acquisition.
For Market Incumbents: Hedge against margin erosion by deepening backward integration into cryogenic production assets near launch infrastructure, mirroring SpaceX's Starbase model. Acquire toxic materials handling specialists at White Sands Missile Range and similar remote sites to consolidate defense prime relationships as coastal facilities face relocation pressure. Certification investment in OSHA process safety management tiering offers channel control against emerging entrants lacking established compliance infrastructure. For New Entrants and Emerging Players: E-commerce-enabled procurement platforms for research institutions and university suborbital programs offer lowest competitive intensity, with White Sands and Wallops Island operations presenting penetrable white-space targets. Alaska's Pacific Spaceport Complex polar trajectory demand remains underserved by incumbent cryogenic logistics networks. A direct-to-lab go-to-market angle emphasizing rapid small-batch qualification cycles bypasses long-term offtake contract barriers dominating commercial launch procurement. For Investors and Strategic Acquirers: FAA Part 450 streamlined licensing approval for new vehicle developers is the leading indicator that propellant qualification cycle velocity will accelerate, favoring suppliers with flexible certification infrastructure. Long-term viability over the next decade hinges on positioning for orbital refueling architectures extending demand beyond launch into on-orbit servicing. Acquisition targets should emphasize cryogenic transfer technology specialists and remote-site toxic handling operators with established defense relationships. Practitioners should monitor Starship orbital refueling demonstration milestones for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cryogenic Production | SpaceX's Starbase captive liquid oxygen supply reduces third-party dependency and transport cost exposure. |
| Remote Site Toxic Handling Consolidation | Defense contractors with White Sands infrastructure capture hydrazine procurement as coastal facilities relocate. |
| Long-term Offtake Contract Negotiation | United Launch Alliance multi-year agreements with industrial gas suppliers lock volume security for manifest commitments. |
| Methane Liquefaction Infrastructure Deployment | Coastal spaceport modular units enable launch-site fuel generation for Raptor and BE-4 engine operations. |
| Orbital Refueling Capability Development | NASA and commercial cryogenic transfer programs extend propellant demand into on-orbit servicing applications. |
Research Methodology
Independent corroboration across launch operator procurement executives, industrial gas supply chain managers, and EPA compliance officers underwrites the qualitative findings in this study. Primary interviews with cryogenic logistics specialists, defense prime propellant procurement leads, and commercial spaceport operations directors combined with secondary validation from FAA launch licensing databases, EPA Risk Management Plan filings, and SEC disclosures from aerospace contractors. Customs data on air separation unit imports and cryogenic transport equipment shipments anchored supply-side triangulation. Bottom-up propellant consumption estimates by launch vehicle class reconciled against top-down market value assessments.
Rate-of-change decomposition across the analysis window separates volume growth from pricing dynamics and mix shifts between propellant chemistries. Segmentation dimensions modeled include cryogenic versus storable formulations, commercial spaceflight versus defense applications, government agency versus private contractor procurement patterns, and cryogenic versus ambient storage modalities. CAGRs derived from historical launch cadence trajectories, reusable architecture adoption curves, and orbital refueling program development timelines. Industry-specific forecast inputs incorporated SpaceX Starbase consumption patterns and ArianeGroup Kourou logistics capacity expansions.
The model holds under sustained commercial launch cadence growth and stable EPA enforcement intensity; deviation in FAA regulatory streamlining pace or hurricane disruption frequency at Gulf Coast production clusters would shift trajectory. Forecasts reflect assumptions on reusable architecture market share progression and defense budget continuity for strategic missile modernization. Practitioners should monitor Starship orbital refueling demonstration schedules and Part 450 licensing approval velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Hydrogen Fuel Tanks Market
Fuels
Gas Hydrates Market
Fuels
Europe Bunker Fuel Market
Fuels
Palm Methyl Ester Market
Fuels
Europe Black and Wood Pellets Market
Fuels
Biobutanol Market
Fuels
Fuel Oxygenate Market
Fuels
Compressed Natural Gas Market
Fuels
United States Coal Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Gas and Solid Fuels (Wood) Fireplaces Market
Fuels
Middle-East and Africa Commercial Aircraft Aviation Fuel Market
Fuels
Petroleum Fuel Dyes Sales Market
Fuels
China LNG Market
Fuels
Global Industrial Burner Market