
 Canada Coal Market | 2026-2036
Canada Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Coal Market Outlook
Export logistics revenue is reconfiguring margin capture across the Canada coal value chain. Teck Resources leverages its integrated rail and port infrastructure to control metallurgical coal flows from British Columbia to Asian steel mills. Conuma Coal Resources anchors its position through specialized coking coal recovery from formerly idled mines in the Peace River region. Glencore competes via diversified commodity trading networks that buffer domestic production against international price cycles.
Canada coal encompasses carbonaceous sedimentary rock formations with calorific values ranging from sub-bituminous grades through high-rank anthracite, extracted via open-pit and underground longwall methods for combustion and reduction processes. Thermal coal shipments to electric utilities face structural decline as provincial grids integrate alternative baseload sources, while coking coal bound for steel manufacturers retains firmer demand through blast furnace dependency. Metallurgical processes applications command premium pricing due to specific volatile matter and coke strength requirements, whereas power generation volumes contract under federal emissions regulations and provincial coal phase-out mandates.
Environment and Climate Change Canada enforces the Output-Based Pricing System and coal-fired electricity regulations that constrain new thermal generation investments, while provincial regulators in Alberta and British Columbia administer mine permitting and reclamation bonds that shape operational cost structures. The Canadian Environmental Assessment Agency coordinates federal impact reviews for major mine expansions, extending approval timelines and capital commitment horizons. Stakeholders must monitor evolving carbon border adjustment mechanisms and steel industry decarbonization pathways that could abruptly revalue metallurgical coal demand.
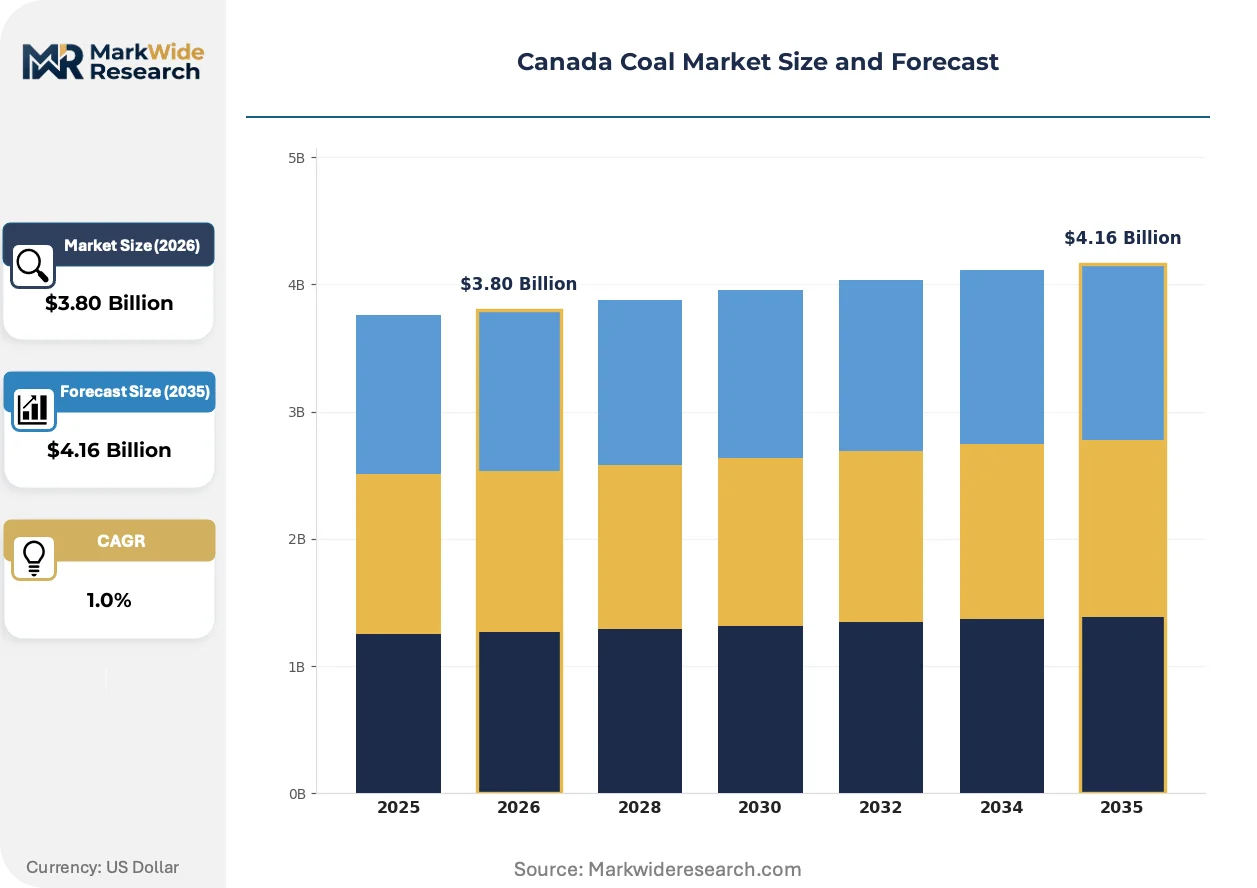
Market Dynamics
The federal carbon pricing framework and provincial coal phase-out mandates are compressing thermal coal demand while metallurgical coal retains structural support from Ontario and Quebec blast furnace operations.
Growth Catalysts
- Steel sector demand:Blast furnace operations in Ontario and Quebec sustain metallurgical coal consumption despite broader energy transition pressures.
- Export infrastructure:British Columbia's Ridley Island and Neptune terminals enable Pacific Rim coking coal shipments.
- Regulatory flexibility:Alberta's Technology Innovation and Emissions Reduction system allows compliance through intensity reductions rather than absolute caps.
Market Restraints
- Input cost volatility:Diesel fuel and ammonium nitrate prices fluctuate with crude oil benchmarks, squeezing open-pit mining margins.
- Supply concentration risk:Peace River coalfield operations depend on CN and CP rail corridors vulnerable to weather disruptions.
- Substitution threat:Electric arc furnace steelmaking and hydrogen-based direct reduction are eroding long-term coking coal demand.
Strategic Opportunities
- Carbon capture integration:Alberta's 45Q-equivalent tax credits incentivize CCUS deployment at coal-fired facilities.
- Reclamation contracting:Progressive mine closure bonds create service revenue streams for environmental remediation specialists.
- Biomass co-firing:Wood pellet substitution trials at remaining thermal plants offer compliance pathway under federal regulations.
Industry Challenges
- Specialized workforce attrition:Longwall mining technicians and certified blasters face generational replacement gaps as enrollment in mining engineering programs declines.
- Permitting timeline compression:Canadian Environmental Assessment Agency coordinated reviews extend major expansion approvals beyond capital commitment horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Coal Market |
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.16 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Coal, Thermal Coal, Coking Coal, Anthracite End User: Electric Utilities, Steel Manufacturers, Cement Producers, Chemical Industry Distribution Channel: Direct Sales, Wholesale Distributors, Online Platforms, Export Application: Power Generation, Metallurgical Processes, Heating, Carbon Production |
| Companies Covered | Teck Resources Limited, Conuma Coal Resources Limited, Peabody Energy Corp, Glencore, Westmoreland Mining LLC, Dodd's Coal Mining Company Ltd., Colonial Coal International Corp., SouthGobi Resources Ltd., Arch Coal Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Coal Market Strategic Shifts
Automation and environmental compliance technologies are reconfiguring operational economics across Canadian coal extraction and processing.
Autonomous haulage systems at British Columbia open-pit operations are rendering obsolete conventional truck-and-shovel labor models. Teck Resources and Conuma Coal have deployed Komatsu and Caterpillar driverless fleets at Elk Valley and Peace River sites. Labor productivity gains are compressing unit costs while reducing exposure to remote-site workforce housing constraints.
Environment and Climate Change Canada's Output-Based Pricing System tightens emissions intensity benchmarks annually. Coal-fired generators in Alberta face escalating compliance obligations or early retirement decisions. Utilities are responding with fuel switching to natural gas and renewable procurement under provincial clean electricity standards.
Steel mill procurement teams are consolidating supplier relationships around certified low-ash, low-sulfur coking coal specifications. Long-term offtake agreements are displacing spot market purchases for Asian buyers. British Columbia metallurgical coal producers are capturing this shift through quality premiums and dedicated vessel charter arrangements.
Canada Coal Market Segmentation
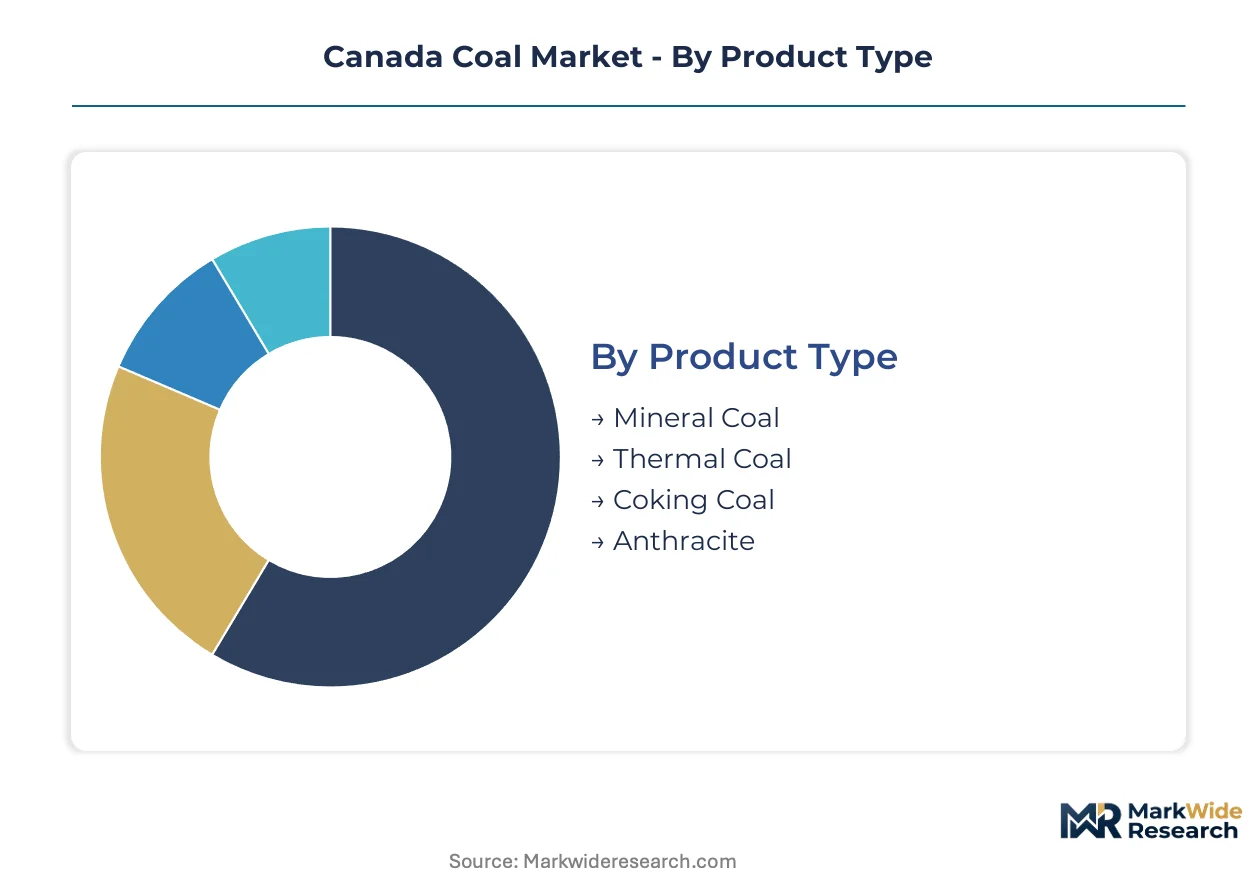
Canada's coal market segments reflect divergent demand trajectories. Metallurgical grades command premium pricing through steel sector dependency while thermal volumes contract under federal emissions policy. Understanding these segment dynamics illuminates where capital commitments and regulatory exposure concentrate.
Product Type:
Maturity varies sharply across product categories, with established metallurgical grades holding structural positions against declining thermal alternatives.
- Coking Coal:High-volatile bituminous grades with specific plasticity and coke strength indices serve blast furnace reduction chemistry. Ontario and Quebec steel manufacturers anchor domestic offtake while British Columbia export terminals handle Pacific Rim shipments. Federal carbon pricing exempts metallurgical end-uses, insulating demand from compliance cost pressures.
- Thermal Coal:Sub-bituminous and bituminous combustion grades face accelerated displacement. Alberta power generators under the Technology Innovation and Emissions Reduction system are retiring coal-fired capacity ahead of federal phase-out mandates. Provincial clean electricity standards are compressing remaining utility procurement volumes.
- Anthracite:Highest-rank carbon content supports specialized carbon black and silicon metal production in Quebec industrial zones.
- Mineral Coal:Lower-grade deposits serve regional heating markets and niche industrial applications in Atlantic Canada.
Coking coal handles the majority of throughput; thermal coal is contracting fastest on share.
End User:
Customer concentration patterns reveal where procurement power and long-term contracting discipline reside.
- Steel Manufacturers:Blast furnace operators in Hamilton, Sorel-Tracy, and Contrecoeur specify low-ash, low-sulfur coking coal blends. ArcelorMittal Dofasco and Algoma Steel maintain dedicated supplier relationships with British Columbia producers through multi-year offtake agreements.
- Electric Utilities:TransAlta and Capital Power are executing coal-to-gas conversions at Alberta generating stations. Remaining thermal coal burn concentrates at Keephills and Sheerness facilities pending final retirement dates.
- Cement Producers:Lafarge and Lehigh Hanson utilize coal as kiln fuel and raw material feedstock for clinker production.
- Chemical Industry:Alberta petrochemical complexes consume coal-derived feedstocks for ammonia and methanol synthesis.
Steel manufacturers dominate procurement volume; cement producers are expanding offtake most quickly.
Distribution Channel:
Channel economics hinge on cargo scale, destination distance, and infrastructure control.
- Export:Dedicated vessel loading at Ridley Island and Neptune terminals enables Pacific Basin coking coal deliveries. Teck Resources and Conuma Coal operate captive port capacity, capturing logistics margin that wholesale intermediaries cannot access.
- Direct Sales:Long-term supply agreements link Peace River coalfield operators to integrated steel mills, bypassing trader intermediation.
- Wholesale Distributors:Regional coal merchants handle residual thermal volumes for industrial and institutional heating in Ontario and Quebec.
- Online Platforms:Digital procurement channels remain marginal, limited to spot supplemental purchases and specialized carbon product grades.
Export channels move the greatest tonnage; direct sales are gaining contract share fastest.
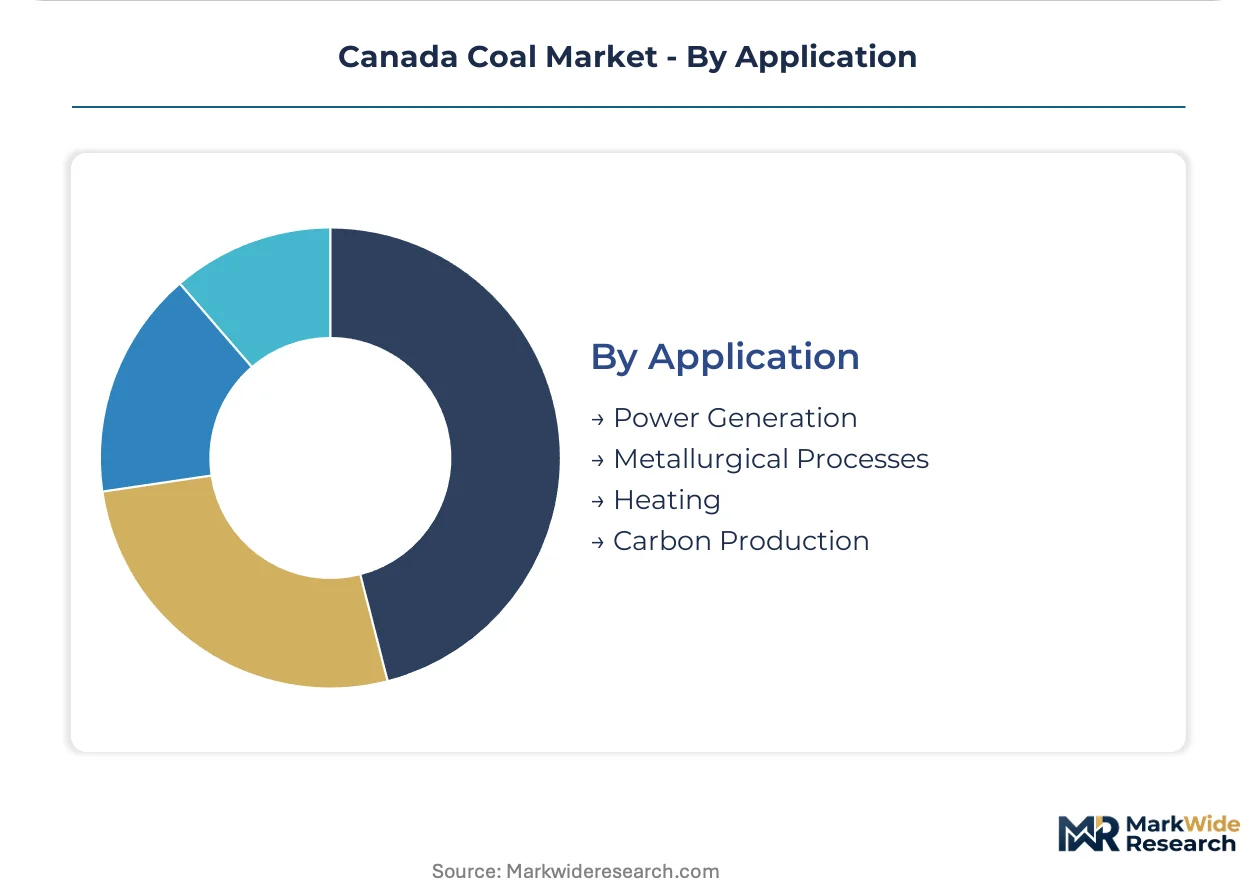
Application:
Application segmentation maps directly to diverging regulatory treatment and technology substitution risk.
- Metallurgical Processes:Coke oven battery operations require precise volatile matter and swelling index specifications. British Columbia mines tailor wash plant circuits to produce premium hard coking coal and semi-soft varieties for blend optimization.
- Power Generation:Pulverized coal combustion faces absolute capacity constraints under Environment and Climate Change Canada regulations. Remaining generators are trialing biomass co-firing to extend operational life.
- Heating:Residential and commercial coal consumption has collapsed to marginal levels in Nova Scotia and New Brunswick.
- Carbon Production:Activated carbon and electrode manufacturing in Quebec utilizes anthracite and calcined coal derivatives.
Metallurgical processes absorb the largest volume; carbon production is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peace River coalfield operations in British Columbia and foothills mining in Alberta concentrate Canadian metallurgical coal supply. Provincial regulatory regimes diverge sharply on carbon pricing implementation and mine permitting timelines. Export terminal capacity at Ridley Island and Neptune anchors Pacific Basin market access.
British Columbia
Elk Valley coking coal deposits feed Asian steel mill demand through dedicated port infrastructure. Environment and Climate Change Canada administers federal impact assessments for major mine expansions, extending approval timelines. Teck Resources operates integrated rail-to-ship logistics from Sparwood to Ridley Island.
Alberta
Foothills region thermal coal faces accelerated phase-out under provincial clean electricity standards. The Technology Innovation and Emissions Reduction system allows generators to comply through intensity reductions rather than absolute caps. Capital Power and TransAlta execute coal-to-gas conversions at Keephills and Sheerness facilities.
Ontario
Hamilton blast furnace operations sustain metallurgical coal demand for ArcelorMittal Dofasco steel production. Provincial emissions regulations exempt coking coal from carbon pricing applied to power generation. The Sarnia petrochemical corridor utilizes coal-derived feedstocks for ammonia synthesis.
Quebec
Sorel-Tracy and Contrecoeur steel mills specify low-ash coking coal blends from British Columbia suppliers. Algoma Steel maintains dedicated supplier relationships through multi-year offtake agreements. Quebec industrial zones consume anthracite grades for carbon black and silicon metal production.
Atlantic Canada
Nova Scotia and New Brunswick retain marginal coal consumption for regional heating and industrial applications. Provincial regulators administer mine reclamation bonds for formerly active Cape Breton operations. Sydney and Pictou County host limited mineral coal distribution for institutional buyers.
Canada Coal Market Competitive Environment
Integrated resource majors and specialized coking coal operators split the market between captive logistics control and regional deposit recovery. The vendor base concentrates around three strategic archetypes: diversified mining conglomerates with Pacific export infrastructure, pure-play metallurgical coal specialists revitalizing idled deposits, and trading houses buffering domestic production against international price cycles. Dominant competitive moves include backward integration into rail and terminal assets, plus portfolio diversification toward copper and zinc to offset coal price volatility.
Within the integrated infrastructure tier, Teck Resources exemplifies captive supply chain control from British Columbia pit to Asian vessel loading. Conuma Coal Resources occupies a position as a specialized operator focused on Peace River coalfield recovery. Glencore anchors the trading-house archetype, utilizing diversified commodity networks to manage price exposure.
| Leading Market Players |
|---|
| Teck Resources Limited |
| Conuma Coal Resources Limited |
| Peabody Energy Corp |
| Glencore |
| Westmoreland Mining LLC |
| Dodd's Coal Mining Company Ltd. |
| Colonial Coal International Corp. |
| SouthGobi Resources Ltd. |
| Arch Coal Inc |
| Others |
Value Chain & Pricing Dynamics
British Columbia's Elk Valley metallurgical coal concentration feeds directly into Teck Resources' captive port infrastructure at Ridley Island, concentrating margin capture at the export terminal tier rather than the mine mouth. This upstream geographic lock-in enables premium pricing to Asian steel mills while insulating domestic producers from spot market volatility.
Pricing Analysis
Long-term offtake contracts with Asian steel mills drive lifetime value beyond spot cargo premiums. Pricing stratifies across premium hard coking coal, semi-soft blending varieties, and standard PCI grades based on volatile matter specifications and coke strength indices. Cost compression in thermal coal tiers is intensifying because Alberta generators face accelerated retirement under provincial clean electricity standards. Electric utilities exhibit the highest price sensitivity as fuel-switching alternatives become cost-competitive, while steel manufacturers demonstrate lower sensitivity due to blast furnace chemistry requirements.
Supply Chain Analysis
Tariff exposure between Canada and China dominates supply chain risk calculus for Pacific Rim metallurgical coal shipments. Production draws from British Columbia's Peace River coalfield, Alberta's foothills region, and Saskatchewan's marginal deposits. Diesel fuel, ammonium nitrate explosives, and steel grinding media constitute critical input dependencies. Distribution runs through CN and CP rail corridors to Ridley Island and Neptune terminals, with single-source vulnerability concentrated in weather-prone mountain passes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
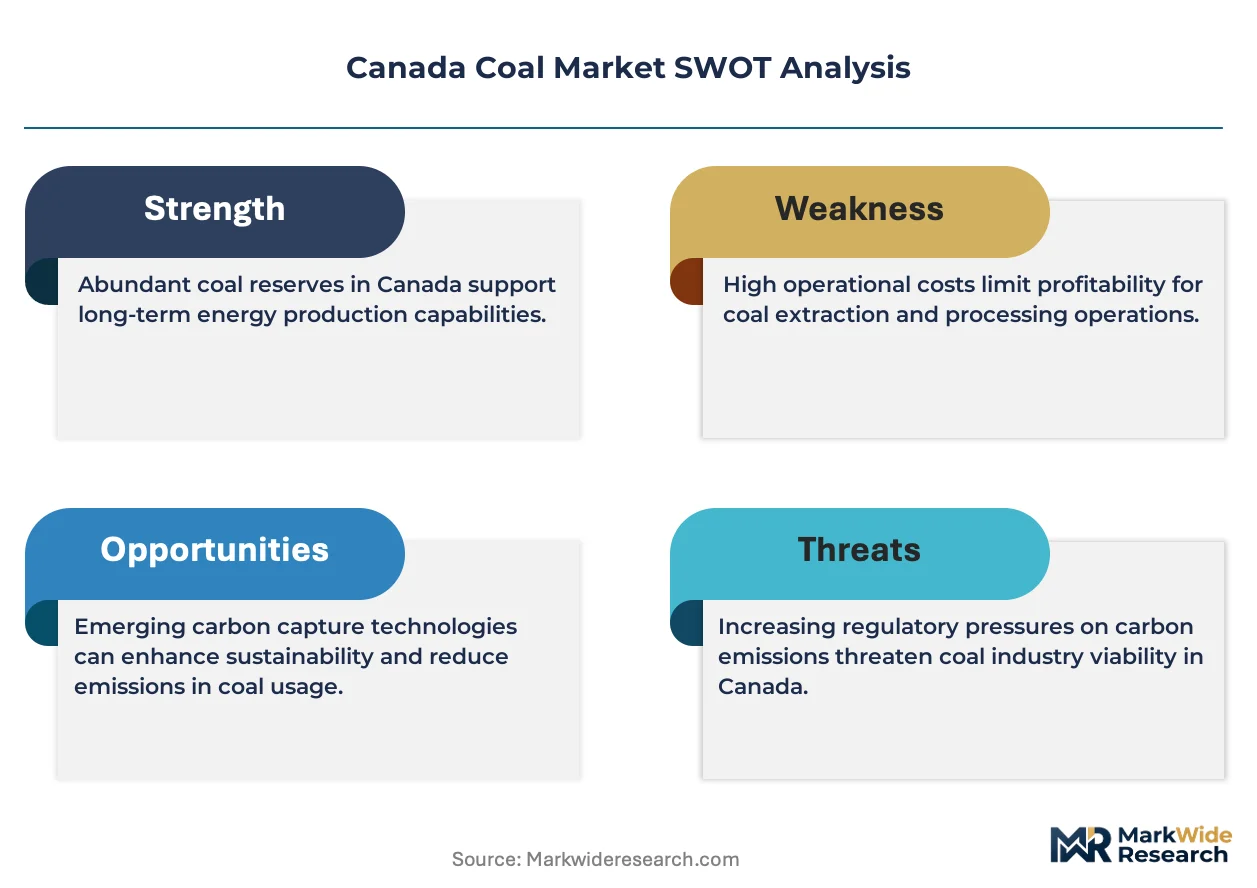
Canada's coal market faces high-growth disruption as hydrogen-based direct reduction technology threatens long-term blast furnace economics. Environment and Climate Change Canada's escalating carbon price trajectory accelerates this inflection for thermal coal while sparing metallurgical end-uses.
For Market Incumbents: Harden defensible positions through backward integration into captive rail and terminal infrastructure. Teck Resources' integrated Sparwood-to-Ridley Island logistics model demonstrates how upstream control over export channels buffers margin erosion from international price cycles. Prioritize low-ash, low-sulfur wash plant investments to capture quality premiums from consolidating Asian steel procurement teams.
For New Entrants and Emerging Players: Build out specialized reclamation contracting capabilities around progressive mine closure bonds in Alberta and British Columbia. The service revenue opportunity in environmental remediation outpaces new mine development given permitting timeline compression. Target carbon capture integration projects at remaining coal-fired facilities under Alberta's 45Q-equivalent tax credit regime.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pure-play metallurgical coal operators revitalizing formerly idled Peace River deposits. Long-term viability hinges on steel sector decarbonization pathways over a five-to-ten year window. Watch for electric arc furnace capacity announcements in Ontario and Quebec as the critical demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Export Terminal Investment | Ridley Island and Neptune capacity locks in Pacific Basin margin capture for British Columbia producers. |
| Carbon Capture Integration | Alberta's 45Q-equivalent credits create compliance pathways for remaining thermal generators. |
| Quality Premium Positioning | Low-ash coking coal specifications command dedicated vessel charters from Asian steel mills. |
| Reclamation Service Expansion | Progressive closure bonds generate recurring revenue streams as mine retirement accelerates. |
| Rail Corridor Diversification | Dual CN and CP access reduces weather-related supply disruption risk to export terminals. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with steel procurement managers, utility fuel planners, mine operations directors, and environmental compliance officers. Secondary validation drew from Environment and Climate Change Canada emissions filings, provincial energy regulator databases, Canadian Environmental Assessment Agency project records, and customs export statistics. Bottom-up volume modeling triangulated against top-down sectoral demand estimates to produce convergent market sizing.
Calibration against historical production volumes and announced capacity retirements anchored the analytical framework across the projection horizon. Segmentation dimensions included product type, end-use sector, distribution channel, and provincial regulatory cluster. CAGRs were derived from trend extrapolation moderated by policy scenario analysis. Forecast inputs incorporated steel mill decarbonization timelines, provincial coal phase-out mandates, and Asian import demand elasticity parameters.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hydrogen-based steelmaking technology developers or accelerated carbon border adjustment implementations would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Italy Chemical Logistics Market
Fuels
No.4 Fuel Oil Market
Fuels
Smart Gas Market
Fuels
CNG Dispenser Market
Fuels
Coal Trading Market
Fuels
Marine Fuel Filter Market
Fuels
North America Bunker Fuel Market
Fuels
Palm Methyl Ester Market
Fuels
Aboveground Fuel Storage Market
Fuels
Iso-Octane Market
Fuels
City Gas Distribution Market
Fuels
Collapsible Fuel Tank Market
Fuels
India LNG Market
Fuels
No.2 Diesel Fuel Market
Fuels
Wood Charcoal Market
Fuels
Alcohol-To-Jet (ATJ) Fuel Market