
 Manual Lifting Light Tower Market | 2026-2036
Manual Lifting Light Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Lifting Light Tower Market Insights
Multi-source procurement is broadening across rental fleets serving infrastructure and extractive industries. Atlas Copco sustains manufacturing scale across European and North American assembly plants for diesel-hybrid units. Generac Power Systems anchors its position through captive supply of portable generator sets integrated with light tower masts. Larson Electronics specializes in hazardous-location certified fixtures for oilfield and petrochemical deployment.
A manual lifting light tower is a mobile illumination system incorporating a telescoping mast raised by hand-crank or winch mechanism, typically supporting metal halide or LED arrays from 4 to 15 meters above ground level, powered by onboard diesel generators, battery banks, or solar arrays. Its primary purpose is to deliver temporary, high-intensity lighting for nighttime construction, emergency response, mining operations, and outdoor events where grid power remains unavailable. Trailer-mounted configurations occupy the largest installed base due to transport efficiency and rapid site-to-site relocation, while hybrid power sources represent the fastest-expanding segment as fuel costs and emissions compliance tighten operating budgets. Solar-powered units remain niche, constrained by battery energy density and higher upfront capital requirements that extend payback periods for seasonal users.
EPA Tier 4 Final standards and the EU F-Gas Regulation are reshaping generator-set specifications, compelling manufacturers to integrate after-treatment systems or abandon diesel-only architectures. OSHA workplace illumination requirements and ISO 8528 power quality standards further constrain product design, particularly for mining and emergency services deployments where failure tolerance approaches zero. Stakeholders must weigh retrofit compatibility against full-platform replacement as battery-hybrid architectures mature and total-cost-of-ownership calculations shift.
Market Dynamics
EPA Tier 4 Final emissions mandates are compressing diesel-only architectures and forcing rental fleets toward hybrid powertrains, reshaping procurement specifications across highway maintenance and mining corridors.
Growth Catalysts
- EPA Tier 4 Final:Rental companies in Texas and Alberta are accelerating diesel-hybrid fleet turnover to avoid penalties and secure municipal contracts.
- Mining corridor expansion:Queensland's extractive operations demand trailer-mounted units for 24-hour pit illumination, sustaining replacement cycles.
- LED retrofit compatibility:Existing metal halide masts accept LED arrays without mast replacement, lowering upgrade friction for seasonal users.
Market Restraints
- Battery energy density limits:Solar-powered units require oversized battery banks that extend payback periods beyond typical rental depreciation schedules.
- Generator-set supply concentration:After-treatment system sourcing clusters among Tier 1 automotive suppliers, creating procurement bottlenecks for small-batch tower manufacturers.
- Substitution by grid-temporary power:Microgrid deployments at remote construction sites reduce reliance on fully mobile illumination for long-duration projects.
Strategic Opportunities
- Hazardous-location certification gap:Oilfield operators in Alberta seek explosion-proof fixtures beyond standard OSHA compliance, rewarding specialized engineering.
- EU F-Gas Regulation:European rental fleets face refrigerant-phaseout timelines that favor battery-hybrid cooling architectures over conventional generator sets.
- Telematics convergence:GPS-enabled run-time monitoring integrated with maintenance scheduling software creates subscription revenue streams for fleet lessors.
Industry Challenges
- After-treatment technician scarcity:EPA Tier 4 Final diesel systems require specialized exhaust-fluid handling and DPF regeneration protocols that strain field-service capacity.
- ISO 8528 certification timelines:Power quality validation for mining and emergency services extends product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Lifting Light Tower Market |
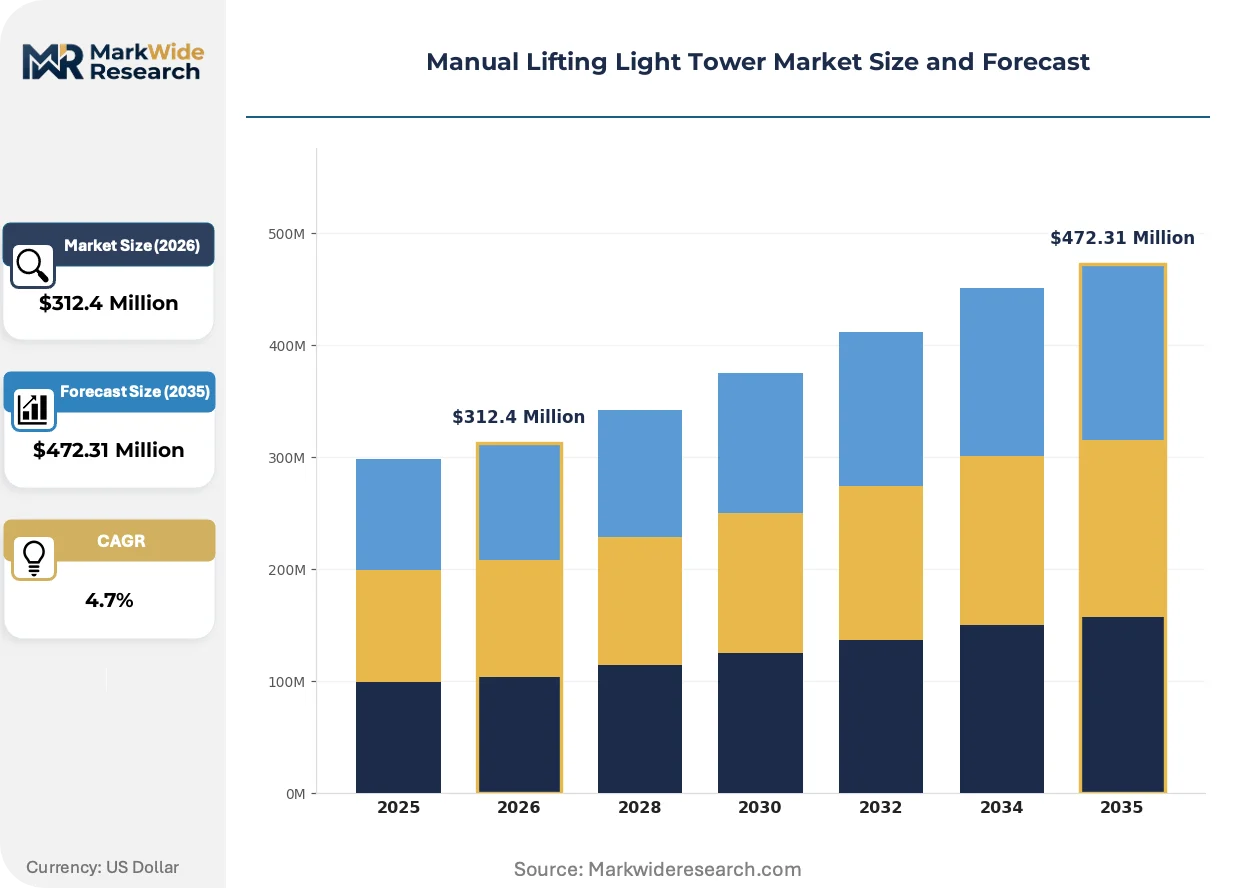
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trailer Mounted, Truck Mounted, Portable Tower, Fixed Tower, Trailerless Deployment Type: On-Demand, Permanent Setup, Temporary Setup, Mobile Operations End User: Construction Firms, Event Management, Emergency Services, Mining Operators, Film Production Power Source: Diesel Generator, Battery Operated, Solar Powered, Hybrid Systems |
| Companies Covered | Allmand Bros., Atlas Copco, Caterpillar, Doosan Portable Power, Generac Power Systems, HIMOINSA, J C Bamford Excavators, Larson Electronics, Trime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Lifting Light Tower Market Trends and Innovations
Hybrid power architectures are displacing conventional diesel-only systems as fuel-cost volatility and emissions compliance tighten operating budgets across rental and construction verticals.
Lithium iron phosphate battery packs are integrating with variable-speed generator sets to enable load-following operation. Highway maintenance contractors in Texas are specifying these configurations for overnight lane closures. The technology is integrating silent-running modes that eliminate noise complaints in residential-adjacent work zones, compressing the competitive advantage of traditional diesel-only rental fleets.
EU F-Gas Regulation phase-down schedules are forcing refrigerant choices in generator-set cooling circuits. Manufacturers serving European rental markets must redesign thermal management or abandon diesel-only platforms entirely. Mining and petrochemical deployments face the steepest re-engineering costs due to explosion-proofing requirements叠加 on emissions compliance.
Equipment-as-a-service contracting is replacing outright purchase for seasonal construction users. Rental companies unbundle maintenance and fuel management from daily rates, shifting margin capture to operational services. This pattern concentrates in Alberta and Queensland where project-based demand creates utilization volatility that favors flexible cost structures over capital ownership.
Manual Lifting Light Tower Market Segmentation
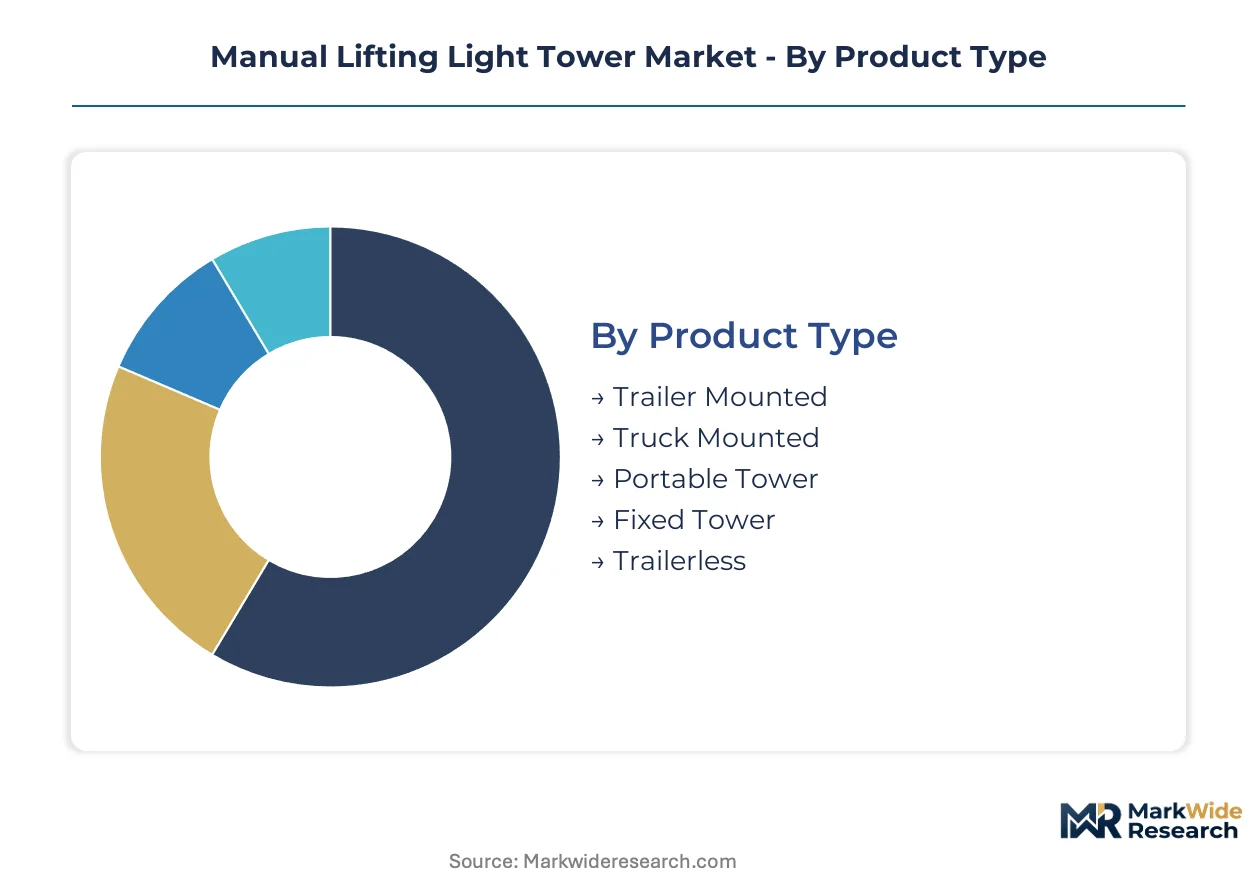
Segmentation in manual lifting light towers reveals how procurement priorities diverge across rental fleets, project-based contractors, and permanent industrial installations. Buyers weigh transport efficiency against power autonomy and regulatory compliance when matching tower configurations to operational requirements.
Product Type:
Transport logistics and site mobility requirements dominate buyer selection criteria, with highway regulations and terrain access dictating chassis configurations.
- Trailer Mounted:These units integrate telescoping masts onto highway-legal trailers with surge brakes and DOT-compliant lighting. Texas and Alberta rental fleets prioritize this format for rapid deployment across multi-site highway maintenance contracts where towing capacity already exists in contractor vehicle pools.
- Portable Tower:Compact units with collapsible masts and wheeled bases allow hand-positioning without mechanical lifting equipment. Event management operators in Queensland favor these for festival grounds where vehicle access remains restricted and setup crews work without heavy machinery.
- Truck Mounted:Direct chassis integration eliminates separate towing assets but requires dedicated vehicle allocation. Mining operators specify these for pit illumination where continuous relocation demands integrated mobility.
- Fixed Tower:Permanent foundation-mounted installations serve long-duration construction sites and security perimeters. These sacrifice mobility for structural stability in high-wind conditions.
- Trailerless:Skid-mounted or frame-based units ship on flatbeds and deploy with site cranes. Remote oilfield camps in Alberta accept this tradeoff where helicopter transport or seasonal ice roads preclude conventional towing.
Trailer mounted configurations lead on scale across rental and construction verticals; portable towers lead on momentum in event and emergency response applications.
Deployment Type:
Project duration and utilization predictability determine whether buyers favor capital ownership, short-term rental, or flexible operational contracts.
- Temporary Setup:Contract-based deployment spanning weeks to months dominates highway maintenance and seasonal construction. Queensland mining contractors specify these arrangements to match equipment life to extraction permit timelines without residual asset risk.
- Mobile Operations:Continuous relocation across dispersed sites characterizes emergency response and film production workflows. These users prioritize rapid mast deployment and compact transport footprints over power efficiency.
- On-Demand:Event-driven rental with 24-48 hour fulfillment windows concentrates in urban markets where staging yard proximity compresses logistics costs.
- Permanent Setup:Foundation-mounted installations serve security and industrial yard lighting where multi-year illumination needs justify fixed infrastructure over recurring mobilization expenses.
Temporary setup leads on scale across extractive and infrastructure verticals; mobile operations lead on momentum in emergency services and entertainment production.
End User:
Regulatory exposure and operational risk tolerance shape specification intensity across buyer categories, with hazardous-location requirements segmenting procurement tiers.
- Construction Firms:General contractors and specialty trades constitute the largest addressable base, with highway maintenance divisions in Texas driving diesel-hybrid adoption to meet municipal emissions clauses.
- Mining Operators:Pit illumination demands 24-hour reliability in dust-laden, high-vibration environments. Queensland surface operations sustain replacement cycles where metal halide-to-LED retrofits extend mast service life.
- Emergency Services:Disaster response and search-and-rescue units prioritize silent-running battery modes for residential-adjacent operations and rapid deployment without fuel logistics.
- Event Management:Festival and outdoor entertainment producers balance noise restrictions against illumination coverage, favoring hybrid units in noise-sensitive urban peripheries.
- Film Production:Location cinematography requires flicker-free LED arrays with precise color temperature control, commanding premium specifications for night shooting continuity.
Construction firms lead on scale across product categories; mining operators lead on momentum in hazardous-location certified equipment procurement.
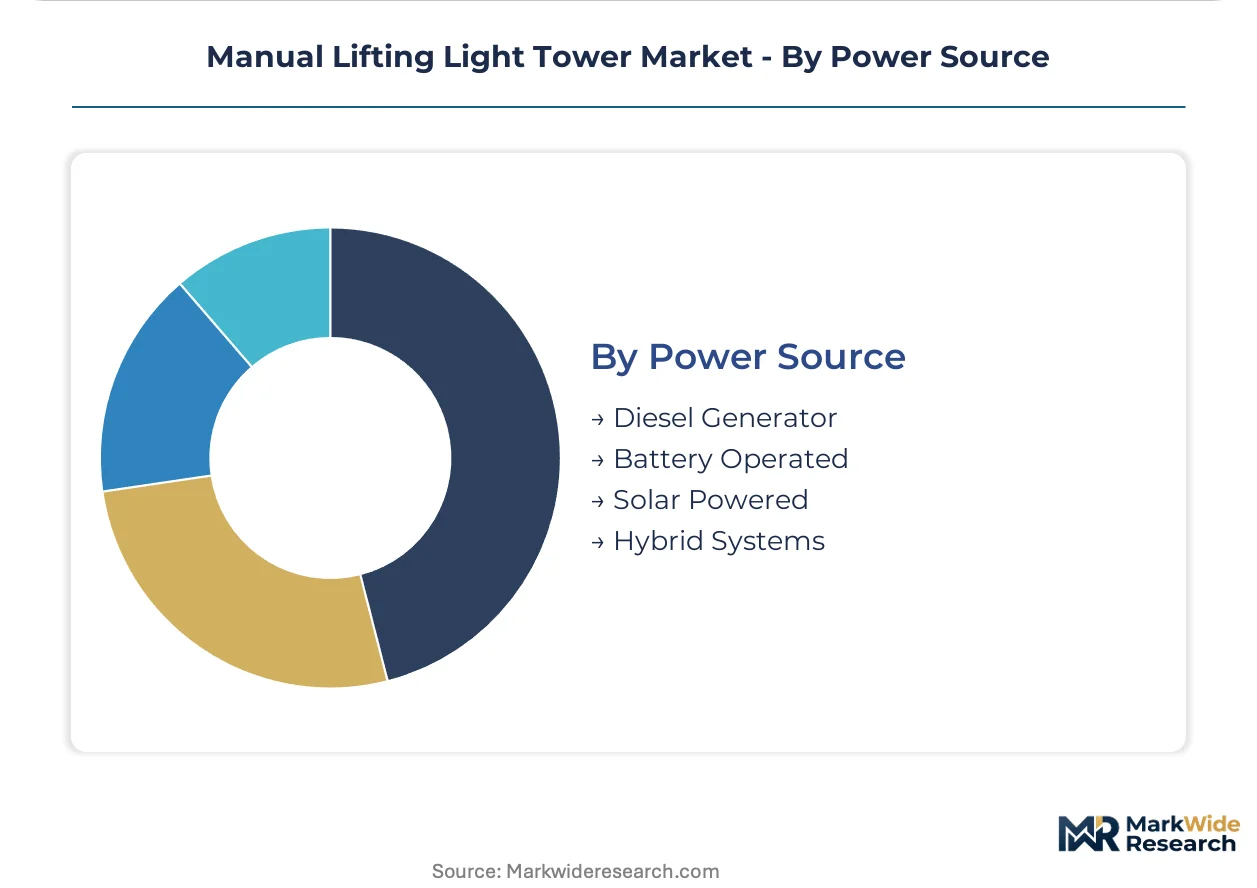
Power Source:
Fuel cost volatility and emissions compliance timelines are compressing diesel-only architectures while battery-hybrid systems capture share in regulated corridors.
- Diesel Generator:Conventional onboard power dominates installed rental fleet value, though EPA Tier 4 Final after-treatment requirements are extending procurement lead times and service complexity.
- Hybrid Systems:Variable-speed generator sets paired with lithium iron phosphate batteries enable load-following operation and silent modes. Texas highway contractors specify these configurations to eliminate noise complaints in residential-adjacent work zones.
- Battery Operated:Grid-charged or solar-recharged pure battery systems serve short-duration applications where runtime requirements remain below 8 hours and noise restrictions are absolute.
- Solar Powered:Photovoltaic arrays with oversized battery banks remain niche, constrained by capital intensity and extended payback periods that exceed typical rental depreciation schedules.
Diesel generator configurations lead on scale across legacy rental fleets; hybrid systems lead on momentum in emissions-regulated jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's mining corridors anchor procurement intensity for trailer-mounted diesel-hybrid units serving 24-hour pit operations. EPA Tier 4 Final compliance timelines and EU F-Gas refrigerant phase-downs are compressing fleet turnover cycles across regulated jurisdictions.
United States
Texas highway maintenance contractors drive diesel-hybrid adoption to satisfy municipal emissions clauses in state procurement contracts. EPA Tier 4 Final enforcement accelerates rental fleet replacement as penalties threaten contract eligibility. The Permian Basin oilfield corridor sustains demand for hazardous-location certified fixtures beyond standard OSHA workplace illumination requirements.
Canada
Alberta's oil sands and conventional extraction operations require explosion-proof lighting architectures for petrochemical deployment environments. Health Canada and provincial regulators enforce emissions standards that parallel EPA frameworks, pushing rental companies toward hybrid powertrains. Edmonton and Calgary equipment yards concentrate fleet staging capacity for seasonal construction mobilization.
Australia
Queensland surface mining operations sustain replacement cycles where metal halide-to-LED retrofits extend mast service life in dust-laden conditions. The country's national emissions reduction commitments pressure diesel-only fleet configurations. Bowen Basin coal corridors and Mount Isa mineral districts concentrate trailer-mounted unit deployment for continuous pit illumination.
Germany
EU F-Gas Regulation phase-down schedules force refrigerant choices in generator-set cooling circuits for rental fleets serving construction verticals. KBA emissions certification requirements extend product validation timelines for manufacturers supplying European markets. Bavaria and North Rhine-Westphalia industrial zones anchor distribution logistics for hybrid unit penetration into Central European infrastructure projects.
Brazil
ANVISA industrial safety standards intersect with emissions compliance for mining and agricultural applications requiring mobile illumination. The country's national development bank infrastructure lending stimulates highway maintenance equipment procurement. Minas Gerais iron ore corridors and São Paulo state construction markets concentrate demand for trailer-mounted configurations with rapid site-to-site relocation capability.
Manual Lifting Light Tower Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-hybrid specialization and hazardous-location certification gaps. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive generator-set supply, specialized lighting engineers with explosion-proof expertise, and regional fabricators serving project-based rental demand. Competitive positioning hardens through backward integration into generator-set manufacturing and telematics-enabled service contracting that shifts margin capture from equipment sales to operational subscriptions.
Within the diversified industrial tier, Atlas Copco and Caterpillar exemplify scale-driven manufacturers with transcontinental assembly footprints and integrated powertrain supply chains. Generac Power Systems anchors the captive-supply archetype through in-house production of portable generator sets integrated with light tower masts. Larson Electronics occupies the hazardous-location specialization vector, representing engineering-intensive positioning for oilfield and petrochemical deployment requirements.
| Leading Market Players |
|---|
| Allmand Bros. |
| Atlas Copco |
| Caterpillar |
| Doosan Portable Power |
| Generac Power Systems |
| HIMOINSA |
| J C Bamford Excavators |
| Larson Electronics |
| Trime |
| Others |
Pricing and Supply Chain Analysis
Rental fleet operators in Texas and Alberta concentrate procurement volume, anchoring contract-based pricing with fuel-management bundling that shifts margin capture from daily rates to operational services. This buyer concentration compresses price transparency and rewards suppliers with captive generator-set production and telematics-enabled maintenance subscriptions.
Pricing Analysis
Input-cost pass-through from lithium iron phosphate battery packs and EPA Tier 4 Final after-treatment systems compresses margins for diesel-hybrid configurations. Three-tier pricing structure across premium, standard, and economy levels separates hazardous-location certified fixtures from general construction units from basic trailer-mounted towers. Cost compression in standard-tier metal halide retrofits is intensifying because LED array prices decline and rental depreciation schedules shorten. Seasonal construction contractors exhibit highest price sensitivity, while mining operators in Queensland accept premium positioning for explosion-proof reliability.
Supply Chain Analysis
Direct-to-rental-fleet channels handle highway maintenance and mining corridor demand, bypassing distribution intermediaries for volume contracting. Manufacturing concentrates in the United States, Germany, and China for generator-set integration and mast fabrication. Battery cell sourcing draws from South Korean and Chinese suppliers, creating tariff exposure as trade policy shifts. Distribution runs through regional equipment yards in Edmonton, Calgary, and Dallas-Fort Worth that stage inventory for seasonal mobilization cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The manual lifting light tower market functions as a stable compounder where infrastructure maintenance obligations and mining extraction timelines generate recurring replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Extend telematics-enabled service contracting to capture subscription revenue from runtime monitoring and predictive maintenance scheduling. Deepen backward integration into variable-speed generator-set manufacturing to secure supply continuity as after-treatment system sourcing bottlenecks persist. Anchor fleet renewal partnerships with Texas municipal procurement programs to lock out hybrid-competitor penetration. For New Entrants and Emerging Players: The price-point gap between premium hazardous-location certified units and economy trailer-mounted towers opens white-space targeting for mid-tier hybrid configurations with silent-running modes. Solar-battery units for short-duration event management in Queensland represent the most penetrable segment where incumbent rental fleets underinvest. Pursue equipment-as-a-service contracting to bypass capital-sale barriers against established fleet operators. For Investors and Strategic Acquirers: Diversified industrial conglomerates with captive powertrain supply are the most active acquirer in this space, seeking bolt-on lighting specialists to complete jobsite equipment portfolios. Five-to-ten-year viability rests on hybrid architecture transition completion and telematics platform integration. Watch EPA enforcement intensity and EU F-Gas implementation timelines as inflection indicators for fleet replacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Integration | Variable-speed generator-battery pairing satisfies EPA Tier 4 Final and noise restrictions in residential zones. |
| Hazardous-Location Certification Investment | Explosion-proof fixture engineering captures premium positioning in Alberta oil sands and petrochemical deployment. |
| Telematics Platform Deployment | GPS-enabled runtime monitoring creates recurring subscription revenue from rental fleet lessors. |
| Backward Integration into Generator Sets | In-house portable power production insulates against after-treatment system procurement bottlenecks. |
| Equipment-as-a-Service Contracting | Operational subscription models shift margin capture from capital sales to maintenance and fuel management. |
Research Methodology
Bottom-up rental fleet modeling reconciled against top-down generator-set manufacturing tracking forms the analytical core of this study. Primary interviews with equipment procurement managers at highway maintenance contractors, mining operations directors, rental fleet asset managers, and aftermarket service heads combined with secondary validation from EPA enforcement disclosures, EU F-Gas regulatory filings, and customs trade data for diesel generator and battery cell imports. Cross-referencing bottom-up deployment estimates with top-down production volumes from assembly plants in the United States and Germany ensures triangulation integrity.
Historical trendline analysis of metal halide-to-LED retrofit cycles and diesel-hybrid fleet penetration rates established baseline growth patterns across the projection horizon. Segmentation modeling spans product type, deployment arrangement, end-use vertical, and power source architecture, with particular attention to regulatory compliance tier and geographic emissions jurisdiction. CAGRs derive from fitted trend extrapolation adjusted for EPA Tier 4 Final phase-in timelines and lithium iron phosphate cost curves. Forecast inputs include mining permit issuance velocity in Queensland and Texas state infrastructure appropriation levels.
Caveats apply where battery energy density breakthroughs or grid-temporary microgrid substitution could materially shift the outlook for solar-powered and diesel-only configurations respectively. Periodic stress-testing of base assumptions against actual fleet turnover data and regulatory enforcement intensity is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Air/Pneumatic Balancers Market
Material Handling Equipment
Automatic Conveyor Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market