
 Helpdesk Management Market | 2026-2036
Helpdesk Management Market Size, Share, and Industry Trends Forecast 2026-2036
Helpdesk Management Market Foresight
Aftermarket service revenue is reconfiguring how software vendors monetize customer relationships. Zendesk leverages its omnichannel architecture to capture enterprise renewals. ServiceNow anchors high-value workflow automation across IT and HR service desks. Freshdesk competes aggressively on price for mid-market SaaS contracts.
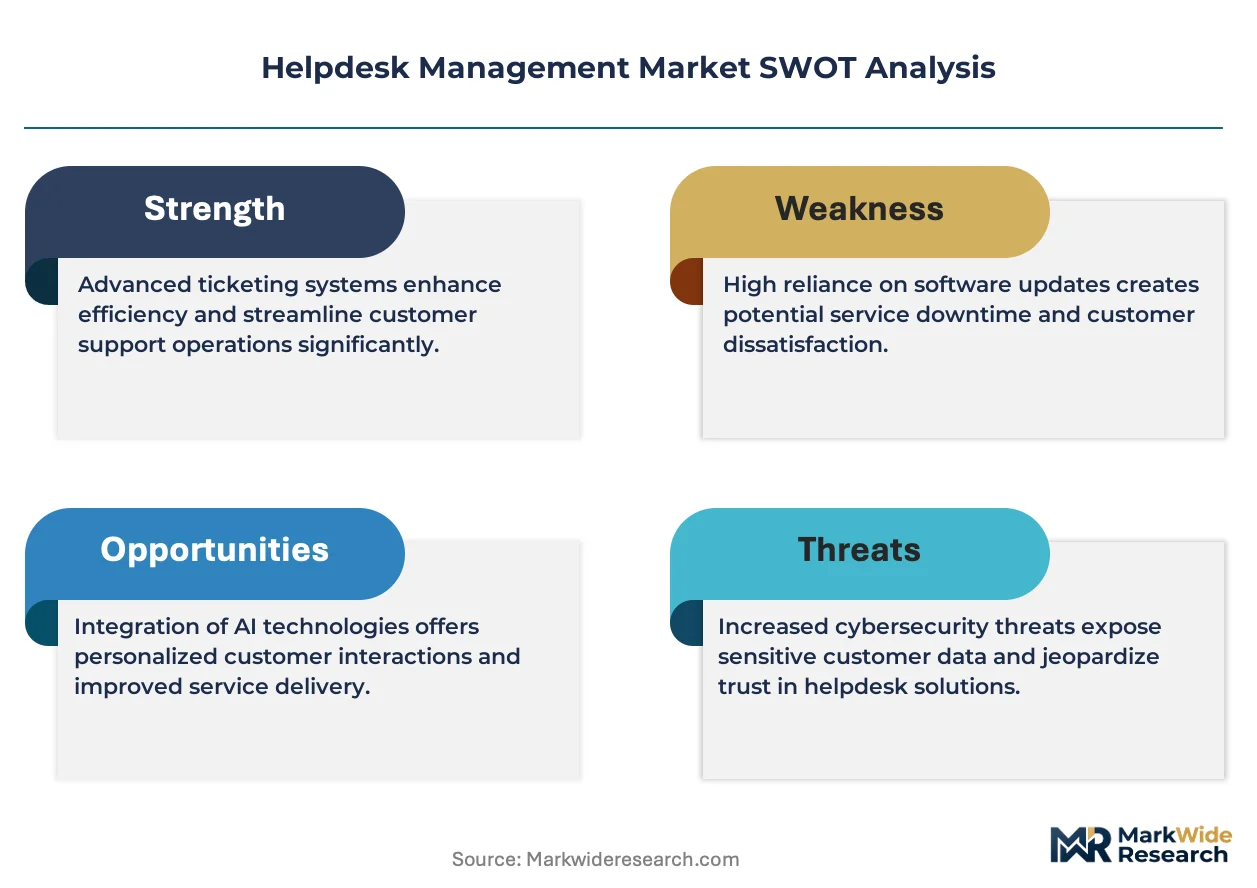
Helpdesk management comprises integrated software platforms that route, track, and resolve customer or internal service requests through ticket lifecycle workflows, typically incorporating SLA timers, knowledge bases, and escalation rules. These systems serve commercial and industrial organizations by reducing mean time to resolution and preserving operational continuity. Cloud-based deployment leads absolute spending as enterprises abandon on-premise maintenance burdens, while AI-powered tools represent the fastest-expanding technology segment as natural language processing automates tier-one triage. Ticketing systems retain the largest installed base but face margin compression from commoditized entry-level offerings.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements on European helpdesk deployments, compelling vendors to localize inference and audit automated decision paths. In the United States, HIPAA and state-level privacy statutes tighten access controls for healthcare-sector implementations. Stakeholders must weigh sovereign AI infrastructure commitments against the cost advantages of centralized cloud training pipelines.
Market Dynamics
Cloud migration is dismantling on-premise helpdesk infrastructure as IT services teams prioritize subscription-based consumption models over capital-intensive deployments. This shift compresses vendor margins while expanding addressable markets through reduced entry barriers.
Growth Catalysts
- Generative AI triage:Natural language processing automates tier-one ticket classification, reducing mean time to resolution for enterprise service desks. Healthcare and financial services verticals deploy these tools most aggressively.
- GDPR Article 22 compliance:European enterprises must maintain human oversight of automated decision-making, creating demand for explainable AI modules within helpdesk platforms. Vendors localize inference infrastructure to satisfy data residency requirements.
- India's PLI scheme for IT hardware:Domestic manufacturing incentives reduce datacenter equipment costs, accelerating cloud helpdesk adoption among mid-market Indian enterprises previously priced out of SaaS tiers.
Market Restraints
- Compute cost volatility:GPU scarcity and cloud provider pricing power inflate AI inference expenses, squeezing margins for vendors offering embedded machine learning features at fixed subscription rates.
- European vendor concentration:GDPR-compliant hosting infrastructure clusters in Ireland, Germany, and France, creating single-region dependency risks for enterprises requiring sub-50ms latency guarantees.
- Technical debt lock-in:Legacy on-premise ticketing systems with customized workflow engines resist API-based migration, extending sales cycles and inflating professional services costs for replacement projects.
Strategic Opportunities
- Underpenetrated German Mittelstand:Mid-sized industrial enterprises in Baden-Württemberg and Bavaria still operate email-based support workflows, presenting greenfield SaaS conversion potential.
- IT-HR service desk convergence:Unified platforms managing employee onboarding tickets alongside technical incidents capture cross-departmental budgets and reduce vendor proliferation.
- EU AI Act algorithmic auditing:Mandatory documentation requirements for high-risk AI systems create recurring revenue streams for vendors offering compliance-as-a-service modules.
Industry Challenges
- Prompt engineering talent scarcity:Helpdesk vendors compete with hyperscalers for natural language processing specialists capable of tuning retrieval-augmented generation pipelines for domain-specific ticket classification.
- HIPAA Business Associate Agreement complexity:Healthcare sector deployments require extended legal review cycles averaging 4-6 months, delaying revenue recognition and inflating customer acquisition costs.
- Multi-cloud orchestration friction:Enterprises demanding portability across AWS, Azure, and Google Cloud infrastructure force vendors into costly abstraction layer development without corresponding pricing power.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helpdesk Management Market |
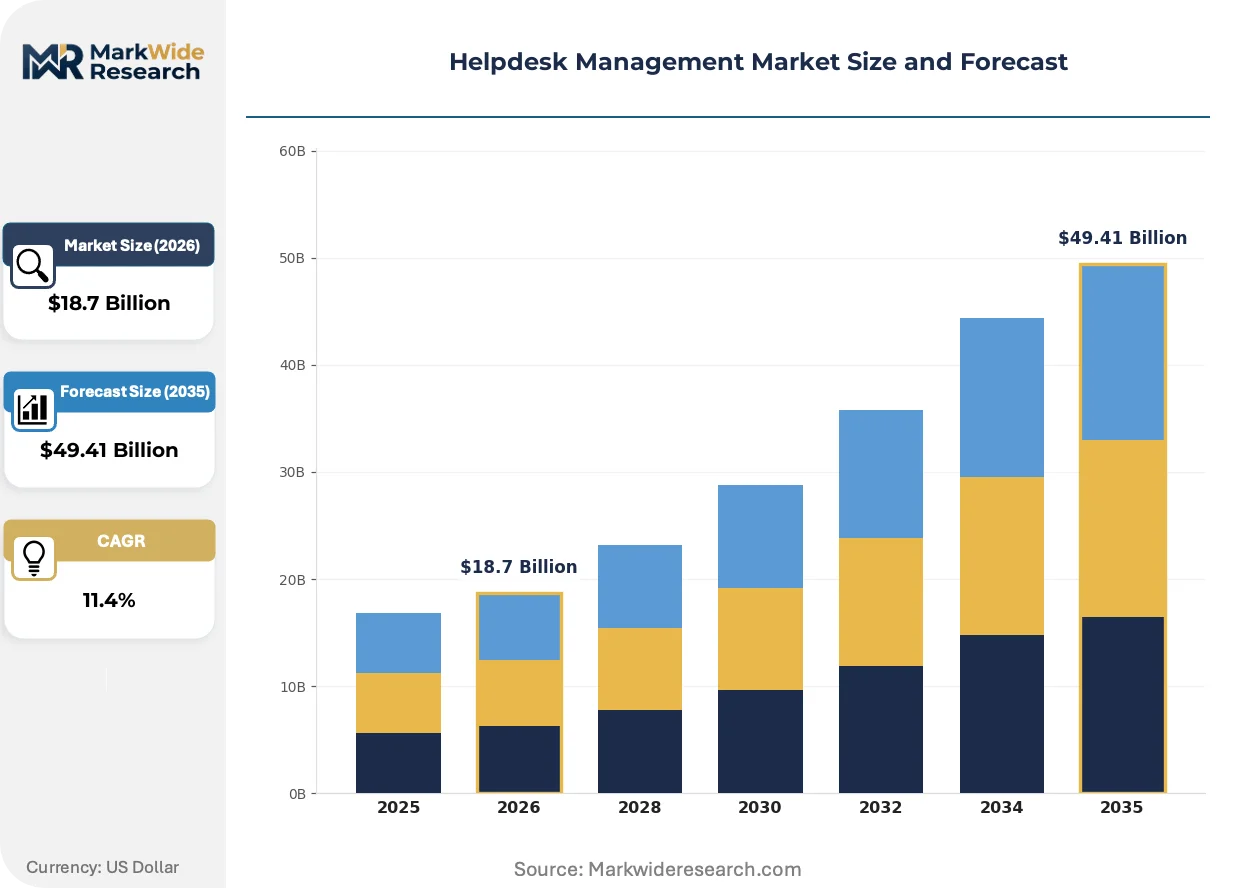
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Email Support, Phone Support, Live Chat, Ticketing Systems Deployment: Cloud-Based, On-Premise, Hybrid, SaaS End User: Retail, IT Services, Healthcare, Education Technology: AI-Powered Tools, Automation Software, CRM Integration, Mobile Access |
| Companies Covered | Zendesk, Freshdesk, ServiceNow, Jira Service Management, Zoho Desk, Help Scout, HappyFox, Kayako, LiveAgent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helpdesk Management Market Shifts & Advancements
Artificial intelligence is rewriting service desk economics by compressing resolution timelines and expanding self-service containment rates. Three converging developments are redefining platform architecture and procurement patterns.
Conversational AI is hybridizing rule-based ticketing with generative response synthesis. Enterprise IT departments in the United States and Germany deploy these systems to handle password resets and access requests without human agent involvement. The technology is hybridizing tier-one support roles into exception-handling functions while collapsing traditional escalation hierarchies.
The EU AI Act's risk classification framework imposes documentation and human oversight mandates on automated ticket routing systems processing sensitive personal data. European helpdesk vendors must maintain algorithmic audit trails and designate qualified personnel for high-risk deployment reviews. Healthcare and public sector implementations face the steepest compliance burdens, with some German municipalities delaying AI rollouts pending regulatory clarity from national data protection authorities.
Enterprise buying committees now demand consumption-based pricing tied to resolved ticket volumes rather than per-agent seat licenses. This model transfers operational risk to vendors while aligning costs with realized value. North American technology companies and Indian business process outsourcing firms have adopted this structure most rapidly, pressuring incumbent vendors to restructure contractual frameworks.
Helpdesk Management Market Segmentation
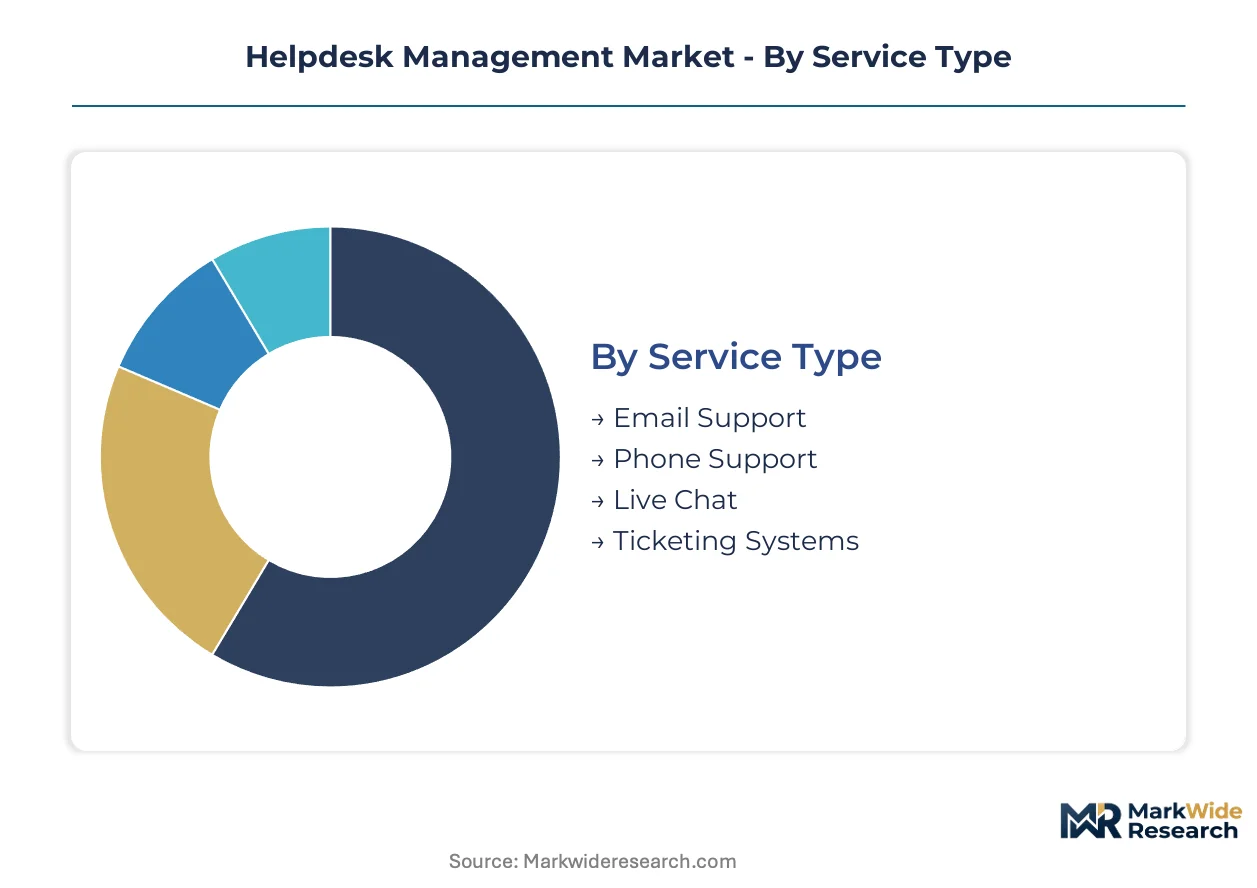
Helpdesk management platforms fragment across service modalities, infrastructure models, and intelligence layers. Procurement patterns diverge sharply between enterprises optimizing for compliance-heavy verticals versus those prioritizing cost-efficient ticket throughput.
Service Type:
Use-case spectrum spans synchronous crisis resolution to asynchronous workflow orchestration, with channel selection driven by incident severity and customer demographic preferences.
- Email Support:Asynchronous ticket logging with threaded conversation history and automated SLA acknowledgment. Manufacturing and B2B wholesale operations in Germany rely on this channel for non-urgent technical documentation requests, constrained by GDPR data retention audit requirements.
- Phone Support:Voice-based escalation path for high-severity incidents requiring immediate human judgment. US healthcare providers maintain this as the mandatory channel for patient-critical system outages under HIPAA contingency protocols, though staffing costs pressure migration to lower-touch alternatives.
- Live Chat:Real-time text interface blending bot-initiated triage with agent takeover triggers. Indian e-commerce platforms deploy this for cart-abandonment recovery and payment troubleshooting, capturing conversion events that asynchronous channels forfeit.
- Ticketing Systems:Centralized request routing with workflow automation, priority queuing, and resolution tracking. IT services teams across all geographies treat this as the foundational record-keeping layer, though interface commoditization compresses differentiation margins.
The dominant share belongs to Ticketing Systems, while Live Chat is closing the gap fastest.
Deployment:
Cost tier stratification separates capital-intensive ownership from operational expenditure models, with latency requirements and data sovereignty dictating hybrid architectures.
- Cloud-Based:Third-party hosted infrastructure with elastic compute scaling and managed security patching. Mid-market US technology firms favor this for rapid geographic expansion without datacenter construction delays, though egress fees accumulate unpredictably.
- On-Premise:Self-managed server deployment with direct hardware control and customized network segmentation. French defense contractors and German automotive suppliers mandate this for air-gapped environments handling classified or competitively sensitive operational data.
- Hybrid:Split workload distribution keeping sensitive data local while bursting compute-intensive analytics to public cloud. European pharmaceutical distributors adopt this to satisfy EMA pharmacovigilance data residency rules while leveraging AWS machine learning for demand forecasting.
- SaaS:Subscription software access with zero infrastructure ownership and automatic feature updates. Indian business process outsourcing firms standardize on this model to minimize upfront capital requirements and accelerate seat scaling for seasonal contract fluctuations.
Cloud-Based deployments hold the largest installed base, yet Hybrid configurations are expanding most quickly among regulated industries.
End User:
Application intensity varies by sector-specific compliance burden and ticket volume seasonality, with IT Services acting as the demand amplification engine.
- Retail:High-volume seasonal support with surge staffing and returns-processing integration. US omnichannel retailers deploy AI triage for Black Friday volume spikes, facing margin pressure from free shipping policy enforcement.
- IT Services:Technical incident management with SLA-backed response commitments and multi-tenant architecture requirements. Managed service providers in India and Germany compete on mean-time-to-resolution metrics, driving automation investment to reduce per-ticket labor costs.
- Healthcare:Patient data handling with HIPAA or GDPR health data safeguards and audit trail mandates. US hospital systems extend helpdesk platforms to medical device troubleshooting, requiring FDA-validated change control procedures.
- Education:Distributed user base with semester-based demand cycles and limited IT budgets. German universities and US community colleges prioritize self-service knowledge bases to offset lean staffing ratios during enrollment peaks.
IT Services commands the dominant share, while Healthcare is gaining share fastest due to compliance-driven platform consolidation.
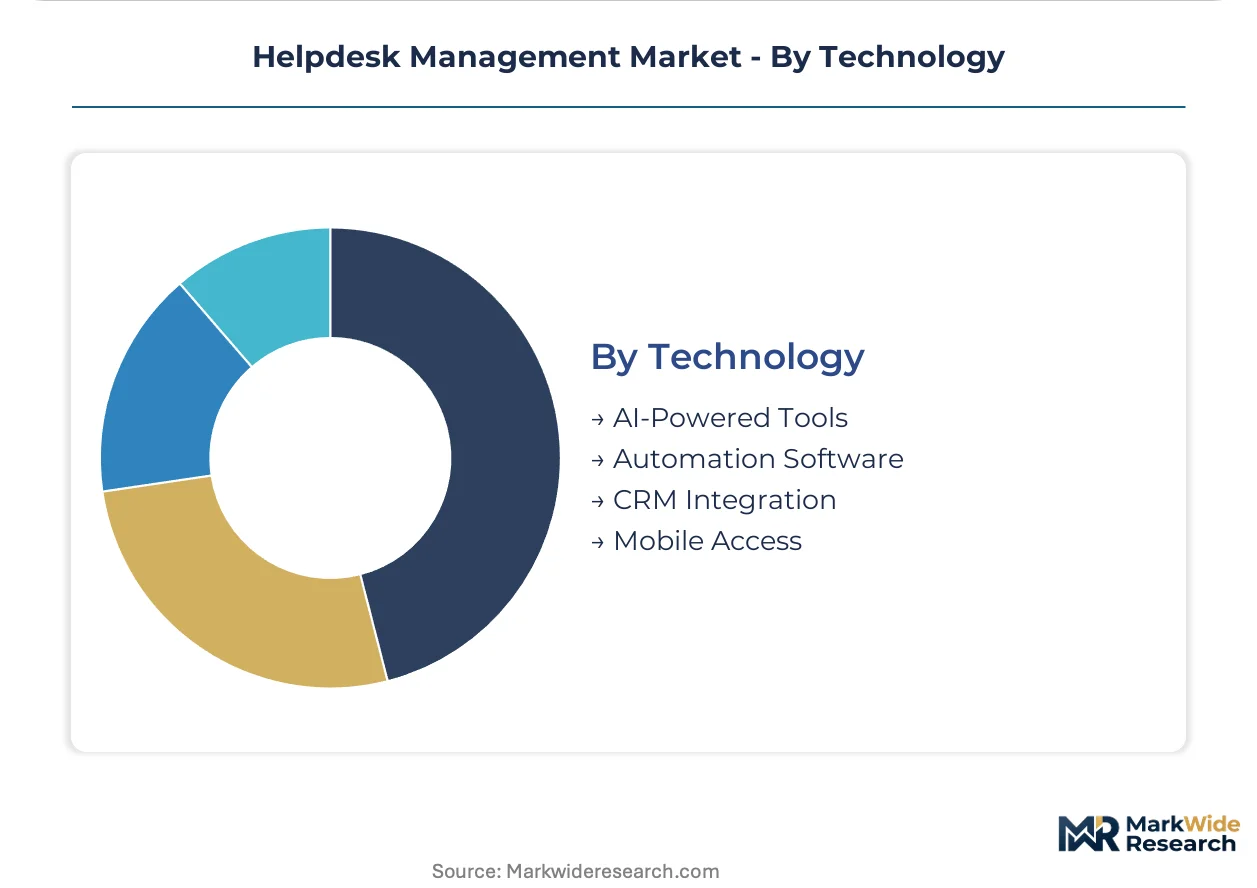
Technology:
Maturity gradients separate proven integration layers from emerging intelligence capabilities, with mobile access now table stakes rather than differentiator.
- AI-Powered Tools:Natural language processing for intent classification, sentiment analysis, and generative response drafting. US financial services and German insurance verticals deploy these for first-line policy inquiry handling, constrained by EU AI Act documentation requirements for automated decision pathways.
- Automation Software:Rule-based workflow orchestration with conditional branching and robotic process integration. Indian back-office operations rely on this for password reset and access provisioning at scale, though script maintenance creates technical debt.
- CRM Integration:Bidirectional data synchronization linking support interactions to customer lifetime value and sales pipeline stages. Retail and IT Services segments treat this as mandatory for account-based escalation and churn prediction.
- Mobile Access:Native application or responsive web interfaces enabling agent ticket handling and supervisor oversight from field locations. Field service technicians across all geographies require offline queue synchronization for connectivity-challenged environments.
CRM Integration retains the dominant share, while AI-Powered Tools are climbing the fastest as vendor R&D concentrates on generative capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure investments concentrate in the United States, Germany, and India, where enterprise IT services teams drive platform procurement. Regulatory divergence across these markets shapes vendor localization strategies and data residency requirements.
United States
Healthcare systems and financial services firms deploy AI-powered triage tools at scale, prioritizing HIPAA-compliant hosting for patient data workflows. The FDA and state-level privacy statutes tighten access controls for medical device troubleshooting integrations. Hospital networks in the Boston-Cambridge corridor and Texas Medical Center anchor demand for high-availability service desk architectures.
Germany
Industrial Mittelstand enterprises in Baden-Württemberg and Bavaria convert from email-based support to SaaS ticketing platforms, reducing mean-time-to-resolution for machinery downtime. The EU AI Act and GDPR Article 22 mandate human oversight of automated routing decisions, compelling vendors to maintain explainable inference modules. Munich and Stuttgart host the densest clusters of manufacturing-sector helpdesk modernization projects.
India
Business process outsourcing firms in Bangalore and Hyderabad scale cloud helpdesk deployments to capture seasonal contract fluctuations with minimal capital outlay. The PLI scheme for IT hardware reduces datacenter equipment costs, accelerating mid-market adoption previously priced out of enterprise SaaS tiers. Domestic technology services companies in the National Capital Region drive consumption-based pricing negotiations with global vendors.
United Kingdom
Financial services institutions in the City of London and Edinburgh deploy unified IT-HR service desk platforms to consolidate cross-departmental budgets. The Financial Conduct Authority and Information Commissioner's Office impose audit trail requirements on automated customer complaint handling. Fintech clusters in Manchester and Leeds represent emerging demand pockets for API-first ticketing integrations.
Japan
Manufacturing conglomerates in the Nagoya-Toyota industrial corridor integrate helpdesk platforms with predictive maintenance systems for supply chain continuity. METI guidelines on data sovereignty encourage hybrid deployment models keeping sensitive operational data on-premise. Osaka-based electronics assemblers anchor regional demand for mobile-accessible field service ticketing.
Helpdesk Management Market Competitive Landscape
Omnichannel-suite vendors and workflow-automation specialists split the market along deployment complexity lines. The vendor base stratifies into three tiers: enterprise-grade platforms commanding annual contract values above $500,000, mid-market SaaS providers competing on rapid implementation timelines, and open-source alternatives capturing cost-sensitive developer-led procurement. Strategic moves center on API ecosystem expansion and vertical-specific compliance module development.
Within the enterprise workflow tier, ServiceNow and Zendesk exemplify divergent positioning strategies. ServiceNow anchors high-value automation across IT and HR service desks through integrated platform architectures. Zendesk occupies a position emphasizing omnichannel customer engagement with rapid deployment characteristics. Freshdesk represents the aggressive mid-market SaaS competitor capturing price-sensitive contracts through freemium-to-paid conversion funnels.
| Leading Market Players |
|---|
| Zendesk |
| Freshdesk |
| ServiceNow |
| Jira Service Management |
| Zoho Desk |
| Help Scout |
| HappyFox |
| Kayako |
| LiveAgent |
| Others |
Supply & Pricing Matrix
Overcapacity in Indian cloud datacenter infrastructure compresses hosting costs for SaaS helpdesk vendors while forcing margin discipline on subscription pricing. This utilization dynamic rewards buyers with predictable per-seat rates while pressuring providers to bundle AI inference credits into enterprise contracts.
Pricing Analysis
Aftermarket service revenue tiers anchor lifetime value capture across helpdesk platforms. Three-tier pricing structure across premium, standard, and economy levels segments by AI feature depth and SLA guarantees. Price differentiation rests on GDPR compliance certification and vertical-specific integration complexity. Cost compression in the mid-market tier is intensifying because Indian BPO firms negotiate consumption-based contracts. Healthcare providers demonstrate lowest price sensitivity due to HIPAA-mandated audit trail requirements.
Supply Chain Analysis
Contract manufacturing concentration for AI inference hardware sits with TSMC foundries in Taiwan and Samsung fabs in South Korea. Cloud infrastructure draws from US hyperscaler regions, Indian PLI-subsidized server assembly, and German sovereign hosting facilities. GPU supply chains hinge on NVIDIA allocation agreements and memory module availability. Single-source vulnerability in advanced node semiconductor fabrication threatens embedded AI feature rollouts. Distribution runs through direct vendor sales teams for enterprise accounts and self-service portals for mid-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helpdesk management fragmentation creates entry niches as enterprise buying committees splinter between compliance-heavy regulated verticals and automation-first cost optimizers.
For Market Incumbents: Pre-empt mid-market SaaS erosion by embedding generative AI triage as standard rather than premium-tier functionality. Anchor high-value workflow automation across IT-HR convergence use cases to capture cross-departmental budgets. Defend against open-source alternatives through vertical-specific compliance module development for EU AI Act and HIPAA implementations.
For New Entrants and Emerging Players: Pursue underpenetrated German Mittelstand manufacturers still operating email-based support workflows in Baden-Württemberg and Bavaria. Target consumption-based pricing models that transfer operational risk from buyers to vendors. Deploy API-first architectures to capture fintech integration demand in UK secondary cities.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native helpdesk deployments as GPU scarcity eases and Indian PLI subsidies reduce hardware costs. Long-term viability favors platforms with embedded compliance-as-a-service revenue streams. Monitor EU AI Act enforcement patterns as inflection signal for explainable AI module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified IT-HR service desks capture cross-departmental budgets from CIO and CHRO joint committees. |
| Compliance Module Development | EU AI Act algorithmic auditing tools create recurring revenue from German healthcare and public sector deployments. |
| Geographic Expansion | Indian mid-market SaaS adoption accelerates through PLI-subsidized datacenter infrastructure cost reductions. |
| Strategic Partnership | Hyperscaler co-sell agreements unlock enterprise procurement channels with pre-negotiated security certifications. |
| Acquisition of Specialist Firm | Conversational AI boutiques add retrieval-augmented generation capabilities for financial services intent classification. |
Research Methodology
Initial hypotheses were tested against primary input from CIOs, IT procurement officers, helpdesk platform engineers, and managed service provider operations leads and refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including SEC 10-K filings, hyperscaler capex disclosures, EU regulatory filings, and Indian PLI scheme implementation reports. Bottom-up deployment model sizing and top-down IT services spending allocation were triangulated to converge on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs were derived from slope analysis of historical penetration curves adjusted for technology substitution effects. Forecast inputs incorporated AI feature adoption velocity and GDPR compliance cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in cloud infrastructure investment cycles or GPU supply availability would shift the trajectory. Forecasts reflect documented assumptions about enterprise SaaS conversion rates and regulatory enforcement intensity. Quarterly review of hyperscaler datacenter expansion announcements and EU AI Act national implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Europe IT Staffing Market
Enterprise Services
Enterprise Social Networks Market
Enterprise Services
Global Cloud Professional Services Market
Enterprise Services
Enterprise Collaboration Service Market
Enterprise Services
Human Capital Management (HCM) Market
Enterprise Services
Field Service Management Market
Enterprise Services
IoT Professional Services Market
Enterprise Services
Outsourced Customer Care Services Market
Enterprise Services
Proactive Services Market
Enterprise Services
Workforce Management Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Electronics Contract Manufacturing Services (EMS) Market
Enterprise Services
Global Enterprise High-Productivity Application Platform As a Service Market
Enterprise Services
Global Enterprise Data Integration Market
Enterprise Services
GCC Managed Service Market