
 Enterprise Portal Market | 2026-2036
Enterprise Portal Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Portal Market Analysis
Enterprise portal development talent is unwinding from legacy Java stacks toward cloud-native and low-code platforms, reshaping vendor competitiveness. Oracle sustains deep integration with its database and ERP ecosystems, anchoring large enterprises in on-premises-to-hybrid transitions. Microsoft dominates the cloud-based segment through Azure AD-backed SharePoint and Viva platforms, extending its productivity suite dominance into portal infrastructure. Salesforce competes by embedding its Customer 360 identity layer across employee, partner, and customer experiences.
An enterprise portal is a unified software framework that aggregates applications, content, and services through role-based access controls, typically supporting single sign-on, API orchestration, and responsive web delivery to streamline organizational workflows. Cloud-based deployment leads volume growth as CIOs retire data center footprints, while hybrid configurations capture margin pools in regulated industries requiring sovereign data residency. Feature sets centered on user analytics and reporting dashboards are expanding fastest as enterprises prioritize behavioral insights over static document repositories.
FDA 21 CFR Part 11 and HIPAA shape healthcare portal requirements around audit trails and patient consent management in the United States, while the EU AI Act and GDPR impose algorithmic transparency and data localization obligations on European deployments. India's MeitY guidelines and BIS cloud standards add compliance layers for multi-tenant architectures serving public-sector clients. Stakeholders must monitor how fragmented sovereignty rules fragment platform architectures and force modular, jurisdiction-specific builds.
Market Dynamics
Cloud migration mandates under HIPAA and the EU AI Act are compressing replacement cycles as enterprises retire legacy intranet systems. Healthcare providers face dual pressure from patient demand for digital access and sovereign data residency requirements.
Growth Catalysts
- HIPAA Cloud Mandates:Healthcare providers in the United States must modernize patient-facing portals to meet audit trail and consent management requirements, accelerating infrastructure replacement.
- EU AI Act Algorithmic Transparency:European enterprises deploy explainable AI layers within employee portals to satisfy automated decision-making disclosure rules.
- Low-Code Platform Maturation:Cloud-native development tools reduce portal deployment timelines from months to weeks, expanding addressable demand among mid-market enterprises.
Market Restraints
- Sovereign Data Fragmentation:India's MeitY guidelines and BIS cloud standards force modular, jurisdiction-specific architectures that inflate engineering overhead for multi-tenant platforms.
- Legacy Integration Debt:Oracle database ecosystems anchor large enterprises in hybrid configurations, delaying full cloud transitions and extending sales cycles.
- Specialized Talent Scarcity:Cloud-native portal architects command premium compensation, compressing margins for system integrators serving price-sensitive public-sector clients.
Strategic Opportunities
- German Mittelstand Modernization:Mid-sized manufacturers seek employee portals with embedded analytics, creating whitespace for vendors with industrial IoT integration capabilities.
- Behavioral Analytics Convergence:User journey tracking combined with identity management layers enables predictive workflow optimization in financial services portals.
- Partner Ecosystem Expansion:Salesforce Customer 360 architecture demonstrates demand for unified identity across employee, customer, and supplier experiences.
Industry Challenges
- API Orchestration Complexity:Enterprises struggle to unify hundreds of legacy application endpoints into coherent portal experiences without degrading performance.
- Cross-Border Compliance Engineering:Engineering teams must maintain parallel codebases to satisfy divergent GDPR, HIPAA, and BIS requirements simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Portal Market |
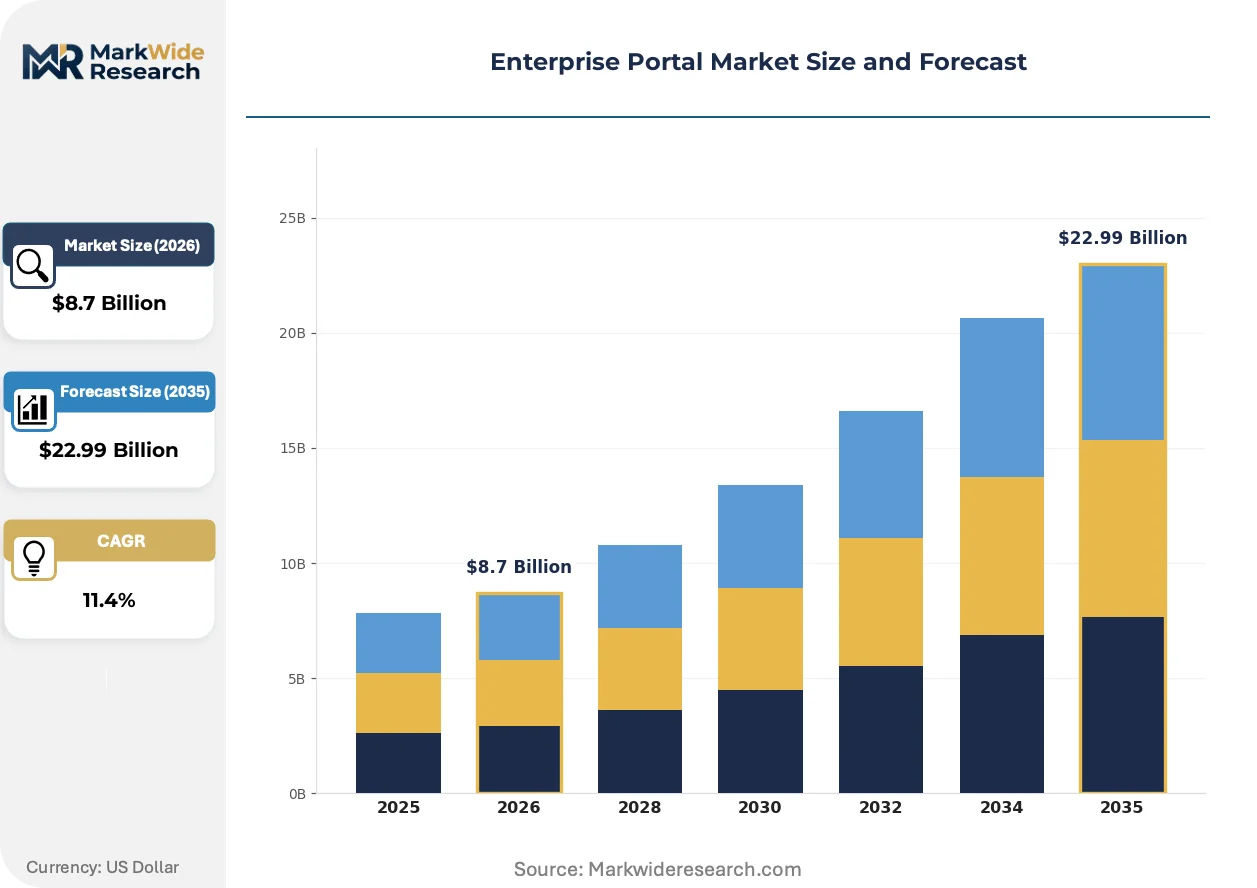
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services User Type: Employees, Customers, Partners, Administrators Feature Set: Collaboration Tools, Document Management, Reporting Dashboards, User Analytics Industry Vertical: Healthcare, Education, Manufacturing, Retail |
| Companies Covered | IBM, Zoho, Oracle, Atlassian, Salesforce, SAP, ServiceNow, Aurea, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Portal Market Emerging Trajectories
Generative AI interfaces are rewriting user expectations for portal search and task completion. Vendors race to embed conversational agents without triggering regulatory scrutiny over automated decision-making.
Headless CMS architectures are supplanting traditional monolithic content management in enterprise portal stacks. Financial services firms adopt these decoupled front-ends to deliver consistent experiences across mobile banking apps, employee intranets, and partner extranets. This shift is compressing vendor switching costs and enabling best-of-breed component selection.
The EU AI Act's risk-based classification system imposes documentation burdens on portals deploying recommendation engines or automated workflow routing. Healthcare and HR applications face heightened scrutiny as high-risk use cases. German and French enterprises are front-loading algorithmic impact assessments to preempt enforcement actions.
Subscription-based portal procurement is displacing perpetual license models in mid-market segments. CIOs prefer operational expenditure treatment for cloud-native deployments, particularly in India and Southeast Asia where capital constraints shape buying committees. This reconfiguration favors vendors with consumption-metered pricing and rapid time-to-value demonstration.
Enterprise Portal Market Segmentation
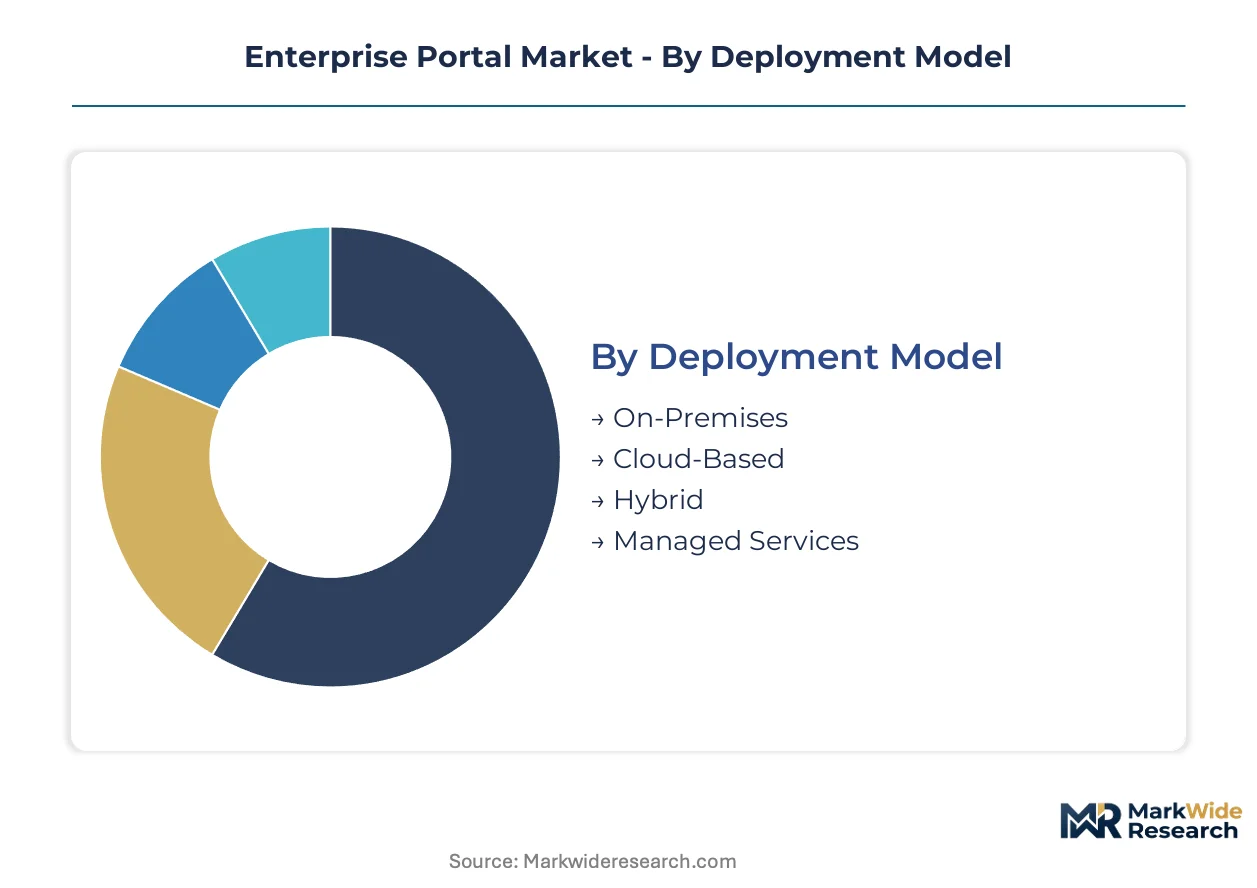
Enterprise portal procurement patterns diverge sharply across deployment models, user constituencies, and regulatory exposure. Vendors must align architectural choices with specific compliance burdens and integration legacy to capture expansion opportunities.
Deployment Model:
German and Indian demand concentrates in cloud-native configurations, while US healthcare maintains substantial on-premises footprint due to HIPAA data residency requirements.
- Cloud-Based:Multi-tenant architectures with API-first design enable rapid scaling across distributed workforces. Demand concentrates in India's IT services sector and Germany's Mittelstand manufacturers seeking to retire data center assets under EU AI Act transparency mandates.
- Hybrid:Split-stack configurations separate sensitive identity data on-premises from collaborative workloads in cloud environments. US healthcare providers deploy these architectures to satisfy HIPAA audit trail requirements while enabling patient mobile access.
- On-Premises:Legacy Oracle and Microsoft SharePoint installations persist in defense and classified government environments.
- Managed Services:Third-party operational handoff appeals to mid-market enterprises lacking internal cloud architecture expertise.
Cloud-based configurations command the established base. The steepest expansion runs through hybrid deployments bridging sovereignty and agility requirements.
User Type:
Cost tier stratification separates employee-facing intranets from customer and partner portals requiring external identity federation.
- Employees:Role-based access controls integrate HRIS directories with productivity suites. Manufacturing firms in Germany embed IoT operational dashboards directly into employee homepages.
- Customers:Self-service portals demand conversational AI interfaces and predictive case routing. US healthcare providers invest here to deflect call center volume under value-based care contracts.
- Partners:Supplier extranets require granular permission scoping across multi-enterprise supply chains.
- Administrators:Super-user interfaces concentrate audit logging and compliance reporting functions for regulated industries.
Employee portals absorb the majority of current spend. Customer-facing deployments are climbing the fastest as digital experience investments displace traditional service channels.
Feature Set:
Application maturity separates commoditized document repositories from behavioral analytics commanding premium pricing.
- User Analytics:Journey mapping and predictive workflow optimization tools capture behavioral signals across portal interactions. Financial services firms in the United States deploy these to identify employee productivity bottlenecks and customer abandonment patterns.
- Reporting Dashboards:Real-time data visualization layers aggregate ERP, CRM, and operational metrics. Manufacturing verticals prioritize these for shop-floor-to-boardroom visibility.
- Collaboration Tools:Embedded messaging, video, and co-editing capabilities compete with standalone productivity platforms.
- Document Management:Version control and retention policy enforcement remain baseline expectations with limited differentiation.
Document management anchors legacy installations. User analytics represents the fastest-growing trajectory as enterprises prioritize behavioral intelligence over static content repositories.
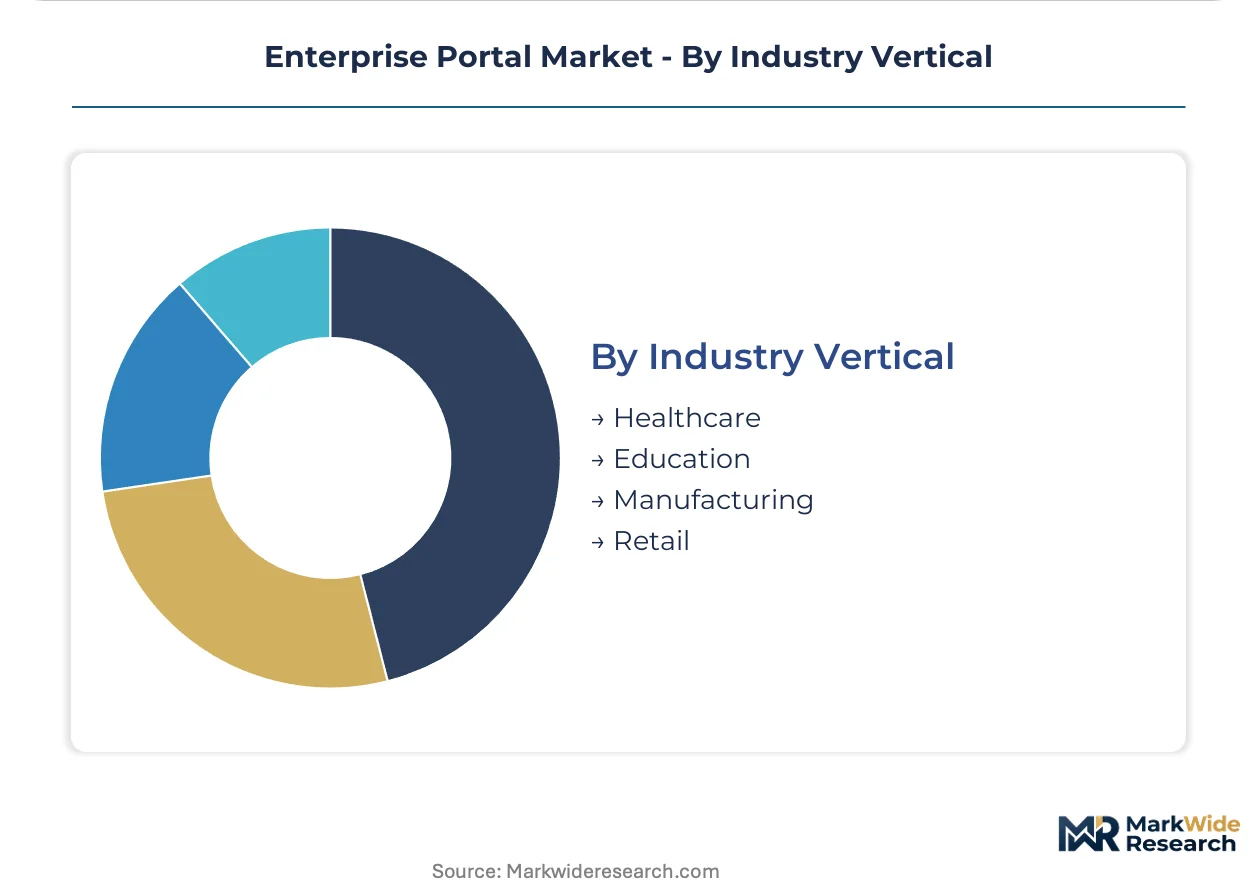
Industry Vertical:
Regulatory intensity varies dramatically, with healthcare and education facing distinct compliance architectures versus manufacturing and retail flexibility.
- Healthcare:Patient-facing portals must satisfy FDA 21 CFR Part 11 audit trails and HIPAA consent management. US providers modernize these systems under cloud migration mandates while preserving sovereign data controls.
- Manufacturing:Industrial IoT integration and supplier ecosystem coordination drive portal complexity. German automotive suppliers lead in embedding predictive maintenance dashboards for workforce access.
- Education:Learning management system integration and student privacy compliance shape procurement criteria.
- Retail:Omnichannel inventory visibility and franchisee network coordination dominate functional requirements.
Healthcare deployments command premium pricing due to compliance engineering overhead. Manufacturing applications are expanding most quickly as Industry 4.0 investments converge with workforce digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where compliance engineering commands premium deployment fees, while Indian vendors compete on operational cost arbitrage for mid-market cloud-native implementations.
United States
Healthcare providers drive patient portal modernization under HIPAA cloud migration mandates and FDA 21 CFR Part 11 audit trail requirements. The FDA and CMS enforce strict consent management protocols for electronic health records. Boston and the San Francisco Bay Area anchor healthtech clusters where Epic Systems and Cerner legacy integrations create substantial replacement opportunity.
Germany
Mittelstand manufacturers seek employee portals with embedded industrial IoT dashboards under EU AI Act algorithmic transparency rules. The KBA and BSI coordinate cybersecurity certification for critical infrastructure operators. Stuttgart and Munich automotive supplier networks lead predictive maintenance portal deployments for workforce access.
India
IT services exporters and public-sector clients demand cloud-native configurations compliant with MeitY guidelines and BIS cloud standards. The RBI and SEBI impose data localization requirements on financial services portals. Bengaluru and Hyderabad technology corridors concentrate vendor development centers serving both domestic and export markets.
United Kingdom
Financial services firms prioritize behavioral analytics convergence with identity management layers under FCA operational resilience directives. The Information Commissioner's Office enforces GDPR-derived accountability frameworks. London's fintech cluster drives demand for predictive workflow optimization in employee and customer-facing portal experiences.
Japan
Enterprise digitization lags in legacy-heavy industries now confronting METI Industry 4.0 transformation targets. The PMDA and JIS standards bodies regulate medical device portal integrations. Tokyo and Osaka manufacturing headquarters initiate phased intranet retirements toward hybrid cloud configurations.
Enterprise Portal Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. The market consolidates around database-anchored incumbents with deep ERP integration and cloud-native challengers with rapid deployment capabilities. Three archetypes dominate: legacy stack specialists maintaining hybrid configurations, platform ecosystem players extending productivity suites, and low-code pure-plays compressing implementation timelines. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through localized compliance engineering.
Within the legacy-to-hybrid transition tier, Oracle and IBM occupy positions anchoring large enterprises through database ecosystem stickiness. Microsoft and Salesforce exemplify platform ecosystem players extending cloud productivity dominance into portal infrastructure. SAP represents the ERP-integrated archetype serving manufacturing verticals with embedded operational dashboards.
| Leading Market Players |
|---|
| IBM |
| Zoho |
| Oracle |
| Atlassian |
| Salesforce |
| SAP |
| ServiceNow |
| Aurea |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with hyperscaler cloud providers lock in both infrastructure access and predictable unit economics for enterprise portal deployments across regulated industries. These arrangements tether pricing visibility to sovereign data residency commitments under HIPAA and GDPR, compressing margin flexibility for vendors serving multi-tenant architectures.
Pricing Analysis
The customization-premium spread separates standard SaaS tiers from configured-to-order implementations demanding compliance engineering. Subscription metering dominates cloud-native segments, while hybrid deployments command project-based fees tied to legacy integration complexity. Price differentiation rests on certification grade—FDA 21 CFR Part 11 validation commands substantial premiums—and vertical integration depth in identity management layers. Cost compression in mid-market SaaS tiers is intensifying because low-code platforms collapse deployment timelines. Public-sector buyers in India exhibit highest price sensitivity; US healthcare providers show lowest sensitivity due to bundled compliance requirements.
Supply Chain Analysis
API gateway provisioning from a concentrated vendor base in the United States, Ireland, and India creates chokepoint exposure for global portal rollouts. Core infrastructure draws from hyperscaler regions in Virginia, Frankfurt, and Mumbai, with identity federation services anchored in Microsoft and Salesforce ecosystems. Supply chain risk centers on single-source vulnerability for enterprise-grade single sign-on modules. Distribution runs through systems integrator networks with specialized healthcare and financial services practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
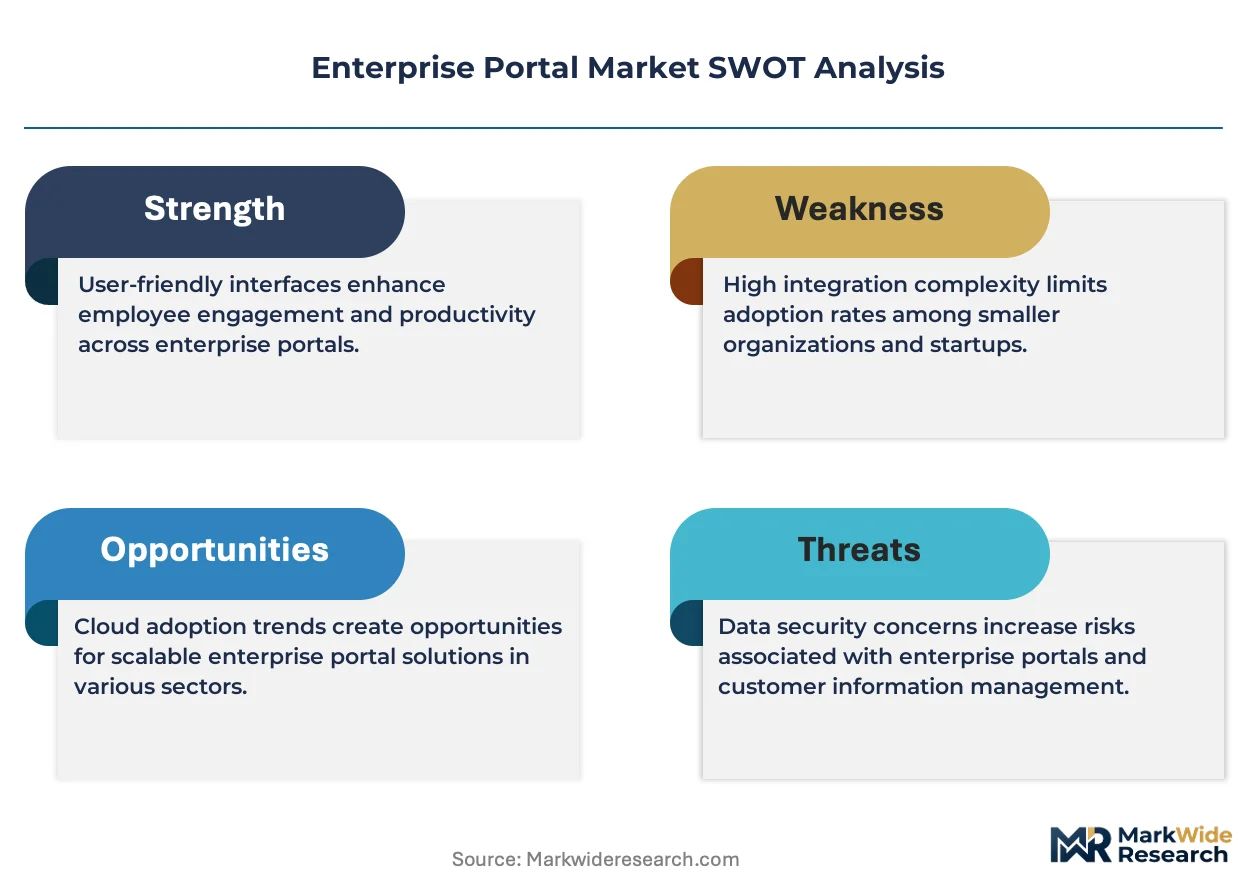
Enterprise portal adoption sits in early-cycle expansion as HIPAA cloud migration mandates force infrastructure replacement across US healthcare networks. Penetration remains below saturation even in regulated verticals, creating runway for specialized vendors.
For Market Incumbents: Shield installed base revenue by embedding generative AI interfaces before challengers capture search and task-completion workflows. Deepen vertical integration into sovereign data residency infrastructure to preempt modular competitors. Fortify Oracle and SAP ecosystem anchoring through pre-validated compliance modules that extend replacement cycles.
For New Entrants and Emerging Players: EU AI Act algorithmic transparency certification fast-tracks entry into German Mittelstand manufacturing accounts seeking predictive maintenance dashboards. White-space concentrates in mid-market healthcare providers lacking internal cloud architecture expertise. Go-to-market should lead with consumption-metered pricing and rapid time-to-value demonstration against perpetual-license incumbents.
For Investors and Strategic Acquirers: Cloud-native portal architects with healthcare compliance specializations represent the priority acquisition archetype for capability gap-filling. Long-term viability favors vendors with jurisdiction-specific modular builds addressing sovereign data fragmentation. Monitor FDA enforcement patterns on patient consent management as inflection signal for compliance-engineering premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding Salesforce Customer 360 across employee and customer experiences unifies identity layers. |
| Compliance Certification Fast-Track | Pre-validated FDA 21 CFR Part 11 modules accelerate healthcare procurement cycles. |
| Geographic Expansion | Localized engineering centers in Bengaluru address MeitY guidelines for Indian public-sector clients. |
| Strategic Partnership | Systems integrator alliances with healthcare practices unlock enterprise sales channel access. |
| Product Launch | Headless CMS architectures displace monolithic SharePoint installations in financial services. |
Methodological Framework
A spread of perspectives from chief technology officers, healthcare IT procurement directors, cloud platform engineers, and systems integrator practice leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, hospital procurement databases, and EU regulatory impact assessments. Bottom-up deployment modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled span deployment architecture, user constituency, feature maturity tier, and regulatory exposure cluster. Value projections incorporate infrastructure replacement cycles under HIPAA and EU AI Act mandates, low-code platform adoption curves, and sovereign data residency engineering premiums. CAGRs derive from trend extrapolation anchored in disclosed vendor bookings patterns and healthcare provider modernization timelines.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity or hyperscaler pricing stability would require recalibration. Forecasts reflect documented assumptions on compliance cost trajectories and cloud migration velocity. Practitioners should keep alternative scenarios live as FDA audit trail requirements and EU algorithmic transparency enforcement patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Human Capital Management (HCM) Market
Enterprise Services
Europe Managed Infrastructure Services Market
Enterprise Services
Enterprise Web Development Outsourcing Services Market
Enterprise Services
Global AWS Managed Services Market
Enterprise Services
Global IT Infrastructure Services Market
Enterprise Services
HR Tech Consulting Market
Enterprise Services
Supplier Management Market
Enterprise Services
United States Managed Services Market
Enterprise Services
North America Public Sector Consulting and Advisory Services Market
Enterprise Services
Global Supply Chain Management (SCM) Market
Enterprise Services
Workforce Management Market
Enterprise Services
Indonesia Managed Services Market
Enterprise Services
Enterprise Social Software Market
Enterprise Services
Travel and Expense Management Market
Enterprise Services
Shared Services Center Market
Enterprise Services
North America Warehouse Management Systems Market