
 Shared Services Market | 2026-2036
Shared Services Market Size, Share, and Industry Trends Forecast 2026-2036
Shared Services Market Analysis
Asset-light operating leases and outcome-based contracting is tilting competitive dynamics toward firms that can deploy capital without owning fixed delivery infrastructure. Accenture leverages its global delivery network to sustain margin advantages across hybrid engagements. Genpact anchors its position through deep vertical specialization in finance and accounting transformation. Tata Consultancy Services dominates large-scale IT management migrations for enterprise clients seeking captive-to-third-party transitions.
Shared services denotes the consolidation of business support functions—finance, human resources, procurement, and information technology—into a single centralized unit that serves multiple divisions or geographic entities through standardized processes, service-level agreements, and process automation. These operations typically run on enterprise resource planning platforms with defined turnaround times, cost-per-transaction metrics, and continuous improvement protocols aimed at eliminating duplication and extracting scale efficiencies. Finance and accounting functions currently occupy the largest value pool given their transaction intensity and regulatory exposure, while cloud-based delivery models represent the fastest-expanding structural category as enterprises exit legacy data center commitments. Procurement services command premium pricing where category management extends beyond transactional processing into strategic sourcing and supplier risk analytics.
The European Union's GDPR and the U.S. SEC's climate disclosure rules are reshaping data governance and reporting requirements, forcing shared services operators to embed compliance controls directly into workflow automation and cross-border data transfer protocols. India's RBI data localization mandates and China's cybersecurity law impose additional jurisdictional constraints on centralized processing architectures. Stakeholders must evaluate whether geographic concentration of delivery centers creates unacceptable regulatory tail risks as data sovereignty frameworks proliferate.
Market Dynamics
Cloud migration is hybridizing with data sovereignty mandates, forcing shared services operators to rearchitect delivery footprints while maintaining centralized efficiency gains. This structural tension between scale economics and jurisdictional compliance defines current competitive positioning.
Growth Catalysts
- GDPR data residency enforcement:European healthcare organizations must localize processing, creating demand for EU-based shared services centers with compliant infrastructure.
- Finance and accounting automation:Banking sector concentration in North America drives transaction volume into cloud-based F&A platforms with embedded AI.
- India:RBI data localization mandates push multinational corporations to establish captive centers or third-party partnerships within Indian jurisdiction.
Market Restraints
- Delivery center concentration risk:Heavy reliance on Indian and Philippine talent pools creates geopolitical and business continuity exposure.
- Cross-border data transfer friction:China's cybersecurity law blocks seamless centralized processing for Asia-Pacific operations.
- Legacy ERP integration costs:SAP and Oracle system heterogeneity inflates transition timelines and capital requirements for unified platforms.
Strategic Opportunities
- Central and Eastern Europe:Poland and Romania offer GDPR-compliant nearshore capacity with lower cost structures than Western European alternatives.
- AI-augmented compliance automation:Convergence of machine learning and workflow engines enables real-time regulatory reporting across multiple jurisdictions.
- Outcome-based contracting:Enterprise buyers increasingly demand cost-per-transaction pricing tied to measurable business outcomes rather than FTE-based models.
Industry Challenges
- Specialized talent scarcity:Shortage of professionals combining domain expertise in finance or HR with cloud architecture and automation skills constrains expansion.
- Multi-jurisdiction certification complexity:ISO 27001, SOC 2 Type II, and industry-specific attestations require overlapping audit cycles and documentation burdens.
- Hybrid cloud orchestration:Managing workloads across private data centers and multiple public clouds introduces operational friction and security perimeter challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shared Services Market |
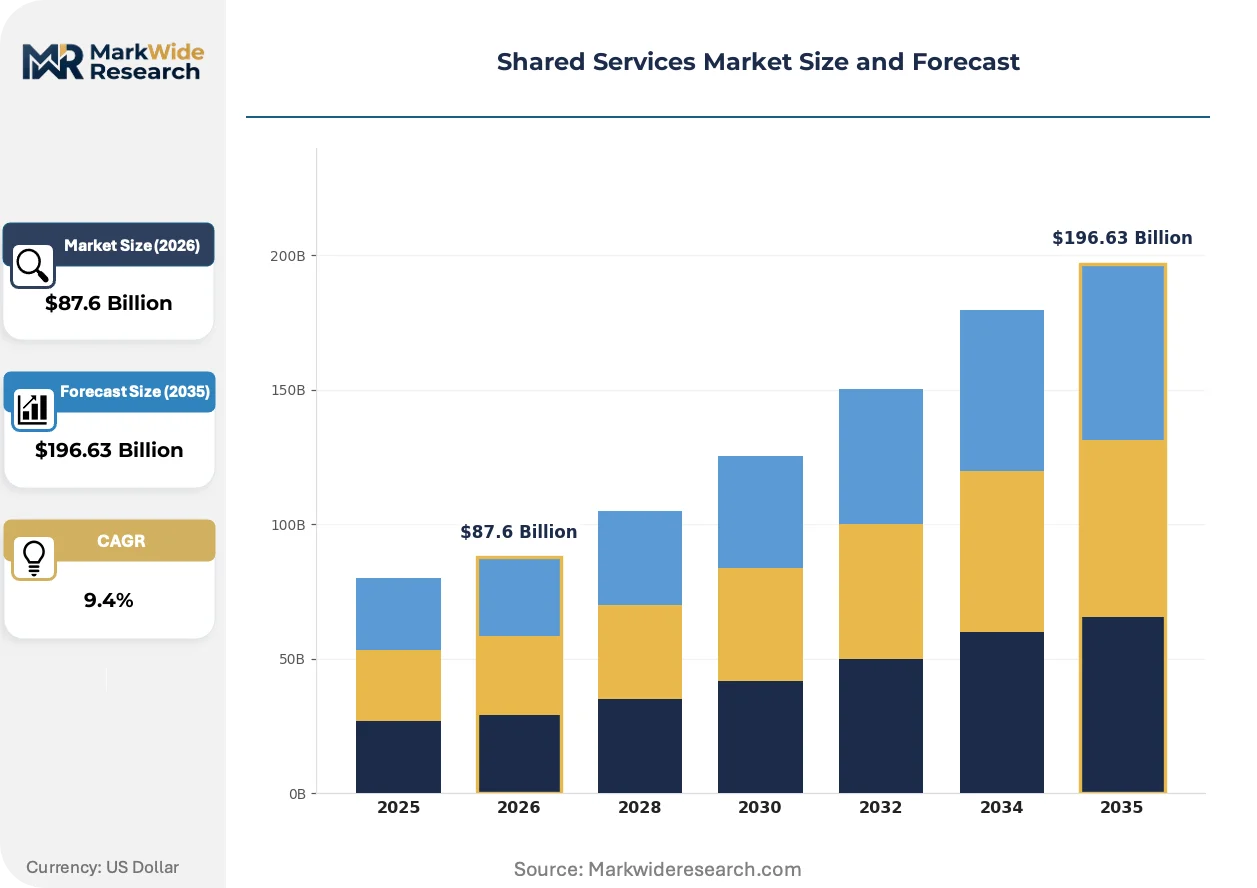
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: IT Services, Finance and Accounting, Human Resource, Procurement Delivery Model: On-premise, Cloud-based, Hybrid, Managed Services End User Industry: Healthcare, Financial Services, Manufacturing, Retail Function: Customer Support, IT Management, Data Processing, Compliance |
| Companies Covered | Accenture, Capgemini, Cognizant, Deloitte, Ernst & Young, Genpact, Infosys, PwC, Tata Consultancy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shared Services Market Emerging Trajectories
Generative AI and process mining tools are compressing service delivery timelines while regulatory fragmentation forces architectural investments in geographic redundancy. These forces are reshaping how operators balance efficiency against resilience.
Intelligent process automation is hybridizing robotic process automation with large language models to handle unstructured document processing. Healthcare payers in Germany and the United States are deploying these tools for claims adjudication and prior authorization workflows. This convergence is compressing headcount requirements in high-volume transaction functions while elevating the strategic role of exception handling and complex case management.
The EU AI Act introduces risk-based classification for automated decision systems used in HR and credit scoring within shared services operations. Providers must implement human oversight mechanisms and algorithmic transparency documentation for high-risk applications. Financial services shared services centers in Frankfurt and Paris are prioritizing compliance architecture investments ahead of enforcement timelines.
Enterprise procurement departments are unbundling monolithic outsourcing contracts into modular, best-of-breed service towers. Large manufacturers in the United States and United Kingdom now source finance automation, HR administration, and IT service desk through separate vendors with API-based integration. This fragmentation demands stronger vendor management capabilities from client organizations while creating entry points for specialized mid-market providers.
Shared Services Market Segmentation
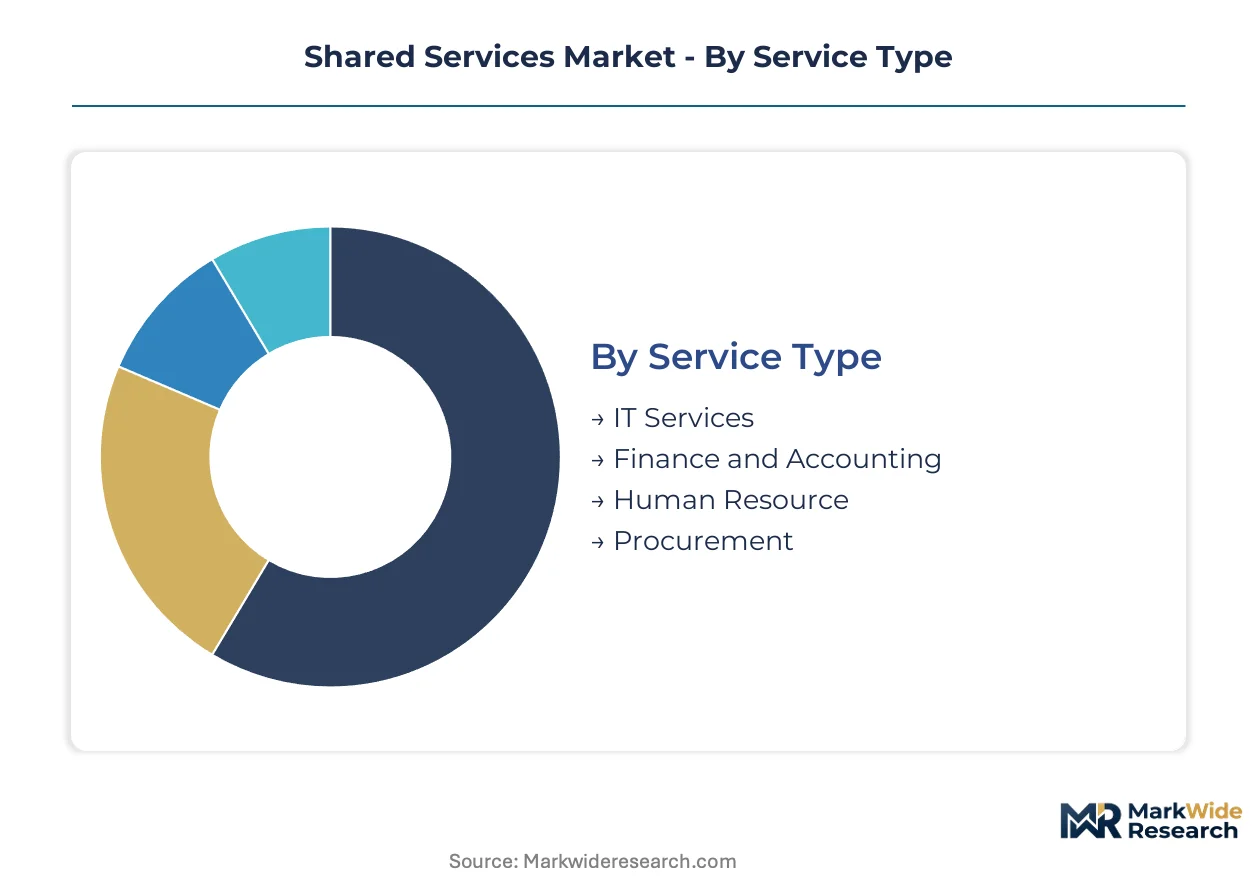
Shared services operators configure delivery architectures around transaction intensity, regulatory exposure, and cloud maturity. Segment boundaries blur as enterprises unbundle monolithic contracts into modular service towers with API-based integration.
Service Type:
Cost tier stratification separates high-volume transactional processing from advisory and transformation services.
- Finance and Accounting:Encompasses accounts payable, receivable, general ledger, and treasury operations executed through ERP platforms with embedded robotic process automation. Banking sector concentration in the United States drives cloud migration for transaction processing, while GDPR data residency enforcement pushes European healthcare organizations toward EU-based delivery centers.
- IT Services:Covers infrastructure management, application maintenance, and service desk operations spanning legacy data center and multi-cloud environments. Large-scale captive-to-third-party transitions in enterprise manufacturing create demand for hybrid orchestration capabilities across private and public cloud footprints.
- Human Resource:Payroll administration, benefits management, and talent acquisition delivered through HCM platforms with employee self-service portals.
- Procurement:Strategic sourcing, category management, and supplier risk analytics commanding premium pricing beyond transactional processing.
The dominant share belongs to Finance and Accounting, while IT Services is closing the gap fastest.
Delivery Model:
Application maturity determines infrastructure commitment levels across enterprise client portfolios.
- Cloud-based:Fully hosted SaaS and IaaS delivery eliminating capital-intensive data center ownership, with automatic updates and elastic capacity scaling. North American banking sector adoption accelerates as institutions exit legacy mainframe commitments for finance automation platforms.
- Hybrid:Workload distribution across private infrastructure and multiple public clouds balancing latency-sensitive operations with burst capacity. German healthcare payers deploy this architecture to maintain local claims processing while leveraging cloud analytics for population health management.
- On-premise:Client-owned data centers retaining sensitive workloads under direct physical control.
- Managed Services:Outcome-based contracts with third-party operators assuming operational risk for defined service levels.
Cloud-based deployment captures the largest revenue pool, though Hybrid architectures are expanding most quickly.
End User Industry:
Customer type differentiation reflects sector-specific compliance burdens and transaction velocity requirements.
- Healthcare:Claims adjudication, revenue cycle management, and prior authorization workflows subject to HIPAA and GDPR constraints. United States payers and German statutory health insurers deploy intelligent process automation to compress headcount in high-volume transaction functions.
- Financial Services:Regulatory reporting, anti-money laundering monitoring, and trade processing with embedded compliance controls. SEC climate disclosure rules and EU CSRD mandates force architectural investments in real-time data governance.
- Manufacturing:Supply chain finance, vendor master data management, and indirect procurement across distributed production networks.
- Retail:Seasonal workforce scaling, omnichannel customer support, and inventory financing with demand volatility management.
Healthcare holds the leading position, while Financial Services is gaining share fastest.
Function:
Margin structure varies with automation potential and exception handling complexity.
- IT Management:Infrastructure monitoring, patch management, and incident response with increasing AI-augmented predictive maintenance. India's RBI data localization mandates push multinational corporations toward captive centers or third-party partnerships within Indian jurisdiction.
- Compliance:Regulatory reporting, audit documentation, and risk assessment workflows requiring multi-jurisdiction certification. EU AI Act risk-based classification for automated decision systems demands human oversight mechanisms in Frankfurt and Paris shared services centers.
- Customer Support:Multi-channel inquiry resolution with escalating self-service adoption through conversational AI.
- Data Processing:High-volume transaction cleansing, validation, and migration with generative AI document extraction.
IT Management commands the deepest revenue base, while Compliance is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government data localization mandates and sector-specific compliance requirements are fragmenting delivery footprints across major economies. Healthcare and financial services organizations prioritize jurisdictional alignment over pure cost arbitrage.
United States
SEC climate disclosure rules and HIPAA enforcement drive healthcare payers toward cloud-based finance automation with embedded compliance controls. Banking sector concentration in New York and Charlotte accelerates captive-to-third-party transitions for transaction processing. Texas and Arizona host expanding delivery centers serving domestic data residency requirements.
Germany
GDPR data residency enforcement and the EU AI Act reshape healthcare shared services architecture for statutory health insurers. Frankfurt and Berlin clusters prioritize compliance infrastructure investments ahead of automated decision system enforcement timelines. Bavaria-based manufacturing enterprises localize procurement analytics to satisfy supply chain due diligence regulations.
India
RBI data localization mandates push multinational corporations toward captive centers or third-party partnerships within Indian jurisdiction. Bengaluru and Hyderabad dominate IT management migrations for enterprise clients seeking hybrid cloud orchestration. Mumbai financial services hubs embed regulatory reporting automation for cross-border banking operations.
United Kingdom
Post-Brexit data adequacy negotiations and FCA operational resilience requirements influence shared services location strategy. London retains concentration in compliance and risk analytics for financial services. Manchester and Birmingham emerge as alternative delivery locations for back-office functions previously centralized in EU jurisdictions.
Poland
GDPR-compliant nearshore capacity attracts German and Nordic enterprises seeking lower cost structures than Western European alternatives. Kraków and Warsaw shared services centers specialize in finance and accounting transformation with multilingual delivery capabilities. EU structural funds support digital infrastructure investments for cloud-based service delivery.
Shared Services Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale advantages fragment by vertical depth. Consolidation pressures concentrate among mid-market providers lacking geographic redundancy or compliance certification breadth. Three archetypes dominate: global consultancies with captive delivery networks, vertical specialists anchoring finance and accounting transformation, and IT-centric operators managing hybrid cloud migrations. Competitive moves center on outcome-based contracting structures and modular service tower unbundling to capture enterprise procurement shifts.
Among global consultancies, Accenture, Deloitte, and Genpact exemplify contrasting strategic positions. Accenture represents the delivery network archetype with hybrid engagement capabilities spanning multiple jurisdictions. Deloitte occupies the advisory-led position where compliance and risk services integrate with operational execution. Genpact anchors the vertical specialization vector with concentrated finance and accounting transformation expertise.
| Leading Market Players |
|---|
| Accenture |
| Capgemini |
| Cognizant |
| Deloitte |
| Ernst & Young |
| Genpact |
| Infosys |
| PwC |
| Tata Consultancy Services |
| Others |
Supply Flow & Price Mechanics
Regulatory chokepoints around data sovereignty are compressing pricing tier spreads while forcing supply chain reconfiguration toward jurisdictional redundancy. GDPR enforcement in Europe and RBI localization mandates in India simultaneously inflate compliance-premium service rates and fragment delivery center concentration.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 27001 and SOC 2 Type II attestations commanding 15-25% rate premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation resting on automation depth and geographic delivery cost. Cost compression in the economy tier is intensifying because generative AI tools commoditize transactional processing. Mid-market enterprises show highest price sensitivity, while financial services buyers prioritize compliance assurance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are emerging as critical supplier selection criteria as operators absorb client working capital pressures. Talent supply concentrates in India, Poland, and the Philippines, with delivery infrastructure drawing from cloud hyperscaler regions in Frankfurt, Mumbai, and Singapore. Raw material dependencies span specialized IT infrastructure, multilingual workforce pipelines, and compliance certification audit capacity. Single-source vulnerability in Philippine voice operations creates continuity exposure during geopolitical disruption. Distribution runs through direct enterprise sales, systems integrator partnerships, and GPO-style procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of professionals combining domain expertise with cloud architecture and automation skills constrains expansion velocity across all competitive tiers. Organizations that secure this hybrid talent base gain disproportionate pricing power in outcome-based engagements.
For Market Incumbents: Entrench position through backward integration into proprietary AI/ML training data pipelines and captive certification audit capabilities. Defend against modular unbundling by embedding workflow automation deeper into client ERP architectures. Prioritize geographic redundancy investments in Central and Eastern Europe to offset Indian delivery concentration risk. For New Entrants and Emerging Players: Establish a beachhead in mid-market healthcare compliance automation, where GDPR and HIPAA dual-certification scarcity creates service gaps. Target German statutory health insurers and United States regional payers with pre-configured regulatory reporting modules. Lead with API-first architecture enabling rapid integration with existing client technology stacks. For Investors and Strategic Acquirers: Boutique compliance automation specialists with EU AI Act readiness offer the strongest acquisition profile for near-term consolidation. Long-term viability hinges on jurisdictional coverage breadth rather than cost arbitrage alone. Watch for inflection when outcome-based contract penetration exceeds FTE-based pricing in banking sector RFPs.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Orchestration Investment | Enables GDPR-compliant processing for German healthcare payers while maintaining cloud analytics scale. |
| AI-Augmented Compliance Automation | Addresses EU AI Act human oversight requirements for automated decision systems in HR and credit scoring. |
| Central and Eastern Europe Delivery Expansion | Captures nearshore demand from Nordic and German enterprises seeking lower cost structures than Western alternatives. |
| Modular Service Tower Unbundling | Aligns with enterprise procurement shifts toward best-of-breed sourcing through API-based integration. |
| Outcome-Based Contract Structuring | Shifts revenue model from FTE-based to cost-per-transaction tied to measurable business results. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with shared services executives, cloud migration specialists, and procurement officers at healthcare payers and financial institutions; and secondary validation through SEC 10-K disclosures, EU regulatory filings, and hyperscaler infrastructure expansion announcements. Bottom-up transaction volume estimates were triangulated against top-down market sizing from service provider revenue aggregation.
Forecast inputs span service type segmentation, delivery model migration curves, and end-user industry adoption patterns across the projection horizon. CAGRs were derived from regression analysis against historical captive-to-third-party transition velocities and cloud infrastructure spend trajectories. Modeled variables include automation penetration rates, regulatory enforcement timelines, and talent pool expansion constraints.
Stress conditions across data localization mandate intensity, generative AI capability commoditization, and geopolitical disruption to Indian delivery centers were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and enterprise cloud migration appetite. Macroeconomic contraction, accelerated AI substitution, or fragmentation of cross-border data adequacy agreements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Enterprise Services
Workforce Management Market
Enterprise Services
North America Warehouse Management Systems Market
Enterprise Services
Multi Vendor Support Services Market
Enterprise Services
Proactive Services Market
Enterprise Services
Global Translation Services Market
Enterprise Services
Consumer Technical Support Services Market
Enterprise Services
Online Corporate Meeting Services Market
Enterprise Services
Integrated Workplace Management System (IWMS) Market
Enterprise Services
Europe Warehouse Management Systems Market
Enterprise Services
Enterprise Portal Market
Enterprise Services
Bring Your Own Device Market
Enterprise Services
Telecom Enterprise Services Market
Enterprise Services
Enterprise Service Bus Software Market
Enterprise Services
Global Enterprise Data Warehouse (EDW) Market
Enterprise Services
Enterprise Data Loss Prevention (DLP) Services Market
Enterprise Services
United States Management Consulting Services Market