
 Learning Analytics Solution Market | 2026-2036
Learning Analytics Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Learning Analytics Solution Market Foresight
Platform licensing revenue is fragmenting across specialized dashboards, predictive modules, and data-integration layers as buyers reject monolithic suites. IBM Corporation leverages its Watson analytics stack to anchor premium positioning in large university systems. Microsoft competes through Azure-native education tools that sustain tight integration with institutional productivity workflows. SAS Institute Inc. differentiates via deep statistical heritage in learning outcome assessment models.
A learning analytics solution is an information system that ingests multimodal educational data—clickstream logs, assessment scores, discussion forum metadata, and biometric engagement signals—and applies algorithmic processing to generate actionable intelligence for instructional design and learner intervention. Cloud-based deployment now leads solution delivery, though on-premise configurations retain share among government agencies with data-sovereignty constraints. Predictive analytics represents the fastest-expanding application segment as institutions seek early-alert systems for at-risk students. Dashboards and reporting tools occupy the mature core where margin pools have compressed due to open-source alternatives.
Federal regulators including the US Department of Education and the FTC shape demand through FERPA enforcement and emerging algorithmic accountability guidance for educational technology vendors. European operators navigate GDPR learner-consent requirements alongside the EU AI Act's risk-classification protocols for automated assessment systems. Stakeholders must monitor how divergent transatlantic compliance architectures reshape product roadmaps and geographic deployment strategies.
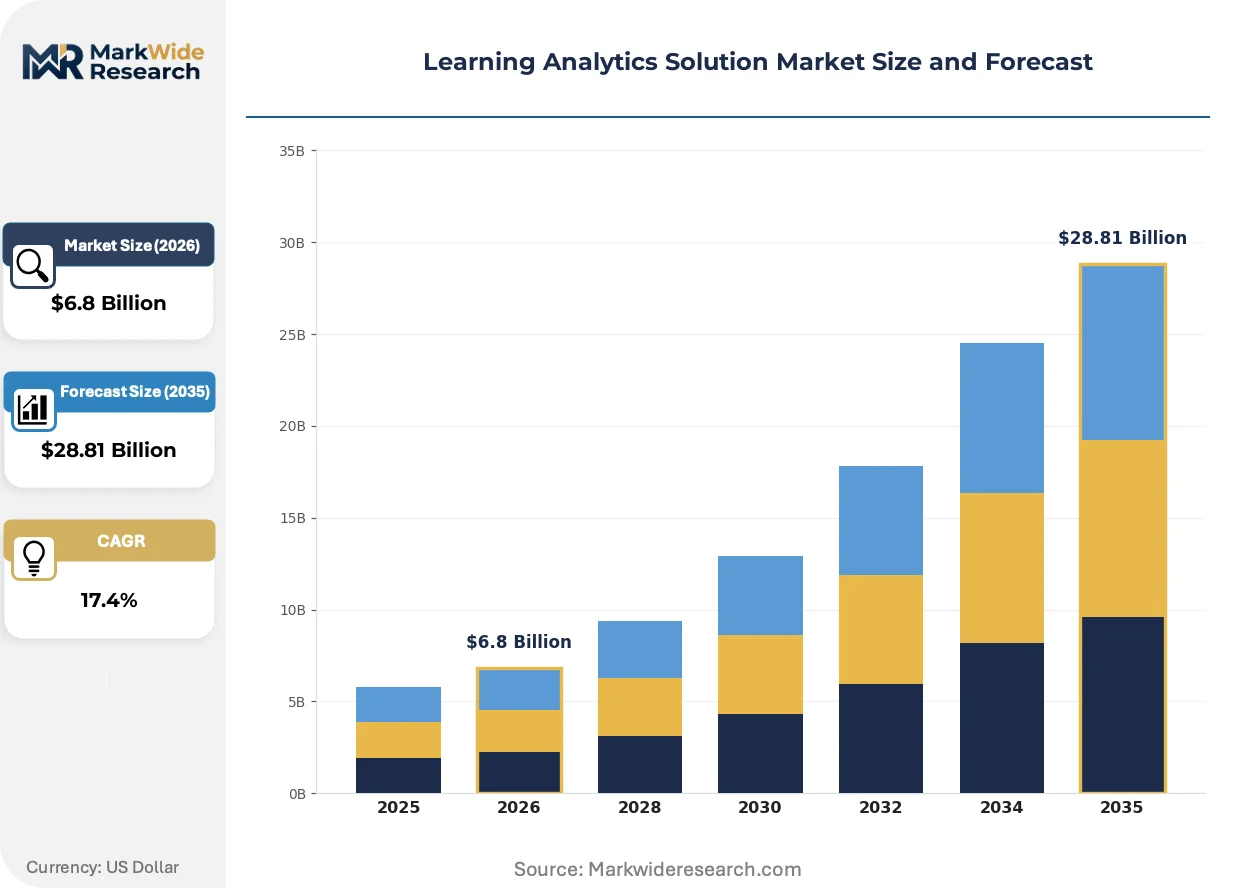
Market Dynamics
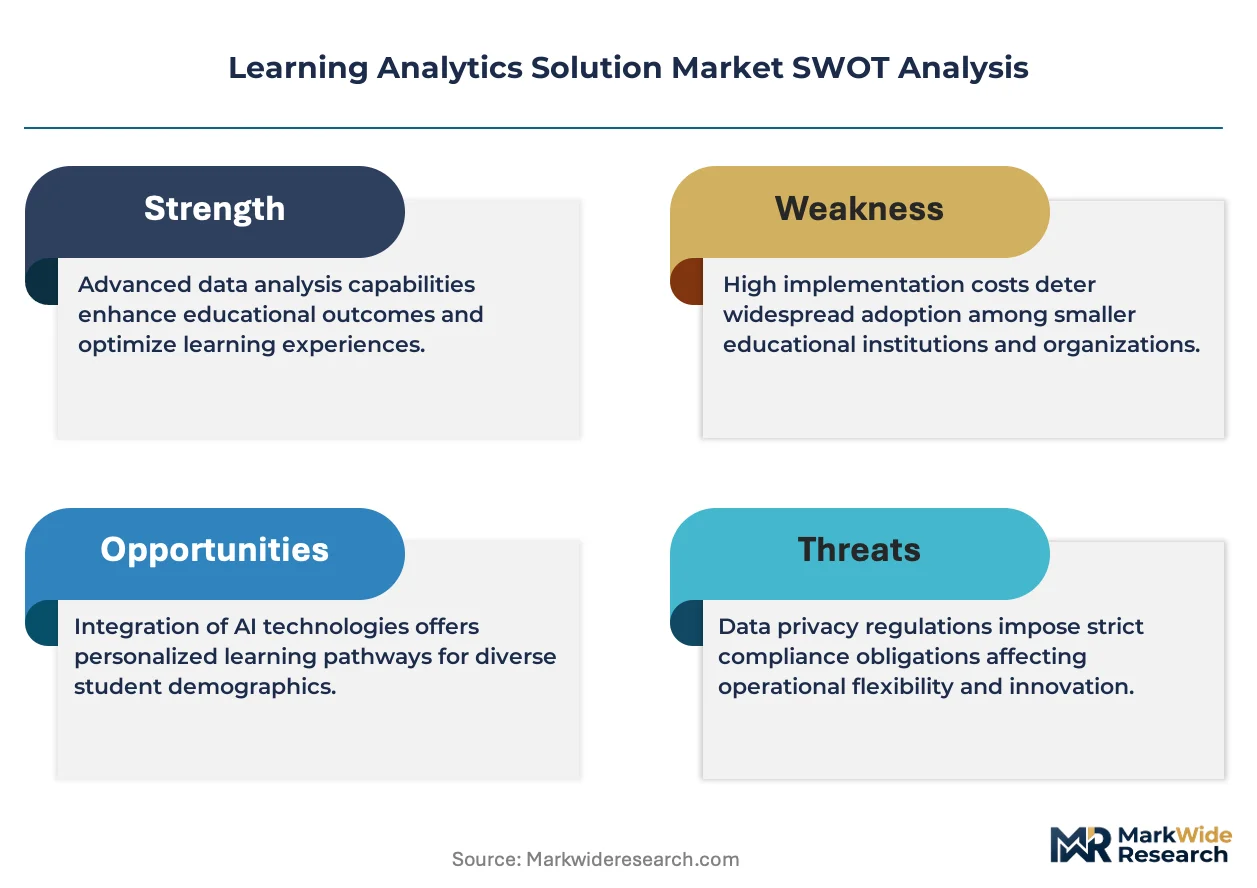
Platform unbundling is fragmenting buyer procurement patterns as universities reject monolithic suites in favor of modular predictive dashboards and data-integration layers sourced from specialized vendors.
Growth Catalysts
- Federal reporting mandates:United States public universities face enrollment transparency requirements that accelerate procurement of predictive analytics modules for student retention programs.
- EU AI Act risk protocols:European campuses must classify automated assessment systems by risk tier, creating compliance-driven refresh cycles for legacy analytics infrastructure.
- Biometric engagement tracking:Wearable sensors and eye-tracking hardware generate multimodal data streams that expand the addressable dataset for intervention algorithms.
Market Restraints
- Cloud-sovereignty constraints:Government agencies in France and Germany retain on-premise configurations, limiting addressable market for pure-SaaS vendors.
- GDPR consent complexity:Learner data processing requires granular opt-in frameworks that increase legal overhead and extend sales cycles.
- Open-source dashboard compression:Apache Superset and Metabase alternatives erode pricing power in mature reporting segments.
Strategic Opportunities
- India's digital university expansion:National Education Policy implementation drives demand for scalable cloud-native analytics across 1,000+ affiliated institutions.
- Skills-based credentialing convergence:Integration of learning analytics with blockchain-verified microcredentials opens new revenue streams in corporate training markets.
- Brazilian federal procurement reform:ANVISA-aligned data governance standards create first-mover advantage for compliant vendors in Latin America's largest education market.
Industry Challenges
- Interoperability with legacy SIS:Student information systems from the 2010s lack API-native architectures, forcing costly middleware development.
- Algorithmic bias audit capacity:Shortage of learning scientists trained in fairness metrics delays deployment of automated early-alert systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Learning Analytics Solution Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Tenant End User: Educational Institutions, Corporate Training, EdTech Companies, Government Agencies Application: Student Performance Tracking, Curriculum Development, Learning Outcome Assessment, Engagement Analytics Solution: Dashboards, Reporting Tools, Predictive Analytics, Data Integration |
| Companies Covered | IBM Corporation, Microsoft, SAP SE, Oracle, D2L Corporation, Tableau Software, SAS Institute Inc., TIBCO Software Inc., Instructure Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Learning Analytics Solution Market Shifts & Advancements
Real-time inference architectures and multimodal data fusion are compressing the latency between learner behavior detection and instructional intervention from weeks to minutes.
Federated learning architectures enable model training across distributed campus datasets without centralizing sensitive learner records. Large university systems in California and Texas pilot these privacy-preserving approaches to circumvent GDPR and FERPA data-transfer restrictions. The technique is rendering obsolete traditional data-warehouse consolidation projects that required physical migration of institutional records.
The EU AI Act's risk-classification framework mandates human-in-the-loop review for high-risk automated assessment systems. Vendors serving European higher education must redesign algorithmic transparency interfaces and maintain audit trails for automated decisions. Predictive enrollment tools face the steepest compliance burden, driving consolidation toward vendors with dedicated regulatory product teams.
Subscription fatigue among procurement officers is displacing perpetual-license renewal patterns. Chief information officers at mid-sized state universities now demand usage-based pricing tied to active student enrollments rather than institution-wide site licenses. This shift is most pronounced in the United Kingdom, where Office for Students accountability metrics pressure finance departments to align technology spend with measurable retention outcomes.
Learning Analytics Solution Market Segmentation
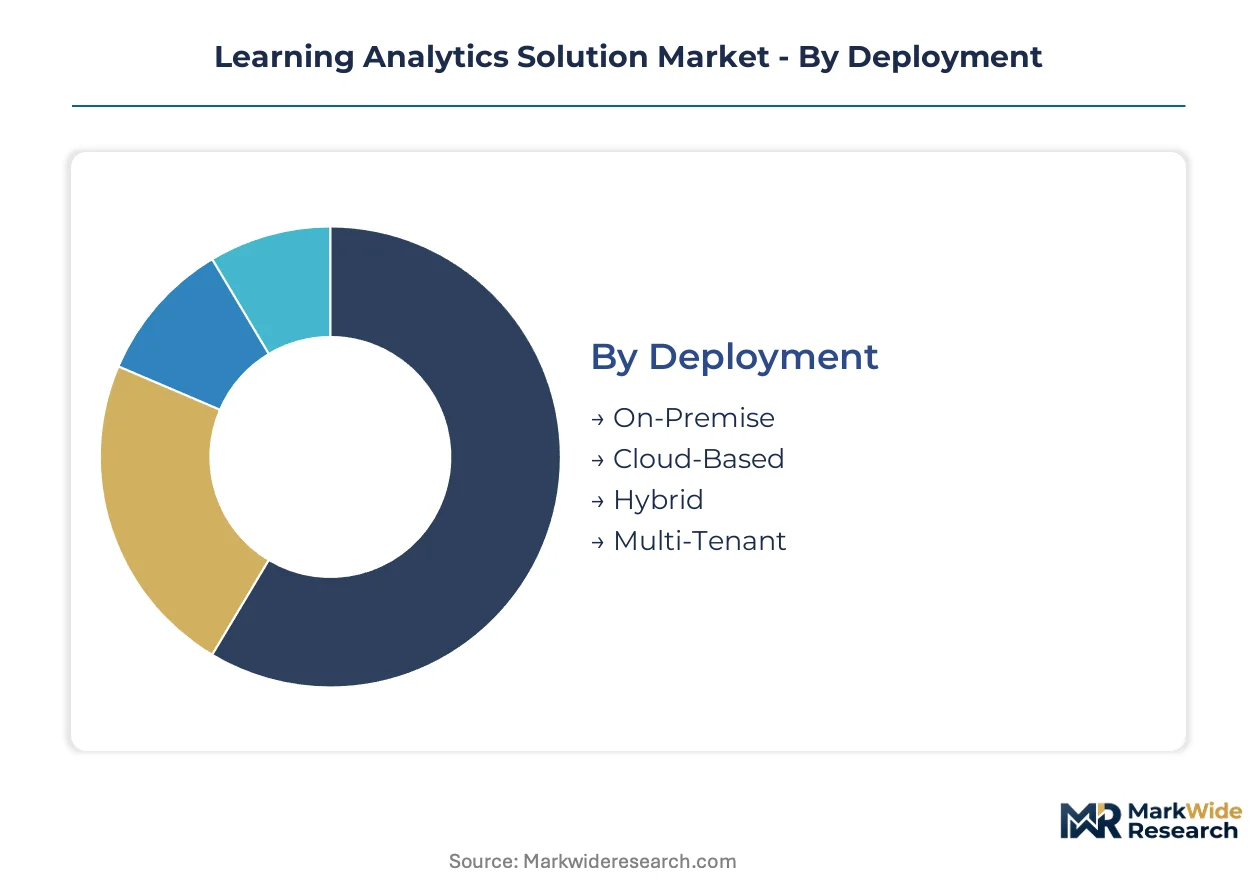
Learning analytics solutions serve fundamentally different operational needs across deployment environments, user types, and analytical applications. Segmentation reveals where procurement budgets concentrate and which feature sets command premium positioning.
Deployment:
Deployment architecture determines data sovereignty compliance, latency performance, and total cost of ownership across institutional IT environments.
- Cloud-Based:SaaS delivery models dominate procurement at mid-sized universities seeking elastic compute for enrollment forecasting workloads. North American public institutions drive volume here, pressured by federal reporting mandates that demand scalable predictive infrastructure without capital expenditure cycles.
- On-Premise:Self-hosted configurations retain mandatory share among French and German government agencies where data-sovereignty constraints block cross-border data flows. These deployments carry higher upfront licensing but eliminate recurring subscription exposure and satisfy national cybersecurity certification requirements.
- Hybrid:Split architectures process sensitive biometric engagement data locally while pushing anonymized aggregates to cloud analytics layers. This pattern gains traction among Texas and California university systems piloting federated learning approaches.
- Multi-Tenant:Shared infrastructure platforms serve India's digital university expansion, where 1,000+ affiliated institutions require standardized analytics dashboards without individual deployment overhead.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
End User:
Buyer sophistication and procurement authority vary sharply across organizational types, shaping solution packaging and sales cycle complexity.
- Educational Institutions:Universities and K-12 districts represent the core revenue base, with procurement concentrated in student retention and early-alert system investments. United States public universities accelerate spending here under enrollment transparency requirements.
- Corporate Training:Enterprise L&D departments seek skills-based credentialing convergence, integrating analytics with blockchain-verified microcredentials. Manufacturing and healthcare verticals show particular appetite for competency-gap identification tools.
- EdTech Companies:Platform vendors embed white-label analytics to differentiate learning management systems, requiring API-native architectures and real-time data pipelines that traditional institutional buyers rarely demand.
- Government Agencies:Federal and state education departments procure at scale for statewide reporting systems, with Brazilian ANVISA-aligned procurement reform creating new compliant vendor opportunities.
Procurement authority concentrates in Educational Institutions; steepest expansion trajectory appears in Corporate Training.
Application:
Functional use cases span the instructional lifecycle from curriculum design through outcome validation, with varying algorithmic complexity requirements.
- Predictive Analytics:Early-alert algorithms for at-risk student identification command the steepest price premiums and fastest growth. United States federal mandates for retention accountability drive deployment across public university systems.
- Student Performance Tracking:Dashboards monitoring assessment scores and assignment completion represent mature functionality where open-source alternatives compress margins. Apache Superset deployments erode pricing power in this segment.
- Learning Outcome Assessment:Statistical models measuring pedagogical effectiveness serve accreditation bodies and quality assurance offices. SAS Institute maintains positioning here through deep methodological heritage.
- Engagement Analytics:Multimodal data fusion from clickstreams, discussion forums, and biometric sensors enables real-time intervention. EU AI Act risk-classification protocols impose compliance overhead on automated engagement scoring systems.
Revenue pools concentrate in Predictive Analytics; regulatory complexity concentrates in Engagement Analytics.
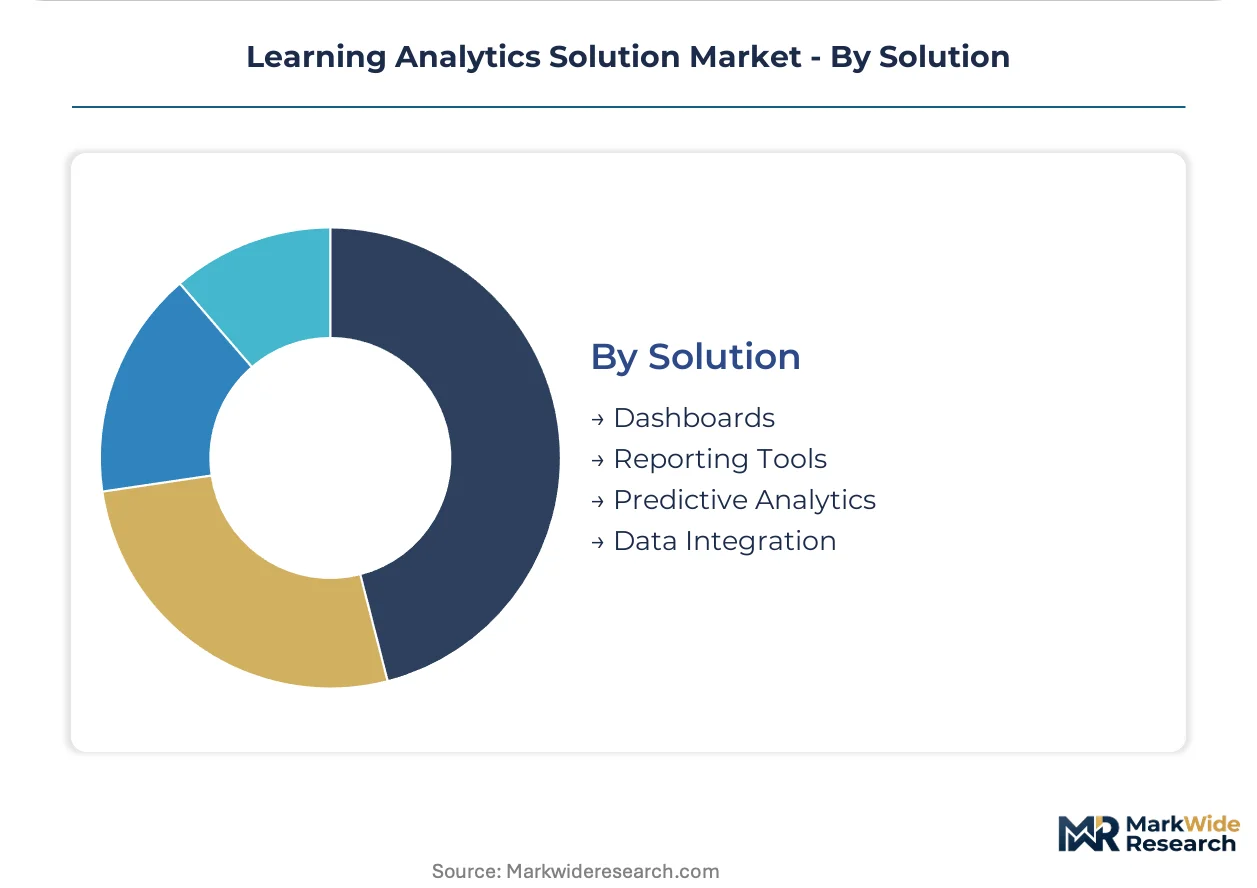
Solution:
Product-layer unbundling allows buyers to assemble modular stacks rather than accepting monolithic suites, fragmenting vendor competitive dynamics.
- Data Integration:Middleware connecting learning management systems, student information systems, and external data sources solves the API deficiency of 2010s-era SIS infrastructure. IBM Watson anchors premium positioning here for large university systems.
- Dashboards:Visualization layers for administrative and instructional audiences face commoditization from open-source alternatives. Procurement officers increasingly demand usage-based pricing tied to active enrollments rather than site licenses.
- Reporting Tools:Scheduled and ad-hoc report generation serves compliance documentation needs. United Kingdom Office for Students accountability metrics pressure finance departments to align spend with measurable retention outcomes.
- Predictive Analytics:Algorithmic modules for enrollment forecasting and risk scoring represent the highest-margin layer, with Microsoft Azure-native tools sustaining integration advantages in institutional productivity workflows.
Margin compression threatens Dashboards; differentiation potential concentrates in Data Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure providers cluster in the United States, while European data-sovereignty requirements sustain on-premise deployment specialists. Procurement patterns diverge sharply across jurisdictions.
United States
Federal reporting mandates from the Department of Education accelerate predictive analytics procurement across public university systems. FERPA enforcement and emerging FTC algorithmic accountability guidance reshape vendor compliance roadmaps. Texas and California university systems pilot federated learning architectures to circumvent data-transfer restrictions.
Germany
Data-sovereignty constraints block cross-border cloud flows, preserving mandatory share for on-premise configurations among government agencies. National cybersecurity certification requirements under BSI standards extend procurement cycles. Berlin-Brandenburg clusters host specialized middleware vendors serving legacy SIS integration needs.
United Kingdom
Office for Students accountability metrics pressure finance departments to align technology spend with measurable retention outcomes. Subscription fatigue displaces perpetual-license patterns among mid-sized state universities. London-based procurement officers increasingly demand usage-based pricing tied to active enrollments.
India
National Education Policy implementation drives demand for scalable cloud-native analytics across 1,000+ affiliated institutions. Multi-tenant shared infrastructure platforms serve digital university expansion without individual deployment overhead. Maharashtra and Karnataka host emerging vendor development centers targeting this procurement wave.
Brazil
ANVISA-aligned data governance standards create first-mover advantage for compliant vendors in Latin America's largest education market. Federal procurement reform opens statewide reporting system contracts at scale. São Paulo clusters concentrate implementation partners serving corporate training convergence with blockchain-verified microcredentials.
Learning Analytics Solution Market Competitive Landscape
Cloud-native platform vendors and legacy statistical software providers split the market along deployment-architecture lines. The vendor base concentrates around three strategic archetypes: hyperscale cloud integrators, specialized predictive analytics boutiques, and open-source dashboard commoditizers. Consolidation pressures intensify as procurement officers reject monolithic suites. Dominant competitive moves include modular unbundling of platform components and federated-learning partnership structures.
Within the hyperscale tier, IBM Corporation and Microsoft exemplify divergent integration strategies—Watson analytics stacks versus Azure-native education tools. SAS Institute Inc. occupies a position in statistical heritage segments. These three anchors demonstrate how premium positioning fragments across data-integration layers, cloud productivity workflows, and methodological assessment models respectively.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft |
| SAP SE |
| Oracle |
| D2L Corporation |
| Tableau Software |
| SAS Institute Inc. |
| TIBCO Software Inc. |
| Instructure Inc. |
| Others |
Supply & Pricing Matrix
Silicon Valley cloud infrastructure clusters anchor global capacity for learning analytics platforms, with hyperscale data center expansion directly conditioning downstream SaaS pricing power for predictive enrollment modules.
Pricing Analysis
FERPA and emerging FTC algorithmic accountability guidance dictate the pricing tier structure across the learning analytics market. Three-tier pricing structure across premium, standard, and economy levels separates Watson-anchored enterprise deployments from Azure-native mid-market suites and open-source dashboard alternatives. Price differentiation rests on integration depth with legacy student information systems and real-time inference latency guarantees. Pricing pressure stems from Apache Superset and Metabase commoditization in mature reporting segments. Mid-sized state universities exhibit highest price sensitivity through usage-based pricing demands, while large university systems in Texas and California absorb premium positioning for federated learning architectures.
Supply Chain Analysis
US Commerce Department export controls on advanced GPU clusters and inference accelerators limit hardware flows to certain national education markets, reshaping deployment architecture availability. Supply concentrates in the United States, Ireland, and Singapore for cloud-native platform development, with India emerging as a secondary hub for multi-tenant shared infrastructure serving digital university expansion. Component dependencies include NVIDIA data center GPUs, ARM-based edge inference chips, and proprietary LTI 1.3 Advantage standard middleware. Single-source vulnerability runs through TSMC-fabricated AI accelerators. Distribution runs through direct enterprise sales teams serving educational institutions and systems integrators embedding white-label analytics for EdTech platform vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics tied to federal enrollment reporting mandate refresh cycles, with procurement waves accelerating as Department of Education transparency requirements renew across state university systems.
For Market Incumbents: Harden compliance infrastructure against divergent transatlantic regulatory architectures. Invest in dedicated EU AI Act product teams to capture European campus refresh cycles. Consolidate middleware capabilities around legacy SIS integration to defend against API-native challengers. Vertical integration into biometric sensor hardware partnerships secures multimodal data pipeline control. For New Entrants and Emerging Players: India's 1,000+ affiliated institutions under National Education Policy implementation represent the most penetrable entry point for cloud-native analytics deployment. Brazilian ANVISA-aligned federal procurement reform opens statewide reporting system contracts for compliant vendors. Skills-based credentialing convergence with blockchain-verified microcredentials in corporate training verticals offers alternative channel development. Partner with Maharashtra-based implementation specialists for digital university market penetration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized predictive analytics boutiques with federated learning IP and regulatory product team infrastructure. Long-term viability across the five-to-ten-year window hinges on algorithmic bias audit capacity and fairness metrics expertise. Acquisition targets should demonstrate deployed early-alert systems at scale with human-in-the-loop review interfaces. Watch for EU AI Act enforcement action against non-compliant automated assessment vendors as inflection indicator for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership Structure | California and Texas university systems pilot privacy-preserving model training across distributed campus datasets without centralizing FERPA-restricted learner records. |
| Regulatory Product Team Investment | Dedicated EU AI Act compliance infrastructure captures European higher education refresh cycles for high-risk automated assessment system vendors. |
| Legacy SIS Middleware Acquisition | API-deficient 2010s-era student information systems force costly integration development, creating defensive moat for established data-integration layer providers. |
| Biometric Sensor Hardware Partnership | Wearable engagement tracking and eye-tracking hardware expand multimodal data streams for real-time intervention algorithm training. |
| Usage-Based Pricing Model Transition | United Kingdom Office for Students accountability metrics pressure finance departments to align technology spend with measurable retention outcomes. |
Research Methodology
A standing panel of chief information officers, learning science directors, procurement officers at mid-sized state universities, and regulatory affairs leads at EdTech platform vendors provided ongoing calibration. Primary interviews combined with secondary validation from EDGAR filings of publicly traded education technology vendors, Department of Education enrollment reporting mandate documentation, EU AI Act implementing guidance, and National Education Policy implementation circulars. Bottom-up institutional procurement tracking triangulated against top-down vendor revenue segmentation across deployment models, end-user categories, and application layers.
Scenario-bracketing framed demand projections across the analysis window, with high-growth, baseline, and constrained trajectories reflecting divergent federal funding environments and regulatory enforcement intensity. Segmentation dimensions modeled include deployment architecture, end-user sophistication tier, application functional complexity, and solution layer modularity. CAGRs derived from institutional procurement cycle analysis and vendor pipeline conversion rates. Forecast inputs incorporated biometric sensor hardware adoption curves and federated learning pilot expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in federal education technology appropriations and cross-border data flow restriction severity would shift the trajectory. Forecasts reflect documented assumptions regarding mandate enforcement consistency and open-source dashboard competitive intensity. Material shifts in EU AI Act risk-classification protocol implementation or FERPA algorithmic accountability guidance finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Europe Retail Analytics Market
Analytics
Spend Analytics Software Market
Analytics
Global Data Fusion Market
Analytics
Global System Monitoring Market
Analytics
Canada Geospatial Imagery Analytics Market
Analytics
US Predictive Analytics Market
Analytics
Global Saas-Based Business Analytics Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
SME Big Data Market
Analytics
Predictive Analytics Market
Analytics
Cloud Performance Management Market
Analytics
Europe Location Data Analytics Market
Analytics
Global Business Intelligence (BI) Software Market
Analytics
Data Analytics in Telecom Market
Analytics
APAC Location Analytics Market
Analytics
Speech and Voice Analytics Market