
 Switzerland E-Commerce Market | 2026-2036
Switzerland E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland E-Commerce Market Analytics
Swiss fulfillment infrastructure is decoupling from traditional retail footprints as dedicated e-commerce logistics parks expand around Basel and Lausanne. Digitec Galaxus AG leverages its domestic electronics specialization to dominate high-consideration purchases. Amazon.com, Inc. competes through Prime delivery density in German-speaking cantons. Coop Genossenschaft sustains grocery e-commerce leadership via integrated last-mile networks from existing store bases.
Switzerland E-Commerce denotes digitally mediated transactions for goods and services executed through web platforms and mobile applications, typically involving encrypted payment gateways, inventory management systems, and multi-node fulfillment orchestration. Its commercial purpose centers on reducing friction between product discovery and physical delivery while capturing granular consumer behavioral data. Electronics and clothing categories anchor transaction volume, though B2C channels generate disproportionate margin concentration relative to B2B flows. Express delivery modes are gaining structural importance as Swiss consumers demonstrate elevated willingness-to-pay for speed.
Swissmedic and the Federal Data Protection and Information Commissioner shape product authenticity requirements and consumer data governance, while FINMA oversight extends to payment service providers operating within the market. The revised Federal Act on Data Protection imposes stricter consent architectures, directly elevating compliance costs for foreign platforms serving Swiss residents. Stakeholders must monitor whether Bern extends digital tax parity measures to level competition between domestic operators and cross-border sellers.
Market Dynamics
The revised Federal Act on Data Protection is compressing operating margins for cross-border platforms while accelerating domestic fulfillment infrastructure buildouts around Basel and Lausanne logistics corridors.
Growth Catalysts
- Same-day fulfillment economics:Urban density in the Zurich-Geneva corridor supports express delivery network expansion. Swiss consumers demonstrate elevated willingness-to-pay for speed.
- FINMA payment authentication protocols:Strengthened oversight elevates trust in encrypted payment gateways. Domestic platforms capture margin from compliance-ready infrastructure.
- Grocery digital channel migration:Integrated last-mile networks from existing store bases enable fresh category penetration. Retailers accelerate warehouse automation investments.
Market Restraints
- Cross-border data governance friction:The Federal Act on Data Protection imposes stricter consent architectures. Foreign platforms face elevated compliance costs serving Swiss residents.
- Last-mile labor cost structure:Alpine topography and cantonal wage regulations compress delivery unit economics. Automation deployment lags urban density requirements.
- German-speaking canton platform concentration:Amazon Prime delivery density creates asymmetric competition. Domestic specialists defend position through category depth.
Strategic Opportunities
- Romandy region underpenetration:French-speaking cantons show lower e-commerce penetration relative to Zurich. Localized platform investments capture latent demand.
- B2B procurement digitization:Industrial supply and medical equipment categories lag B2C sophistication. Specialized vertical platforms address procurement workflow gaps.
- Swissmedic authenticity frameworks:Product verification requirements create premium positioning for compliant sellers. Authentication technology integration differentiates marketplace trust.
Industry Challenges
- Multi-node fulfillment orchestration complexity:Inventory synchronization across decentralized warehouses strains legacy ERP systems. Real-time visibility gaps increase stockout risk.
- Consent architecture engineering talent scarcity:Federal Data Protection and Information Commissioner requirements demand specialized legal-technical hybrid roles. Recruitment lags regulatory timeline pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland E-Commerce Market |
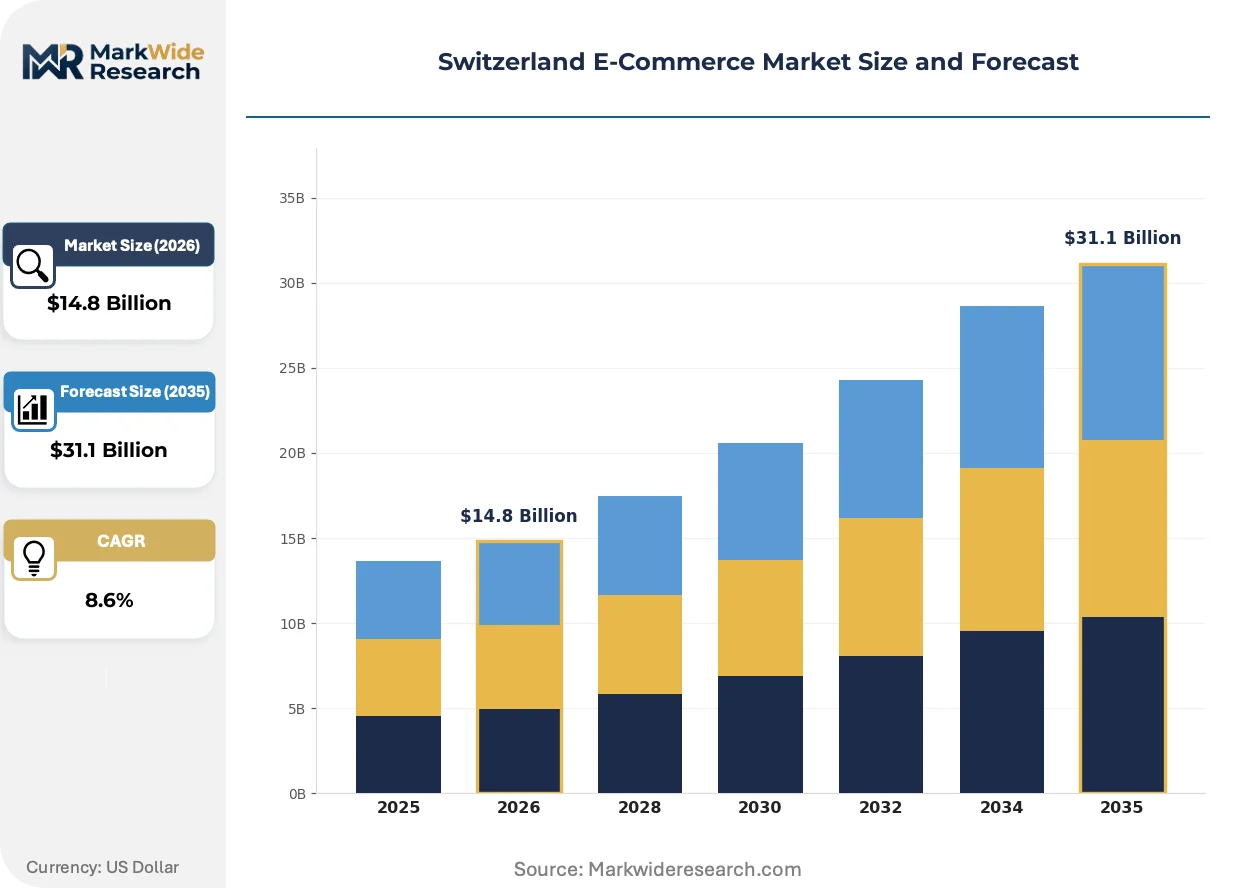
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Beauty Products, Home Goods Customer Type: B2B, B2C, C2C, D2C Payment Method: Credit Card, PayPal, Bank Transfer, Invoice Delivery Mode: Standard Shipping, Express Delivery, Click & Collect, Drop Shipping |
| Companies Covered | Coop Genossenschaft, Brack.ch AG, Digitec Galaxus AG, Nestlé Nespresso SA, Apple Inc., Amazon.com, Inc., Migros-Genossenschafts-Bund, Zur Rose Group AG, Zalando SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland E-Commerce Market Evolving Landscape
Swiss e-commerce infrastructure is pivoting from marketplace aggregation toward vertically specialized fulfillment networks that compress delivery windows while capturing behavioral data for predictive inventory positioning.
Automated micro-fulfillment centers are expanding into urban peripheries around Basel, Lausanne, and Winterthur. Digitec Galaxus AG and Coop Genossenschaft deploy robotic picking systems to process same-day orders. This technology compression is enabling 30-minute delivery promises in dense cantons while reducing per-unit labor costs.
The Federal Act on Data Protection revision mandates granular consent architectures for consumer behavioral tracking. Swissmedic and the Federal Data Protection and Information Commissioner coordinate enforcement across health and general commerce sectors. Cross-border sellers serving Swiss residents must reengineer data flows or exit the market, advantaging domestic platforms with compliant infrastructure.
Subscription-based replenishment models are displacing transactional grocery purchasing in Zurich and Geneva urban cores. Coop Genossenschaft integrates predictive consumption algorithms with existing store-based fulfillment networks. This pattern shift is most visible in household essentials and fresh categories where convenience premiums override price comparison behavior.
Switzerland E-Commerce Market Segmentation
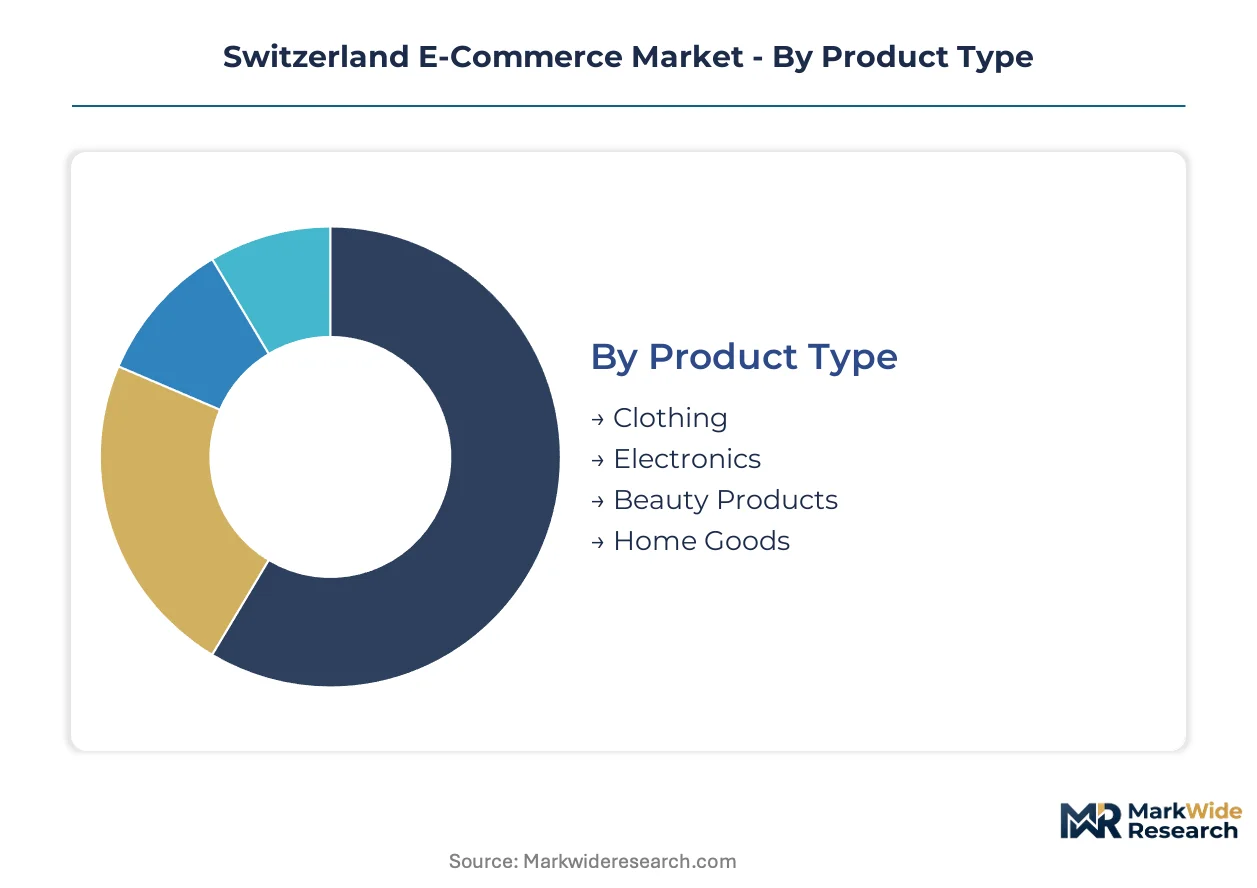
Swiss e-commerce segmentation reveals divergent margin profiles across transaction types. Product category concentration in electronics and clothing drives fulfillment infrastructure investment, while customer type distribution shapes platform architecture and payment authentication requirements.
Product Type:
Buyers in this category differentiate by consideration cycle length and return frequency, with high-consideration purchases demanding specialized logistics and low-margin categories requiring volume efficiency.
- Electronics:High-consideration purchases with extended warranty and technical support requirements. Demand concentrates in the Zurich-Geneva corridor where Digitec Galaxus AG maintains specialized fulfillment networks for same-day delivery of computing and consumer devices.
- Clothing:High return-rate category driving reverse logistics infrastructure investment. Swiss consumers in urban cantons demonstrate elevated willingness-to-pay for speed, compressing delivery windows to same-day or next-day standards.
- Beauty Products:Swissmedic authentication requirements elevate compliance costs for cross-border sellers. Domestic platforms capture margin through verified supply chains and temperature-controlled fulfillment.
- Home Goods:Bulky item logistics strain last-mile networks in Alpine topography. Basel and Lausanne logistics corridors support automated micro-fulfillment for smaller home essentials.
Electronics leads volumes today; beauty products is gaining share fastest through subscription replenishment models.
Customer Type:
Transaction architecture varies sharply by counterparty relationship, with B2B flows demanding procurement workflow integration and direct-to-consumer models requiring granular consent architectures under the revised Federal Act on Data Protection.
- B2C:Dominant transaction volume with disproportionate margin concentration. Swiss consumers demonstrate elevated willingness-to-pay for speed, driving express delivery network expansion in German-speaking cantons.
- B2B:Industrial supply and medical equipment procurement lags B2C sophistication. Specialized vertical platforms address workflow gaps in manufacturing and healthcare sectors.
- D2C:Brand-owned channels bypass marketplace fees but require in-house fulfillment investment. Subscription-based replenishment models displace transactional purchasing in Zurich and Geneva urban cores.
- C2C:Peer-to-peer platforms face elevated trust barriers under FINMA oversight. Secondary market authentication creates positioning for compliant sellers.
B2C dominates transaction value today; B2B is expanding most quickly through procurement digitization.
Payment Method:
Authentication protocol maturity separates domestic platforms from cross-border competitors, with FINMA oversight elevating infrastructure requirements for encrypted gateway providers.
- Credit Card:Strengthened authentication protocols under FINMA elevate trust in encrypted gateways. Domestic platforms capture margin from compliance-ready infrastructure.
- PayPal:Cross-border friction from the revised Federal Act on Data Protection reengineers data flows for foreign providers.
- Bank Transfer:Preferred in B2B procurement workflows for invoice reconciliation. Industrial buyers favor traceable payment rails.
- Invoice:Post-delivery payment elevates default risk but captures convenience-sensitive segments. Buy-now-pay-later models extend this structure.
Credit card leads transaction volume today; bank transfer is climbing the fastest in B2B digitization.
Delivery Mode:
Speed tier selection correlates with urban density and cantonal wage structures, with express economics viable only in the Zurich-Geneva corridor.
- Express Delivery:30-minute and same-day promises enabled by robotic picking in Basel, Lausanne, and Winterthur micro-fulfillment centers. Swiss consumers demonstrate elevated willingness-to-pay for speed.
- Standard Shipping:Cost-optimized option for non-urgent purchases. Alpine topography and cantonal wage regulations compress unit economics.
- Click & Collect:Integrated last-mile networks from existing store bases enable fresh category penetration. Coop Genossenschaft leverages this for grocery e-commerce leadership.
- Drop Shipping:Inventory-light model for marketplace sellers. Multi-node fulfillment orchestration complexity strains legacy ERP systems.
Standard shipping leads volumes today; express delivery shows the steepest expansion trajectory through automated fulfillment investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border e-commerce operators face escalating compliance costs under the revised Federal Act on Data Protection, prompting domestic fulfillment infrastructure buildouts that exploit the regulatory arbitrage gap between foreign and local platforms.
German-Speaking Cantons
Zurich and Basel anchor electronics and general merchandise volume, with Digitec Galaxus AG leveraging specialized fulfillment networks for same-day delivery. FINMA payment authentication protocols elevate trust infrastructure requirements. Automated micro-fulfillment centers in Winterthur process 30-minute delivery promises for urban consumers.
Romandy Region
Geneva and Lausanne exhibit lower e-commerce penetration relative to Zurich, creating latent demand capture opportunities for localized platform investments. The Federal Data Protection and Information Commissioner coordinates enforcement with French-language consumer advocacy groups. Lausanne logistics corridors support robotic picking systems for express grocery fulfillment.
Ticino
Italian-speaking southern cantons demonstrate distinct payment method preferences and cross-border shopping patterns with neighboring Lombardy. Swissmedic product authenticity requirements create compliance barriers for marketplace sellers sourcing from Italian suppliers. Lugano serves as a modest fulfillment node for Alpine cross-border logistics.
Central Switzerland
Lucerne and Zug concentrate B2B procurement digitization for industrial supply and medical equipment categories. The country's national data protection authority mandates granular consent architectures for behavioral tracking. Zug's pharmaceutical cluster drives specialized cold-chain fulfillment requirements for temperature-sensitive shipments.
Swiss Plateau Periphery
Bern and Aargau support distributed warehouse networks that reduce last-mile delivery distances to Alpine communities. Cantonal wage regulations compress unit economics for express delivery in lower-density areas. Bern's administrative concentration shapes regulatory interpretation consistency across enforcement regions.
Switzerland E-Commerce Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue vertical specialization and subscription-based replenishment models. The market structure consolidates around three distinct maturity tiers: domestic retail conglomerates with integrated store-based fulfillment, international marketplace operators with Prime delivery density, and category specialists leveraging authentication technology. Three strategic archetypes dominate: grocery retailers accelerating warehouse automation, electronics platforms deploying robotic picking systems, and cross-border marketplaces reengineering data flows for compliance. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among domestic retail conglomerates, Coop Genossenschaft exemplifies integrated last-mile network leverage from existing store bases, while Migros-Genossenschafts-Bund occupies a position within the grocery e-commerce tier. Digitec Galaxus AG anchors the electronics specialist archetype through domestic fulfillment infrastructure concentration in the Zurich-Geneva corridor.
| Leading Market Players |
|---|
| Coop Genossenschaft |
| Brack.ch AG |
| Digitec Galaxus AG |
| Nestlé Nespresso SA |
| Apple Inc. |
| Amazon.com, Inc. |
| Migros-Genossenschafts-Bund |
| Zur Rose Group AG |
| Zalando SE |
| Others |
Value Network & Pricing Analysis
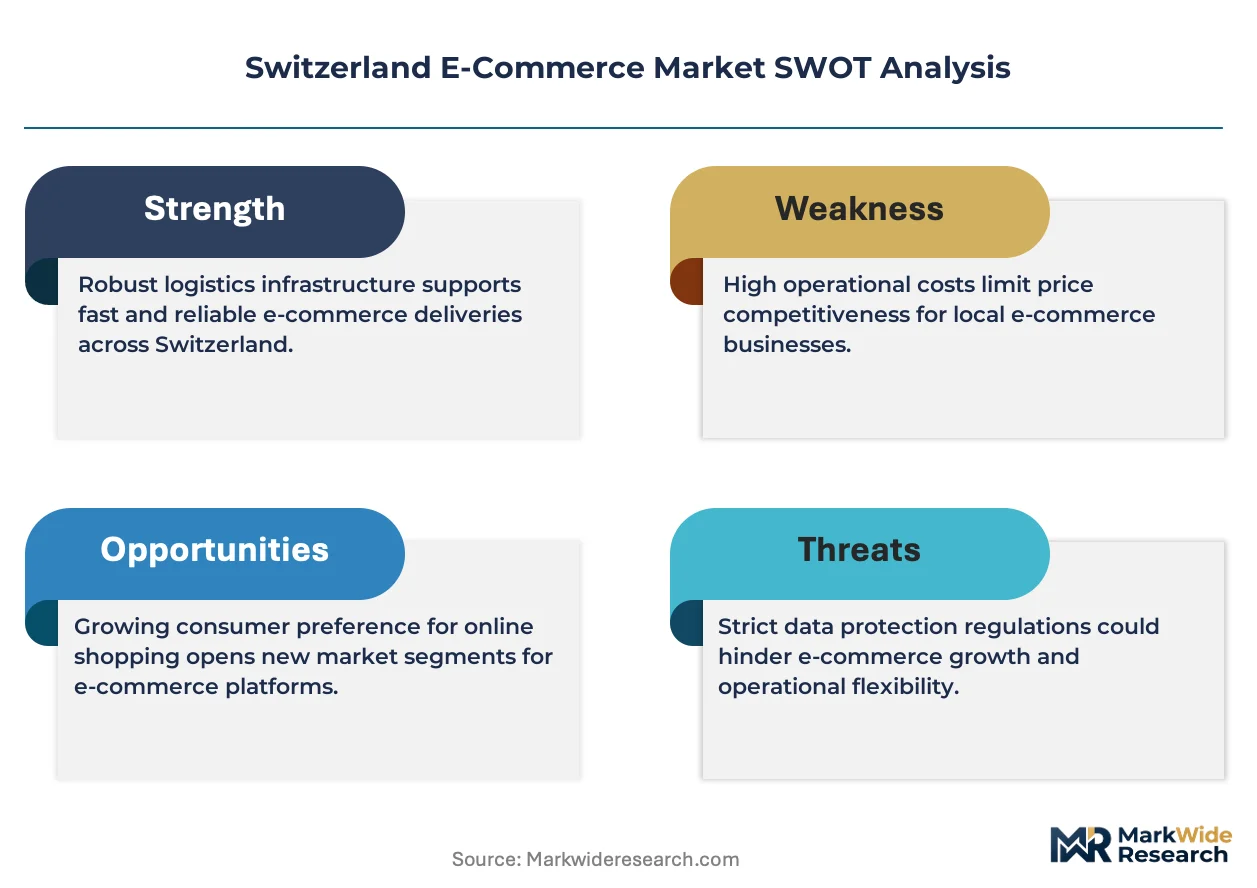
Certification-tier divergence between Swissmedic-compliant domestic platforms and cross-border sellers creates a two-speed pricing architecture where authentication infrastructure investment translates directly into margin capture and supply chain control. Premium positioning accrues to operators bearing FINMA-grade payment authentication and Federal Act on Data Protection consent architecture costs, while non-compliant foreign platforms face forced exit or price erosion through compliance remediation.
Pricing Analysis
Retailer markup compression in grocery categories intensifies as Coop Genossenschaft and Migros-Genossenschafts-Bund automate warehouse operations to offset cantonal wage pressures. Price differentiation stratifies across express delivery premiums, subscription replenishment bundling, and marketplace commission tiers. Pricing pressure stems from last-mile labor cost inflation in Alpine topography. B2B procurement buyers demonstrate lowest price sensitivity due to invoice reconciliation requirements, while C2C peer-to-peer segments exhibit highest elasticity.
Supply Chain Analysis
Reverse-logistics flows for clothing returns strain decentralized warehouse networks, driving investment in automated sortation at Basel and Lausanne logistics corridors. Manufacturing concentration draws from China, Germany, and Italy for electronics, apparel, and home goods respectively. Component dependencies rest on semiconductor chips, lithium-ion cells, and temperature-controlled packaging materials. Single-source vulnerability concentrates in Swissmedic-regulated beauty product authentication technology. Distribution runs through integrated last-mile networks from existing store bases and dedicated e-commerce logistics parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Switzerland E-Commerce Market functions as a stable compounder anchored by urban density economics in the Zurich-Geneva corridor that sustain express delivery network expansion and subscription replenishment model penetration.
For Market Incumbents: Extend automated micro-fulfillment capacity in Winterthur and Lausanne to compress delivery windows against Amazon Prime density. Deepen vertical integration into predictive inventory positioning algorithms to defend margin against grocery digital channel migration. Reinforce Swissmedic authentication infrastructure to maintain premium positioning as cross-border sellers reengineer data flows.
For New Entrants and Emerging Players: Capture latent demand in Romandy region French-speaking cantons where localized platform investment gaps persist. Target B2B procurement digitization in Lucerne-Zug industrial supply corridors as the most penetrable white-space segment. Deploy specialized vertical marketplace architecture addressing medical equipment workflow gaps.
For Investors and Strategic Acquirers: Consolidation pressure builds where compliance-ready infrastructure scarcity advantages domestic platforms over reengineering cross-border competitors. Long-term viability favors operators with captive fulfillment networks and FINMA authentication certification. Monitor Federal Data Protection and Information Commissioner enforcement intensity as inflection signal for foreign platform exit velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Micro-Fulfillment Expansion | Robotic picking in Basel-Lausanne corridors enables 30-minute delivery promises against Prime density. |
| Subscription Replenishment Model Launch | Predictive consumption algorithms integrated with Coop store networks displace transactional grocery purchasing. |
| Swissmedic Authentication Technology Integration | Product verification infrastructure differentiates marketplace trust for beauty and medical equipment categories. |
| Romandy Region Localization Investment | French-language platform adaptation captures underpenetrated Geneva-Lausanne demand relative to Zurich. |
| B2B Procurement Workflow Platform Development | Specialized vertical platforms address industrial supply digitization gaps in manufacturing and healthcare sectors. |
Research Methodology
Bottom-up transaction volume modeling reconciled against top-down fulfillment infrastructure tracking forms the analytical core of this study. Primary interviews with e-commerce operations directors, logistics park developers, FINMA compliance officers, and grocery retail category managers combined with secondary validation from Swiss Federal Statistical Office trade data, FINMA payment service provider registrations, and Federal Data Protection and Information Commissioner enforcement disclosures. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of same-day fulfillment penetration and subscription model adoption rates informed the projection framework. Segmentation dimensions modeled include product category consideration cycle, customer type transaction architecture, payment method authentication tier, and delivery mode speed premium across the analysis window. CAGRs derive from urban density corridor expansion trajectories and regulatory compliance cost pass-through assumptions. Forecast inputs incorporate cantonal wage regulation indexing and Swissmedic authentication requirement phase-in schedules.
Regulatory enforcement intensity, cross-border data flow restriction expansion, and automated fulfillment technology deployment velocity are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions about Federal Act on Data Protection interpretation consistency and FINMA authentication protocol adoption rates. Practitioners should monitor Federal Data Protection and Information Commissioner staffing levels and Alpine logistics automation investment announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
China Alcohol E-Commerce Market
E-Commerce Solutions
Europe Automotive E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
United States E-Commerce Logistics Market
E-Commerce Solutions
Slovakia E-Commerce Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
E-Commerce App Market