
 Carrier Aggregation Solutions Market | 2026-2036
Carrier Aggregation Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Carrier Aggregation Solutions Market Analysis
Market Context
Baseband chipset fabrication in Taiwan is restructuring capacity allocation toward advanced modem architectures. Qualcomm Technologies leverages its integrated Snapdragon platforms to dominate premium-tier carrier aggregation design wins. Huawei Technologies sustains captive silicon development despite foundry access constraints, anchoring its base station portfolio in domestic Chinese deployments.
Technical Definition and Segment Structure
Carrier aggregation solutions combine multiple fragmented spectrum blocks into unified logical channels, enabling throughput beyond single-carrier limits through inter-band and intra-band bonding across licensed and unlicensed frequencies. The technology serves commercial mobile networks by boosting spectral efficiency where contiguous bandwidth is scarce. LTE-Advanced deployments still occupy the largest installed base, though 5G NR aggregation is capturing the fastest expansion in operator capex as mmWave and sub-6 GHz combinations proliferate. Cloud-based deployment models are attracting enterprise and managed services demand, while on-premise hardware retains margin concentration among incumbent telecom operators with existing radio access network infrastructure.
Regulatory Environment
The FCC in the United States, MIIT in China, and ETSI through its 3GPP contributions in Europe each shape spectrum allocation rules that directly determine which band combinations equipment vendors must support. REACH and RoHS compliance in Europe plus FCC equipment authorization in the United States constrain hardware material selection and electromagnetic emissions profiles. Stakeholders must monitor pending 3GPP Release 19 timeline decisions and corresponding national spectrum auction schedules to align R&D roadmaps with enforceable band combinations before competitor platforms lock in operator procurement cycles.
Market Dynamics
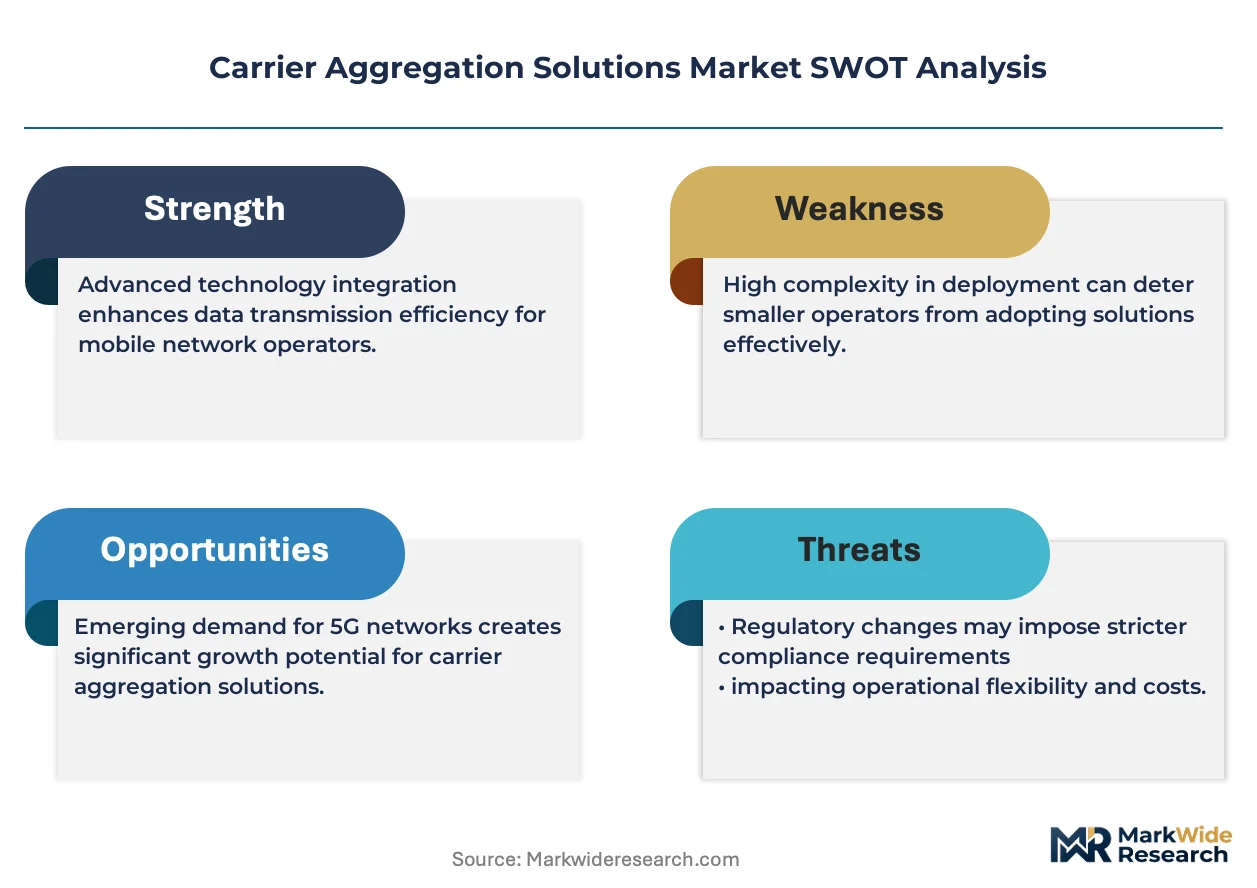
3GPP Release 18 specifications are tightening performance benchmarks for multi-band coordination, forcing baseband chipset vendors and telecom equipment manufacturers to accelerate R&D cycles while recalibrating interoperability testing protocols across fragmented spectrum allocations.
Growth Catalysts
- MIIT spectrum policy:China's accelerated domestic baseband chipset development is compressing procurement timelines for carrier aggregation-enabled base stations across tier-one cities.
- 5G NR mmWave-sub-6 GHz bonding:Telecom operators in South Korea are expanding deployments to manage surging mobile broadband traffic in dense urban corridors.
- Cloud-based deployment models:Enterprise and managed services demand is pulling software-defined radio architectures into private network configurations.
Market Restraints
- Foundry access constraints:Captive silicon development in China faces lithography equipment limitations that compress advanced node availability for modem architectures.
- REACH and RoHS compliance:European hardware material selection rules constrain electromagnetic emissions profiles and extend certification timelines.
- Contiguous bandwidth scarcity:Single-carrier physical layer limitations persist in sub-1 GHz bands where spectrum fragmentation remains structurally embedded.
Strategic Opportunities
- Unlicensed spectrum integration:LTE-LAA and 5G NR-U convergence in enterprise campus networks enables neutral host business models.
- Pending 3GPP Release 19 timeline:Early alignment with band combination specifications allows equipment vendors to lock operator procurement cycles ahead of competitor platforms.
- India's TRAI spectrum roadmap:Mid-band auction schedules for 3.5 GHz and 26 GHz are creating fresh base station replacement demand.
Industry Challenges
- Interoperability certification backlog:GCF and PTCRB testing queue compression delays commercial launch timelines for multi-vendor aggregation configurations.
- Legacy LTE-Advanced infrastructure:Operator capex bifurcation between maintaining installed base and migrating to 5G NR aggregation strains technical workforce allocation.
- Radio frequency front-end integration:Filter and power amplifier co-design complexity escalates with inter-band spacing requirements across non-contiguous allocations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carrier Aggregation Solutions Market |
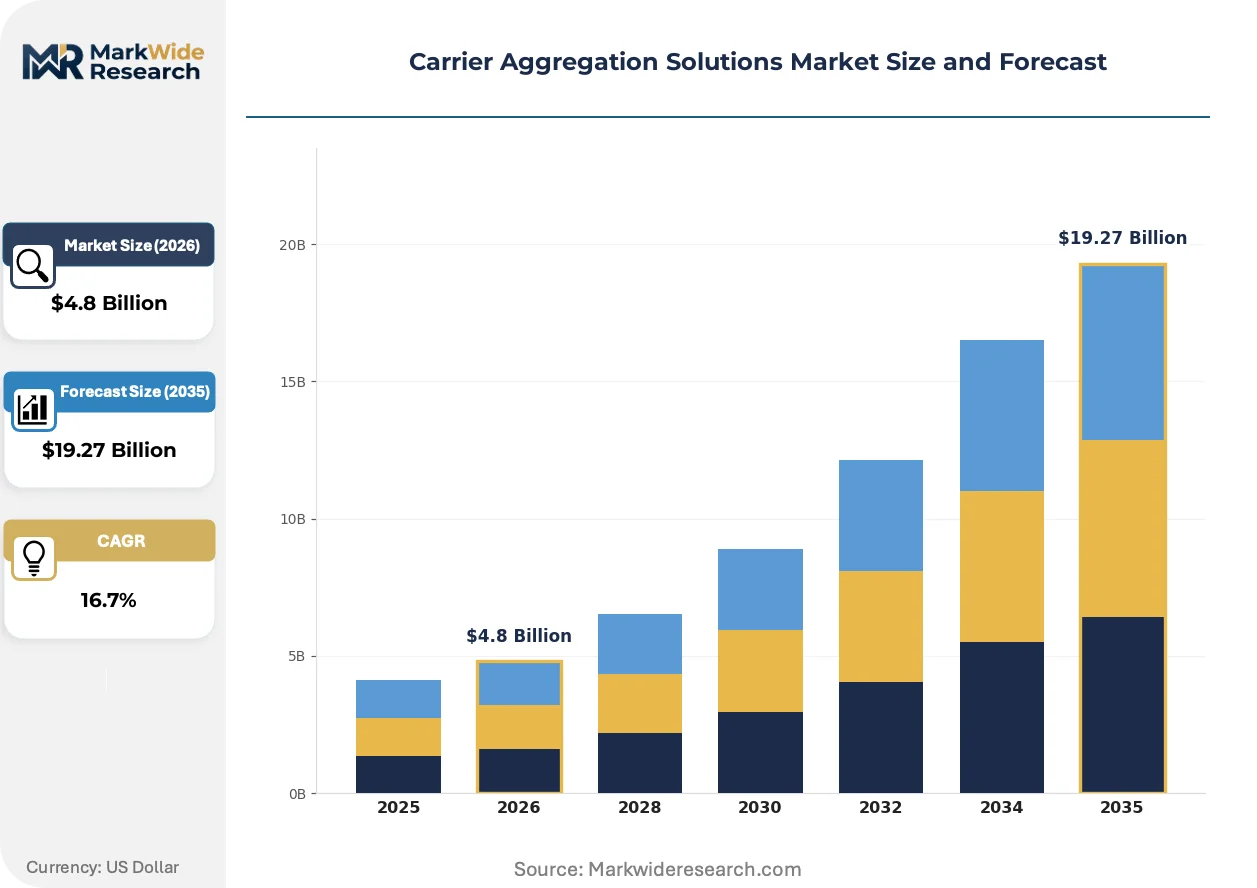
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LTE, LTE-Advanced, 5G NR, HSPA Deployment Model: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Telecom Operators, Enterprises, Government, Research Institutions Application: Mobile Broadband, IoT, Video Streaming, Smart City Solutions |
| Companies Covered | Qualcomm Technologies, Inc., Huawei Technologies Co., Ltd., Telefonaktiebolaget LM Ericsson, Nokia Corporation, Broadcom, Inc., Cisco Systems, Inc., Samsung Electronics Co., Ltd., ZTE Corporation, Verizon Communications, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carrier Aggregation Solutions Market Emerging Trajectories
Open RAN disaggregation is dismantling vertically integrated vendor stacks, forcing modular interface standardization that redistributes value capture across chipset, software, and systems integrator tiers.
Massive MIMO beamforming hardware is modularizing through O-RAN 7-2x split architectures, allowing telecom operators to mix radio unit suppliers with centralized baseband processing pools. Tier-one carriers in Japan and Germany are piloting multi-vendor aggregation stacks that compress single-source dependency. This modularization is fragmenting procurement patterns and eroding traditional turnkey contract structures.
The FCC's accelerated C-band clearing mandates and corresponding equipment authorization rulemakings are compressing deployment windows for 3.7-3.98 GHz aggregation combinations. Base station OEMs must recalibrate filter specifications and power amplifier linearity targets to meet tightened out-of-band emission limits. Rural coverage obligations attached to mid-band licenses are redirecting R&D toward extended-range massive MIMO variants.
Neutral host infrastructure procurement is displacing traditional carrier-captive deployment models in stadiums, airports, and commercial real estate verticals. Tower companies and systems integrators are capturing aggregation solution specification authority previously held by mobile network operators. This shift concentrates most visibly in the United States and United Kingdom where regulatory frameworks for shared spectrum access have matured.
Carrier Aggregation Solutions Market Segmentation
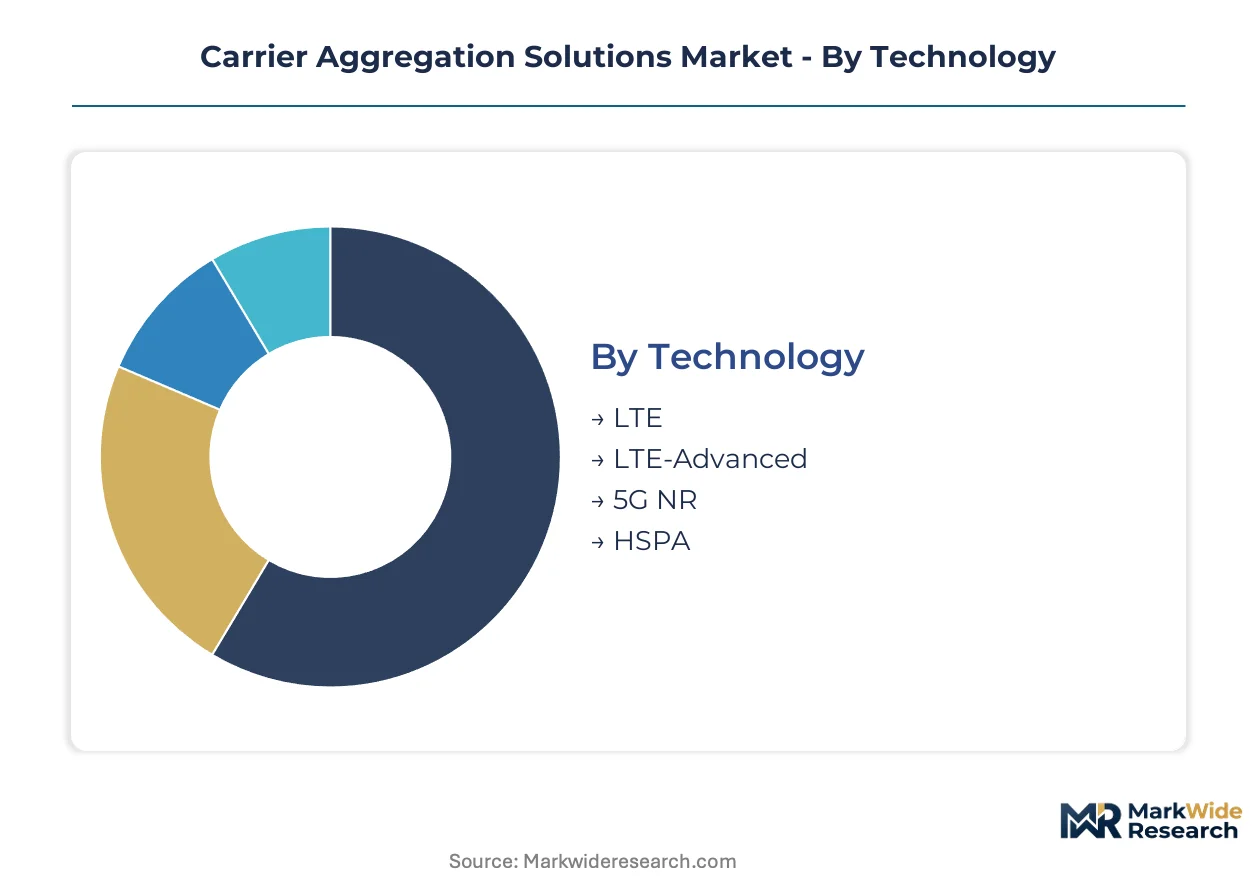
Carrier aggregation solutions require precise segmentation mapping to align baseband chipset architectures with operator procurement cycles. Each dimension—technology generation, deployment topology, buyer type, and use case—commands distinct R&D resource allocation and certification timelines.
Technology:
Upgrade cycles from legacy LTE infrastructure toward 5G NR aggregation are compressing interoperability testing windows as operators phase out single-carrier equipment.
- LTE-Advanced:Inter-band and intra-band bonding across fragmented sub-6 GHz allocations remains the dominant installed base. Telecom operators in South Korea and Japan maintain this technology for backward compatibility during 5G NR migration.
- 5G NR:mmWave-sub-6 GHz combinations and carrier aggregation across 3GPP Release 18 band definitions are capturing the steepest operator capex increases. MIIT spectrum policy in China is accelerating domestic baseband chipset qualification for these configurations.
- LTE:Baseline dual-carrier aggregation serves cost-sensitive deployments in emerging markets where spectrum refarming proceeds gradually.
- HSPA:Legacy triple-carrier bonding persists in rural coverage extensions and specialized machine-to-machine applications with extended equipment lifecycles.
LTE-Advanced sits at the top of the volume ranking, with 5G NR climbing the fastest.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise hardware from operating-expense-driven cloud architectures.
- On-Premise:Dedicated baseband processing units and radio access network hardware dominate incumbent telecom operator deployments. FCC equipment authorization timelines and REACH compliance requirements extend procurement cycles for these configurations.
- Cloud-Based:Software-defined radio architectures with centralized baseband processing pools attract enterprise private network demand. Tier-one carriers in Germany pilot these models for stadium and airport neutral host infrastructure.
- Hybrid:Split architectures combining edge radio units with cloud-native core processing address rural coverage obligations attached to mid-band licenses.
- Managed Services:Third-party systems integrators assume lifecycle responsibility for aggregation solution deployment and optimization.
On-Premise retains the largest revenue share, though Cloud-Based deployments are expanding most quickly.
End User:
Customer type determines specification authority and contract structure, from carrier-captive procurement to neutral host arrangements.
- Telecom Operators:Mobile network operators specify band combinations and interoperability requirements across multi-vendor supply chains. 3GPP Release 18 performance benchmarks dominate their technical evaluation criteria.
- Enterprises:Manufacturing campuses and logistics hubs deploy private 5G NR aggregation for deterministic latency applications.
- Government:Public safety networks and defense communications require hardened equipment with extended environmental operating ranges.
- Research Institutions:Universities and standards bodies operate testbeds for pre-standard band combination validation.
Telecom Operators command the highest absolute spending, with Enterprises gaining specification authority fastest.
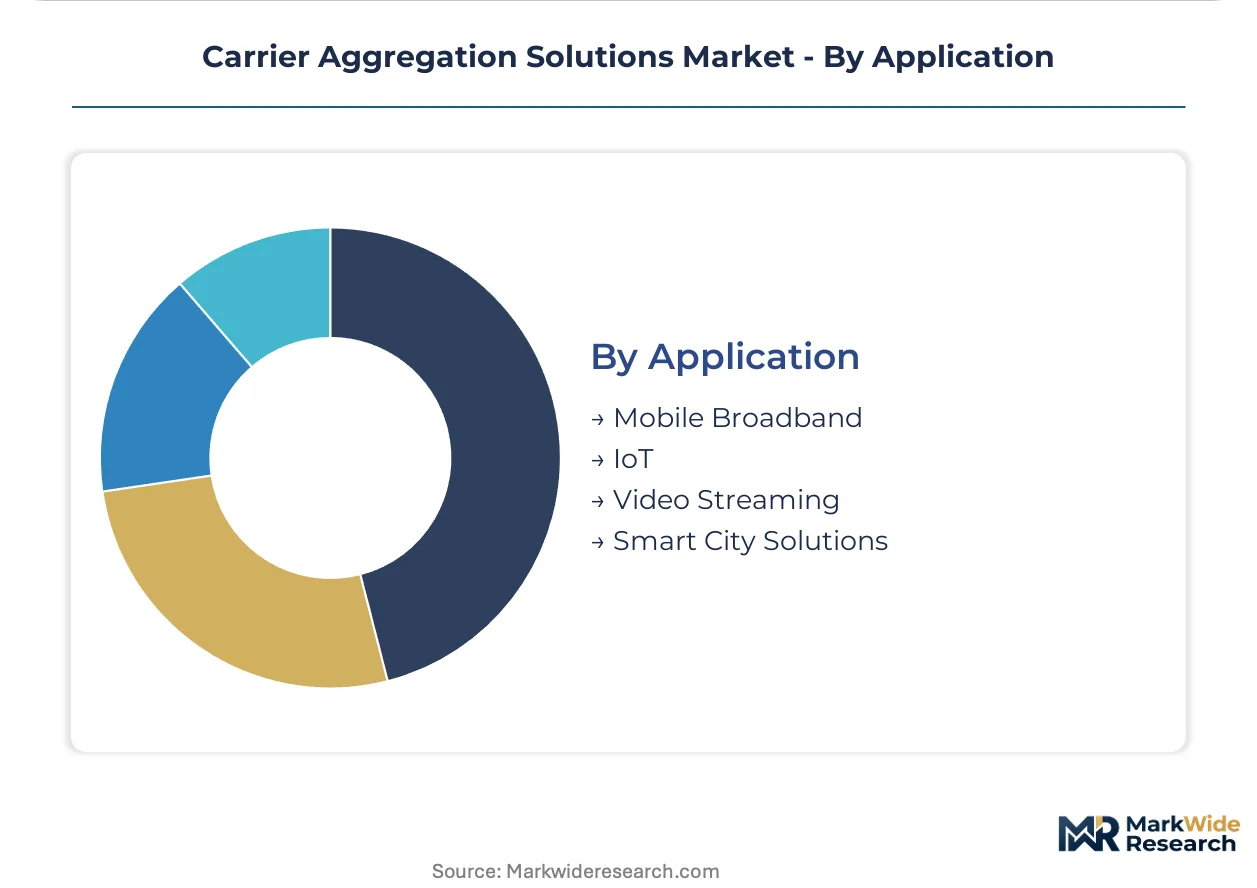
Application:
Maturity differentiation separates established mobile broadband from emerging IoT and smart city configurations.
- Mobile Broadband:Consumer data traffic aggregation across licensed spectrum blocks constitutes the foundational use case. South Korean operators expand 5G NR deployments specifically to manage surging throughput demand in dense urban corridors.
- Video Streaming:Sustained uplink capacity for live broadcast and user-generated content drives symmetric carrier aggregation requirements.
- IoT:Massive machine-type communications utilize narrowband aggregation across sub-1 GHz fragments for extended coverage.
- Smart City Solutions:Traffic management and environmental monitoring networks combine licensed and unlicensed spectrum bonding.
Mobile Broadband maintains the deepest installed base, with Smart City Solutions showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean operators deploy 5G NR carrier aggregation at scale, while German carriers pilot multi-vendor open RAN stacks. China's MIIT spectrum mandates compress domestic chipset qualification timelines. India's TRAI mid-band auctions and the FCC's C-band clearing rules reshape equipment procurement across three continents.
United States
Verizon and AT&T expand C-band aggregation deployments to meet rural coverage obligations attached to mid-band licenses. FCC equipment authorization rulemakings compress deployment windows for 3.7-3.98 GHz combinations. Tower companies in Texas and the Southeast specify neutral host infrastructure for stadium and airport verticals.
China
MIIT spectrum policy accelerates domestic baseband chipset development for 5G NR mmWave-sub-6 GHz bonding. National regulators mandate accelerated procurement timelines for carrier aggregation-enabled base stations across tier-one cities. Huawei Technologies anchors captive silicon production in Shenzhen and Dongguan clusters despite foundry access constraints.
South Korea
SK Telecom and KT Corporation expand 5G NR carrier aggregation to manage surging mobile broadband traffic in Seoul and Busan dense urban corridors. The Korea Communications Commission enforces interoperability benchmarks for multi-band coordination. Samsung Electronics drives R&D concentration in Suwon and Pyeongtaek semiconductor complexes.
Germany
Deutsche Telekom pilots cloud-based aggregation architectures for enterprise private networks in Munich and Frankfurt industrial zones. ETSI contributions through 3GPP shape European spectrum allocation rules for Release 18 band combinations. REACH and RoHS compliance requirements extend certification timelines for base station hardware deployments.
India
Reliance Jio and Bharti Airtel await TRAI spectrum roadmap clarity for 3.5 GHz and 26 GHz mid-band auctions. The Department of Telecommunications links base station replacement demand to national 5G rollout targets. Bangalore and Hyderabad clusters concentrate systems integrator capacity for managed services deployment.
Carrier Aggregation Solutions Market Vendor Landscape
United States and South Korean producers anchor the premium-tier chipset segment; Chinese specialists hold captive positions in domestic base station deployments. The market structures around three tiers: integrated platform vendors, modular radio unit suppliers, and systems integrators capturing neutral host specification authority. Competitive moves concentrate on strategic partnerships for open RAN interoperability and vertical integration into filter and power amplifier co-design.
Among integrated platform vendors, Qualcomm Technologies, Inc. and Samsung Electronics Co., Ltd. occupy positions exemplifying premium-tier Snapdragon and Exynos modem architectures. Huawei Technologies Co., Ltd. represents the captive silicon archetype, sustaining baseband development despite external foundry constraints. These three companies illustrate how geographic origin and corporate structure shape competitive positioning across divergent regulatory environments.
| Leading Market Players |
|---|
| Qualcomm Technologies, Inc. |
| Huawei Technologies Co., Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Broadcom, Inc. |
| Cisco Systems, Inc. |
| Samsung Electronics Co., Ltd. |
| ZTE Corporation |
| Verizon Communications, Inc. |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China's semiconductor clusters anchor supply behavior while compressing pricing discipline for baseband chipset procurement. MIIT spectrum mandates accelerate domestic qualification timelines, forcing private-equity-rolled-up radio unit specialists to recalibrate margin structures against state-subsidized competition.
Pricing Analysis
Capacity additions in Taiwan are reshaping price floors for advanced modem architectures as foundry utilization rates shift. Three-tier pricing structure across premium, standard, and economy levels separates Qualcomm Snapdragon platforms from Huawei captive silicon and emerging MediaTek alternatives. Cost compression in the standard tier intensifies because Chinese OEMs scale domestic baseband production. Enterprise buyers show highest price sensitivity, while telecom operators in South Korea and Germany absorb premiums for 3GPP Release 18 certification.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan's leading-edge lithography capacity for 7nm and below modem fabrication. Taiwan, South Korea, and the United States concentrate supply for baseband silicon, RF front-end components, and test equipment respectively. The chain draws from gallium arsenide substrates, high-purity silicon wafers, and specialized filter ceramics as critical inputs. Tariff exposure on semiconductor manufacturing equipment constitutes the dominant structural risk. Distribution runs through direct OEM contracts with tier-one carriers, bypassing traditional distributor networks for aggregation-specific hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory momentum into procurement cycles, with 3GPP Release 19 timeline decisions functioning as the pivotal demand catalyst across operator capex planning.
For Market Incumbents: Cement interoperability certification leadership by compressing GCF and PTCRB testing timelines ahead of competitor submissions. Prioritize backward integration into filter and power amplifier co-design to capture margin erosion from open RAN disaggregation. The threat of modular radio unit suppliers eroding turnkey contract structures demands captive RF front-end capability.
For New Entrants and Emerging Players: Begin with neutral host infrastructure specifications in United States stadium and airport verticals where tower companies have displaced carrier procurement authority. India's pending TRAI mid-band auctions offer the most penetrable geography for base station replacement demand. A software-defined radio architecture with cloud-native core processing provides the cleanest go-to-market angle against incumbent hardware incumbency.
For Investors and Strategic Acquirers: Valuations sit cheapest among modular radio unit suppliers lacking baseband silicon integration but commanding open RAN specification authority. The five-to-ten-year viability window favors acquisition targets with O-RAN 7-2x split architecture certification and established operator pilot relationships. Watch for 3GPP Release 19 band combination finalization as the inflection signal locking procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| 3GPP Release 19 Alignment | Early specification commitment locks operator procurement cycles ahead of rival platforms. |
| RF Front-End Backward Integration | In-house filter and power amplifier production captures margin from open RAN fragmentation. |
| Neutral Host Partnership | Tower company relationships in Texas and the Southeast redirect specification authority from carriers. |
| Cloud-Native Baseband Development | Software-defined architectures penetrate enterprise private networks in German industrial zones. |
| MIIT Spectrum Compliance Investment | Domestic Chinese qualification accelerates base station deployment across tier-one cities. |
Methodological Framework
Multiple input streams — semiconductor foundry utilization data, operator capex disclosure filings, and 3GPP contribution tracking — were reconciled through bottom-up and top-down triangulation. Primary interviews with baseband chipset architects, telecom procurement directors, and open RAN systems integrators informed demand-side assumptions. Secondary validation drew from FCC equipment authorization databases, MIIT spectrum policy releases, ETSI standardization contributions, and SEC filings from listed equipment vendors.
Segmentation-level reconciliation across technology generation, deployment topology, and end-user type anchored the analytical framework across the projection horizon. Modeled dimensions included LTE-Advanced versus 5G NR migration curves, on-premise versus cloud-based architecture splits, and telecom operator versus enterprise specification authority shifts. CAGRs were derived from equipment shipment trajectories and average selling price evolution across the analysis window, with foundry capacity constraints and spectrum auction schedules functioning as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor access, abrupt 3GPP timeline delays, and unlicensed spectrum regulatory reversals. Forecasts reflect documented assumptions regarding operator migration pace and foundry yield recovery. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Denmark ICT Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
IP Telephony Market
Telecommunications
Esim Subscription Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Indonesia Volte Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
IP DECT Phones Market
Telecommunications
Transport Stream Switching Market
Telecommunications
A2P Messaging Market
Telecommunications
Malaysia Telecom Towers Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
DWDM System Market
Telecommunications
Turkey Telecom Market
Telecommunications
Cambodia Telecom Market