
 Virtualized RAN (Vran) Market | 2026-2036
Virtualized RAN (Vran) Market Size, Share, and Industry Trends Forecast 2026-2036
Virtualized RAN (Vran) Market Analytics
Software-defined network management subscriptions is expanding as the primary monetization layer for vRAN vendors, shifting revenue from perpetual hardware licenses to recurring service contracts. Nokia Corporation leverages its end-to-end portfolio to anchor large-scale brownfield modernization programs across European telecom operators. Samsung Electronics Co., Ltd. dominates 5G vRAN deployments in North American markets through its cloud-native baseband portfolio. Ericsson sustains R&D intensity in intelligent automation features that reduce operational expenditure for carrier customers.
Virtualized RAN disaggregates baseband processing from proprietary hardware into software running on commercial off-the-shelf servers, using open interfaces and containerized network functions to enable multi-vendor interoperability and elastic capacity scaling. Cloud-RAN architectures concentrate the largest installed base among technology segments, while Open RAN protocols attract the fastest-growing share of new greenfield deployments as interoperability testing matures. Private Cloud deployment models command premium margins from enterprises and government buyers seeking data sovereignty controls, whereas Public Cloud instances gain traction among managed service providers delivering network-as-a-service offerings to mid-market telecom operators.
The FCC in the United States and the European Commission through its 5G cybersecurity toolbox impose supply chain diversification and vendor interoperability requirements that accelerate Open RAN procurement timelines. Japan's MIC and South Korea's MSIT enforce domestic equipment certification standards that shape product development roadmaps for baseband software and radio unit integrations. Stakeholders must monitor spectrum auction schedules, open interface standardization milestones from the O-RAN Alliance, and national cybersecurity certification schemes to align investment and partnership decisions with procurement windows.
Market Dynamics
Telecom operators are dismantling proprietary hardware lock-in as Open RAN interoperability mandates from the FCC and European Commission force multi-vendor procurement frameworks into 5G network rollouts.
Growth Catalysts
- 5G Spectrum Auctions:The United States, Germany, Japan, South Korea, and India have concluded or scheduled mid-band spectrum allocations that create immediate infrastructure deployment windows for virtualized baseband solutions.
- O-RAN Alliance Standardization:Mature open interface specifications enable radio unit and baseband software interoperability testing that reduces integration risk for multi-vendor deployments.
- Containerized Network Functions:Kubernetes-orchestrated microservices architectures allow elastic capacity scaling that matches traffic demand patterns without overprovisioning proprietary hardware.
Market Restraints
- Server Silicon Concentration:x86 and ARM processor supply for commercial off-the-shelf servers concentrates among a limited foundry base, creating input cost volatility for distributed unit deployments.
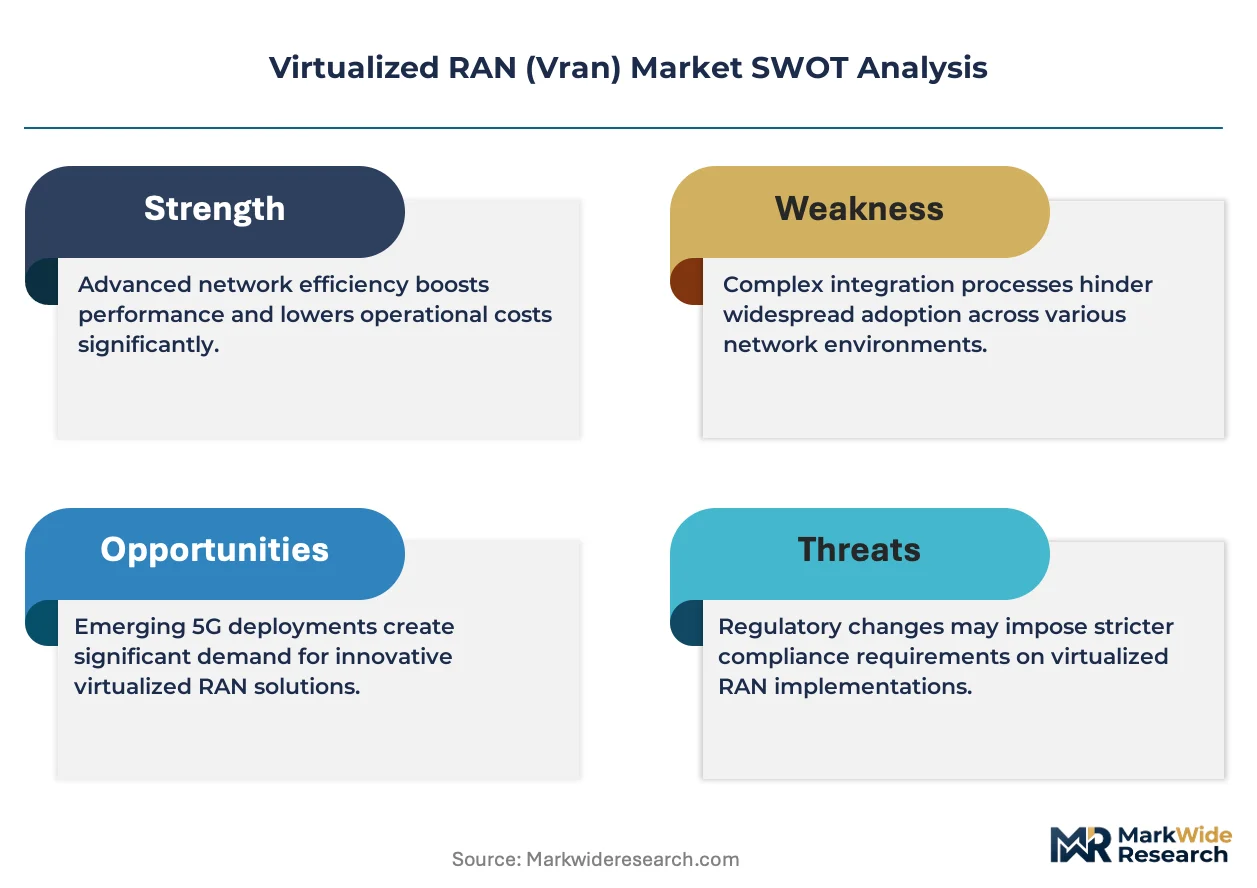
- Legacy Integration Friction:Brownfield operators face structural barriers retrofitting virtualized layers onto existing proprietary baseband hardware with closed management interfaces.
- Certification Timeline Compression:Japan's MIC and South Korea's MSIT enforce domestic equipment certification standards that extend product qualification cycles before commercial deployment authorization.
Strategic Opportunities
- Private Cloud Sovereignty:Enterprise and government buyers in Germany and India seek on-premises vRAN deployments with data residency controls that command premium service margins.
- Public Cloud Network-as-a-Service:Managed service providers are building multi-tenant vRAN instances on hyperscaler infrastructure to serve mid-market telecom operators without captive data center capacity.
- Intelligent Automation Convergence:Machine learning-driven radio resource management integrated with cloud-native orchestration platforms creates new operational expenditure reduction value propositions for carrier procurement teams.
Industry Challenges
- Container Orchestration Expertise Gap:Telecom engineering organizations lack sufficient Kubernetes and cloud-native architecture skills to operate disaggregated vRAN stacks at production scale.
- Multi-Vendor Integration Complexity:Disaggregated radio units, distributed units, and centralized units from different suppliers create fault isolation and performance optimization execution risks during live network operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtualized RAN (Vran) Market |
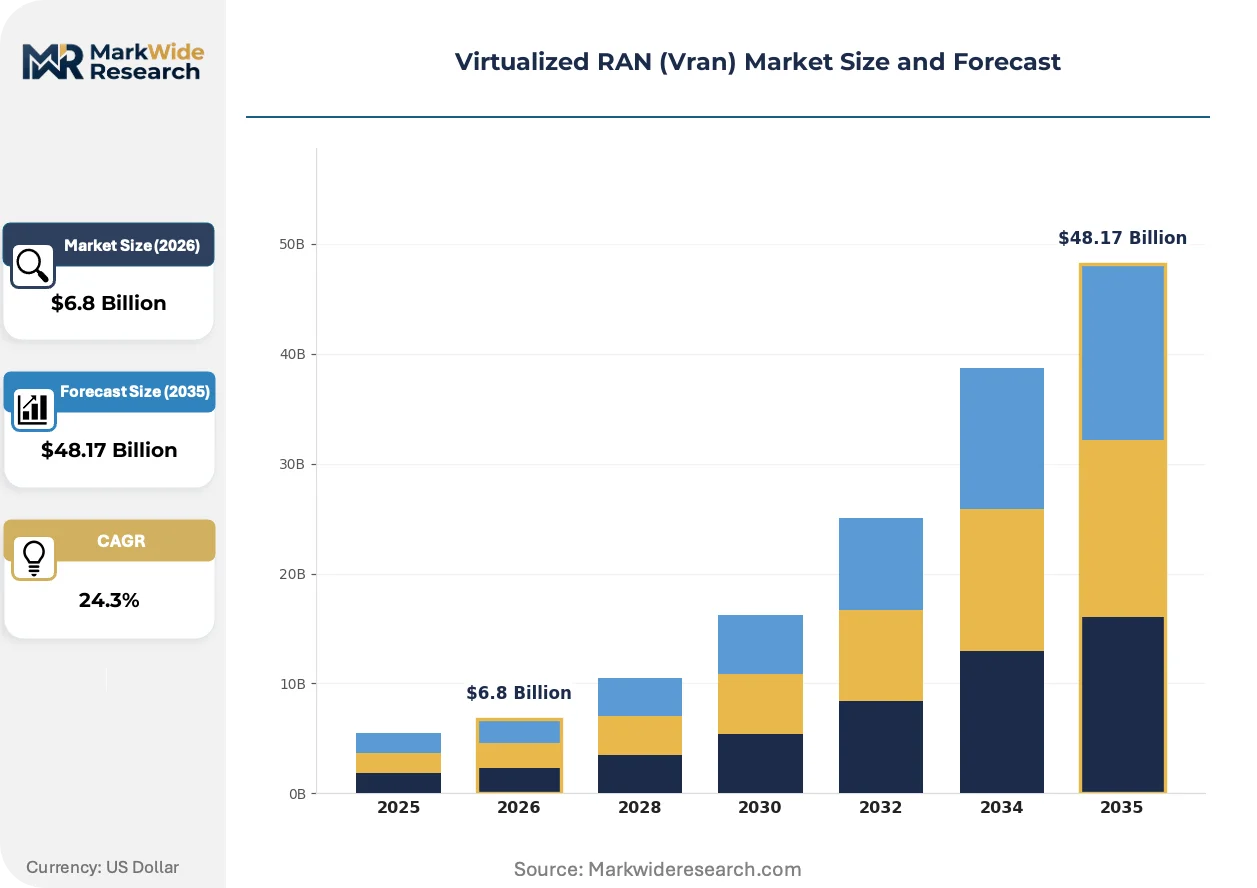
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $48.17 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-RAN, Open RAN, vEPC, Software Defined Networking Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Telecom Operators, Enterprises, Government, Managed Service Providers Application: Mobile Network, Fixed Wireless Access, Internet of Things, Emergency Services |
| Companies Covered | Nokia Corporation, Ericsson, Samsung Electronics Co., Ltd., NEC Corporation, Mavenir, Intel Corporation, Fujitsu Limited, Qualcomm Technologies, Inc., Parallel Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtualized RAN (Vran) Market Evolving Landscape
Software abstraction layers are compressing hardware differentiation as containerized network functions and open interfaces enable vendor-agnostic procurement strategies across 5G infrastructure programs.
Cloud-native baseband software is absorbing packet processing and timing synchronization functions previously executed on dedicated hardware accelerators. Tier-one operators in North American markets are deploying these disaggregated stacks in production networks. This absorption is compressing the addressable market for proprietary baseband silicon while expanding server vendor attach rates.
The European Commission's 5G cybersecurity toolbox imposes supply chain diversification requirements that reshape vendor qualification processes for network equipment procurement. Operators must document multi-source strategies and exclude high-risk suppliers from critical network functions. German and French carriers are responding by accelerating O-RAN-compliant radio unit qualification timelines.
Subscription-based software licensing is displacing perpetual hardware-centric contracts as the dominant commercial framework for vRAN procurement. Carrier finance organizations prefer operational expenditure treatment and vendor risk sharing through recurring service agreements. This shift is most visible in United States operator requests for proposal that specify multi-year software subscription minimums with automatic renewal clauses.
Virtualized RAN (Vran) Market Segmentation
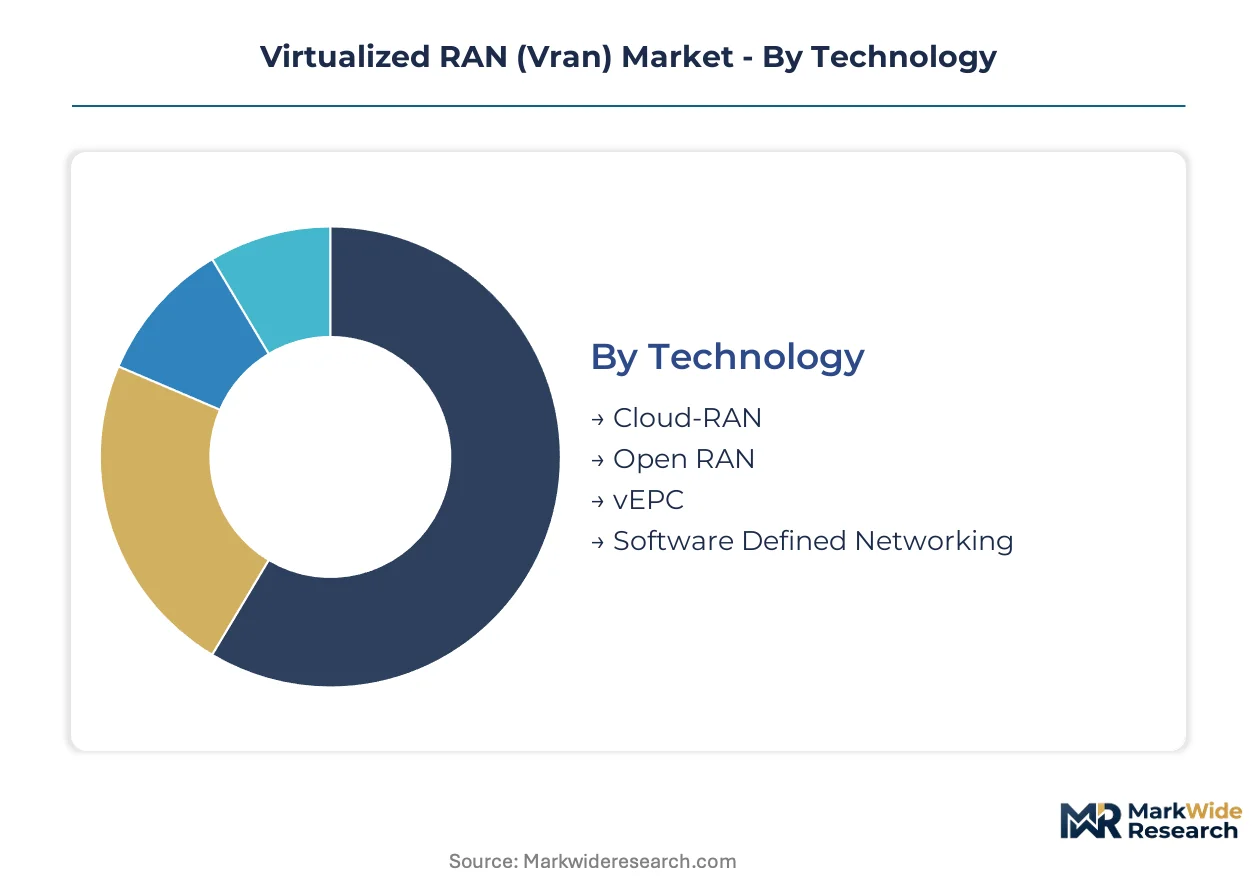
vRAN procurement patterns diverge sharply across deployment architectures and buyer types, with technology choices determining interoperability scope and operational expenditure profiles for carrier infrastructure teams.
Technology:
Supply concentration in baseband software stacks creates vendor lock-in risks that open interface specifications aim to dismantle.
- Cloud-RAN:Centralized baseband processing architectures pool computational resources across multiple cell sites, reducing hardware redundancy. United States operators deploy these configurations in dense urban markets where fiber backhaul supports latency requirements. The architecture compresses capital expenditure through shared server pools but demands robust transport network investments.
- Open RAN:Disaggregated radio units and distributed units interoperate through O-RAN Alliance standardized interfaces, enabling multi-vendor procurement. Germany and Japan accelerate qualification programs for compliant equipment as regulatory pressure intensifies. Supply chain diversification mandates from the European Commission reshape vendor selection criteria.
- vEPC:Virtualized evolved packet core functions handle subscriber management and data routing on commercial servers. Mobile network operators in South Korea integrate these elements with 5G standalone core deployments. The segment benefits from container orchestration maturity in carrier data centers.
- Software Defined Networking:Programmable control planes separate network intelligence from forwarding hardware, enabling traffic engineering automation. Managed service providers leverage these capabilities for multi-tenant network-as-a-service offerings.
Cloud-RAN absorbs the bulk of installed capacity; Open RAN is expanding most quickly.
Deployment Model:
Cost tier differentiation separates premium sovereignty-compliant deployments from volume-driven hyperscaler instances.
- Private Cloud:On-premises server deployments with dedicated infrastructure satisfy data residency requirements for sensitive workloads. Government buyers in India and Germany specify these models for critical communications networks. Premium service margins reflect compliance certification overhead and localized support obligations.
- Public Cloud:Hyperscaler-hosted vRAN instances enable rapid scaling without captive data center investments. Mid-market telecom operators in the United States adopt these configurations through managed service provider intermediaries. Operational expenditure treatment appeals to finance organizations seeking balance sheet flexibility.
- Hybrid Cloud:Split workloads across private control planes and public compute bursts accommodate traffic volatility. Enterprises with fluctuating connectivity demands favor this architecture for campus network extensions.
- On-Premises:Traditional server deployments in operator-owned facilities persist where regulatory frameworks restrict external data processing. Japan's MIC certification requirements reinforce this model for certain network functions.
Private Cloud commands premium margins; Public Cloud instances gain share fastest among new deployments.
End User:
Customer type determines procurement sophistication and contract structure preferences across the buyer base.
- Telecom Operators:Tier-one carriers with extensive radio access networks drive volume demand and shape vendor roadmaps through multi-year framework agreements. Brownfield modernization programs in Germany and the United States prioritize backward compatibility with existing infrastructure.
- Enterprises:Manufacturing campuses, logistics hubs, and mining operations deploy private 5G networks with localized vRAN stacks. India and South Korea witness accelerating industrial digitization projects requiring dedicated spectrum allocations.
- Government:Defense and public safety agencies mandate domestic equipment certification and supply chain provenance controls. Procurement timelines extend to accommodate security vetting processes.
- Managed Service Providers:Intermediaries aggregate demand from smaller operators lacking internal engineering capacity, standardizing multi-tenant vRAN operations on cloud-native platforms.
Telecom Operators absorb the bulk of installed capacity; Enterprises represent the steepest expansion trajectory.
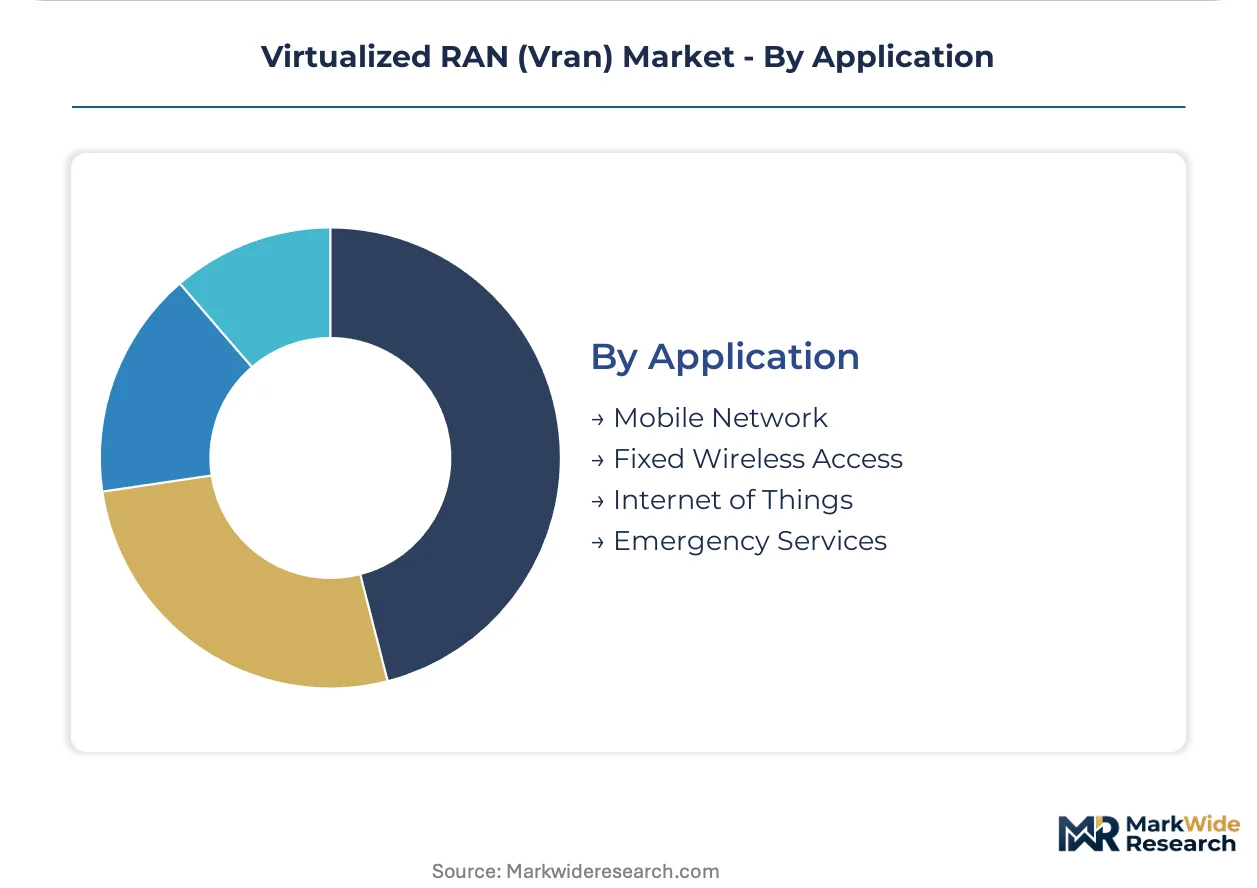
Application:
Maturity gradients separate established mobile broadband from emerging fixed wireless and IoT connectivity patterns.
- Mobile Network:Enhanced mobile broadband remains the primary revenue foundation for vRAN deployments, with 5G mid-band densification driving radio unit and baseband software demand. Spectrum auctions in India and the United States created immediate deployment windows.
- Fixed Wireless Access:Wireless last-mile connectivity substitutes for fiber in suburban and rural markets, with vRAN elasticity matching subscriber growth without stranded infrastructure. United States operators expand these offerings aggressively.
- Internet of Things:Massive machine-type communications require optimized signaling overhead and power efficiency in vRAN protocol stacks. Smart city deployments in South Korea and Japan pilot these configurations.
- Emergency Services:Mission-critical push-to-talk and public safety broadband demand hardened infrastructure with guaranteed availability. Government buyers specify dedicated network slices with priority preemption capabilities.
Mobile Network applications dominate current capacity; Fixed Wireless Access climbs fastest as fiber alternatives proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of vRAN software stacks concentrates in Finland, Sweden, and South Korea, while consumption spreads across telecom operators in the United States, Germany, and Japan executing 5G densification programs.
United States
Mid-band spectrum auctions by the FCC created immediate deployment windows for cloud-native baseband solutions. The regulator's Open RAN interoperability mandates force multi-vendor procurement frameworks into carrier RFPs. Dense urban clusters in New York, Los Angeles, and Chicago anchor brownfield modernization programs where fiber backhaul supports centralized processing architectures.
Germany
Deutsche Telekom and Vodafone Deutschland drive demand for private cloud vRAN deployments with data sovereignty controls. The European Commission's 5G cybersecurity toolbox imposes supply chain diversification requirements that reshape vendor qualification. Industrial corridors in Bavaria and North Rhine-Westphalia host private 5G campus networks for automotive and manufacturing digitization.
Japan
NTT Docomo and KDDI accelerate Open RAN qualification timelines to meet 5G standalone core deployment targets. The Ministry of Internal Affairs and Communications enforces domestic equipment certification standards that extend product validation cycles. Tokyo-Osaka-Nagoya metro corridors concentrate radio unit integration testing for O-RAN Alliance compliant gear.
South Korea
SK Telecom and KT Corporation integrate vEPC functions with 5G standalone core rollouts following MSIT spectrum allocations. The Ministry of Science and ICT enforces domestic equipment certification that shapes baseband software roadmaps. Seoul Capital Area and Busan-Ulsan industrial zones pilot massive machine-type communications for smart city deployments.
India
Reliance Jio and Bharti Airtel execute national broadband strategies requiring elastic capacity scaling for subscriber growth. The Department of Telecommunications advances spectrum auction schedules that create infrastructure deployment windows. Maharashtra and Karnataka host emerging private 5G networks for manufacturing campuses and logistics hubs.
Virtualized RAN (Vran) Market Competitive Landscape
Top-tier vendors anchor large-scale framework agreements with tier-one carriers, while specialist software firms and silicon suppliers occupy adjacent layers. The vendor base stratifies across three tiers: integrated equipment manufacturers with end-to-end portfolios, cloud-native software specialists, and semiconductor suppliers providing server processors and acceleration hardware. Dominant competitive moves include strategic partnerships between radio unit suppliers and baseband software vendors, plus portfolio diversification into intelligent automation features that reduce carrier opex.
Within the integrated equipment tier, Nokia Corporation and Ericsson exemplify vendors leveraging end-to-end portfolios to anchor brownfield modernization programs. Samsung Electronics Co., Ltd. occupies a position representing cloud-native baseband specialists targeting North American deployment velocity. These three firms exemplify distinct archetypes: the European brownfield integrator, the Nordic automation-focused vendor, and the Korean greenfield cloud-native supplier.
| Leading Market Players |
|---|
| Nokia Corporation |
| Ericsson |
| Samsung Electronics Co., Ltd. |
| NEC Corporation |
| Mavenir |
| Intel Corporation |
| Fujitsu Limited |
| Qualcomm Technologies, Inc. |
| Parallel Wireless |
| Others |
Value Network & Pricing Analysis
Containerized network function migration simultaneously compresses proprietary hardware premiums and redistributes value capture toward software orchestration layers and commercial server silicon. This shift concentrates procurement leverage among hyperscale server vendors while fragmenting radio unit supply across O-RAN Alliance qualified suppliers.
Pricing Analysis
Margin tightening in private cloud deployments reflects certification overhead for data sovereignty compliance in Germany and India. Three-tier pricing structure across premium, standard, and economy levels separates government-grade certified stacks from enterprise campus configurations and managed service provider volume tiers. Pricing pressure stems from ARM-based server commoditization challenging x86 incumbents. Mid-market telecom operators exhibit highest price sensitivity due to balance sheet constraints, while government buyers accept premium positioning for security vetting inclusion.
Supply Chain Analysis
x86 and ARM processor supply rests on Taiwanese foundry capacity and South Korean memory fabrication, with Intel and Qualcomm anchoring baseband acceleration silicon. Radio unit manufacturing concentrates in South Korea, Japan, and Finland, while commercial off-the-shelf server assembly localizes in Mexico and Vietnam for North American demand. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through direct carrier procurement for tier-one operators and managed service provider intermediaries for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Server silicon fabrication capacity constraints prop software-defined pricing premiums, as foundry allocation scarcity limits distributed unit deployment velocity. This supply bottleneck sustains vendor pricing power in qualified baseband software stacks.
For Market Incumbents: Anchor brownfield modernization programs through backward integration into legacy interface adaptation layers, defending against cloud-native specialists targeting greenfield velocity. Prioritize R&D investment in Kubernetes-orchestrated automation features that reduce carrier operational expenditure and deepen switching costs. Fortify certification relationships with Japan's MIC and South Korea's MSIT to extend qualification timeline advantages over emerging entrants. For New Entrants and Emerging Players: FCC Open RAN interoperability mandates in the United States open a window for radio unit specialists to penetrate tier-two carrier procurement frameworks previously locked by integrated vendors. Target private 5G campus networks in Indian manufacturing corridors and German automotive zones where brownfield legacy constraints are weakest. Pursue strategic partnerships with hyperscale cloud providers to bypass captive data center capacity requirements among mid-market operators. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated equipment manufacturers seeking cloud-native software capabilities. Long-term viability favors baseband software specialists with O-RAN Alliance protocol certification and container orchestration IP. Acquisition target archetype: mid-scale vendors with proven interoperability testing records and existing framework agreements with European or Asia-Pacific carriers. Watch O-RAN Alliance security specification finalization as inflection indicator for procurement mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| O-RAN Alliance Certification Investment | Qualification for FCC and European Commission interoperability mandates accelerates carrier procurement access. |
| Container Orchestration Platform Integration | Kubernetes-native baseband deployment reduces carrier operational expenditure and deepens vendor stickiness. |
| Hyperscaler Cloud Partnership | Public cloud vRAN instances unlock mid-market operator segments lacking captive infrastructure. |
| Private 5G Campus Network Specialization | Industrial digitization projects in Germany and India command premium sovereignty-compliant margins. |
| Intelligent Automation Feature Development | Machine learning-driven radio resource management differentiates vendor proposals in tier-one carrier RFPs. |
Research Methodology
Independent corroboration across network engineering executives at tier-one carriers, procurement leads at managed service providers, and cloud infrastructure architects at hyperscalers underwrites the qualitative findings. Primary fieldwork with baseband software vendors and radio unit suppliers combined with secondary validation through FCC spectrum auction records, O-RAN Alliance specification documents, and national regulatory filings from Japan's MIC and South Korea's MSIT. Bottom-up deployment forecasts triangulated against top-down capital expenditure disclosures from Deutsche Telekom, NTT Docomo, and Reliance Jio.
Historical reference periods spanning completed 5G spectrum auctions and operational vRAN deployments anchored the projection framework. Segmentation modeling incorporated technology architecture, deployment model sovereignty requirements, end-user procurement sophistication, and application maturity gradients. CAGRs derived from elasticity-adjusted capacity scaling assumptions and carrier-reported operational expenditure trajectories. Industry-specific inputs included O-RAN Alliance interoperability testing milestones and domestic equipment certification timeline data.
The model assumes a particular technology adoption path; alternative pathways for Open RAN protocol maturation would alter the outlook if security specification delays extend qualification cycles. Forecasts reflect documented assumptions regarding carrier cloud-native skill acquisition rates and hyperscaler infrastructure availability. Spectrum auction schedule slippage, foundry capacity allocation shocks, and cybersecurity certification requirement changes constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
International Wholesale Voice Carrier Market
Telecommunications
Telecom API Platform Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Finland Telecom Market
Telecommunications
5G Connections Market
Telecommunications
Dialer Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Belgium ICT Market
Telecommunications
Angola Telecom Market
Telecommunications
Promotional Sms Market
Telecommunications
Telecommunication Service Market
Telecommunications
Iran Telecom Market
Telecommunications
Optical Fronthaul Market
Telecommunications
Singapore Telecom Market