
 Fixed Voice Market | 2026-2036
Fixed Voice Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed Voice Market Intelligence
Software-defined voice features is expanding the attach rate for programmable APIs alongside traditional dial-tone subscriptions. Bandwidth leverages its nationwide IP network to anchor wholesale carrier relationships with regional telecom operators. Twilio competes through developer-centric platforms that embed voice into enterprise workflows. Vonage differentiates via unified communications bundles that extend fixed voice into video and messaging suites.
Fixed voice encompasses circuit-switched and packet-based telephony services delivered over copper, fiber, or coaxial infrastructure to stationary endpoints, operating at frequencies below 4 kHz for analog lines or utilizing G.711/G.729 codecs for digital compression. Its primary purpose remains reliable person-to-person and automated interactive voice response communication for residential and commercial premises. VoIP services capture the fastest expansion as analog line disconnections accelerate across North American and European incumbent networks. IP-based technology leads deployment preference among large enterprises seeking convergence with existing data infrastructure. Cloud-based deployment models concentrate margin pools through recurring platform fees rather than per-minute transit charges.
The FCC enforces number portability and rural service mandates that preserve fixed voice access obligations even as mobile substitution rises. EMEA regulators including BNetzA in Germany and ARCEP in France impose copper switch-off timelines that force migration toward IP-based alternatives. Stakeholders must monitor interconnection rate disputes and emergency calling compliance requirements as network architectures diverge from legacy time-division multiplexing toward all-IP cores.
Market Dynamics
The migration from time-division multiplexing to all-IP cores is compressing legacy infrastructure economics while forcing wholesale renegotiation of interconnection agreements across incumbent networks.
Growth Catalysts
- Cloud Contact Center Expansion:Enterprise migration to hosted customer engagement platforms sustains Session Initiation Protocol trunking demand as premises-based systems reach end-of-life.
- Copper Retirement Mandates:BNetzA in Germany and ARCEP in France impose legally binding switch-off timelines that compel residential and business subscribers toward fiber and VoIP alternatives.
- API Programmability:Software-defined voice features enable embedded communications within enterprise SaaS workflows, expanding attach rates beyond traditional dial-tone subscriptions.
Market Restraints
- Legacy Interconnection Rate Disputes:Incumbent carriers in the United States and Germany contest IP-to-TDM termination pricing, creating margin pressure on wholesale voice providers.
- Copper Network Stranded Assets:Incumbent local exchange carriers face accelerated depreciation obligations as physical loop infrastructure loses economic utility before accounting write-down completion.
- Mobile Substitution Acceleration:Fixed-mobile convergence bundles and unlimited wireless plans displace standalone fixed voice subscriptions among price-sensitive residential segments.
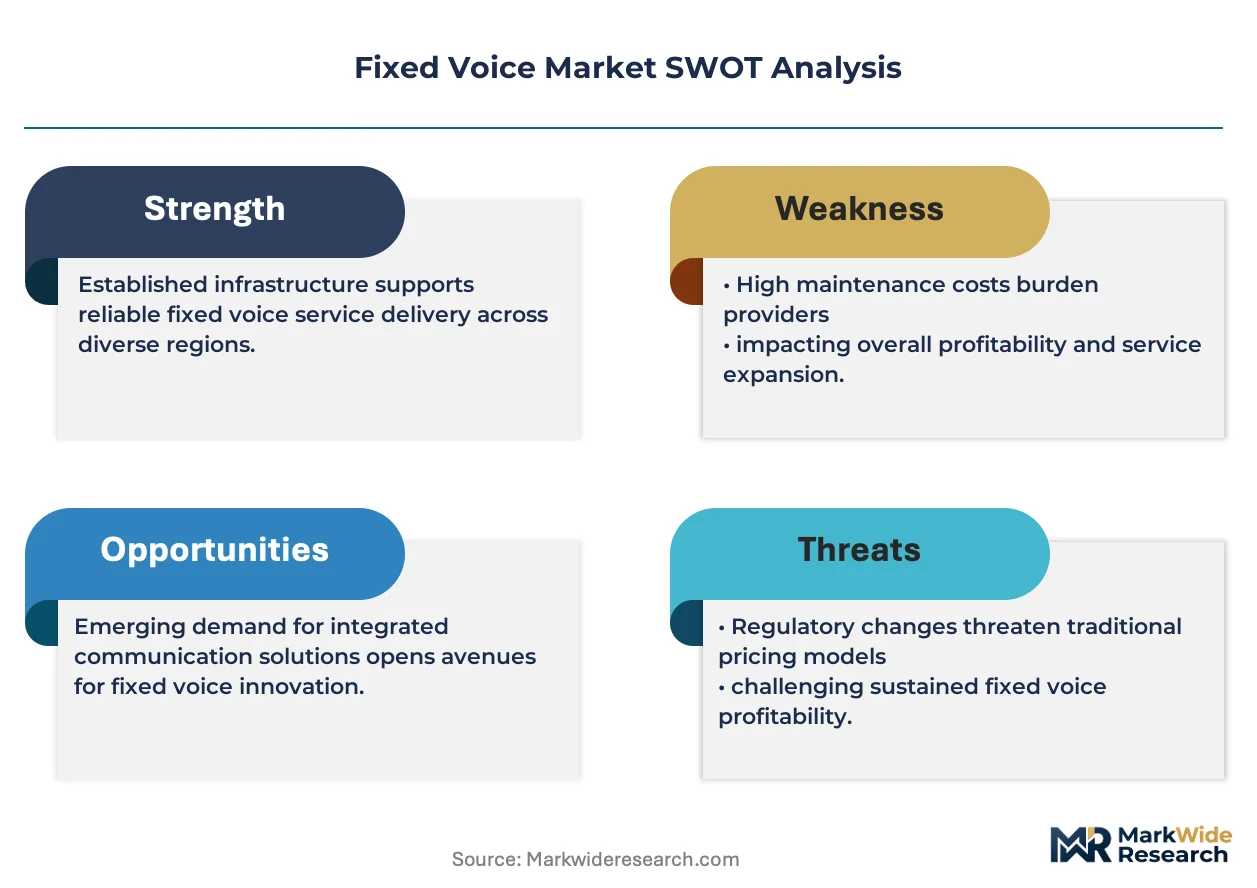
Strategic Opportunities
- Rural Broadband Universal Service:FCC Connect America Fund and comparable rural development programs in Brazil and India subsidize voice-capable infrastructure deployment in underserved areas.
- Unified Communications Convergence:Integration of fixed voice with video conferencing and team messaging suites creates stickier enterprise relationships and higher per-seat recurring revenue.
- Emergency Services IP Transition:Next-generation 911 mandates in the United States and comparable frameworks in Japan require location-accurate VoIP infrastructure investment.
Industry Challenges
- Legacy System Integration Complexity:Enterprises maintaining hybrid TDM-IP environments face interoperability failures between proprietary private branch exchange equipment and cloud-native platforms.
- E911 Location Accuracy Compliance:VoIP providers must validate dispatchable address data for nomadic endpoints, creating operational overhead as regulatory deadlines tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed Voice Market |
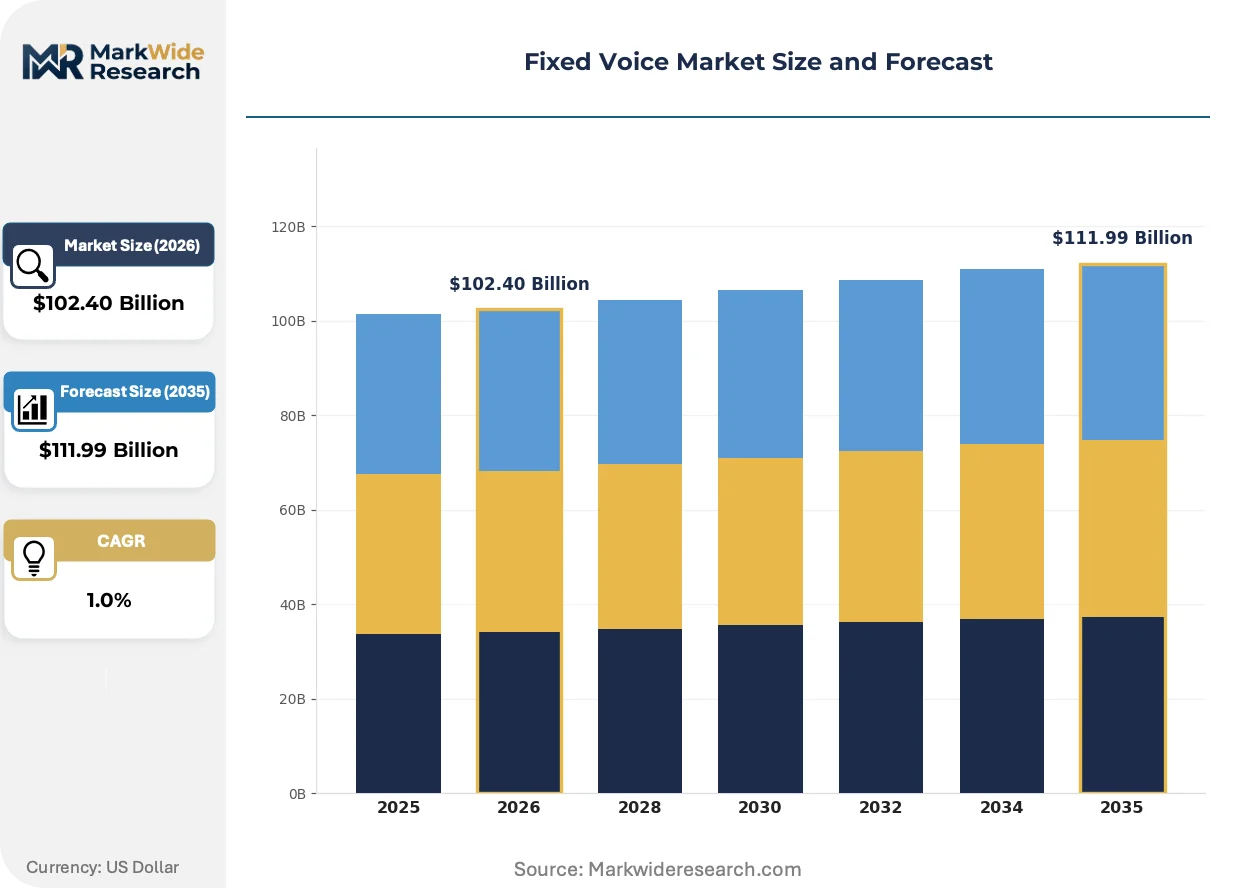
| Market Size in 2026 | $102.40 Billion |
| Market Size in 2035 | $111.99 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Local Line, VoIP, Private Branch Exchange, Integrated Services Digital Network Technology: Analog, Digital, ISDN, IP-based End User: Residential, Small Business, Large Enterprise, Government Deployment: On-premises, Cloud-based, Hybrid, Managed Services |
| Companies Covered | Sangoma Carrier Services, RingCentral, Viirtue, Twilio, Ooma, Telnyx, Nextiva, Vonage, Bandwidth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed Voice Market Strategic Shifts & Innovations
Artificial intelligence and programmable network APIs are transforming fixed voice from a commodity transport service into a configurable platform layer embedded within enterprise software stacks.
WebRTC-based browser telephony is automating the deployment of voice capabilities without dedicated endpoint hardware or client software installation. Mid-market enterprises and software vendors adopt this stack to embed click-to-call functions directly into customer relationship management interfaces. The technology is automating the elimination of traditional private branch exchange capital expenditure cycles.
The FCC's STIR/SHAKEN caller ID authentication mandate is reshaping intercarrier signaling requirements across the United States. Originating service providers must cryptographically sign call metadata, imposing certificate infrastructure costs while reducing robocall volumes that erode subscriber trust. Tier-1 carriers have deployed compliant networks; regional competitive local exchange carriers face compressed implementation timelines.
Enterprise buyers increasingly unbundle voice services from traditional managed network contracts. Procurement teams negotiate standalone software-defined wide area network connectivity, then source voice as a separate cloud platform subscription. This pattern concentrates most visibly among technology and financial services verticals in the United States and United Kingdom, where internal IT organizations possess sufficient integration capability to manage multi-vendor stacks.
Fixed Voice Market Segmentation
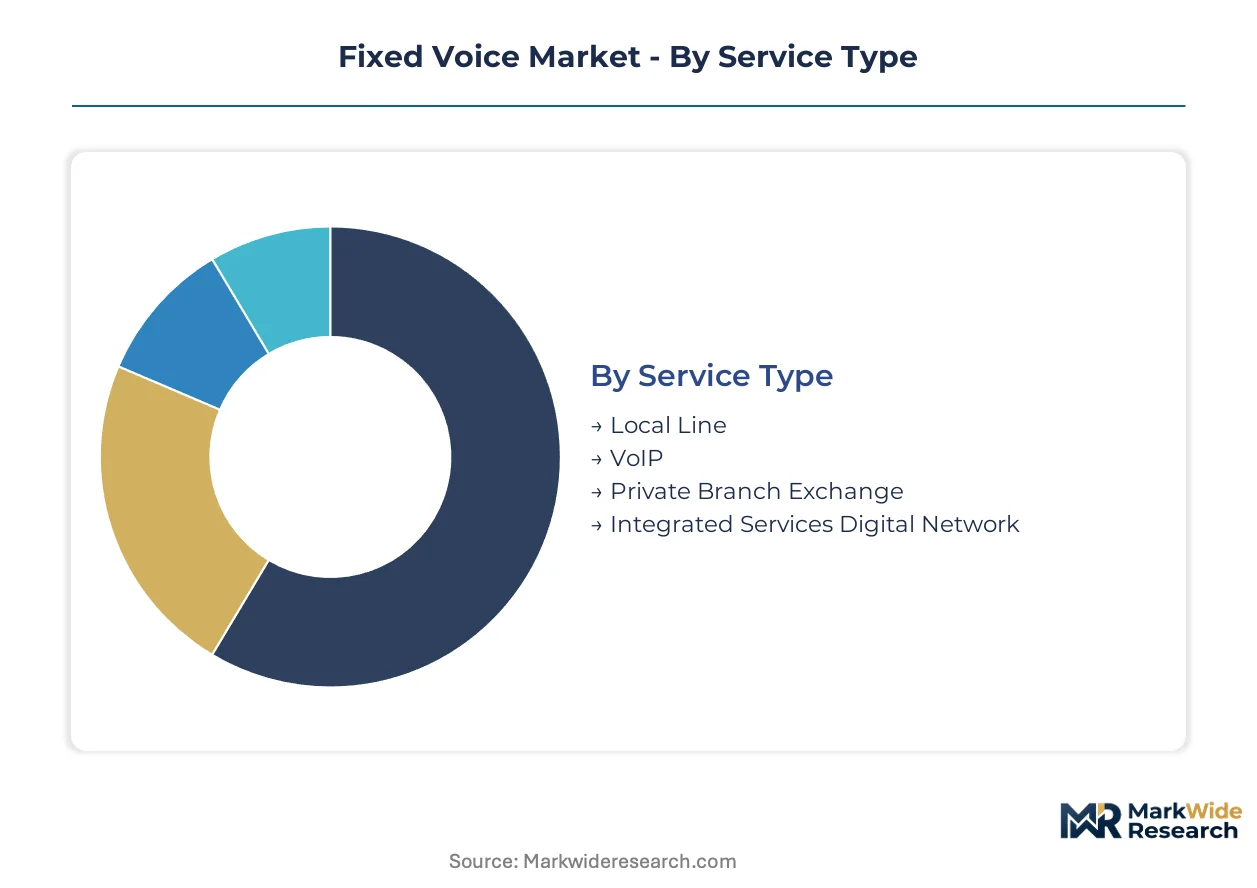
Fixed voice segmentation reveals how capital deployment and operational complexity vary sharply across service architectures. Infrastructure ownership models and regulatory obligations differ fundamentally between legacy circuit-switched and emerging packet-based alternatives.
Service Type:
Capital intensity peaks with physical infrastructure obligations, while software-defined alternatives shift spending toward recurring platform fees rather than depreciable assets.
- Local Line:Copper loop infrastructure requires trenching, pole attachment rights, and central office switching equipment with 20-30 year depreciation schedules. Residential subscribers in Germany and France face forced migration as BNetzA and ARCEP mandates accelerate copper retirement timelines.
- VoIP:Session Initiation Protocol trunking eliminates dedicated physical loops, converting voice into compressed data packets traversing existing IP networks. Enterprise contact centers in the United States sustain demand as cloud migration accelerates and premises-based systems reach end-of-life.
- Private Branch Exchange:On-premises switching hardware demands upfront capital expenditure for chassis, line cards, and maintenance contracts.
- Integrated Services Digital Network:Legacy digital bearer channels face accelerating disconnection as carriers prioritize fiber and IP core investments.
Local Line absorbs the bulk of installed capacity; VoIP is expanding most quickly.
Technology:
Technology choice determines interoperability requirements and the pace at which carriers can decommission stranded legacy assets.
- Analog:Pulse-code modulation at 64 kbps per channel occupies excessive bandwidth relative to modern compression codecs. Rural broadband subsidies in the United States preserve limited analog deployments where fiber economics fail.
- Digital:Time-division multiplexing infrastructure concentrates in incumbent carrier central offices facing accelerated depreciation as traffic migrates to packet cores.
- ISDN:Basic Rate Interface and Primary Rate Interface circuits sustain legacy point-of-sale and alarm monitoring connections.
- IP-based:G.711 and G.729 codecs enable bandwidth-efficient voice transport converged with enterprise data infrastructure.
IP-based platforms capture the steepest expansion trajectory; Analog retains residual presence only where regulatory universal service obligations mandate preservation.
End User:
Customer scale dictates pricing power, integration complexity, and the viability of bundled versus standalone service offerings.
- Residential:Price-sensitive subscribers increasingly select fixed-mobile convergence bundles that displace standalone voice lines. Unlimited wireless plans from national carriers accelerate substitution trends across North American and European markets.
- Small Business:Limited IT staff drive preference for managed services and cloud-based deployment to avoid capital expenditure and maintenance burden.
- Large Enterprise:Procurement teams unbundle voice from network contracts, sourcing standalone cloud platform subscriptions alongside software-defined wide area network connectivity. Technology and financial services verticals in the United States and United Kingdom lead this pattern.
- Government:Emergency calling compliance and security classifications impose specialized requirements distinct from commercial deployments.
Large Enterprise generates the highest per-seat recurring revenue; Residential is contracting fastest under mobile substitution pressure.
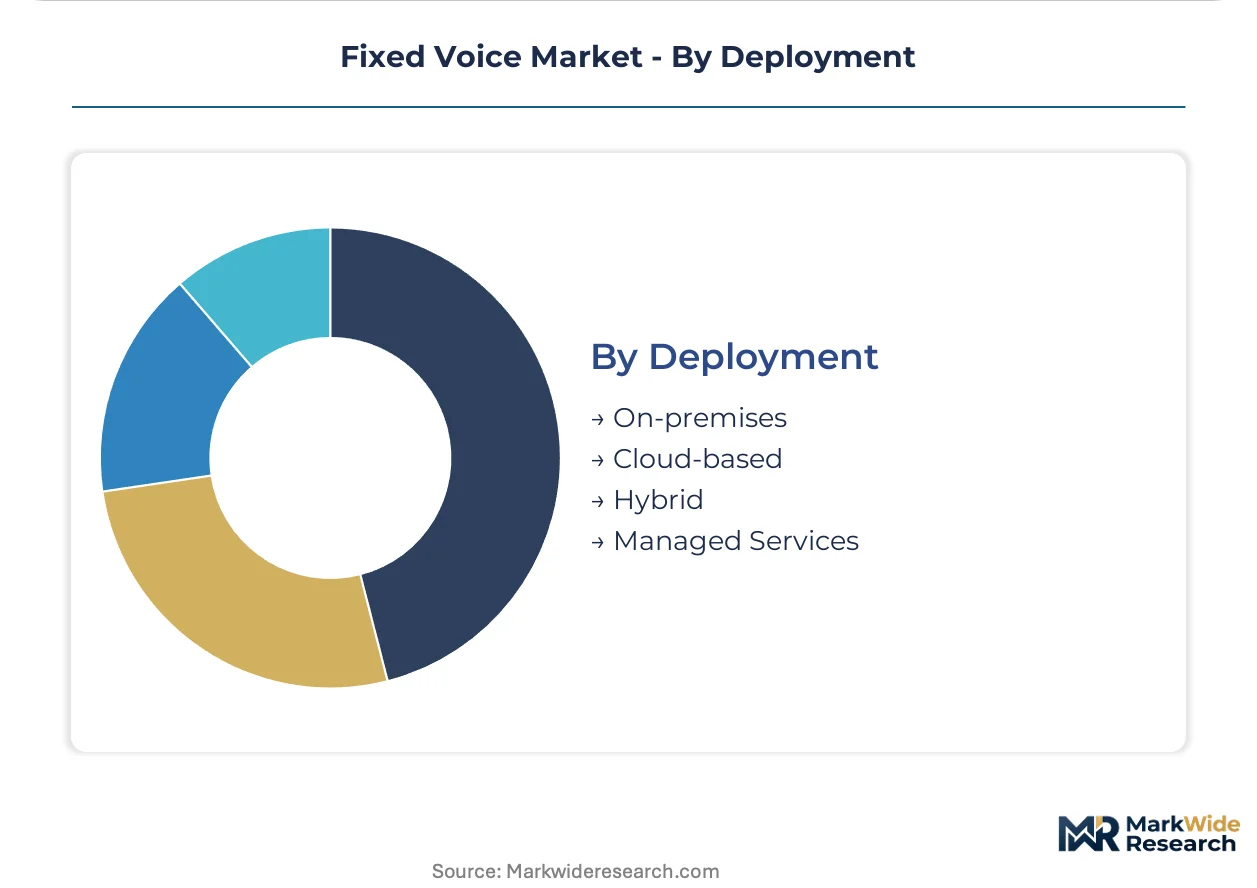
Deployment:
Deployment model selection reflects internal IT capability, regulatory data sovereignty requirements, and appetite for operational risk transfer.
- On-premises:Organizations with legacy private branch exchange investments and strict data localization mandates retain physical infrastructure control.
- Cloud-based:WebRTC-based browser telephony eliminates endpoint hardware, embedding click-to-call functions directly into customer relationship management interfaces.
- Hybrid:Enterprises maintaining mixed TDM-IP environments face interoperability failures between proprietary equipment and cloud-native platforms.
- Managed Services:Outsourced operational responsibility appeals to mid-market organizations lacking specialized voice engineering expertise.
On-premises retains substantial installed base; Cloud-based is climbing the fastest as WebRTC and API programmability reduce deployment friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European carrier interconnection activity, where Deutsche Telekom operates one of the continent's densest IP exchange points. The metropolitan cluster concentrates Session Initiation Protocol trunking demand from financial services and logistics headquarters.
United States
Enterprise contact centers in Chicago and Dallas sustain wholesale SIP trunking volumes as cloud migration accelerates. The FCC enforces STIR/SHAKEN caller ID authentication mandates that impose certificate infrastructure costs on originating service providers. Atlanta hosts dense competitive local exchange carrier interconnection facilities where regional operators negotiate IP-to-TDM termination pricing.
Germany
BNetzA mandates legally binding copper switch-off timelines that compel residential and business subscribers toward fiber and VoIP alternatives. The regulator's 2024 framework accelerates legacy infrastructure depreciation obligations for incumbent local exchange carriers. Munich and Hamburg concentrate mid-market enterprise demand for unified communications bundles that extend fixed voice into video suites.
Japan
METI frameworks guide next-generation 911-equivalent mandates requiring location-accurate VoIP infrastructure investment. Tokyo and Osaka enterprise corridors drive demand for programmable APIs that embed voice into SaaS workflows. NTT's regional operating companies face wholesale renegotiation of interconnection agreements as traffic migrates to all-IP cores.
Brazil
Anatel's rural broadband universal service programs subsidize voice-capable infrastructure deployment in underserved northern and northeastern states. São Paulo anchors enterprise SIP trunking demand from financial services and manufacturing headquarters. The country's central bank regulates payment system integrations that increasingly converge with cloud contact center platforms.
United Kingdom
Ofcom's copper retirement consultations align with Openreach's 2025 PSTN switch-off deadline that forces migration toward IP-based alternatives. London's technology and financial services verticals lead procurement patterns that unbundle voice from managed network contracts. Manchester and Birmingham concentrate mid-market demand for WebRTC-based browser telephony eliminating endpoint hardware requirements.
Fixed Voice Market Key Industry Players
Capital-heavy network owners compete with asset-light platform developers for enterprise voice relationships. The market structures around three tiers: incumbent carriers with physical infrastructure obligations, wholesale platform providers leveraging nationwide IP networks, and developer-centric API vendors embedding communications into software workflows. Strategic moves concentrate on cloud contact center partnerships and programmable voice feature expansion rather than capacity-driven infrastructure builds.
Within the wholesale carrier tier, Bandwidth and Telnyx exemplify platform models that anchor relationships with regional telecom operators through API programmability. Vonage occupies a position in unified communications convergence, representing the bundle strategy that extends fixed voice into video and messaging suites. These three companies illustrate how margin pools shift from per-minute transit charges toward recurring platform fees as deployment models migrate cloudward.
| Leading Market Players |
|---|
| Sangoma Carrier Services |
| RingCentral |
| Viirtue |
| Twilio |
| Ooma |
| Telnyx |
| Nextiva |
| Vonage |
| Bandwidth |
| Others |
Cost & Logistics Intelligence
Large enterprise procurement teams in the United States and United Kingdom anchor pricing power through unbundled sourcing of standalone cloud voice platforms alongside software-defined wide area network connectivity. Their technical integration capabilities compress margins for bundled managed service providers while elevating API-centric platform vendors.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and call-completion rates dominates enterprise SIP trunking contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates by service-level agreement stringency and geographic redundancy. Pricing pressure stems from mobile substitution accelerating residential segment attrition. Residential subscribers exhibit highest price sensitivity; government and financial services verticals demonstrate lowest.
Supply Chain Analysis
Direct-to-enterprise channels handle large buyer demand for cloud-native deployments while wholesale carrier relationships feed regional operator requirements. Manufacturing concentrates in China for endpoint hardware, Taiwan for semiconductor components, and the United States for software platform development. Supply chain risk centers on single-source vulnerability for specialized voice codecs and session border controller chipsets. Distribution runs through tier-1 carriers, competitive local exchange carriers, and cloud platform marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Legacy copper infrastructure decommissioning timelines create supply-constrained conditions that prop pricing for IP-based alternatives. BNetzA and ARCEP mandates compress migration windows, preserving margin pools for fiber and VoIP providers.
For Market Incumbents: Cement wholesale interconnection relationships through API programmability investments before copper retirement accelerates. Defend margin position by consolidating stranded central office real estate and accelerating depreciation schedules. Vertical integration into cloud contact center platforms offsets premises-based system decline.
For New Entrants and Emerging Players: Begin with mid-market enterprises in Germany and Brazil where legacy system end-of-life creates immediate replacement demand. Target WebRTC-based browser telephony deployments that eliminate endpoint hardware procurement friction. Lead with CRM-embedded click-to-call functionality as primary go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional competitive local exchange carriers with dense interconnection facilities in Atlanta and São Paulo. Long-term viability hinges on successful IP core migration and cloud platform attach rate expansion. Watch STIR/SHAKEN compliance cost burdens as inflection indicator for regional carrier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| API Platform Expansion | Twilio and Bandwidth embed voice into Salesforce and ServiceNow workflows. |
| Copper Retirement Acceleration | Deutsche Telekom and Openreach compress PSTN switch-off timelines per regulator mandates. |
| Cloud Contact Center Partnership | Vonage and RingCentral bundle voice with Genesys and Amazon Connect integrations. |
| E911 Infrastructure Investment | Bandwidth and Telnyx deploy dispatchable location databases for FCC compliance. |
| Wholesale Interconnection Consolidation | Regional competitive local exchange carriers merge to negotiate IP-to-TDM termination rates. |
Research Approach
FCC filings, carrier interconnection databases, and regulatory docket records formed the secondary backbone for this analysis. Primary interviews with wholesale voice platform executives, enterprise IT procurement officers, and competitive local exchange carrier engineering directors validated secondary findings. Bottom-up and top-down triangulation reconciled service provider capacity disclosures with enterprise adoption surveys.
Bottom-up modeling aggregated individual country-level SIP trunking deployments and copper disconnection schedules. Top-down validation cross-checked aggregate figures against carrier revenue disclosures and universal service fund distributions. Segmentation dimensions included service architecture, deployment model, end-user scale, and regional regulatory cluster. CAGRs derived from fitted trend lines across historical copper retirement velocity and VoIP substitution rates.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than hybrid TDM-IP environments due to clearer platform reporting. Forecasts reflect assumptions about copper switch-off adherence and mobile substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Argentina Telecom Market
Telecommunications
Iran Telecom Market
Telecommunications
Explosion Proof Mobile Communication Devices Market
Telecommunications
GPON Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
DWDM System Market
Telecommunications
Iceland Telecom Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
Global GPON Technology Market
Telecommunications
Mexico Telecom Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Germany ICT Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Brazil Telecom Market