
 Norway Telecom Market | 2026-2036
Norway Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Telecom Market Insights
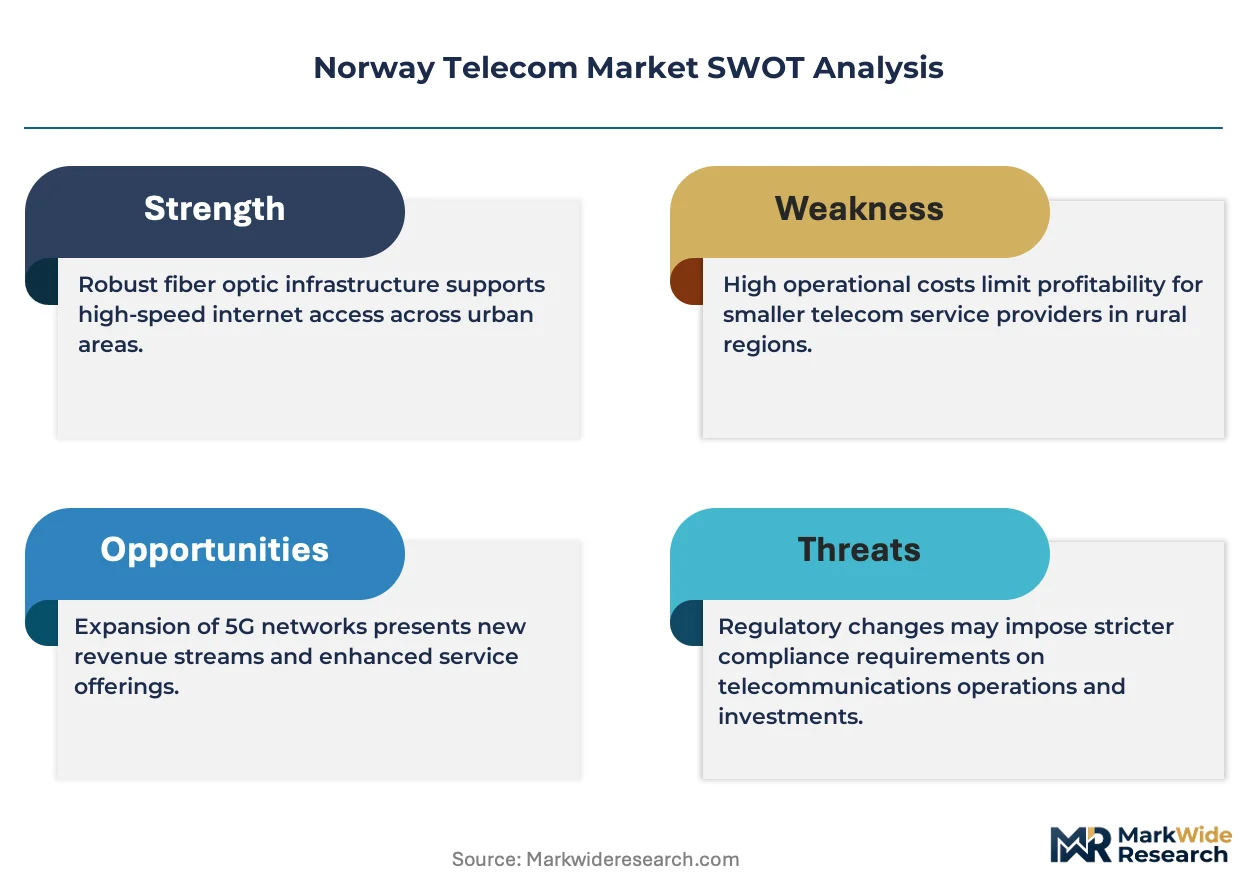
Network-as-a-service leasing and infrastructure-sharing agreements are reshaping capital deployment across Norway's telecom sector. Telenor leverages its nationwide fiber backbone to sustain wholesale dominance in rural trunk routes. Ice Communication competes through aggressive 5G spectrum positioning in underserved western counties. Telia Company anchors enterprise connectivity contracts across Nordic cross-border corridors.
Norway telecom encompasses terrestrial and wireless communication infrastructure delivering voice, data, and video transmission through copper, fiber, radio, and satellite media with throughput specifications ranging from gigabit passive optical networks to sub-6 GHz 5G New Radio. The sector serves industrial automation, public safety, consumer broadband, and maritime connectivity requirements across fjord-indented terrain. Mobile services generate the largest revenue pool as 5G standalone core deployments mature, while fiber optics represents the fastest-growing infrastructure category driven by government-mandated universal broadband deadlines. Enterprise customer segments concentrate margin pools through multi-year managed service contracts, whereas residential TV services face structural pressure from over-the-top streaming displacement.
The Norwegian Communications Authority (Nkom) enforces spectrum allocation and net neutrality rules that directly determine operator bidding strategies and service tier structures. Norway's implementation of the EU Electronic Communications Code through the Ekomloven framework mandates infrastructure competition and wholesale access pricing. National security screening under the Norwegian National Security Act restricts vendor selection for critical 5G core components. Stakeholders must monitor pending regulatory consultations on data localization requirements and satellite-ground station integration standards.
Market Dynamics
Industrial spectrum reallocation under Ekomloven is compressing operator bidding timelines and forcing capital redeployment toward private network infrastructure. Maritime logistics and offshore energy clusters now command dedicated 5G slices, reshaping wholesale pricing power across the Oslo-Stavanger corridor.
Growth Catalysts
- Mid-band spectrum auctions:Nkom's industrial frequency reallocation enables dedicated private networks for autonomous vessel operations and subsea monitoring systems.
- Energy sector automation:Offshore platform digitization demands ultra-reliable low-latency connectivity for predictive maintenance and remote robotics.
- Subsea cable landing stations:Data center clustering around Stavanger and Kristiansand creates anchor tenancy demand for dark fiber and wavelength services.
Market Restraints
- Fjord terrain topology:Deep valleys and archipelago geography multiply radio site requirements and backhaul complexity versus comparable European markets.
- Vendor concentration in 5G core:National Security Act screening limits equipment sourcing to pre-approved vendors, extending procurement cycles.
- Fiber trenching costs:Permafrost and bedrock conditions in northern counties inflate civil engineering expenses for universal broadband rollout.
Strategic Opportunities
- Arctic connectivity corridors:Troms and Finnmark counties remain underserved for enterprise-grade wireless, presenting first-mover positioning for industrial IoT coverage.
- Satellite-ground convergence:Low Earth orbit gateway integration with terrestrial 5G cores enables hybrid connectivity for fishing fleets and remote mining camps.
- EU Green Deal alignment:Carbon-neutral network operations mandates create service differentiation opportunities through renewable-powered edge data centers.
Industry Challenges
- Specialized radio frequency engineering:Private 5G deployment for industrial automation requires scarce expertise in network slicing and edge orchestration.
- Legacy copper migration:Rural PSTN switch-off deadlines force coordinated customer transitions while maintaining service continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Telecom Market |
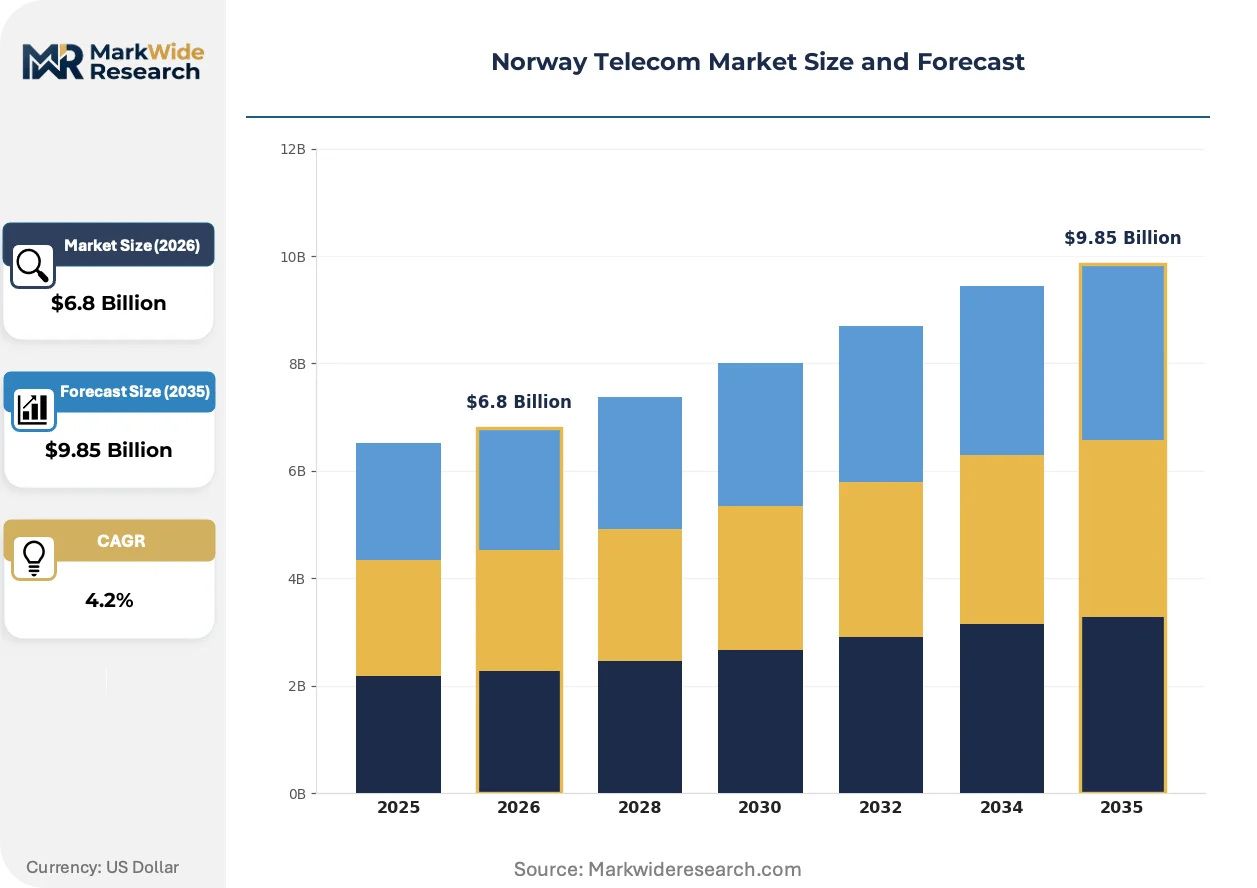
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Broadband, TV Services Technology: 4G, 5G, Fiber Optics, Satellite Customer Type: Residential, Business, Government, Enterprise Deployment: On-Premises, Cloud, Hybrid, Edge Computing |
| Companies Covered | Telenor, Telia Company, Ice Communication, BT Solutions Norway, Tata Communications (Nordic), LINK Mobility Group, Comrod, Appear, Jotron, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Telecom Market Trends and Innovations
Standalone 5G core deployment is digitizing operational technology networks across energy and maritime verticals. Network function virtualization and edge computing architectures are compressing latency specifications below 10 milliseconds for machine-to-machine control loops.
Open RAN architectures are digitizing baseband processing through software-defined radio implementations. Telenor and Ice Communication are trialing multi-vendor interoperable equipment in western county pilot zones. This disaggregation is digitizing supplier relationships and enabling component-level procurement rather than turnkey system purchases.
Ekomloven transposition of the EU Electronic Communications Code mandates infrastructure sharing and wholesale access pricing transparency. Nkom enforcement actions have compelled fiber unbundling in three metropolitan zones. Operators are responding through network-as-a-service leasing models that separate asset ownership from service delivery.
Enterprise procurement of connectivity is consolidating around multi-year managed service contracts with outcome-based SLAs. System integrators and hyperscale cloud providers are inserting themselves between operators and end customers in the Oslo-Stavanger corridor. Energy majors now specify latency, availability, and cybersecurity certifications as primary selection criteria rather than bandwidth metrics alone.
Norway Telecom Market Segmentation
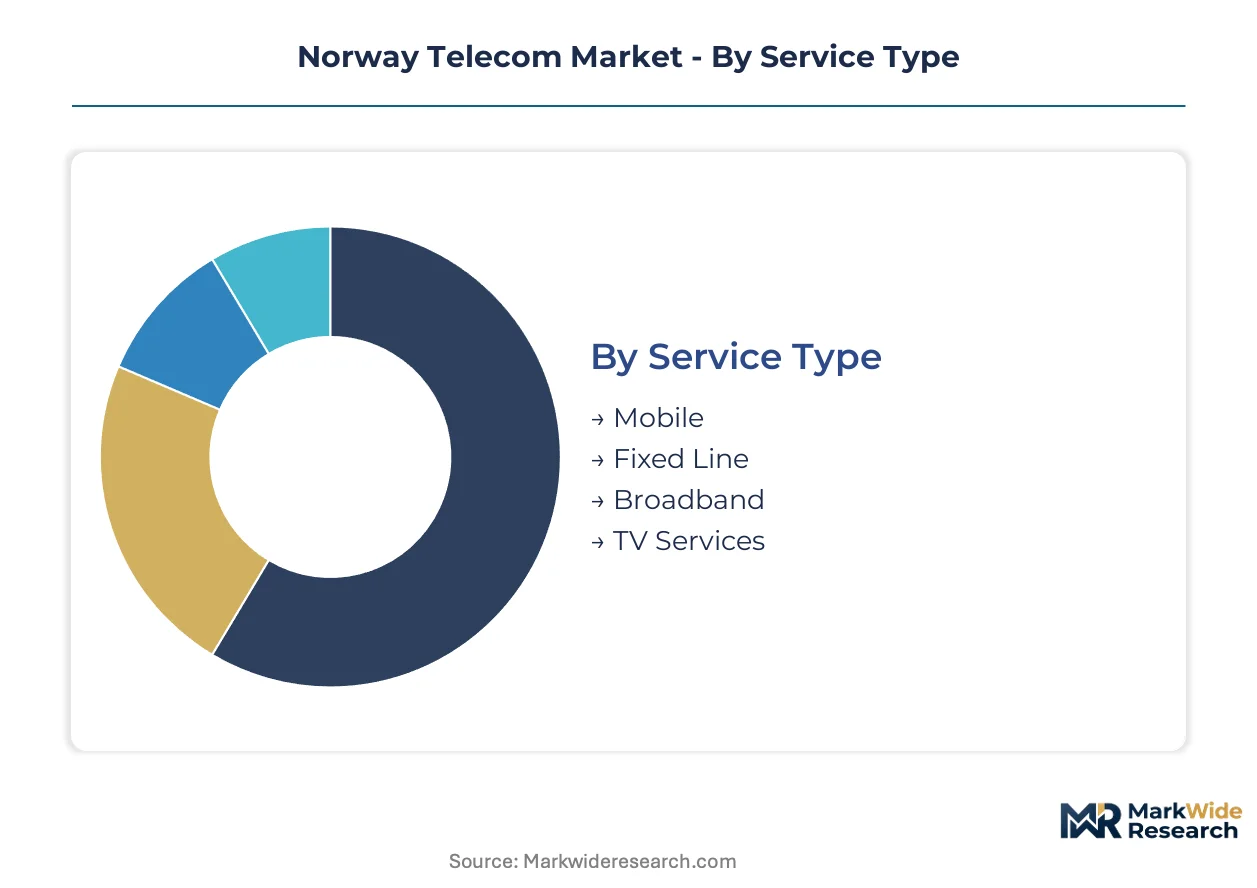
Norway's telecom segmentation reflects the country's distinctive geography and industrial structure. Fjord-indented terrain and offshore energy clusters create specialized demand patterns that diverge from continental European markets. Understanding these segment boundaries clarifies where capital deployment concentrates and where regulatory intervention reshapes competitive boundaries.
Service Type:
Revenue concentration across service tiers tracks the migration from legacy voice to data-centric consumption models.
- Mobile:5G standalone core deployments now support network slicing for maritime and energy verticals. Oslo-Stavanger corridor enterprises command premium tariffs for guaranteed latency SLAs on private infrastructure.
- Broadband:Fiber-to-the-home penetration accelerates under government-mandated universal deadlines. Northern county deployments face bedrock trenching cost premiums that distort provider economics versus southern zones.
- Fixed Line:PSTN switch-off timelines force coordinated customer migration to IP voice platforms. Rural trunk routes sustain wholesale leasing demand from Telenor's fiber backbone dominance.
- TV Services:Over-the-top streaming displacement compresses traditional broadcast revenue pools. Residential bundles increasingly detach video from core connectivity contracts.
Mobile holds installed capacity. Broadband is rotating up the share rankings.
Technology:
Technology adoption curves reflect spectrum allocation decisions by Nkom and infrastructure lifecycle replacement cycles.
- 5G:Mid-band spectrum auctions enable dedicated private networks for autonomous vessel operations. Sub-6 GHz New Radio deployments concentrate in industrial zones around Stavanger data center clusters.
- Fiber Optics:Passive optical network specifications now reach gigabit symmetrical throughput in metropolitan zones. Subsea cable landing stations at Kristiansand anchor dark fiber demand from hyperscale tenants.
- 4G:LTE infrastructure sustains coverage in Arctic counties where 5G site economics remain prohibitive. Troms and Finnmark rely on legacy radio for fishing fleet and remote camp connectivity.
- Satellite:Low Earth orbit gateway integration trials proceed with terrestrial 5G core interconnection. Hybrid architectures address coverage gaps in mountainous fjord terrain where fiber backhaul fails.
Fiber optics holds installed capacity. 5G is rotating up the share rankings.
Customer Type:
Margin capture varies sharply across customer categories based on contract structure and service customization depth.
- Enterprise:Multi-year managed service contracts specify outcome-based SLAs for latency and availability. Energy majors now require cybersecurity certifications as primary selection criteria alongside bandwidth metrics.
- Business:Small and medium enterprises procure connectivity through system integrator intermediaries. Cloud provider partnerships reshape direct operator relationships in the Oslo-Stavanger corridor.
- Government:Public safety networks demand ultra-reliable low-latency specifications for emergency response coordination. National Security Act screening restricts vendor selection for critical infrastructure components.
- Residential:Price-sensitive mass market faces streaming-driven video service unbundling. Universal broadband mandates ensure baseline connectivity access across archipelago geography.
Enterprise holds installed capacity. Business is rotating up the share rankings.
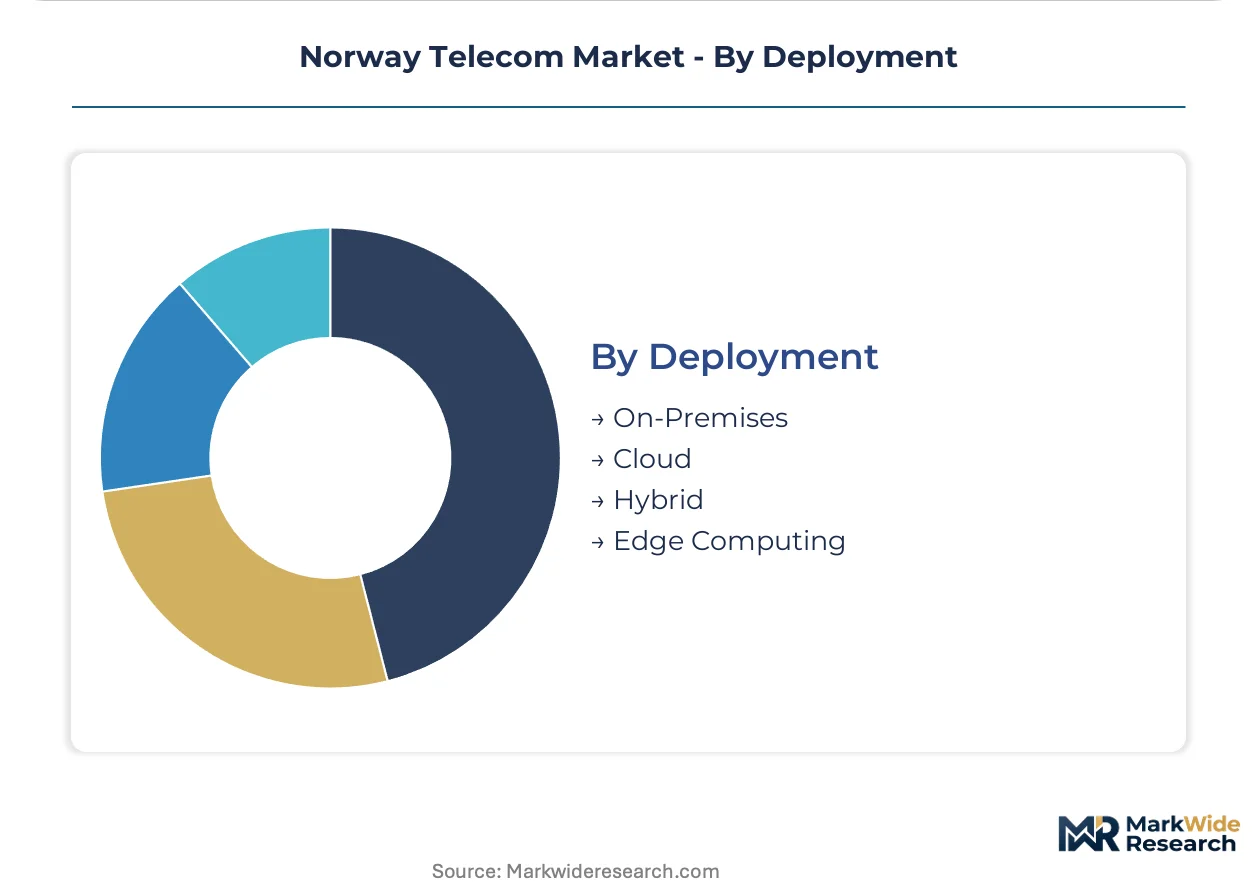
Deployment:
Infrastructure ownership models separate asset-heavy operators from service-layer competitors.
- Cloud:Network function virtualization enables software-defined core deployment without proprietary hardware lock-in. Telia Company anchors Nordic cross-border enterprise contracts through centralized cloud orchestration.
- Edge Computing:Distributed processing architectures compress latency below 10 milliseconds for industrial automation control loops. Renewable-powered edge data centers create Green Deal-aligned service differentiation.
- Hybrid:Mixed cloud-edge configurations balance cost efficiency with latency-sensitive workload placement. Maritime logistics operators trial split architectures for vessel-to-shore connectivity.
- On-Premises:Private 5G cores serve offshore platforms with data residency requirements. Autonomous subsea monitoring systems mandate localized processing for security isolation.
On-premises holds installed capacity. Edge computing is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power across Norway's telecom sector concentrates in the Oslo-Stavanger corridor, where subsea cable landing stations and data center clusters command premium connectivity tariffs, while northern counties face cost premiums from bedrock trenching and sparse population density.
Oslo-Viken Corridor
Enterprise demand for private 5G networks and fiber-to-the-home penetration drive infrastructure investment across Norway's capital region. The Norwegian Communications Authority enforces wholesale access pricing under Ekomloven, mandating infrastructure competition in metropolitan zones. Fornebu and Lillestrøm host hyperscale data center clusters that anchor dark fiber demand from international tenants.
Stavanger-Rogaland
Offshore energy platform digitization and autonomous vessel operations require ultra-reliable low-latency connectivity specifications. National security screening under the Norwegian National Security Act restricts vendor selection for critical 5G core components serving oil and gas infrastructure. The Greater Stavanger area concentrates subsea cable landing stations that interconnect Nordic and North Atlantic fiber routes.
Bergen-Vestland
Maritime logistics clusters and fjord-indented terrain create specialized radio site requirements for fishing fleet connectivity. Ice Communication competes through aggressive 5G spectrum positioning in these underserved western counties. The Port of Bergen anchors industrial IoT trials for hybrid satellite-terrestrial vessel tracking systems.
Trondheim-Trøndelag
Public safety networks and regional healthcare digitization drive government procurement of secure connectivity infrastructure. Universal broadband mandates under government rollout deadlines accelerate fiber deployment despite challenging topography. Trondheim's technology university cluster generates specialized radio frequency engineering expertise for private network deployment.
Troms and Finnmark
Arctic connectivity gaps and remote mining camps present first-mover opportunities for industrial IoT coverage in Norway's northernmost counties. Permafrost conditions inflate civil engineering expenses for fiber trenching versus southern zones. Kirkenes and Hammerfest trial low Earth orbit gateway integration with terrestrial 5G cores for hybrid fishing fleet connectivity.
Norway Telecom Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying radio access equipment and core network functions. Norway's telecom structure consolidates around three nationwide mobile network operators with infrastructure-sharing agreements reducing redundant capital deployment. Strategic archetypes include fiber backbone owners leasing wholesale trunk capacity, spectrum-positioned challengers targeting underserved geographies, and Nordic cross-border service integrators anchoring enterprise contracts. Dominant competitive moves encompass network-as-a-service leasing models that separate asset ownership from service delivery, and multi-vendor Open RAN trials that disaggregate traditional supplier relationships.
Within the integrated operator tier, Telenor leverages its nationwide fiber backbone to sustain wholesale dominance in rural trunk routes, while Telia Company anchors enterprise connectivity contracts across Nordic cross-border corridors. Ice Communication occupies a challenger position through aggressive 5G spectrum positioning in western counties. These three entities represent distinct strategic postures: incumbent infrastructure leverage, regional enterprise integration, and geographic whitespace exploitation.
| Leading Market Players |
|---|
| Telenor |
| Telia Company |
| Ice Communication |
| BT Solutions Norway |
| Tata Communications (Nordic) |
| LINK Mobility Group |
| Comrod |
| Appear |
| Jotron |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Nordic equipment vendors for 5G core components compresses procurement timelines and widens pricing spreads between premium-certified and standard-tier connectivity contracts. Nkom's national security screening under the Norwegian National Security Act forces buyers toward pre-approved supplier rosters, concentrating supply leverage and inflating upfront capital commitments for private network deployments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Oslo-Stavanger corridor, with energy majors negotiating multi-year managed service agreements that bundle latency SLAs with cybersecurity certifications. Price differentiation separates premium private 5G slices from standard mobile broadband tiers based on guaranteed availability metrics and edge computing proximity. Pricing pressure stems from hyperscale cloud providers inserting themselves between operators and end customers, compressing direct operator margins. Residential segments exhibit highest price sensitivity as streaming-driven unbundling detaches video from core connectivity contracts, while enterprise buyers prioritize outcome-based specifications over unit bandwidth costs.
Supply Chain Analysis
Extended payment terms from Nordic network equipment manufacturers to component subcontractors stretch working capital cycles across the vendor base. Geographic supply concentration centers on Sweden, Finland, and Germany for radio access equipment and core network functions. Raw material dependencies include gallium nitride semiconductors, fiber optic preforms, and rare earth elements for antenna systems. Single-source vulnerability runs through specialized radio frequency engineering talent pools for private network deployment. Distribution runs through system integrator intermediaries that reshape direct operator relationships in enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Network-as-a-service leasing models represent a service-attach opportunity expanding faster than hardware ownership, as operators separate asset ownership from service delivery to capture recurring revenue streams.
For Market Incumbents: Entrench wholesale fiber dominance through infrastructure-sharing agreements that reduce redundant capital deployment across rural trunk routes. Deepen backward integration into edge data center operations to defend margin position against hyperscale cloud provider encroachment. Prioritize certification investment under EU Green Deal alignment to differentiate carbon-neutral network operations. For New Entrants and Emerging Players: Establish a beachhead in Arctic connectivity corridors across Troms and Finnmark counties where enterprise-grade wireless remains underserved. Target maritime logistics clusters in Bergen-Vestland for hybrid satellite-terrestrial vessel tracking systems. Pursue system integrator partnerships as the primary go-to-market angle to bypass direct operator channel control. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fiber backbone owners with wholesale leasing capabilities and spectrum-positioned challengers in geographic whitespace. Long-term viability hinges on exposure to private 5G network deployment for energy and maritime verticals. Watch Nkom regulatory consultations on data localization requirements as the inflection indicator for infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Network Deployment | Captures premium enterprise contracts from Equinor and Aker BP for offshore platform digitization. |
| Edge Data Center Buildout | Enables sub-10 millisecond latency for industrial automation control loops in Stavanger clusters. |
| Open RAN Architecture Adoption | Disaggregates supplier relationships and reduces dependency on single-source 5G core vendors. |
| Satellite-Ground Convergence | Addresses coverage gaps in fjord terrain through low Earth orbit gateway integration trials. |
| Infrastructure Sharing Agreement | Compresses capital deployment timelines under Ekomloven wholesale access pricing mandates. |
Research Methodology
Initial hypotheses were tested against primary input from network operations executives, enterprise procurement managers at energy majors, regulatory affairs specialists at Nkom, and system integrator technical leads, then refined through secondary validation. Secondary sources included Norwegian Communications Authority spectrum auction records, Ekomloven regulatory filings, subsea cable landing station operator disclosures, and Nordic cross-border operator financial statements. Bottom-up demand modeling across customer segments was triangulated with top-down market sizing from infrastructure investment disclosures.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions covering service type, technology generation, customer category, and deployment architecture. CAGRs were derived from installed capacity growth rates adjusted for replacement cycles and regulatory-driven acceleration factors. Industry-specific inputs included Nkom auction timelines, universal broadband rollout deadlines, and national security screening approval rates for 5G core vendors.
Stress conditions across spectrum allocation delays, vendor approval bottlenecks, and Arctic deployment cost overruns were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and infrastructure subsidy continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
5G Technology Market
Telecommunications
Ghana Telecom Market
Telecommunications
Russia Telecom Market
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
Ireland Telecom Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Australia Telecom Market
Telecommunications
Egypt ICT Market
Telecommunications
Competitive Local Exchange Carriers (CLEC) Market
Telecommunications
Dialer Market
Telecommunications
Telecom Services Market