
 North America Managed Mobility Service Market | 2026-2036
North America Managed Mobility Service Market Size, Share, and Industry Trends Forecast 2026-2036
North America Managed Mobility Service Market Foresight
Corporate zero-trust security mandates from the US federal government is consolidating demand for managed endpoint security across enterprise mobility programs. AT&T Inc. leverages its carrier-native infrastructure to deliver integrated network-security bundles that reduce vendor fragmentation for large employers. IBM Corporation anchors its position through AI-driven predictive analytics that automate device lifecycle decisions across heterogeneous fleets. Cisco Systems Inc. competes on the strength of its SASE architecture, extending policy enforcement from campus networks to mobile endpoints without perimeter dependency.
Managed mobility services encompass the full outsourcing of procurement, provisioning, security, expense management, and lifecycle support for corporate mobile device fleets, typically governed by SLAs specifying mean-time-to-resolution thresholds below four hours for critical incidents. The primary commercial purpose is to convert capital-intensive telecom operations into predictable operating expenditures while enforcing consistent security posture across geographically dispersed workforces. Device Management commands the largest share of service revenues due to hardware refresh cycles and OS fragmentation complexity, while Security Management generates the highest margins as ransomware insurance requirements harden endpoint protection standards. Cloud-Based deployment is displacing on-premises MDM infrastructure as enterprises prioritize elastic capacity for seasonal workforce scaling without data center capital.
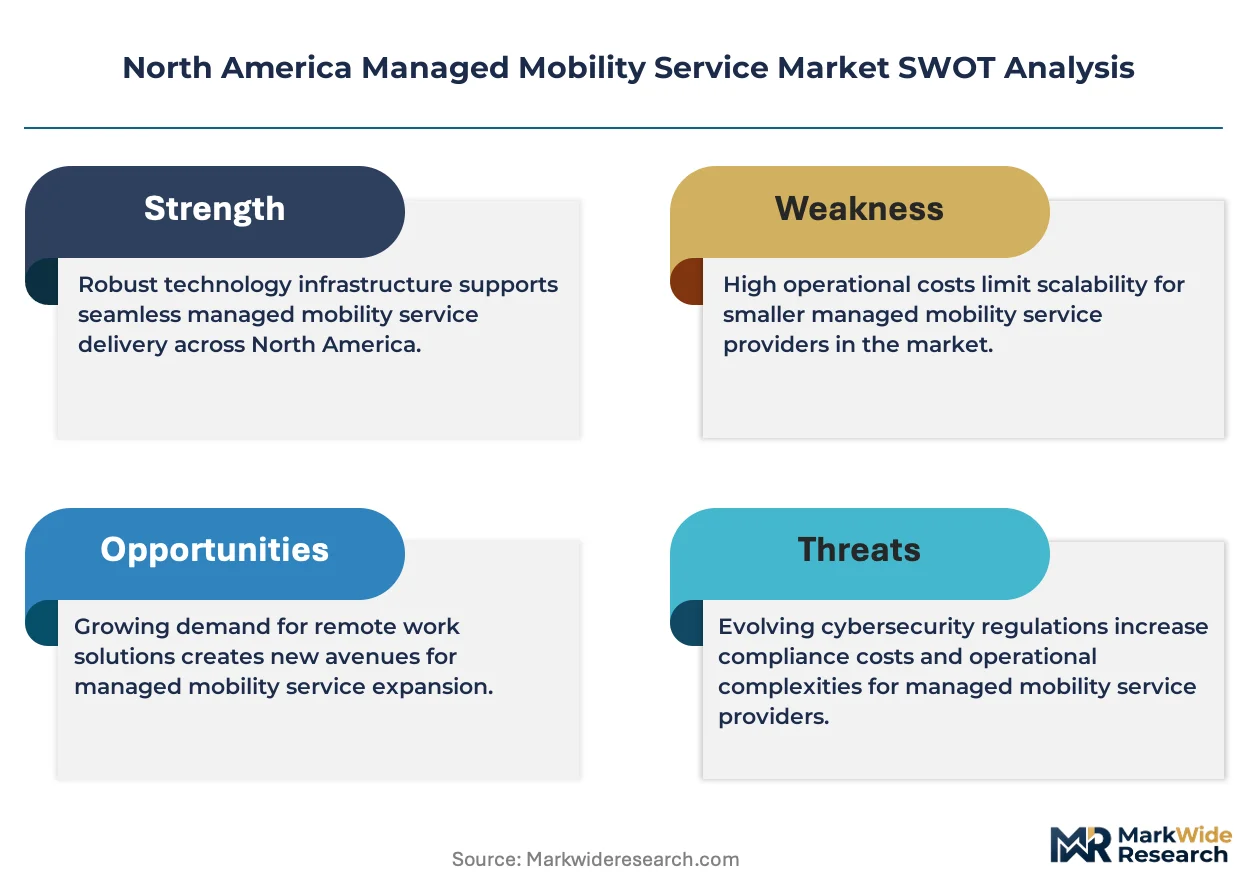
FCC net neutrality restoration and NIST zero-trust architecture guidance shape how carriers architect managed connectivity services, while HIPAA security rule enforcement drives healthcare-specific mobile encryption requirements that exceed baseline commercial standards. State-level data residency laws in California and New York fragment compliance obligations, forcing providers to maintain regionally segmented policy engines. Stakeholders must evaluate whether their current vendor relationships can absorb emerging quantum-resistant authentication protocols without wholesale platform replacement.
Market Dynamics
Federal zero-trust cybersecurity mandates are compressing procurement cycles across enterprise mobility programs, forcing carriers and systems integrators to bundle network connectivity with endpoint security under unified SLAs. This structural shift favors providers with native infrastructure over pure-play software vendors.
Growth Catalysts
- Zero-trust architecture mandates:NIST guidance requires continuous device verification across federal contractor supply chains, expanding addressable market for managed endpoint security services.
- Healthcare encryption requirements:HIPAA security rule enforcement drives Canadian and US hospital systems toward outsourced mobile device management exceeding baseline commercial standards.
- Elastic cloud infrastructure:Cloud-based deployment models enable seasonal workforce scaling without data center capital, accelerating displacement of on-premises MDM installations.
Market Restraints
- Carrier concentration risk:Managed connectivity services depend on three dominant US wireless operators, creating single-source vulnerability for bundled offerings.
- State-level data fragmentation:California and New York residency laws force providers to maintain parallel policy engines, inflating compliance architecture costs.
- Legacy OS support burden:Android fragmentation across hardware OEMs extends security patch cycles, elevating mean-time-to-resolution for critical incidents.
Strategic Opportunities
- Canadian government vertical:Federal and provincial digital transformation programs in Ottawa and Toronto corridors represent underpenetrated demand for secure fleet management.
- Quantum-resistant authentication:Post-quantum cryptographic standards from NIST create upgrade cycles for credential infrastructure across financial services mobility programs.
- AI-powered lifecycle automation:Predictive analytics converging with device telemetry enable proactive refresh scheduling, reducing unplanned hardware expenditures for enterprise clients.
Industry Challenges
- Zero-trust engineering scarcity:Shortage of architects certified in continuous verification frameworks limits service provider capacity to meet compressed federal procurement timelines.
- Heterogeneous fleet integration:Enterprises operating mixed iOS, Android, and ruggedized Windows endpoints face policy engine complexity that degrades unified security posture enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Managed Mobility Service Market |
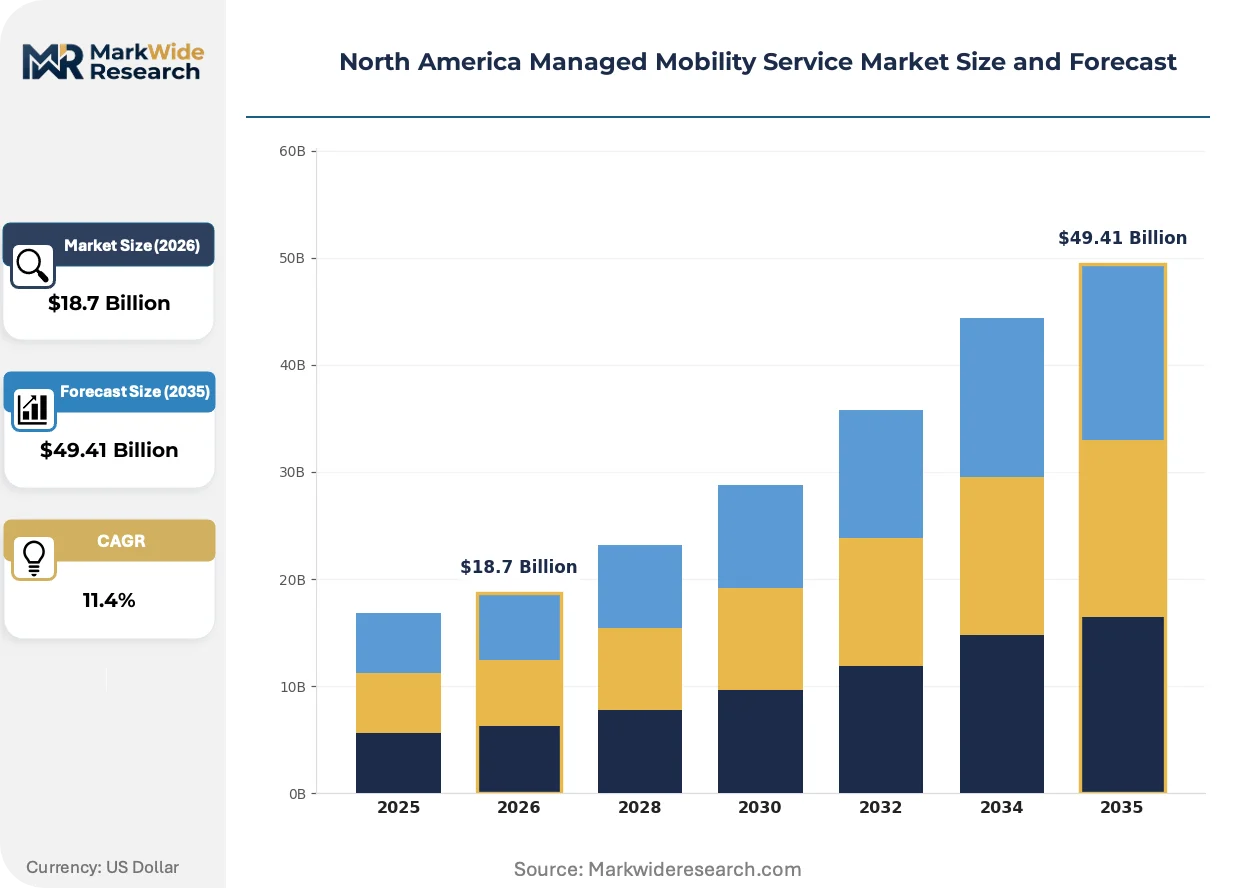
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Device Management, Application Management, Security Management, Network Management Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed End User: SMBs, Enterprises, Government, Healthcare Technology: IoT, AI, MDM, BYOD |
| Companies Covered | Cisco Systems Inc, Accenture PLC, AT&T Inc., Fujitsu Ltd, Telefonaktiebolaget L M Ericsson, IBM Corporation, DXC Technology, HCL Technologies, Hewlett Packard Enterprise Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Managed Mobility Service Market Shifts & Advancements
Endpoint security architecture is converging with network policy enforcement, eliminating perimeter-dependent protection models. This integration is compressing vendor stacks and reshaping how enterprises evaluate managed service providers.
SASE architecture is consolidating network and security policy enforcement into cloud-native delivery models. Large employers with distributed workforces are adopting these frameworks fastest, compressing procurement from separate network and security vendors into single-source relationships. The technology is consolidating competitive positioning around carriers with native infrastructure.
FCC net neutrality restoration is reshaping how carriers architect managed connectivity services, requiring transparent traffic management disclosures. This regulatory shift elevates compliance documentation burdens for service-level agreements. Healthcare and government segments are responding by demanding carrier attestation of non-discriminatory routing practices.
Enterprise sourcing patterns are rotating toward consumption-based pricing for device lifecycle services. Traditional per-seat models are yielding to metered arrangements tied to actual support ticket volume and data consumption. This shift is most visible among US financial services firms with seasonal staffing fluctuations.
North America Managed Mobility Service Market Segmentation
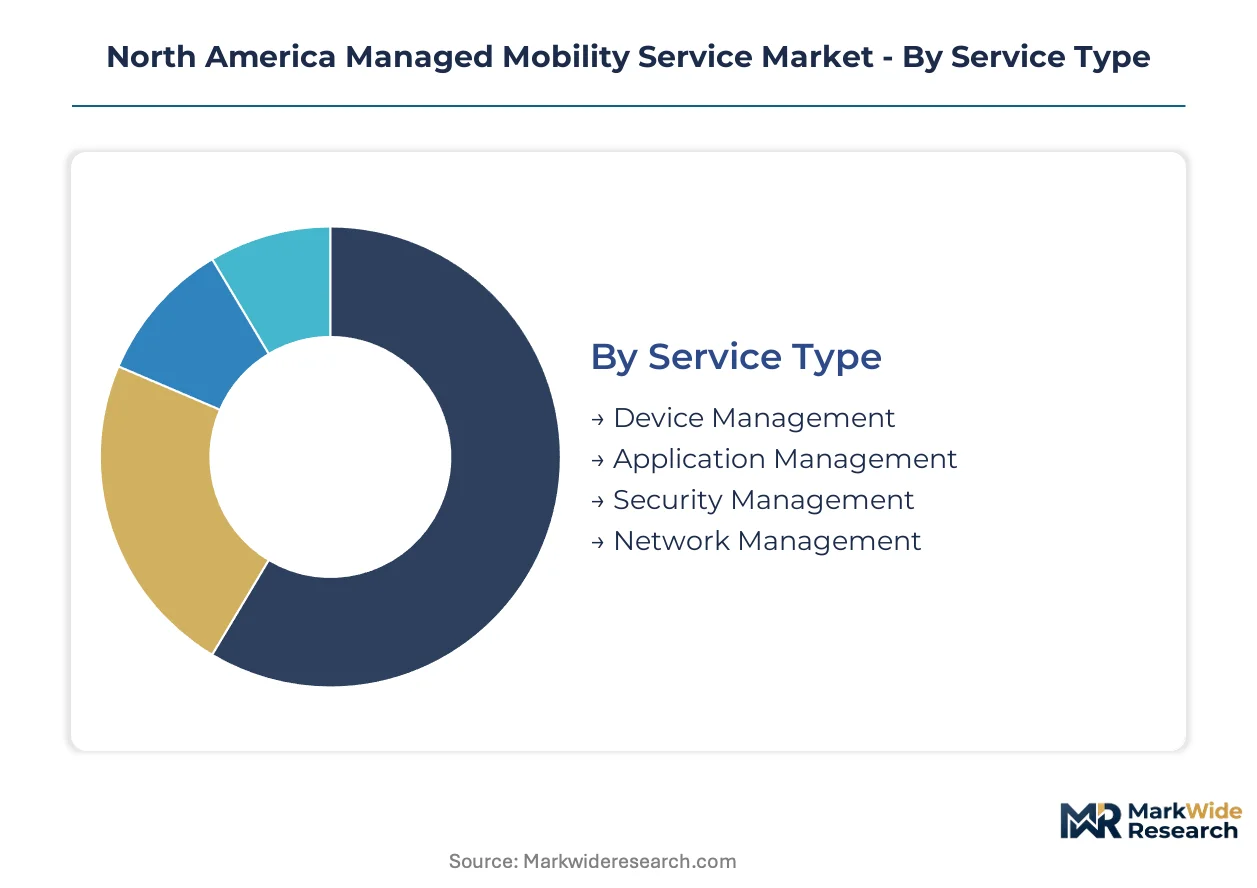
Segmentation in managed mobility services determines how providers architect pricing, compliance, and service-level commitments. Enterprise procurement teams evaluate vendors across deployment architecture, security depth, and vertical-specific regulatory attestation before contract execution.
Service Type:
Technical sophistication and margin structure vary sharply across functional service layers, with security and lifecycle automation commanding premium positioning.
- Device Management:Encompasses procurement, provisioning, OS patching, and hardware refresh scheduling across heterogeneous fleets. US federal contractors and Fortune 500 manufacturers concentrate demand here, driven by compressed replacement cycles for Android fragmentation and NIST zero-trust hardware attestation requirements.
- Security Management:Delivers endpoint threat detection, encryption policy enforcement, and conditional access tied to continuous device verification. Canadian hospital systems and US financial services firms represent the most intense demand concentration, propelled by HIPAA security rule enforcement and ransomware insurance underwriting standards that mandate outsourced mobile security operations.
- Application Management:Controls enterprise app distribution, version control, and containerization across managed devices.
- Network Management:Optimizes carrier connectivity, roaming cost containment, and SLA performance monitoring across dispersed workforces.
Mature deployment sits with Device Management. Newer deployment is concentrated in Security Management.
Deployment Model:
Capital efficiency and elastic capacity requirements are reshaping how enterprises contract for mobility infrastructure, with consumption-based arrangements displacing perpetual licensing.
- Cloud-Based:Delivers multi-tenant policy engines, automatic scaling, and API-native integration with identity providers and SIEM platforms. US technology firms and seasonal retail operations in California and New York corridors drive adoption, seeking to avoid data center capital while maintaining regionally segmented policy engines for state residency compliance.
- Hybrid:Combines on-premises policy enforcement for sensitive data with cloud-delivered analytics and support automation. Canadian provincial government agencies and US defense contractors favor this architecture, balancing classified workload isolation with operational cost discipline.
- On-Premises:Legacy MDM infrastructure requiring dedicated hardware and internal security operations center integration.
- Managed:Fully outsourced operational responsibility with vendor-owned infrastructure and staff augmentation.
Established footprints remain in On-Premises. Fastest expansion is occurring in Cloud-Based.
End User:
Contract scale and compliance complexity diverge dramatically across organizational size and sectoral regulatory exposure.
- Enterprises:Multi-thousand seat contracts with unified endpoint management across global footprints, typically requiring carrier-agnostic connectivity and dedicated technical account management. Demand concentrates among US-based multinationals with distributed manufacturing and professional services workforces, where federal zero-trust mandates are compressing procurement cycles toward bundled network-security offerings.
- Government:Federal, state, and provincial agencies requiring FedRAMP or equivalent attestation, domestic data residency, and supply chain security verification. Canadian federal digital transformation programs in Ottawa and Toronto corridors represent underpenetrated demand, while US civilian agencies face accelerated modernization timelines under zero-trust architecture guidance.
- SMBs:Mid-market employers with simplified procurement needs and standardized device configurations.
- Healthcare:Hospital systems and clinical networks with specialized mobile encryption and patient data isolation requirements.
Volume concentration rests with Enterprises. Regulatory complexity peaks in Government.
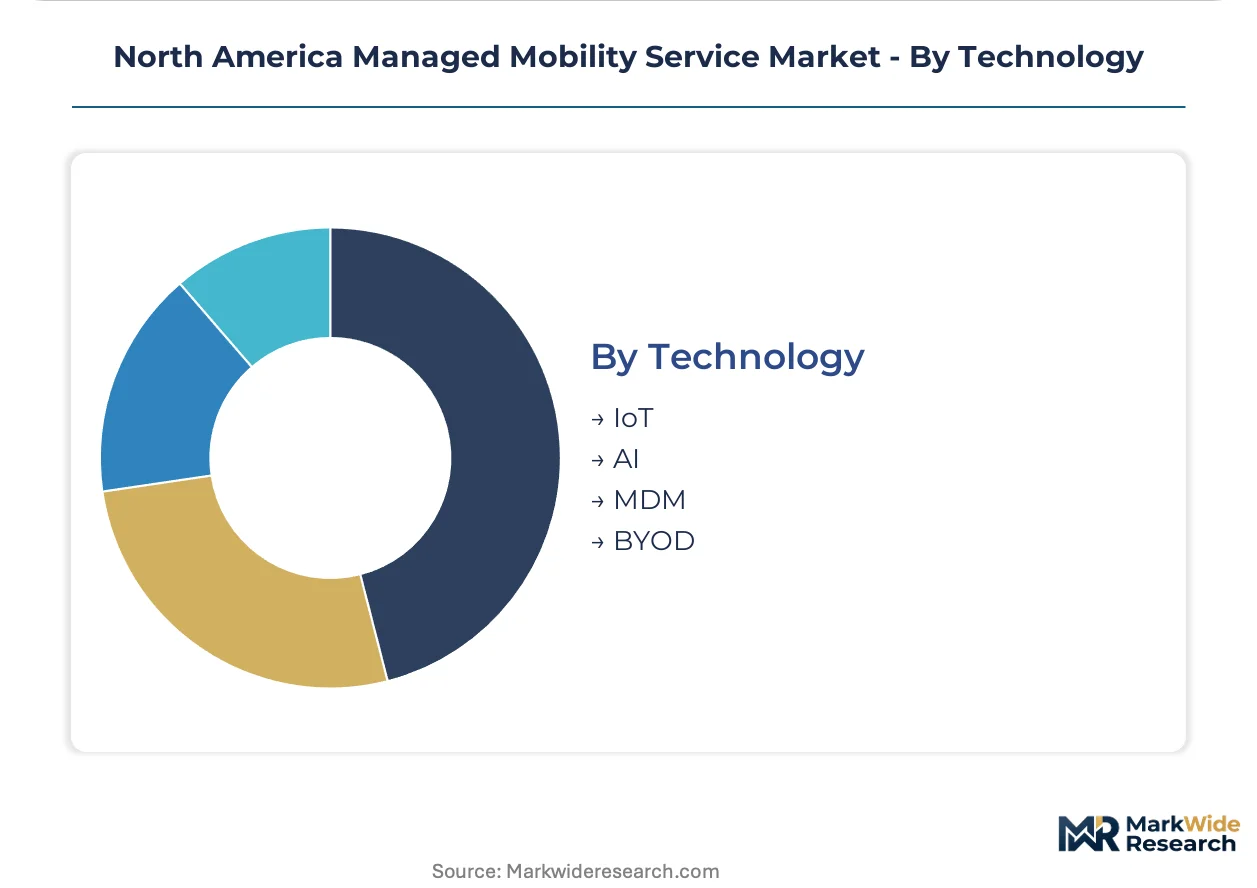
Technology:
Intelligence layer integration determines competitive differentiation, with predictive automation and edge connectivity expanding addressable use cases.
- AI:Powers predictive device failure detection, automated ticket routing, and anomaly-based security policy adjustment. US financial services firms with seasonal staffing fluctuations are adopting AI-driven lifecycle analytics fastest, seeking to reduce unplanned hardware expenditures through proactive refresh scheduling based on telemetry patterns.
- IoT:Extends managed connectivity and security policy to non-traditional endpoints including fleet telematics, industrial sensors, and medical devices. Demand clusters in Canadian resource extraction operations and US logistics corridors, where cellular-connected asset tracking requires unified policy enforcement alongside traditional mobile fleets.
- MDM:Core mobile device management platforms providing baseline enrollment, configuration, and compliance monitoring.
- BYOD:Bring-your-own-device frameworks enabling personal hardware access to corporate resources through containerization.
Baseline functionality resides in MDM. Steepest expansion trajectory belongs to AI.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth corridor anchors North American managed mobility service deployment, hosting major carrier infrastructure and enterprise security operations centers that feed procurement decisions across the continent.
United States
Federal zero-trust mandates from NIST and OMB compress procurement cycles for civilian agencies and defense contractors. FCC net neutrality restoration requires transparent traffic management disclosures that reshape carrier SLA architectures. The Washington DC-Baltimore corridor concentrates government contractor demand, while Silicon Valley technology firms drive cloud-native deployment adoption.
Canada
Provincial healthcare systems in Ontario and Quebec accelerate outsourced mobile device management to meet HIPAA-equivalent encryption standards. Federal digital transformation programs through Shared Services Canada expand secure fleet management contracts. The Ottawa-Toronto corridor emerges as the primary demand cluster for government and hospital system procurement.
Mexico
Manufacturing operations in Nuevo León and Baja California generate cross-border mobility management requirements for US-owned maquiladoras. Mexico's federal data protection authority enforces localization requirements that complicate unified policy enforcement. The Mexico City metro area concentrates financial services demand for secure endpoint management.
North America Managed Mobility Service Market Competitive Landscape
The competitive structure tilts toward carrier-integrated systems integrators with native network infrastructure. Three US wireless operators control underlying connectivity, forcing pure-play software vendors into partnership arrangements. Strategic archetypes include carrier-native bundlers, AI-driven lifecycle automation specialists, and SASE architecture providers. Consolidation through vertical capability acquisition and unified SLA bundling represents the dominant competitive motion.
Within the carrier-native tier, AT&T Inc. exemplifies infrastructure-integrated service delivery, while IBM Corporation occupies a position as an AI-centric lifecycle automation anchor. Cisco Systems Inc. represents the SASE-converged security architecture archetype. These three entities collectively illustrate how federal procurement compression favors providers with unified network-security policy engines over fragmented vendor stacks.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Accenture PLC |
| AT&T Inc. |
| Fujitsu Ltd |
| Telefonaktiebolaget L M Ericsson |
| IBM Corporation |
| DXC Technology |
| HCL Technologies |
| Hewlett Packard Enterprise Company |
| Others |
Supply & Pricing Matrix
Carrier-native security bundles versus pure-play software licensing creates a sharp bifurcation in contract economics, with unified SLA offerings commanding substantial premiums while fragmented vendor stacks face compression from federal procurement consolidation. This tier divergence manifests in supply chain configurations: premium positioning requires direct infrastructure ownership and FedRAMP-certified data centers, while commodity tiers depend on third-party carrier partnerships and shared policy engines.
Pricing Analysis
Value-based pricing anchored to mean-time-to-resolution guarantees and zero-trust compliance attestation dominates enterprise procurement. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized providers with native infrastructure from regional resellers and basic MDM operators. Cost compression in the standard tier is intensifying because carrier bundling eliminates standalone security vendor margins. SMBs exhibit highest price sensitivity, while defense contractors and financial services firms prioritize compliance depth over unit cost.
Supply Chain Analysis
FedRAMP authorization and NIST zero-trust certification gating restricts viable infrastructure providers to a narrow tier of domestic operators with cleared personnel and segmented policy engines. Geographic supply concentration centers on the United States for federal workloads, with Canada emerging for provincial healthcare compliance and Mexico serving cross-border manufacturing corridors. Raw material dependencies include semiconductor components for endpoint hardware, cryptographic modules for zero-trust implementations, and cloud compute capacity from hyperscaler regions. Single-source vulnerability runs through the three dominant wireless carriers controlling underlying connectivity. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-trust engineering scarcity constrains service provider capacity, propping pricing power for certified architects and infrastructure owners against compressed federal procurement timelines.
For Market Incumbents: Anchor market position through backward integration into quantum-resistant credential infrastructure before NIST post-quantum standards harden procurement requirements. Defensive consolidation should prioritize AI-driven lifecycle automation capabilities to offset margin pressure from carrier-native bundling. Vertical integration into FedRAMP-authorized data centers protects against pure-play software commoditization. For New Entrants and Emerging Players: Begin with Canadian provincial government and healthcare verticals, where Shared Services Canada modernization programs and HIPAA-equivalent encryption mandates create underpenetrated demand corridors. The Ottawa-Toronto cluster offers the most penetrable geography given limited incumbent specialization in bilingual compliance attestation. A channel partnership route through systems integrators already holding federal contracts accelerates credibility without direct certification burden. For Investors and Strategic Acquirers: Re-rating potential sits with AI-centric lifecycle automation specialists given convergence of predictive analytics with device telemetry reshaping refresh economics. Long-term viability across the analysis window favors providers with unified network-security policy engines over fragmented vendor stacks. The signal to watch is carrier M&A activity targeting pure-play security vendors, indicating bundling acceleration and margin compression for standalone operators.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks federal contractor supply chain access under OMB zero-trust mandates. |
| AI Lifecycle Automation Platform | Reduces unplanned hardware expenditures for financial services seasonal workforces. |
| Canadian Provincial Partnership | Captures Shared Services Canada digital transformation procurement corridors. |
| Quantum-Resistant Credential Infrastructure | Positions for NIST post-quantum cryptographic standard upgrade cycles. |
| SASE Architecture Convergence | Eliminates perimeter-dependent protection models for distributed enterprise workforces. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with mobility program directors, federal procurement officers, carrier enterprise account executives, and healthcare IT security leads. FCC net neutrality dockets, NIST zero-trust guidance documents, and FedRAMP authorization databases provided compliance architecture benchmarks. Bottom-up triangulation across service provider contract disclosures and top-down validation against carrier infrastructure investment patterns ensured cross-verification.
Segment-level modeling addressed deployment architecture, security depth tiering, vertical regulatory exposure, and end-user scale categories across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves incorporating federal mandate acceleration effects and cloud displacement rates. Forecast inputs included carrier capital expenditure trajectories, zero-trust certification pipeline data, and seasonal workforce scaling patterns from retail and financial services verticals.
Underlying measurement precision varies by segment; cloud-based deployment and enterprise end-user categories carry tighter precision than emerging SMB and hybrid architecture segments. Forecasts reflect documented assumptions regarding federal procurement timeline compression and carrier bundling penetration. A model refresh is warranted upon material change in NIST zero-trust implementation deadlines or FCC traffic management disclosure requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Brazil Digital Twin Market
Digital Solutions
Enterprise Search Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
Virtual Office Market
Digital Solutions
Global B2B Services Review Platforms Market
Digital Solutions
Smart Signage Market
Digital Solutions
Digital Onboarding Software Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Serverless Architecture Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Global E-Passport and E-Visa Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Global User Experience (UX) Market
Digital Solutions
Global Connected Workplace Market
Digital Solutions
US Transcription Market