
 Luxembourg Telecom Market | 2026-2036
Luxembourg Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Luxembourg Telecom Market Insights
Enterprise cloud connectivity revenue is narrowing as hyperscale providers build direct fiber into Luxembourg's financial district. POST Luxembourg leverages its incumbent infrastructure to sustain wholesale dominance across the Grand Duchy. Orange Luxembourg competes through aggressive 5G fixed-wireless positioning in suburban zones. SES anchors satellite backhaul demand from institutional clients beyond terrestrial reach.
Luxembourg Telecom encompasses wireline, wireless, and satellite communication services delivered over infrastructure ranging from copper DSL loops to single-mode fiber and sub-6 GHz 5G NR. The sector supports high-frequency trading, sovereign data hosting, and cross-border EU regulatory compliance with latency thresholds below 10 milliseconds for fiber links between Luxembourg City and Frankfurt. Fiber optics leads capital deployment as ILR's national broadband plan prioritizes gigabit-passive-optical-network coverage. 5G trails in enterprise adoption but accelerates among logistics operators near Findel Airport. Mobile service revenue remains mature with prepaid erosion offset by postpaid family plan bundling.
ILR spectrum auctions and EU Electronic Communications Code transposition shape operator rollout timelines and wholesale pricing obligations. GDPR and national data protection frameworks impose encryption and residency requirements that elevate demand for locally hosted core network functions. Stakeholders must weigh fiber densification economics against 5G fixed-wireless alternatives as enterprise customers renegotiate multi-year connectivity contracts.
Market Dynamics
Hyperscale cloud providers are building direct fiber infrastructure into Luxembourg's financial district, compressing margins for traditional carrier wholesale services while ILR's universal service obligations maintain baseline coverage mandates.
Growth Catalysts
- GDPR data residency frameworks:Financial institutions require locally hosted core network functions, elevating demand for sovereign Luxembourg data centers with sub-10 millisecond latency to Frankfurt.
- Findel Airport logistics corridor:Freight operators near Luxembourg's cargo hub are accelerating 5G adoption for real-time shipment tracking and automated warehouse systems.
- ILR national broadband plan:Regulatory prioritization of gigabit-passive-optical-network coverage is channeling capital toward fiber densification across the Grand Duchy.
Market Restraints
- Copper loop decommissioning costs:Legacy DSL infrastructure retirement imposes stranded asset write-downs on incumbent operators maintaining universal service obligations.
- Spectrum scarcity in sub-6 GHz bands:ILR auction timelines constrain 5G fixed-wireless expansion, limiting suburban coverage alternatives to fiber backhaul.
- Hyperscale bypass threat:Direct cloud provider fiber builds into Luxembourg City are eroding traditional enterprise connectivity pricing power.
Strategic Opportunities
- Cross-border EU regulatory compliance:Luxembourg's data protection authority CNPD enforcement creates specialized hosting demand from institutions requiring GDPR-aligned infrastructure.
- Satellite backhaul institutional niche:SES geostationary services address connectivity gaps for sovereign clients beyond terrestrial fiber reach in rural Luxembourg.
- 5G fixed-wireless suburban positioning:Orange Luxembourg's aggressive rollout in peripheral zones captures residential and SME segments underserved by fiber economics.
Industry Challenges
- Multi-year contract renegotiation cycles:Enterprise customers are consolidating connectivity vendors, forcing carriers to defend position through bundled service integration.
- Fiber-to-the-premises skill shortages:Specialized splicing and GPON deployment technicians are scarce relative to ILR coverage targets, extending rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxembourg Telecom Market |
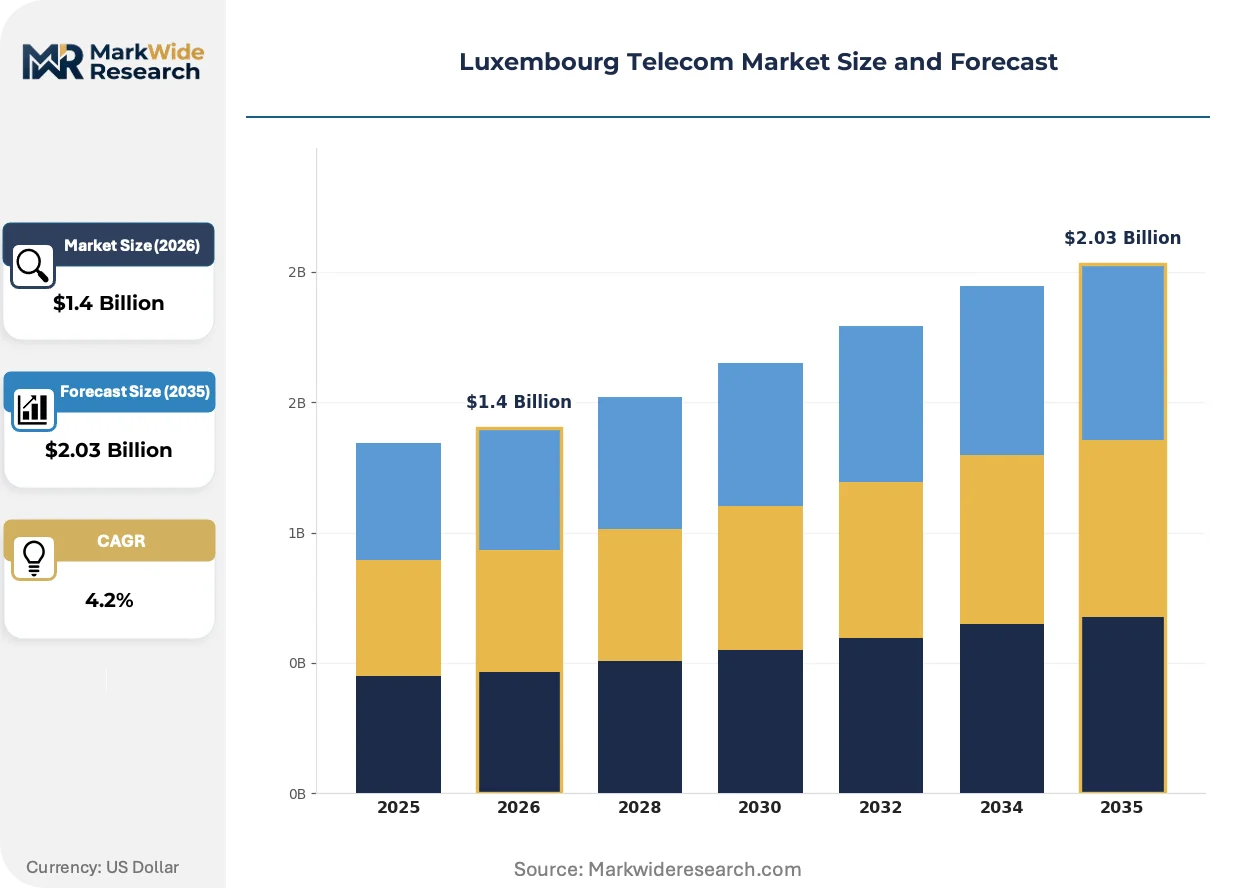
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Internet, VoIP Customer Type: Residential, SME, Large Enterprises, Government Technology: 4G, 5G, Fiber Optics, DSL Pricing Model: Subscription, Prepaid, Postpaid, Bundled Services |
| Companies Covered | Vodafone Luxembourg, Eltrona Luxembourg, POST Luxembourg, Telindus Luxembourg, Luxembourg Online SA, Tango SA, Proximus Luxembourg, SES, Orange Luxembourg, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxembourg Telecom Market Trends and Innovations
Digital infrastructure in Luxembourg is bifurcating between hyperscale-direct connectivity and regulated universal service layers, with satellite and fixed-wireless technologies filling coverage gaps.
Single-mode fiber with coherent optical transmission is rendering obsolete traditional wavelength-division multiplexing equipment in Luxembourg City's data center corridor. Financial trading firms are adopting 400Gbps interfaces at accelerated pace. This compression of transport economics is forcing wholesale carriers to restructure tariff frameworks.
ILR's transposition of the EU Electronic Communications Code imposes wholesale pricing transparency obligations on dominant infrastructure owners. The regulatory consequence is opening dark fiber access to alternative operators. POST Luxembourg's incumbent position faces structural unbundling pressure in enterprise segments.
Enterprise procurement teams are consolidating multi-year connectivity contracts around integrated service level agreements spanning wireline, wireless, and cloud interconnection. Traditional carrier sales channels are losing relevance to direct hyperscale negotiations. This pattern concentrates in Luxembourg City's fund administration and custody banking verticals.
Luxembourg Telecom Market Segmentation
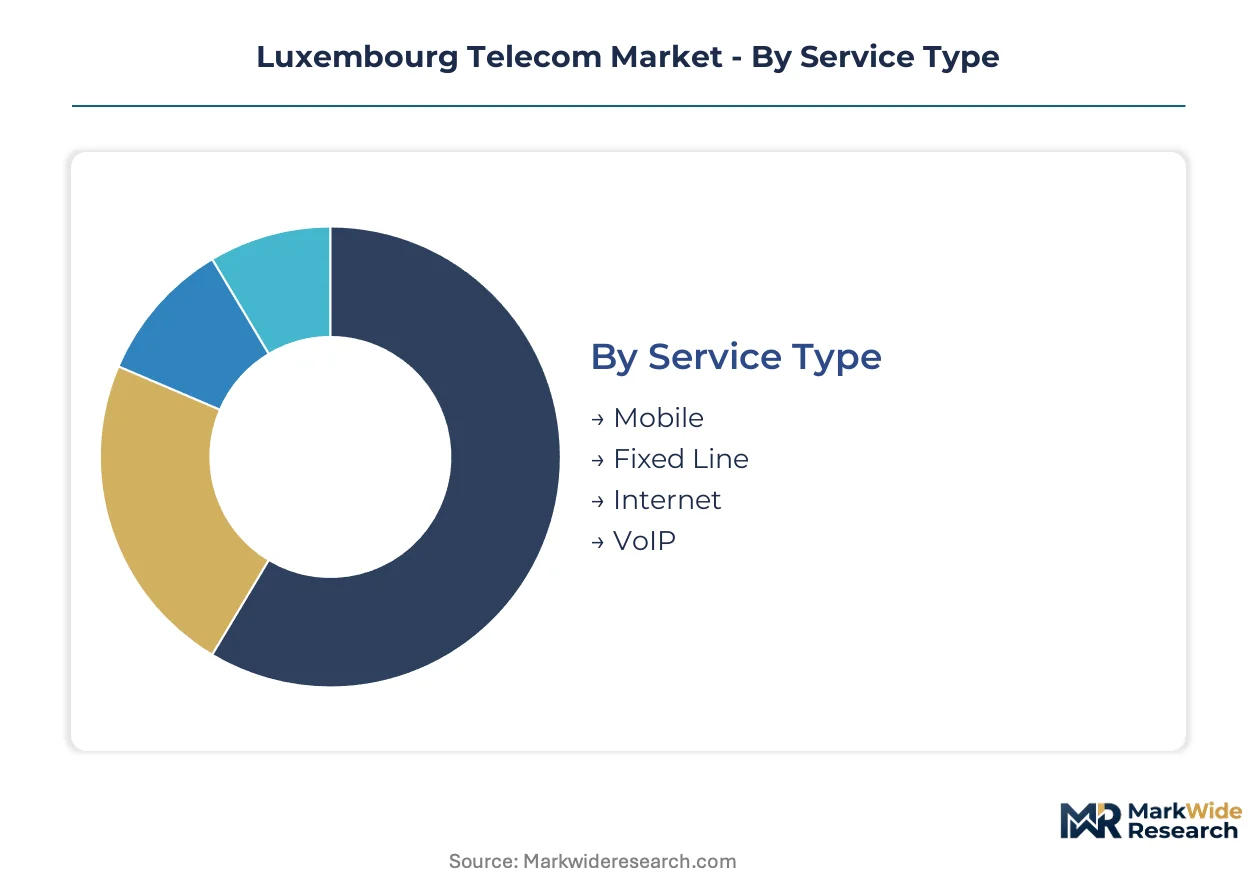
Segmentation reveals how ILR regulatory mandates and hyperscale bypass pressures differentially impact service tiers across Luxembourg's compact geography. Customer concentration in Luxembourg City's financial corridor creates distinct margin profiles by segment.
Service Type:
After-sales service intensity varies sharply across service types, with enterprise fixed-line contracts demanding 24/7 network operations center support while prepaid mobile operates on self-service models.
- Mobile:5G NR sub-6 GHz networks deliver voice and data services across Luxembourg's 2,586 km² territory. Postpaid family plan bundling concentrates demand among residential subscribers in Luxembourg City's southern suburbs, offsetting prepaid erosion through multi-line ARPU expansion.
- Fixed Line:Copper PSTN infrastructure transitions to IP-based voice over fiber backbones. Financial services firms in the Kirchberg district require guaranteed availability through redundant routing, driving premium service tier uptake.
- Internet:GPON fiber-to-the-premises deployments dominate capital allocation under ILR's national broadband plan. Enterprise cloud connectivity demand from fund administration clusters compresses wholesale pricing power.
- VoIP:Session initiation protocol trunking replaces legacy ISDN for SME cost optimization. Adoption concentrates among professional services firms seeking unified communications integration.
Fixed Line holds the largest share; momentum sits with Internet.
Customer Type:
Cost tier differentiation separates sovereign-grade compliance requirements at the top from price-sensitive residential mass market at the base.
- Residential:Household subscribers consume bundled triple-play packages across fiber and 5G fixed-wireless access. Orange Luxembourg's suburban positioning captures segments underserved by fiber economics in peripheral communes.
- SME:Small and medium enterprises procure connectivity through standardized service level agreements with limited customization. Professional services clusters in Esch-sur-Alzette drive regional demand concentration.
- Large Enterprises:Financial institutions mandate sub-10 millisecond latency to Frankfurt with GDPR-aligned data residency. Hyperscale direct fiber builds bypass traditional carrier wholesale layers.
- Government:Sovereign clients require encrypted satellite backhaul from SES for sites beyond terrestrial reach. ILR universal service obligations ensure baseline coverage for administrative facilities in rural northern cantons.
Large Enterprises command premium pricing; SME shows steepest expansion trajectory through digitalization mandates.
Technology:
Application requirements dictate technology selection, with latency-sensitive trading systems demanding fiber while logistics mobility favors 5G.
- 4G:LTE-Advanced networks provide fallback coverage and machine-to-machine connectivity for legacy IoT deployments. Freight operators at Findel Airport maintain 4G dependency for established tracking systems.
- 5G:New radio standalone architecture enables network slicing for enterprise quality-of-service guarantees. Logistics corridors near the cargo hub accelerate adoption for automated warehouse robotics.
- Fiber Optics:Single-mode coherent transmission at 400Gbps interfaces dominates Luxembourg City's data center corridor. ILR gigabit-passive-optical-network coverage targets channel capital deployment.
- DSL:Copper loop infrastructure faces decommissioning cost burdens under universal service obligations. Stranded asset write-downs pressure incumbent operator balance sheets.
Fiber Optics captures dominant investment; 5G is gaining share fastest through enterprise network slicing.
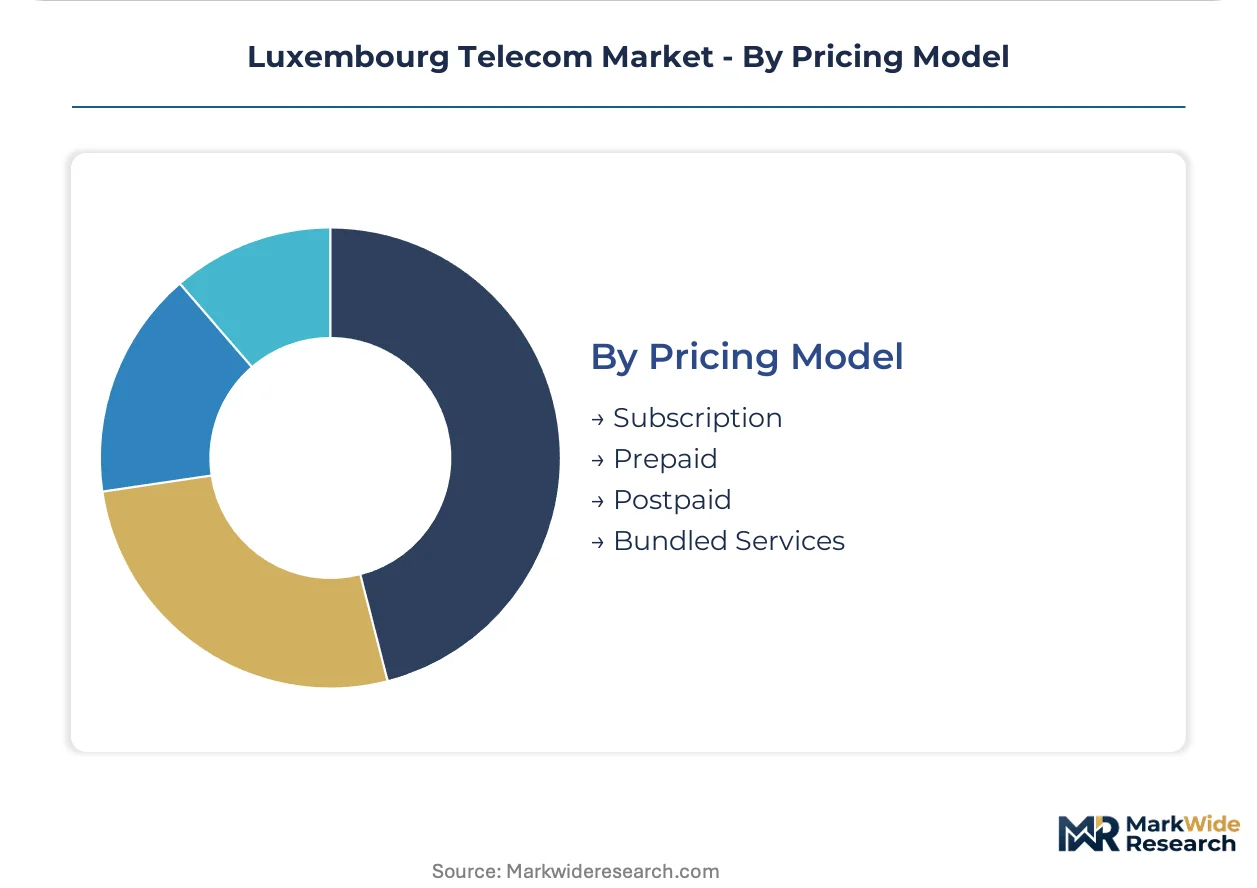
Pricing Model:
Volume concentration in multi-year enterprise contracts shapes pricing model adoption across customer tiers.
- Subscription:Recurring revenue frameworks dominate enterprise procurement with integrated SLA spanning wireline and wireless. Consolidation of connectivity vendors favors bundled subscription structures.
- Prepaid:Pay-as-you-go mobile services erode through postpaid migration. Remaining demand concentrates among temporary residents and cross-border workers.
- Postpaid:Monthly billing with device financing drives family plan bundling. Residential ARPU expansion offsets subscriber acquisition cost pressures.
- Bundled Services:Triple-play and quad-play packages integrate fixed broadband, mobile, television, and VoIP. SME procurement teams favor bundled simplicity over best-of-breed component selection.
Subscription generates largest revenue base; Bundled Services shows strongest momentum through vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Luxembourg's sub-regions. Luxembourg City enterprises absorb premium connectivity costs for regulatory compliance, while peripheral communes drive hard bargains on residential fiber subscriptions.
Luxembourg City and Kirchberg
Financial services firms dominate enterprise demand, mandating sub-10 millisecond latency to Frankfurt. ILR's national broadband plan prioritizes gigabit-passive-optical-network coverage in this corridor. The Kirchberg district anchors sovereign data hosting clusters for fund administration and custody banking.
Southern Suburbs
Postpaid family plan bundling concentrates residential demand among affluent households. Orange Luxembourg targets these zones with aggressive 5G fixed-wireless positioning where fiber economics lag. Esch-sur-Alzette drives SME connectivity procurement through professional services clusters.
Findel Airport Logistics Corridor
Freight operators accelerate 5G adoption for real-time shipment tracking and automated warehouse robotics. ILR spectrum allocation rules shape rollout timelines for sub-6 GHz network slicing. Logistics facilities cluster within 5 kilometers of the cargo hub.
Northern Cantons
Rural administrative facilities rely on ILR universal service obligations for baseline coverage. SES satellite backhaul addresses connectivity gaps beyond terrestrial fiber reach. Copper loop decommissioning costs weigh heavily on incumbent operators serving sparse populations.
Peripheral Communes
Price-sensitive residential segments favor bundled triple-play packages over best-of-breed component selection. Fiber-to-the-premises skill shortages extend deployment timelines relative to ILR targets. 5G fixed-wireless alternatives capture segments underserved by fiber densification economics.
Luxembourg Telecom Market Competitive Landscape
Capability concentration sits with incumbent infrastructure owners; scale advantage sits with multinational operators deploying standardized platforms. POST Luxembourg leverages universal service obligations to sustain wholesale dominance. Orange Luxembourg and Tango SA compete through wireless-centric positioning. Strategic moves center on fiber densification acceleration and 5G fixed-wireless suburban rollout.
Within the incumbent tier, POST Luxembourg occupies the anchor position through legacy infrastructure control. Orange Luxembourg represents the multinational operator archetype with wireless-first market entry. SES exemplifies satellite specialization for institutional backhaul beyond terrestrial reach. These three players collectively illustrate the market's tripartite structure: regulated incumbent, aggressive multinational challenger, and niche technology specialist.
| Leading Market Players |
|---|
| Vodafone Luxembourg |
| Eltrona Luxembourg |
| POST Luxembourg |
| Telindus Luxembourg |
| Luxembourg Online SA |
| Tango SA |
| Proximus Luxembourg |
| SES |
| Orange Luxembourg |
| Others |
Pricing and Supply Chain Analysis
Findel Airport logistics corridor freight operators face divergent connectivity cost structures that concentrate pricing power among fiber infrastructure owners while 5G fixed-wireless alternatives create downstream price differentiation for suburban SMEs. ILR wholesale pricing transparency obligations compress margins for traditional carriers as hyperscale direct builds reshape enterprise procurement economics.
Pricing Analysis
After-sales service revenue from multi-year enterprise network operations center contracts drives lifetime value for incumbent operators. Subscription-based recurring revenue frameworks dominate large enterprise procurement with integrated SLAs spanning wireline and wireless connectivity. Price differentiation stems from latency-grade guarantees and GDPR-aligned data residency certification. Pricing pressure intensifies as hyperscale cloud providers bypass traditional wholesale layers through direct fiber builds. SME segments exhibit highest price sensitivity while financial institutions in Kirchberg absorb premium costs for sovereign-grade compliance.
Supply Chain Analysis
Contract manufacturing concentration for optical transmission equipment rests on specialized vendors in Germany, the Netherlands, and Switzerland holding coherent 400Gbps interface capacity. Network hardware draws from Taiwanese semiconductor foundries, German precision optical component suppliers, and Chinese fiber cable manufacturers. Single-source vulnerability concentrates in coherent DSP chip supply from limited foundry nodes. Distribution runs through POST Luxembourg's incumbent infrastructure with ILR-mandated wholesale access for alternative operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luxembourg Telecom Market fragmentation creates opportunity as enterprise procurement teams consolidate connectivity vendors around integrated service bundles rather than best-of-breed component selection.
For Market Incumbents: Build switching-cost moats through deep fiber densification in Kirchberg financial corridors and captive GPON technician training pipelines. Defend against hyperscale bypass threat by anchoring sovereign data residency compliance services. Prioritize backward integration into dark fiber ownership to preserve wholesale pricing leverage under ILR unbundling pressure. For New Entrants and Emerging Players: Pursue 5G fixed-wireless suburban positioning in peripheral communes where fiber economics lag ILR coverage targets. Target price-sensitive residential segments with aggressive triple-play bundling. Leverage satellite backhaul partnerships with SES for government connectivity gaps beyond terrestrial reach. For Investors and Strategic Acquirers: Niche technology specialists with satellite backhaul institutional relationships and 5G network slicing capabilities offer acquisition appeal. Long-term viability hinges on positioning for post-copper infrastructure transition cycles. Watch ILR spectrum auction timelines and hyperscale capex disclosure patterns as inflection indicators for wholesale pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber Densification Acceleration | POST Luxembourg extends GPON coverage to meet ILR gigabit-passive-optical-network targets in rural northern cantons. |
| 5G Fixed-Wireless Rollout | Orange Luxembourg captures suburban residential and SME segments underserved by fiber economics in peripheral communes. |
| Satellite Backhaul Partnership | SES anchors institutional connectivity for sovereign clients beyond terrestrial fiber reach in remote administrative facilities. |
| Hyperscale Interconnection Facility | Direct cloud provider fiber builds into Luxembourg City compress traditional carrier wholesale enterprise pricing power. |
| GDPR-Aligned Data Residency Certification | CNPD enforcement creates specialized hosting demand from fund administration and custody banking verticals. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with network operations executives at financial institutions, ILR regulatory affairs specialists, procurement leads at logistics operators near Findel Airport, and infrastructure planning directors at incumbent carriers. Secondary validation drew from ILR spectrum auction disclosures, EU Electronic Communications Code transposition documents, SES satellite capacity filings, and hyperscaler capex announcements. Bottom-up service revenue modeling triangulated against top-down national broadband plan investment targets.
Calibration anchored historical growth patterns to observed ILR coverage milestones and enterprise contract renewal cycles across the projection horizon. Segmentation dimensions modeled include service type, customer tier, technology platform, and pricing model structure. CAGRs derived from fiber deployment run-rate analysis and 5G adoption curve benchmarking against comparable European markets. Forecast inputs incorporated ILR wholesale pricing transparency implementation timelines and hyperscale data center expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational cloud providers or accelerated ILR unbundling mandates would shift outcomes beyond modeled ranges. Quarterly review of ILR enforcement actions, hyperscale fiber build permits, and enterprise RFP volume indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
LTE Advanced Pro Market
Telecommunications
South Korea Telecom Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Promotional Sms Market
Telecommunications
5G RAN Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Cambodia Telecom Tower Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Global Premium A2P and P2A Messaging Market
Telecommunications
Austria Telecom Market
Telecommunications
Poland Telecom Market
Telecommunications
Global SS7 Market
Telecommunications
Managed Mobility Services (MMS) Market