
 Machine to Machine (M2M) Services Market | 2026-2036
Machine to Machine (M2M) Services Market Size, Share, and Industry Trends Forecast 2026-2036
Machine to Machine (M2M) Services Market Foresight
Automotive telematics is shifting from aftermarket installations to factory-embedded M2M architectures. AT&T leverages its nationwide LTE-M and NB-IoT footprint to anchor connected vehicle contracts with major OEMs. Deutsche Telekom competes through its European cross-border SIM provisioning and GDPR-compliant data routing infrastructure.
Machine to Machine services encompass automated data exchange between networked devices without human intervention, typically operating over cellular, Wi-Fi, Bluetooth, Zigbee, or proprietary low-power wide-area protocols with latency tolerances from milliseconds to hours depending on application criticality. These services enable remote asset monitoring, predictive maintenance triggers, and supply chain automation across industrial and commercial environments. Connectivity Management dominates current revenue pools due to recurring carrier subscription models, while Application Enablement captures expanding margin as enterprises demand pre-integrated analytics dashboards and API layers. Cellular technology leads deployment scale for wide-area mobility use cases, though Zigbee sustains niche strength in building automation and smart metering where mesh topology and sub-gigahertz penetration matter.
The FCC governs spectrum allocation and device certification for M2M deployments in the United States, directly shaping module design and carrier certification timelines. ETSI and the European Commission's Cyber Resilience Act impose hardware and firmware security standards that vendors must satisfy for CE marking and market access across EU member states. Stakeholders must weigh spectrum licensing costs against private network deployment economics as enterprise buyers demand lower latency and data sovereignty controls.
Market Dynamics
Cellular module manufacturers face margin compression as automotive OEMs consolidate supplier rosters and demand firmware-integrated security stacks that comply with ETSI cybersecurity mandates.
Growth Catalysts
- EU Cyber Resilience Act:Mandated hardware security certifications for connected devices are accelerating replacement cycles across industrial automation fleets in Germany and France.
- Predictive maintenance protocols:Manufacturing facilities in Japan and South Korea are embedding vibration sensors with NB-IoT backhaul to trigger automated work orders before equipment failure.
- FCC spectrum releases:Newly allocated 3.5 GHz CBRS bands enable private LTE deployments for mining operations requiring sub-50 millisecond latency without carrier dependency.
Market Restraints
- Semiconductor supply concentration:Baseband processor fabrication relies heavily on Taiwan-based foundries, creating vulnerability to geopolitical disruption and allocation rationing.
- RoHS compliance costs:Lead-free solder alternatives for M2M modules increase material expenses and thermal management complexity for high-temperature automotive applications.
- Wi-Fi 6/7 substitution:Localized high-bandwidth applications in smart buildings increasingly bypass cellular subscriptions in favor of unlicensed spectrum with lower recurring costs.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for telecom equipment manufacturing are drawing module assembly capacity away from traditional East Asian hubs.
- Edge-AI convergence:On-device inference chips combined with low-power cellular modems enable real-time anomaly detection without cloud round-trips for oil pipeline monitoring.
- Brazil smart grid mandates:ANEEL regulations require automated meter reading infrastructure, creating demand for LPWAN-enabled electricity distribution networks.
Industry Challenges
- Embedded systems talent scarcity:Firmware engineers with cellular protocol stack expertise command premium compensation, stretching R&D budgets at mid-tier module vendors.
- PTCRB certification timelines:North American carrier approval processes extend product launch windows by four to six months, delaying revenue recognition for seasonal industrial deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine to Machine (M2M) Services Market |
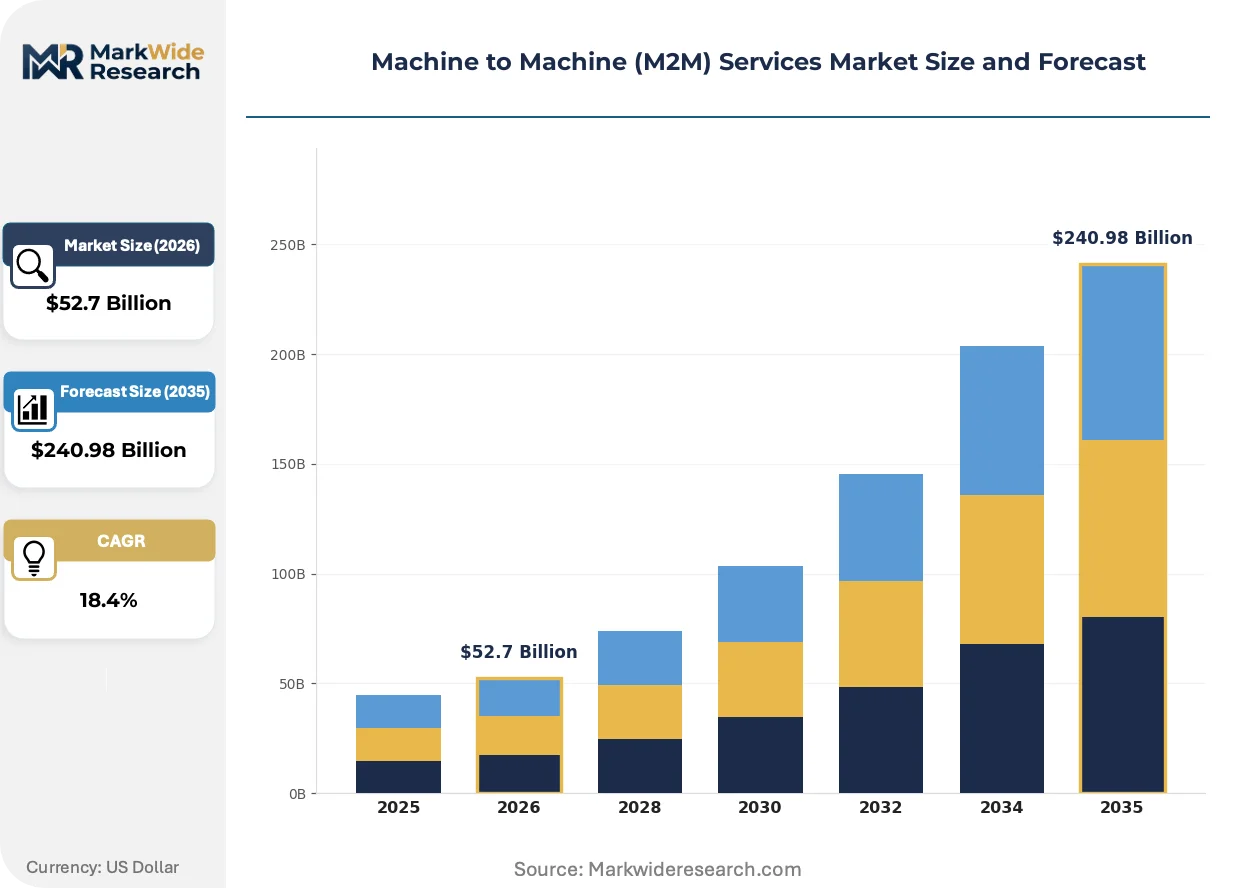
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $240.98 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Connectivity Management, Device Management, Application Enablement, Remote Monitoring Technology: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Manufacturing, Healthcare, Transportation, Retail Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | AT&T, Vodafone Group, Verizon Communications, Cisco Systems, Intel Corporation, Deutsche Telekom, Huawei Technologies, Orange, KORE Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine to Machine (M2M) Services Market Shifts & Advancements
Module vendors are racing to integrate satellite backup connectivity as enterprise buyers demand uninterrupted telemetry from remote assets beyond terrestrial cellular reach.
iSIM technology is rewriting how connectivity credentials are provisioned. Automotive OEMs in Germany and Japan are eliminating physical SIM trays entirely, soldering authentication directly onto system-on-chip architectures. This compression of hardware layers reduces bill-of-materials costs while complicating carrier switching logistics for fleet operators.
ETSI's harmonized standards for cybersecurity certification are forcing firmware architecture redesigns across European deployments. Industrial gateway manufacturers must now demonstrate secure boot chains and encrypted over-the-air update mechanisms before CE marking approval. German automotive suppliers are responding by establishing dedicated security operations centers to monitor certificate lifecycles across installed device populations.
Enterprise buyers are consolidating connectivity procurement under single-platform contracts rather than managing disparate carrier relationships. Manufacturing conglomerates in the United States and South Korea now demand API-unified dashboards spanning multiple national networks, displacing the traditional model of regional SIM swapping. This pattern concentrates purchasing power with carriers offering cross-border roaming agreements and centralized billing infrastructure.
Machine to Machine (M2M) Services Market Segmentation
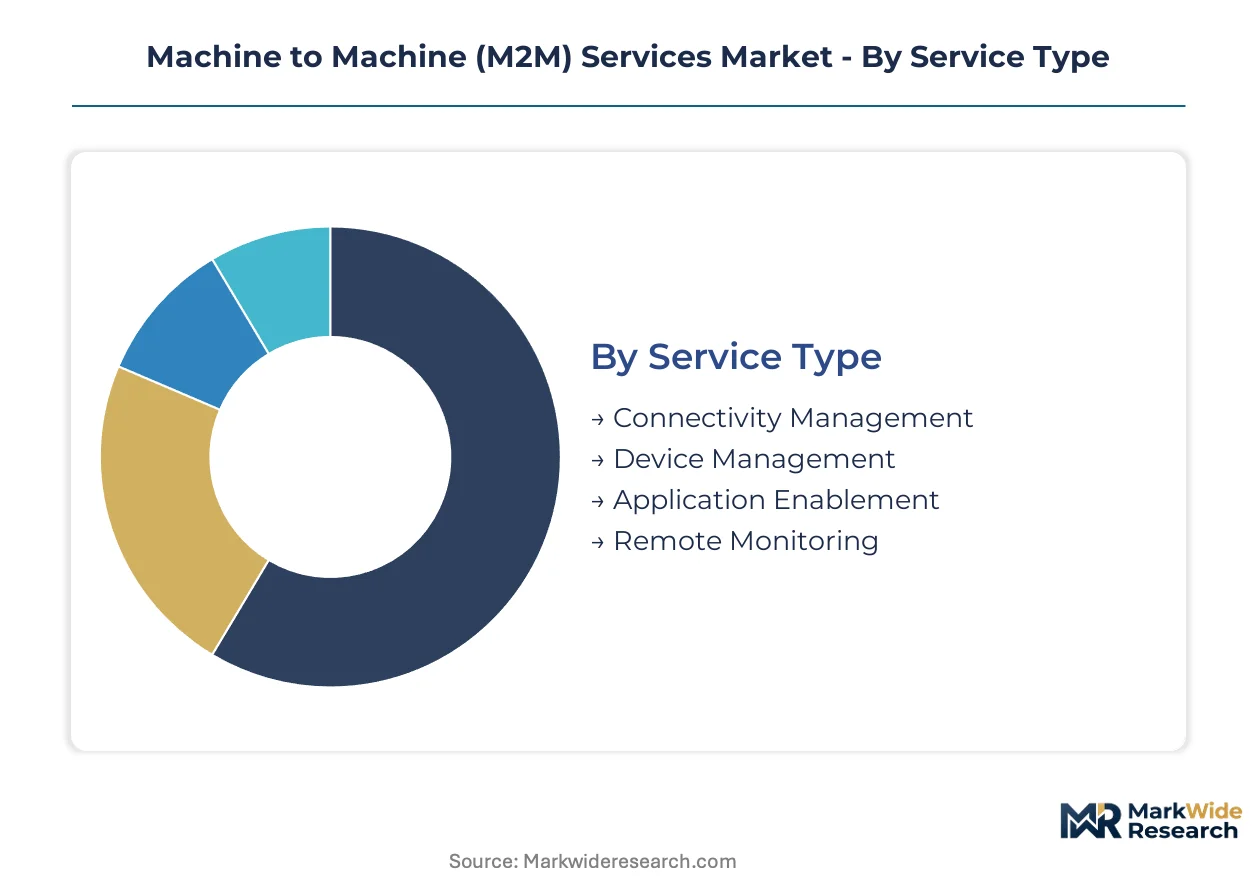
M2M services fragment across four distinct dimensions that determine procurement patterns and vendor positioning. Service type dictates recurring revenue structures while technology choice locks in hardware lifecycles and carrier dependencies. End user verticals impose divergent latency and compliance requirements. Deployment models reflect enterprise data sovereignty preferences.
Service Type:
Supply concentrates with carriers monetizing recurring subscription models rather than one-time software licenses.
- Connectivity Management:Platforms provision SIM lifecycle management, rate plan optimization, and cross-border roaming orchestration. German automotive OEMs embed these services for predictive maintenance telemetry requiring guaranteed SLA uptime across supplier networks. Roaming complexity and GDPR-compliant data routing drive carrier consolidation in this tier.
- Application Enablement:Middleware layers deliver pre-integrated analytics dashboards, API gateways, and device abstraction protocols. Manufacturing facilities in Japan demand these stacks to normalize heterogeneous sensor feeds without custom firmware development. Margin expansion here outpaces raw connectivity as enterprises prioritize time-to-deployment over infrastructure buildout.
- Device Management:Firmware over-the-air update orchestration, certificate lifecycle management, and remote diagnostic tooling. ETSI cybersecurity mandates are accelerating replacement of legacy provisioning systems.
- Remote Monitoring:Asset telemetry aggregation with threshold-based alerting and automated escalation workflows. Oil pipeline operators deploy these for leak detection across geographically dispersed infrastructure.
Connectivity Management absorbs the bulk of installed capacity; Application Enablement is expanding most quickly.
Technology:
Cost tier stratification separates licensed spectrum deployments from unlicensed alternatives with divergent certification burdens.
- Cellular:Licensed spectrum protocols spanning 2G through 5G with carrier-managed QoS guarantees. Fleet management operators in the United States anchor contracts on LTE-M and NB-IoT footprints for nationwide mobility coverage. FCC spectrum releases including 3.5 GHz CBRS enable private LTE alternatives for latency-critical mining operations.
- Zigbee:Mesh-topology protocol operating in sub-gigahertz and 2.4 GHz bands with self-healing network characteristics. Smart metering deployments in Germany leverage this for building penetration where cellular signals attenuate. Sub-meter installation density favors mesh economics over per-device cellular subscription costs.
- Wi-Fi:Unlicensed spectrum with high throughput for localized data aggregation. Smart building retrofits increasingly bypass cellular for indoor asset tracking.
- Bluetooth:Low-energy variants for proximity-based device pairing and short-range sensor networks. Healthcare wearables exploit this for patient monitoring with smartphone tethering.
Cellular dominates wide-area mobility applications; Zigbee sustains installed base in building automation.
End User:
Application maturity varies sharply across verticals with divergent regulatory exposure and integration complexity.
- Transportation:Telematics platforms for fleet optimization, driver behavior scoring, and regulatory compliance logging. OEM embedded architectures are displacing aftermarket installations as factory M2M modules become standard. Predictive maintenance triggers and over-the-air software updates concentrate demand in Germany and Japan.
- Healthcare:Remote patient monitoring with HIPAA-compliant data transmission and FDA-cleared device integration. Chronic disease management programs drive recurring connectivity subscriptions with stringent uptime requirements.
- Manufacturing:Vibration sensors with NB-IoT backhaul triggering automated work orders before equipment failure. Japanese and South Korean facilities lead deployment density.
- Retail:Cold chain monitoring, inventory tracking, and customer proximity engagement. Margin pressure favors unlicensed spectrum for in-store deployments.
Transportation commands premium pricing for mobility-grade SLAs; Healthcare is climbing the fastest on regulatory tailwinds.
Deployment Model:
Customer type segmentation separates hyperscale cloud consumers from sovereignty-conscious enterprise buyers.
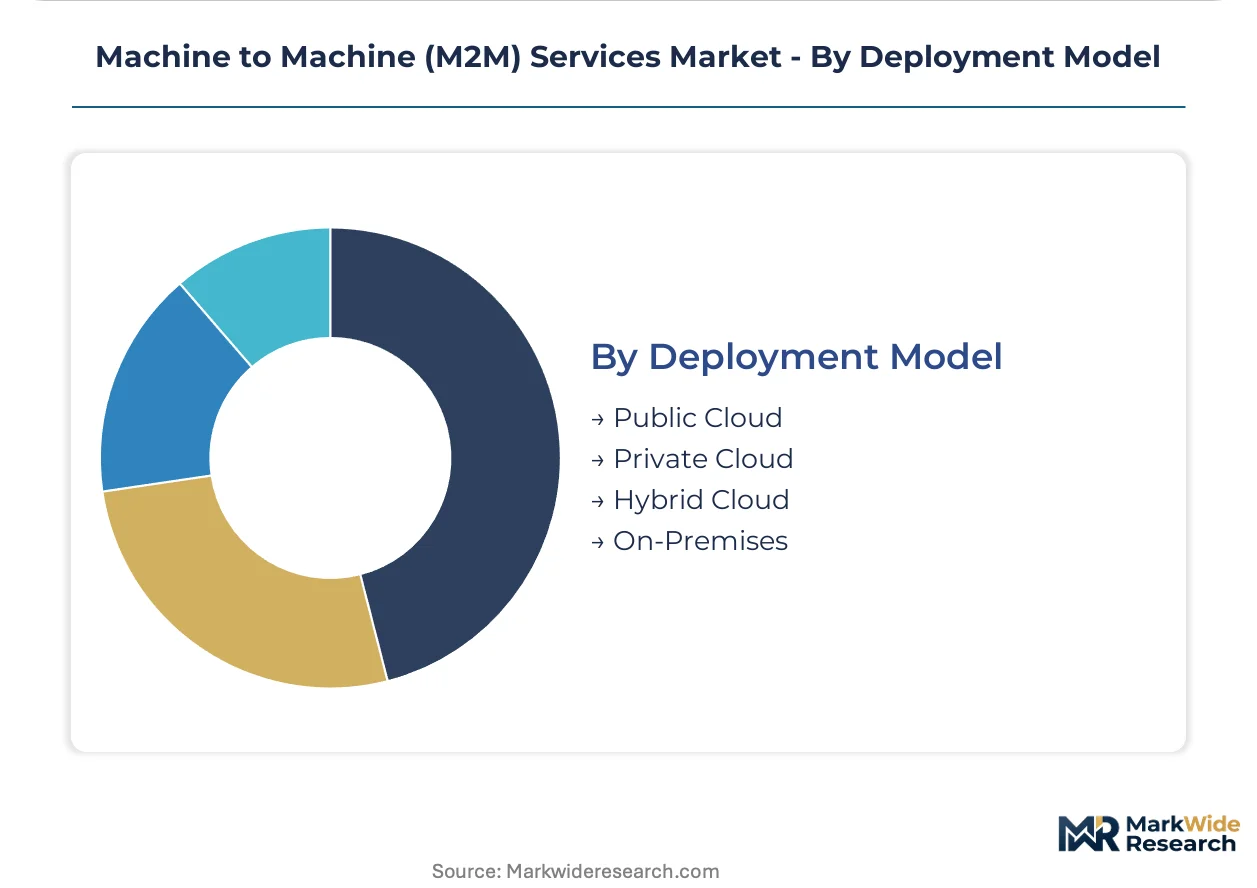
- Public Cloud:Multi-tenant infrastructure with elastic scaling and consumption-based pricing. Mid-market manufacturers without dedicated IT operations default here for fastest deployment.
- Private Cloud:Single-tenant environments with dedicated compute and network isolation. German automotive suppliers mandate this for GDPR-compliant data residency.
- Hybrid Cloud:Workload portability across on-premises and cloud infrastructure with unified orchestration. Enterprises with legacy SCADA investments use this for gradual migration.
- On-Premises:Fully captive infrastructure with no third-party data transit. Critical infrastructure operators in energy and defense sectors require this for air-gapped security postures.
Public Cloud captures volume from price-sensitive adopters; Private Cloud is gaining share fastest on data sovereignty mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production-Linked Incentive scheme for telecom equipment is drawing module assembly capacity toward South Asian manufacturing zones. Special economic zones in Gujarat and Tamil Nadu now host cellular modem production lines serving automotive and industrial automation demand.
United States
Fleet management operators anchor nationwide LTE-M contracts for telematics coverage. The FCC governs spectrum allocation and device certification timelines through PTCRB processes that extend product launches. Detroit-Warren-Dearborn automotive clusters embed factory M2M architectures for predictive maintenance and over-the-air software updates.
Germany
Automotive OEMs demand GDPR-compliant data routing infrastructure for embedded connectivity modules. ETSI cybersecurity mandates and the EU Cyber Resilience Act impose hardware security certifications requiring secure boot chains. Stuttgart and Munich manufacturing corridors concentrate supplier development for vibration-sensor telemetry and automated work order systems.
China
Industrial gateway manufacturers face margin compression from consolidated automotive supplier rosters. MIIT governs module design standards and spectrum licensing for private LTE deployments. Shenzhen and Dongguan electronics corridors host baseband processor integration and firmware security stack development for export markets.
Japan
Manufacturing facilities embed NB-IoT vibration sensors triggering predictive maintenance protocols before equipment failure. METI oversees industrial IoT standardization and edge-AI convergence programs. Nagoya and Osaka industrial zones lead deployment density for automated telemetry in automotive component supply chains.
Brazil
ANEEL regulations mandate automated meter reading infrastructure across electricity distribution networks. The national regulator requires LPWAN-enabled smart grid deployments with guaranteed SLA uptime. São Paulo industrial corridors concentrate system integrators serving utility-scale connectivity procurement.
Machine to Machine (M2M) Services Market Competitive Landscape
Top-tier vendors anchor carrier-grade connectivity platforms, while mid-tier module manufacturers compete on firmware integration speed. The vendor base stratifies across three tiers: multinational carriers with cross-border roaming infrastructure, specialized connectivity management platforms, and regional system integrators. Two strategic archetypes dominate: carrier-anchored full-stack providers and pure-play connectivity aggregators. Competitive moves concentrate on strategic partnerships with automotive OEMs and vertical integration into secure boot chain development.
Within the carrier-anchored tier, AT&T and Verizon Communications occupy positions exemplifying nationwide LTE-M and NB-IoT footprint strategies. Deutsche Telekom AG represents European cross-border SIM provisioning capabilities. Among connectivity aggregators, KORE Wireless sits within the specialized tier serving industrial automation demand. Vodafone Group and Orange anchor multinational roaming architectures spanning automotive and fleet management verticals.
| Leading Market Players |
|---|
| AT&T |
| Vodafone Group |
| Verizon Communications |
| Cisco Systems |
| Intel Corporation |
| Deutsche Telekom |
| Huawei Technologies |
| Orange |
| KORE Wireless |
| Others |
Supply & Pricing Matrix
EU Cyber Resilience Act certification gates qualified supply for premium-tier M2M modules, restricting factory-embedded architectures to vendors with secure boot chain capabilities while spot-market inventory without ETSI compliance trades at structural discounts. RoHS lead-free solder mandates compound material costs for automotive-grade thermal management, compressing margins at mid-tier manufacturers.
Pricing Analysis
Lead-time-driven pricing stratification rewards cellular module vendors with PTCRB pre-certification inventory, commanding premium positioning against spot-market alternatives facing four-to-six-month carrier approval delays. Three-tier pricing structure across premium, standard, and economy levels separates ETSI-certified secure boot modules from baseline connectivity hardware and uncertified spot inventory. Price differentiation hinges on firmware-integrated security stack depth and cross-border roaming SLA guarantees. Pricing pressure stems from automotive OEM supplier roster consolidation, with German and Japanese fleet operators squeezing contract margins. Mid-tier module vendors without carrier-anchored relationships exhibit highest price sensitivity, while tier-one carriers with nationwide LTE-M footprints maintain pricing power.
Supply Chain Analysis
Baseband processor fabrication rests on Taiwan-based foundries, with South Korean memory suppliers and Chinese module assembly operations completing the hardware stack. Silicon wafer supply draws from Japanese specialty chemical producers, while sub-6 GHz RF front-end components source from US and European semiconductor houses. Single-source vulnerability concentrates in advanced node lithography, where geopolitical disruption risks allocation rationing across automotive telematics programs. Distribution runs through carrier-direct procurement for fleet-scale deployments, with industrial automation buyers consolidating under API-unified platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into secure boot chain development and firmware security operations represents the defining competitive race, with automotive OEMs demanding captive certificate lifecycle management capabilities.
For Market Incumbents: Anchor cross-border roaming infrastructure through centralized billing platforms that neutralize pure-play connectivity aggregators. Fortify carrier-grade SLAs against private LTE substitution enabled by FCC 3.5 GHz CBRS releases. Deepen in-house production of ETSI-compliant secure boot firmware to preempt regulatory displacement of legacy provisioning systems. For New Entrants and Emerging Players: Mid-market manufacturers without dedicated IT operations present the most penetrable buyer archetype for API-unified connectivity dashboards. Brazil's ANEEL-mandated smart grid deployments and India's PLI-subsidized module assembly zones offer geographic white-space with lower incumbent saturation. Lead with consumption-based pricing against carrier-anchored subscription models to bypass established roaming infrastructure moats. For Investors and Strategic Acquirers: KORE Wireless pursuing satellite backup connectivity partnerships is the leading indicator that uninterrupted telemetry from remote assets is becoming table stakes for industrial automation contracts. Long-term viability favors carriers with multi-orbit connectivity integration and edge-AI modem convergence capabilities. Watch for iSIM technology adoption inflections among German and Japanese automotive OEMs as signal of hardware layer compression maturity.| Strategic Initiative | Industry Significance |
|---|---|
| iSIM Technology Integration | Eliminates physical SIM trays for German automotive OEMs, reducing bill-of-materials costs while complicating carrier switching. |
| Satellite Backup Connectivity | Addresses telemetry gaps beyond terrestrial cellular reach for oil pipeline and mining operations. |
| Edge-AI Modem Convergence | Enables real-time anomaly detection without cloud round-trips for Japanese manufacturing vibration sensors. |
| Private LTE Deployment | Leverages FCC 3.5 GHz CBRS for sub-50 millisecond latency in US mining operations without carrier dependency. |
| Security Operations Center Buildout | Monitors certificate lifecycles across installed device populations to satisfy ETSI cybersecurity mandates. |
Research Methodology
Document review covered carrier tariff filings, FCC spectrum allocation dockets, ETSI cybersecurity standards, and automotive OEM supplier contracts, complemented by interviews with cellular module procurement directors, fleet telematics operations managers, industrial gateway firmware engineers, and connectivity platform product leads. Secondary validation drew from SEC 10-K disclosures, PTCRB certification databases, and EU Cyber Resilience Act implementation guidance. Bottom-up module shipment estimates triangulated against top-down carrier subscription revenue across the analysis window.
Historical connectivity adoption curves were cross-referenced against panel input from carrier wholesale pricing strategists to derive segment-specific expansion rates. The analytical framework modeled service type, technology protocol, end-use vertical, and deployment model dimensions throughout the forecast period. CAGRs were derived from regression analysis of embedded M2M penetration rates in automotive production and NB-IoT sensor deployment density in Japanese manufacturing facilities.
Revisions become necessary when FCC spectrum reallocation, ETSI cybersecurity standard updates, or Taiwan foundry allocation disruptions materialize. Forecasts reflect assumptions regarding carrier roaming agreement stability and automotive OEM supplier roster consolidation trajectories. A small set of named triggers—geopolitical semiconductor supply constraints, EU hardware security certification timeline shifts, and Wi-Fi 6/7 substitution acceleration in smart building retrofits—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
MENA Mobile Virtual Network Operator Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Mexico Telecom Market
Telecommunications
Mobile Value-Added Services (MVAS) Market
Telecommunications
Global Underwater Acoustic Communication Market
Telecommunications
Argentina ICT Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Global SS7 Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Voip Phone Market
Telecommunications
Global Relay Market
Telecommunications
Iceland Telecom Market
Telecommunications
5G Core Market
Telecommunications
Global 4G LTE Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Telecom Expense Management Market