
 Global Telecom Order Management Market | 2026-2036
Global Telecom Order Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecom Order Management Market Intelligence
Expertise in legacy, monolithic order management systems is unwinding as telecom operators prioritize agile, cloud-native skill sets. This shift benefits software-centric vendors over traditional network equipment providers. Oracle leverages its deep enterprise cloud and database expertise to offer integrated solutions. Amdocs sustains its market position through its extensive portfolio for service provider operations, while Ericsson competes by embedding order management within its broader 5G network and digital transformation offerings.
Telecom order management encompasses the software and processes used to handle a customer order's complete lifecycle, from initial capture through fulfillment, activation, and billing. These systems orchestrate complex workflows across network and IT domains, often utilizing TM Forum Open APIs to ensure interoperability and service automation. Cloud-based deployments are rapidly displacing legacy on-premise systems due to superior scalability and lower total cost of ownership. Within solution offerings, order orchestration remains the central function, while Mobile Network Operators represent the largest and most demanding customer type.
Regulatory frameworks create critical system requirements for telecom order management platforms. In the United States, FCC mandates for number portability and service quality directly influence system design. Similarly, compliance with data privacy rules like Europe's GDPR and service delivery standards set by India's TRAI necessitates specific functionalities for handling customer information and order records. The key strategic decision for operators is whether to adopt pre-integrated suites or pursue a more flexible, multi-vendor architecture built on microservices.
Market Dynamics
The central force shaping the market is the architectural decomposition of monolithic systems into cloud-native microservices. This shift is a direct response to the complexity of 5G service bundles and the need for agile, automated service fulfillment processes.
Growth Catalysts
- 5G Network Slicing:The commercialization of 5G enables network slicing, which requires dynamic, on-demand order management capabilities to create, modify, and monetize tailored network services for enterprise customers in sectors like logistics and smart manufacturing.
- Enterprise IoT Deployments:Large-scale Internet of Things projects necessitate sophisticated order management to handle the activation, provisioning, and lifecycle management of thousands or millions of connected devices, driving system upgrades.
- Cloud-Native Adoption:Telecom operators are migrating from on-premise solutions to cloud-native platforms to achieve greater scalability, reduce total cost of ownership, and accelerate time-to-market for new digital services.
Market Restraints
- Legacy System Integration Costs:The high expense and complexity of integrating modern order management platforms with entrenched, legacy BSS and OSS environments represent a significant barrier for many established telecom operators.
- Interoperability Deficiencies:In multi-vendor environments, a lack of standardized API adoption across all components can lead to friction, custom integration work, and failures in automated, end-to-end service orchestration.
- Data Sovereignty Rules:Regulations like Europe's GDPR impose strict data residency and privacy requirements, complicating the architecture of global or multi-regional cloud-based order management deployments for multinational operators.
Strategic Opportunities
- AI-Powered Automation:Integrating artificial intelligence and machine learning offers a significant opportunity to develop predictive analytics for order fallout, enabling proactive issue resolution and moving toward zero-touch orchestration.
- B2B2X Service Enablement:There is a growing opportunity in creating platforms that manage complex B2B2X service chains, allowing telecom operators to act as enablers for other industries to bundle connectivity with their own offerings.
- Emerging Market Leapfrogging:Operators in developing regions of Southeast Asia and Africa can bypass legacy systems entirely, adopting lightweight, SaaS-based order management solutions to quickly launch new digital services.
Industry Challenges
- Cloud-Native Skills Gap:A scarcity of developers and architects possessing deep expertise in both telecom processes and modern technologies like microservices, Kubernetes, and CI/CD pipelines constrains implementation timelines.
- Complex Migration Paths:Decommissioning deeply embedded legacy order management systems without disrupting active customer services or billing cycles is an extremely high-risk and technically demanding operational challenge.
- API Standardization Pace:The full benefits of a modular, best-of-breed architecture depend on widespread adoption of TM Forum Open APIs, but progress toward universal implementation across all vendors and operators remains uneven.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecom Order Management Market |
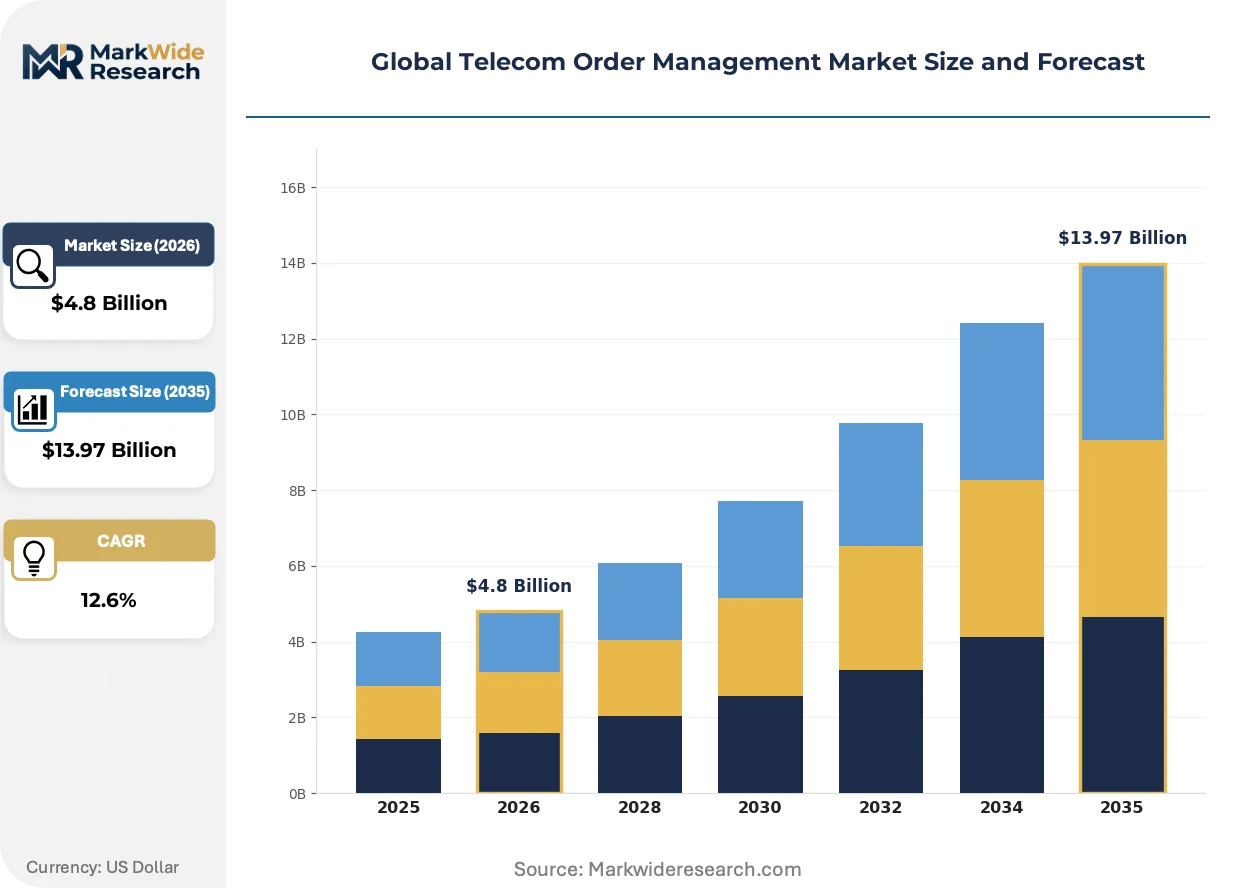
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Offering: Order Orchestration, Service Fulfillment, Billing Integration, Activation Management, Trouble Ticketing Use Case: Subscription Management, Customer Self-Service, Order Tracking, Inventory Management, CRM Integration Customer Type: Mobile Network Operators, Internet Service Providers, Satellite Operators, Wholesale Carriers |
| Companies Covered | Amdocs, Oracle, Ericsson, IBM, Cognizant, Pegasystems, SAP, Nokia, Netcracker Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecom Order Management Market Strategic Shifts & Innovations
The market is shifting from static, workflow-driven processing to intelligent, intent-based orchestration. This evolution is driven by the need for zero-touch automation to manage the volume and complexity of next-generation digital services without increasing operational headcount.
AI-driven order orchestration platforms automate complex fulfillment workflows for new digital services. Mobile Network Operators are the primary adopters, seeking to reduce operational expenditures and accelerate time-to-revenue for 5G and IoT offerings. This technological shift is bifurcating the market between operators leveraging intelligent automation and those still reliant on manual, step-by-step processes that are prone to error.
Regulations from the United States' FCC, especially mandates governing Local Number Portability, impose strict, time-sensitive process requirements on service providers. These rules compel order management systems to automate the intricate, multi-carrier communications required to transfer a customer's phone number seamlessly. The mobile virtual network operator (MVNO) segment is most impacted, as its business model depends on efficient, compliant integration with host carrier systems.
Enterprise customers are increasingly demanding dynamic, on-demand service configuration through APIs rather than purchasing static, pre-defined product bundles. This behavioral change disrupts the traditional product catalog-driven sales model, favoring systems that support real-time service composition and quoting. This trend is most prominent within the SD-WAN and private network markets across North America and Europe, where flexible consumption is a key differentiator.
Global Telecom Order Management Market Segmentation
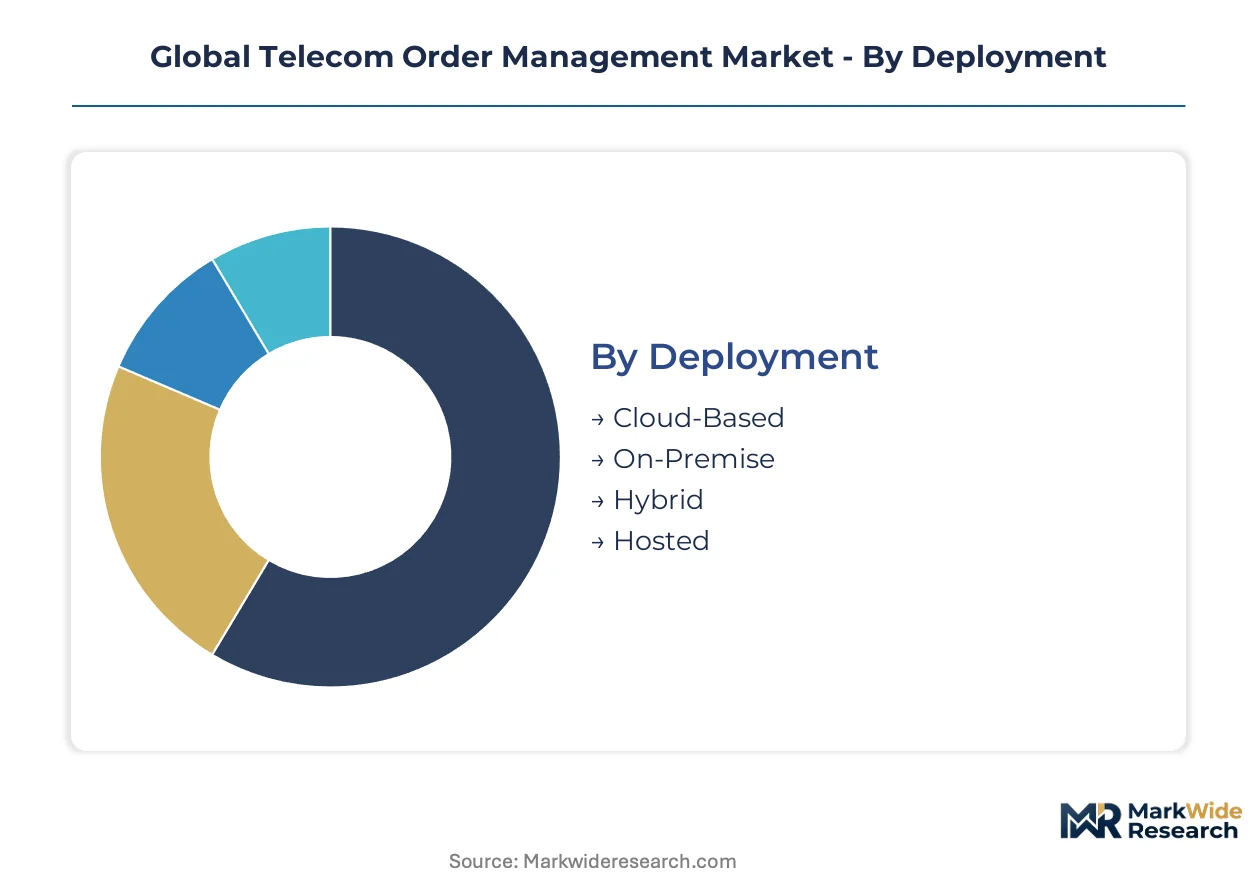
The global telecom order management market categorizes based on deployment models, solution offerings, use cases, and customer types. Analyzing these segments provides critical insights into the architectural preferences, functional demands, and strategic priorities driving investment across the telecommunications industry. This granular view helps operators and vendors identify areas of concentrated growth and specific operational requirements.
Deployment:
The market's deployment segment exhibits varied adoption patterns across different geographies, influenced by regulatory environments and existing infrastructure maturity.
- Cloud-Based:Cloud-Based deployments utilize shared virtualized resources hosted by third-party providers, offering superior scalability and operational flexibility. Demand concentrates in South Korea and the United States, where operators actively pursue agile service delivery for 5G and enterprise IoT.
- On-Premise:On-Premise solutions involve software and hardware installed and managed directly within the operator's own data centers, providing maximum control and data sovereignty. Established operators in Germany and France still maintain significant on-premise infrastructure due to stringent data privacy regulations like GDPR.
- Hybrid:Hybrid models combine on-premise systems with cloud components, enabling a phased migration strategy for complex legacy environments.
- Hosted:Hosted deployments involve third-party management of dedicated infrastructure, offering a middle ground between on-premise control and cloud scalability.
On-Premise commands the established base. The steepest expansion runs through Cloud-Based.
Solution Offering:
Solution offerings cater to distinct operational requirements within the order lifecycle, with varying degrees of complexity and integration needs for different customer types.
- Order Orchestration:Order Orchestration platforms manage the end-to-end workflow of a customer order, coordinating tasks across multiple network and IT systems. Mobile Network Operators frequently prioritize these solutions to automate complex 5G service provisioning and accelerate time-to-market.
- Service Fulfillment:Service Fulfillment systems ensure the accurate and timely delivery of ordered services, including activation, provisioning, and resource allocation. Internet Service Providers demand robust fulfillment capabilities to manage high volumes of broadband and voice service activations efficiently.
- Billing Integration:Billing Integration modules link order data with financial systems, ensuring accurate customer invoicing and revenue recognition.
- Activation Management:Activation Management focuses on the technical setup and activation of services on the network, often using TM Forum Open APIs.
- Trouble Ticketing:Trouble Ticketing systems handle customer service issues and fault resolution, integrating with order data for comprehensive support.
Order Orchestration forms the core of modern systems. Service Fulfillment solutions are climbing the fastest.
Use Case:
The various use cases reflect evolving customer expectations and operational priorities, with some applications driving significant transactional volume.
- Subscription Management:Subscription Management systems handle the entire lifecycle of recurring services, from initial signup to upgrades, downgrades, and cancellations. Enterprise customers in North America leverage these systems for flexible consumption of SD-WAN and private network services.
- Customer Self-Service:Customer Self-Service tools empower users to manage their orders, services, and accounts independently, reducing operational costs for operators. Mobile Network Operators in India deploy extensive self-service portals to handle large customer bases and reduce call center load.
- Order Tracking:Order Tracking provides real-time visibility into the status of a customer's order, enhancing transparency and customer satisfaction.
- Inventory Management:Inventory Management integrates with order systems to track and allocate network resources and physical assets for service delivery.
- CRM Integration:CRM Integration connects order management with customer relationship management platforms for a unified customer view.
Subscription Management drives new revenue models. Customer Self-Service systems are gaining share fastest.
Customer Type:
Different customer types exhibit distinct demands for order management capabilities, often dictated by their network complexity and service portfolios.
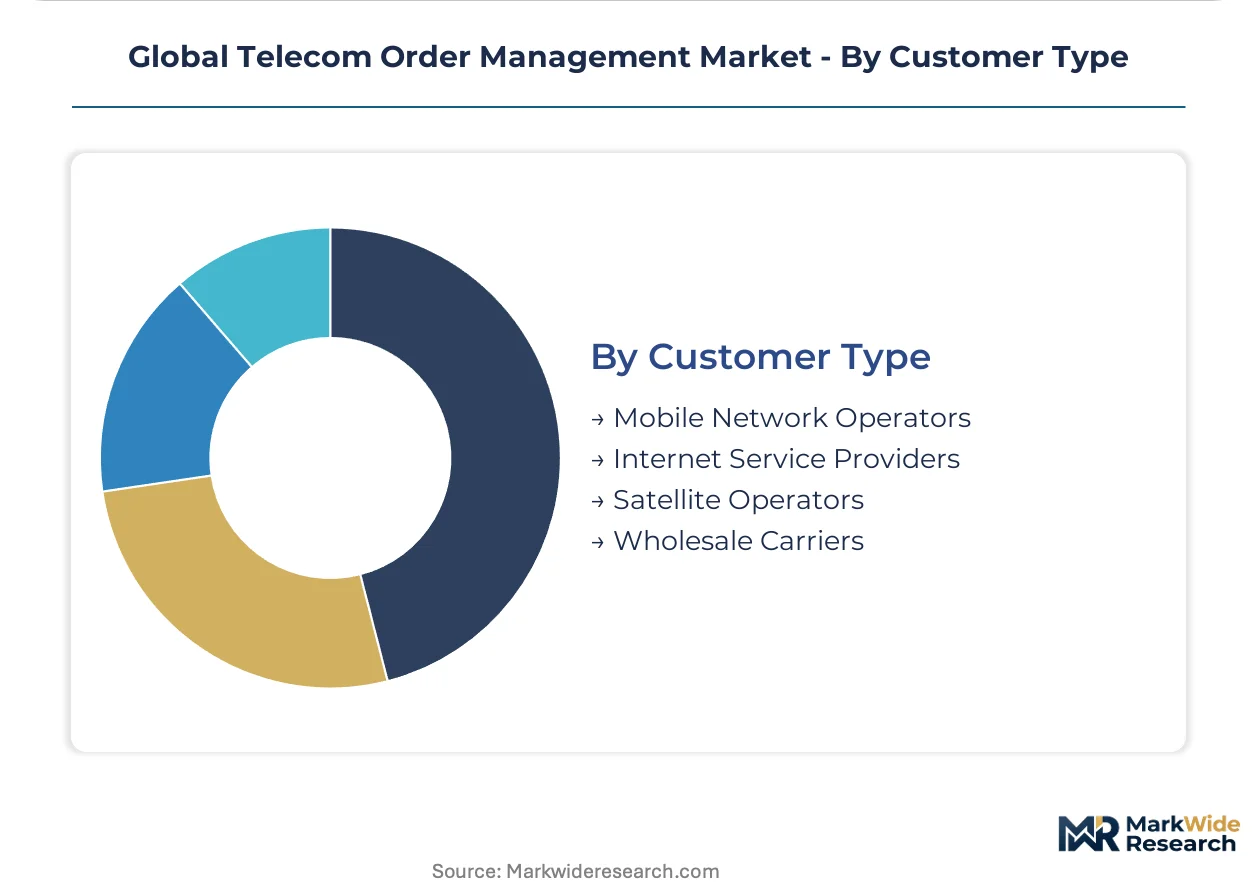
- Mobile Network Operators:Mobile Network Operators (MNOs) require sophisticated order management to handle complex 5G service bundles, network slicing, and enterprise IoT deployments. These operators in South Korea lead adoption due to advanced 5G network commercialization.
- Internet Service Providers:Internet Service Providers (ISPs) need robust systems to manage high volumes of broadband, voice, and TV service activations and changes. North American ISPs heavily invest in these platforms to support competitive service offerings and rapid customer onboarding.
- Satellite Operators:Satellite Operators use order management for provisioning satellite broadband, broadcast, and specialized enterprise communication services.
- Wholesale Carriers:Wholesale Carriers leverage these systems to manage inter-carrier services, capacity leases, and interconnection agreements efficiently.
Mobile Network Operators represent the largest segment. Internet Service Providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC mandates in the United States anchor significant demand for advanced telecom order management platforms. This demand stems from the complexity of 5G service bundles and the need for efficient enterprise IoT deployments. Cloud-native adoption is a key driver across these markets.
United States
FCC mandates for number portability and service quality drive system design requirements. Operators demand agile order management for complex 5G services and enterprise IoT provisioning. Major tech hubs like Silicon Valley and East Coast cities lead innovation in cloud-native platform adoption.
South Korea
Government initiatives for 5G infrastructure propel the need for sophisticated order management. Mobile Network Operators prioritize these solutions for advanced 5G network commercialization and service orchestration. The Seoul Metropolitan Area demonstrates pioneering efforts in digital service innovation.
Germany
Stringent GDPR regulations necessitate robust data privacy and sovereignty features in order management systems. Established operators manage substantial on-premise infrastructure while pursuing hybrid cloud strategies. Frankfurt's data center ecosystem and Munich's industrial base drive enterprise IoT deployments.
India
TRAI service delivery standards influence the need for efficient, scalable order management platforms. Operators deploy extensive customer self-service portals to manage vast subscriber bases and reduce operational load. Bangalore and Hyderabad, as IT hubs, are central to software development and deployment.
France
Data privacy rules under GDPR compel operators to maintain high control over customer information and order records. The market sees a phased migration strategy from legacy systems to cloud-native platforms. The Paris region spearheads digital transformation initiatives within the telecom sector.
Global Telecom Order Management Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the global telecom order management market. This structure combines established players with new cloud-native entrants, creating a dynamic competitive environment. Strategic archetypes include comprehensive solution providers offering end-to-end platforms, agile microservices vendors focusing on specific functionalities, and traditional network equipment manufacturers embedding order management capabilities. Competitive moves often involve strategic partnerships to bridge technology gaps, portfolio diversification into new digital service areas, and targeted mergers and acquisitions to consolidate market share.
Among integrated solution providers, Amdocs exemplifies a vendor with an extensive portfolio catering to comprehensive service provider operations, reflecting a long-standing market presence. Oracle leverages its deep enterprise cloud and database expertise to offer integrated solutions, representing a major software-centric player focused on robust backend infrastructure. Ericsson occupies a position by embedding order management within its broader 5G network and digital transformation offerings, highlighting a network equipment vendor's strategic approach to digital service enablement.
| Leading Market Players |
|---|
| Amdocs |
| Oracle |
| Ericsson |
| IBM |
| Cognizant |
| Pegasystems |
| SAP |
| Nokia |
| Netcracker Technology |
| Others |
Cost & Logistics Intelligence
Significant economies of scale in software development and cloud infrastructure shape both supply concentration and price floors in telecom order management. This structural dynamic ensures that larger vendors with established platforms can offer more competitive pricing while smaller, specialized firms find niche opportunities.
Pricing Analysis
Geographic price spreads exist, with solutions in highly regulated markets like the United States often commanding premiums due to compliance requirements. Subscription-based and SaaS-tiered models represent the dominant pricing structures, reflecting the shift to cloud-native platforms. Price differentiation stems from customization requirements for legacy system integration and the depth of after-sales support provided. Pricing softness stems from the increasing availability of modular, cloud-native solutions that offer lower total cost of ownership. Mobile Virtual Network Operators (MVNOs) exhibit the highest price sensitivity, while large Mobile Network Operators prioritize comprehensive functionality over cost.
Supply Chain Analysis
Software development lead times and feature integration complexity heavily influence the supply chain for telecom order management systems. Supply concentration centers in technology hubs across the United States, alongside specialized software providers in India and Ireland. The market relies heavily on cloud infrastructure services from major hyperscalers and the continuous evolution of TM Forum Open APIs. A key structural risk involves the cloud-native skills gap, which can delay deployment and increase costs. Distribution primarily runs through direct sales channels to large operators and strategic partnerships with system integrators for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
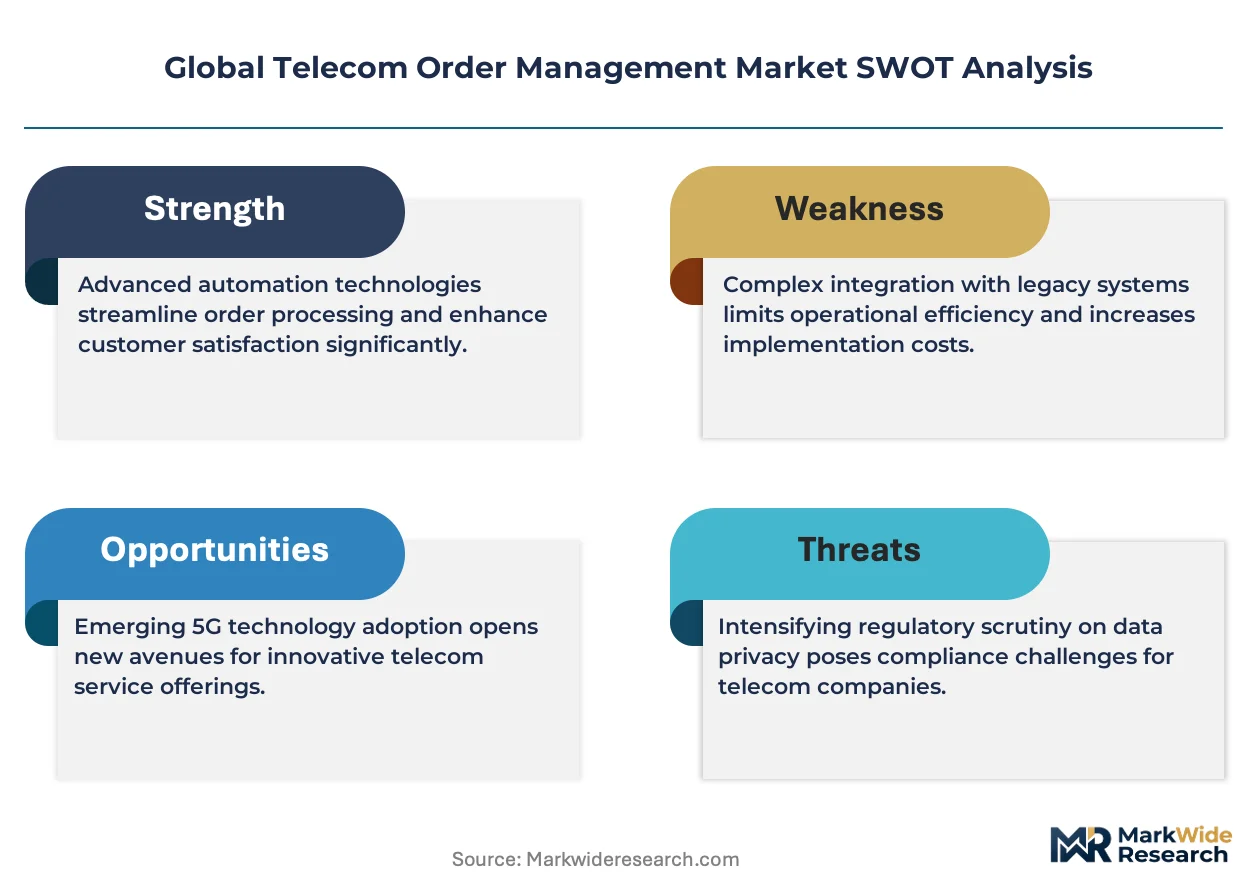
This market requires a substitution defense, as incumbents must navigate the threat of operators developing simpler, in-house orchestration tools or leveraging hyperscaler-provided basic functionalities.
For Market Incumbents:Secure talent pools with deep expertise in cloud-native architectures and microservices to maintain technological leadership. Invest strategically in AI-powered automation capabilities to differentiate offerings and reduce operational expenditures for operators. This approach directly counters the threat of simplified in-house solutions by providing superior, intelligent orchestration. Leverage existing customer relationships to cross-sell advanced digital transformation offerings.
For New Entrants and Emerging Players:Anchor in specific white-space opportunities such as B2B2X service enablement platforms, particularly in emerging markets of Southeast Asia and Africa. Target underpenetrated segments like smaller Internet Service Providers or Mobile Virtual Network Operators with lightweight, SaaS-based solutions. A strong go-to-market angle involves offering rapid deployment and flexible consumption models, appealing to operators seeking agile, low-overhead alternatives.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialist firms with proven cloud-native orchestration capabilities or deep AI/ML integration. The long-term viability (5-10 year window) of this market remains strong, driven by persistent 5G and IoT complexity. Acquisition targets should include agile microservices vendors that can accelerate an acquirer's shift away from monolithic architectures. The signal to watch is the widespread adoption of TM Forum Open APIs across a broader vendor ecosystem.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire Cloud-Native Orchestration Specialists | This move accelerates an operator's transition to agile 5G and IoT service fulfillment. |
| Invest in AI/ML for Zero-Touch Automation | Such investment enables predictive analytics and reduces manual intervention in complex order workflows. |
| Form Strategic Partnerships with Hyperscalers | These partnerships optimize cloud-based deployment and enhance scalability for global operators. |
| Develop Niche B2B2X Service Enablement Platforms | This initiative allows telecom operators to expand revenue streams by bundling connectivity with other industries. |
| Prioritize TM Forum Open API Adherence | Universal API adoption ensures seamless interoperability and accelerates multi-vendor integration efforts. |
Research Approach
A standing panel of Mobile Network Operator CTOs, IT procurement officers, cloud architects, and OSS/BSS leads provided ongoing calibration and validation for market insights. This primary research involved in-depth interviews with industry stakeholders across key geographies. Secondary validation drew from TM Forum reports, operator financial filings, and industry analyst reports, ensuring a comprehensive data foundation. The analysis employed both bottom-up and top-down triangulation to derive robust market estimates.
Outputs were validated against external benchmarks and cross-referenced with macroeconomic indicators to ensure consistency across the analysis window. The analytical framework modeled market sizing across deployment models, solution offerings, use cases, customer types, and regional adoption patterns. Compound Annual Growth Rates (CAGRs) were derived through a proprietary statistical model, incorporating factors like 5G rollout pace and enterprise IoT adoption rates as key forecast inputs.
Material uncertainties — including unforeseen regulatory shifts or major technological disruptions — sit outside the modeled envelope and could influence future market trajectories. Forecasts reflect assumptions documented through extensive primary and secondary research. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
Telecommunication Service Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
Philippines Telecom Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Esim Subscription Market
Telecommunications
Egypt Telecom Market
Telecommunications
Indonesia ICT Market
Telecommunications
Optical Fronthaul Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Telecom API Platform Market