
 Laboratory Filtration Devices Market | 2026-2036
Laboratory Filtration Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Filtration Devices Market Foresight
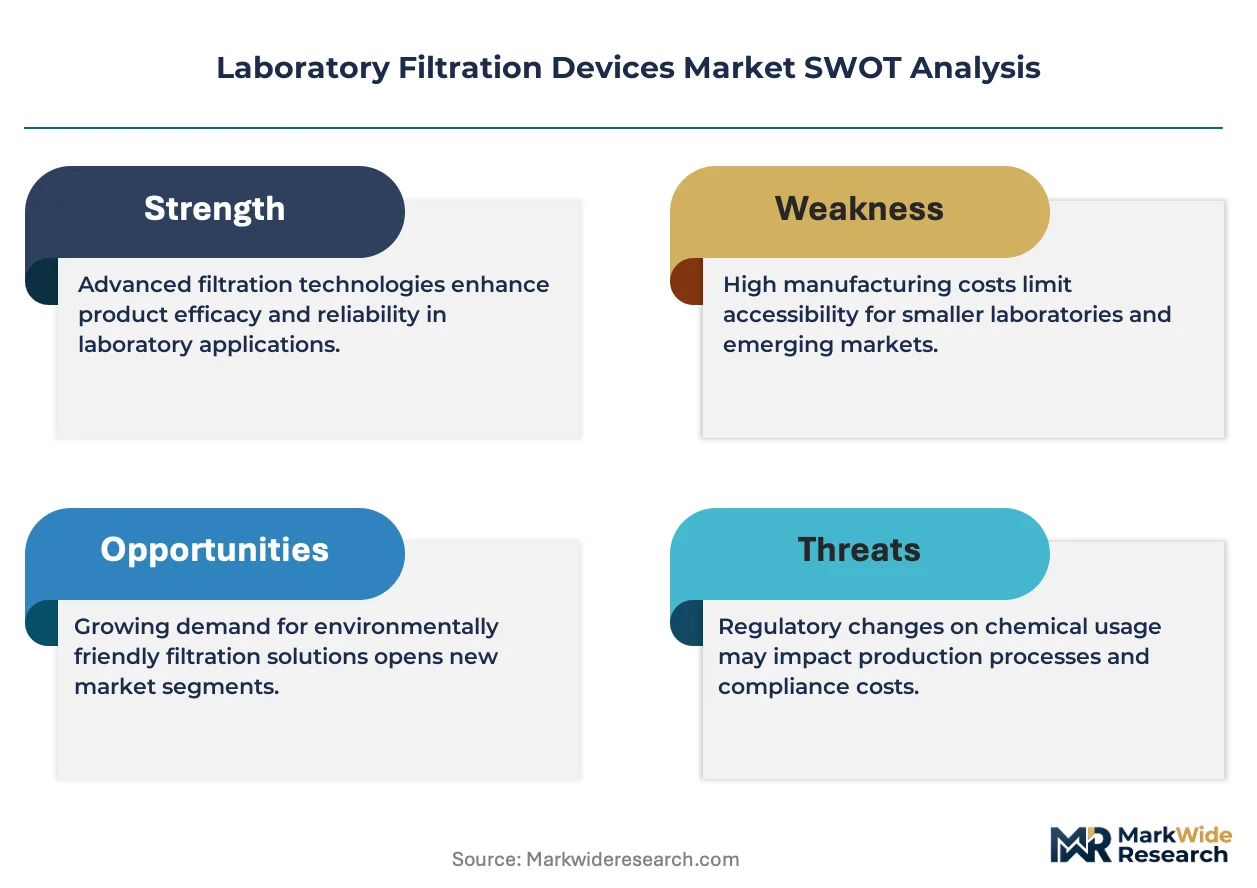
Polyethersulfone is pivoting toward polytetrafluoroethylene in high-temperature sterilization applications, altering cost structures for premium membrane production. Merck KGaA leverages its integrated polymer supply chain to stabilize input costs across European manufacturing hubs. Danaher Corporation anchors North American demand through extensive distribution networks serving pharmaceutical quality-control laboratories. Sartorius AG specializes in single-use filtration assemblies, competing directly with traditional stainless-steel systems in bioprocessing workflows.
Laboratory filtration devices separate, clarify, or sterilize liquid and gaseous samples using porous media with defined pore ratings typically ranging from 0.1 to 10 micrometers, manufactured through phase-inversion casting, track-etching, or melt-blowing processes depending on target application and chemical compatibility. Membrane filters command the dominant share of product-type revenue due to their precision in microbiological analysis and HPLC sample preparation, while ultrafiltration technology captures the fastest expansion as protein concentration and diafiltration protocols multiply in biopharmaceutical development. Depth filters retain substantial volume in prefiltration stages where high particulate loads would prematurely foul finer membranes, preserving margin pools in upstream clarification workflows.
The FDA enforces 21 CFR Part 211 standards for pharmaceutical manufacturing filtration, while the EMA's Annex 1 revision mandates continuous particulate monitoring in sterile processing, directly expanding validation documentation requirements for filter suppliers. ISO 13485 certification increasingly gates access to clinical-diagnostic laboratory contracts, particularly in European and North American procurement frameworks. Stakeholders must monitor evolving endotoxin-testing harmonization between USP and EP methodologies, as divergence in regulatory acceptance criteria threatens to fragment product qualification protocols across jurisdictions.
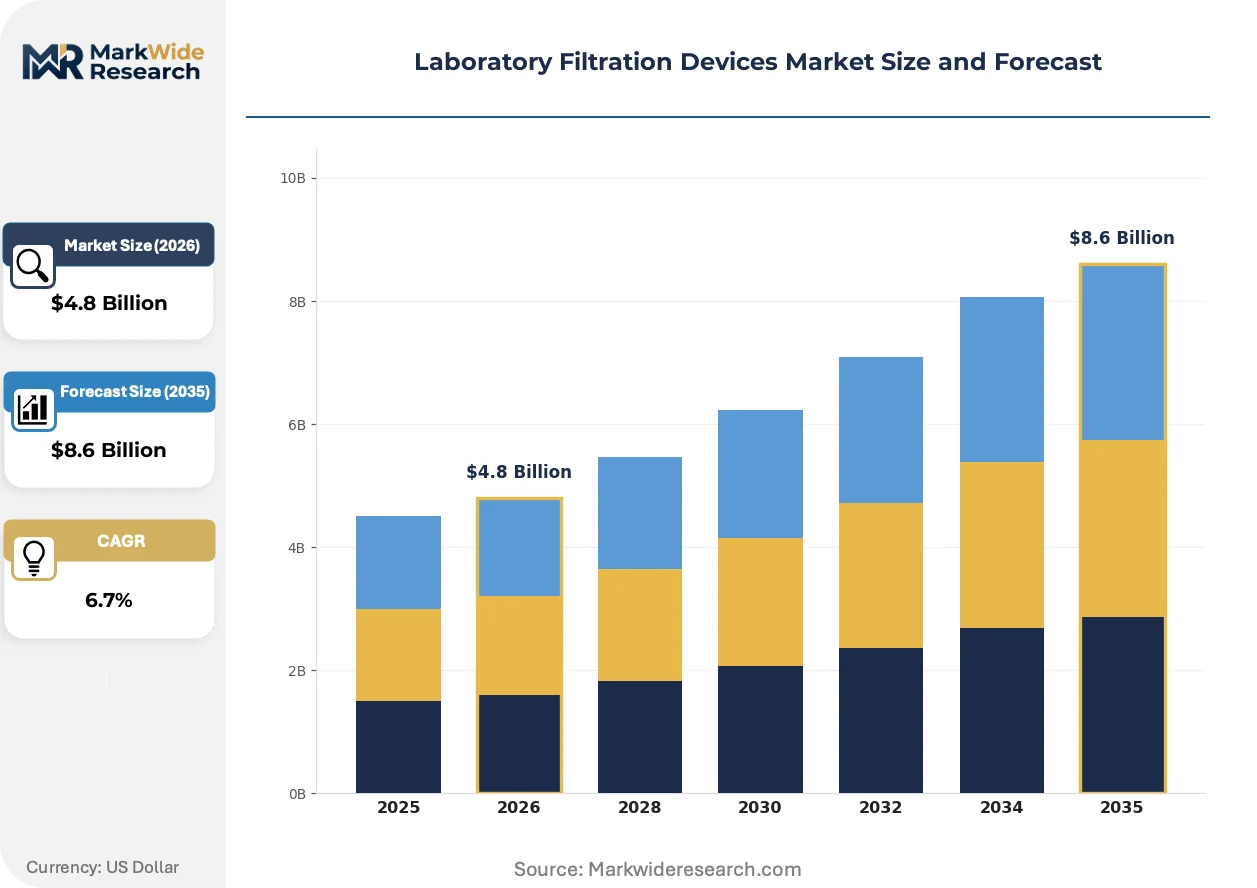
Market Dynamics
Biologics manufacturing expansion is compressing filtration validation cycles while tightening particulate standards force membrane material upgrades across pharmaceutical quality-control workflows.
Growth Catalysts
- EMA Annex 1 Revision:Continuous particulate monitoring mandates in sterile processing expand validation documentation requirements for filter suppliers serving European GMP-certified facilities.
- Protein Concentration Protocols:Ultrafiltration technology captures accelerated adoption in biopharmaceutical development as diafiltration workflows multiply in monoclonal antibody production.
- United States:Dense clusters of FDA-regulated pharmaceutical and biotechnology research facilities concentrate demand for high-performance membrane technologies in quality-control laboratories.
Market Restraints
- Specialty Polymer Volatility:Polyethersulfone and polytetrafluoroethylene input costs fluctuate with fluorochemical supply constraints, compressing margins for premium membrane producers.
- Validation Burden:FDA 21 CFR Part 211 compliance documentation extends product qualification timelines, creating friction for filter suppliers entering pharmaceutical manufacturing contracts.
- Stainless-Steel Incumbency:Traditional reusable filtration systems retain installed-base advantages in large-volume bioprocessing, slowing single-use assembly penetration.
Strategic Opportunities
- China:NMPA certification pathways for imported filtration devices create whitespace for membrane suppliers establishing local technical service capabilities.
- Cell and Gene Therapy:Viral vector purification workflows demand novel nanofiltration formats with enhanced selectivity for emerging biologics modalities.
- ISO 13485 Gatekeeping:Diagnostic laboratory procurement frameworks increasingly require quality management certification, favoring pre-qualified suppliers in European and North American tenders.
Industry Challenges
- Endotoxin Testing Harmonization:Divergence between USP and EP methodology acceptance criteria fragments product qualification protocols across jurisdictions, complicating multinational supplier strategies.
- Track-Etching Capacity:Precision membrane manufacturing requires specialized equipment with long lead times, constraining rapid scaling for high-pore-density applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Filtration Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filters, Depth Filters, Cartridge Filters, Filter Holders Application: Microbiological Analysis, Chemical Analysis, Liquid Filtration, Air Filtration End User: Pharmaceutical Labs, Environmental Labs, Food Testing Labs, Academic Research Technology: Gravity Filtration, Vacuum Filtration, Pressure Filtration, Ultrafiltration |
| Companies Covered | Merck KGaA, Danaher Corporation, Sartorius AG, 3M, Thermo Fisher Scientific Inc., GVS SpA, Agilent Technologies Inc., Cole-Parmer Instrument LLC, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Filtration Devices Market Shifts & Advancements
Membrane material science and regulatory documentation requirements are simultaneously elevating performance thresholds and supplier capability barriers across laboratory filtration procurement.
Single-use filtration assemblies are consolidating position in bioprocessing workflows as pharmaceutical manufacturers prioritize contamination risk reduction over capital equipment depreciation. Contract development and manufacturing organizations adopt these disposable formats fastest, compressing demand for traditional stainless-steel systems in clinical-scale production. The shift is consolidating supplier relationships around vendors with integrated polymer supply chains and sterile packaging capabilities.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of hydrophobic membrane chemistries used in venting and air filtration applications. European filtration device manufacturers face accelerated R&D timelines to qualify PFAS-free alternatives without sacrificing moisture barrier performance. Diagnostic and pharmaceutical packaging segments in Germany and Switzerland are responding earliest, driven by ECHA enforcement timelines and customer sustainability mandates.
Consolidated purchasing through group procurement organizations is compressing vendor margins while elevating technical service requirements in North American hospital and reference laboratory networks. Traditional distribution intermediaries face disintermediation as direct manufacturer partnerships offer validated supply security and customized stocking programs. Academic research institutions in the United States exhibit this behavioral shift most visibly, migrating from catalog distributors to sole-source agreements with membrane specialists.
Laboratory Filtration Devices Market Segmentation
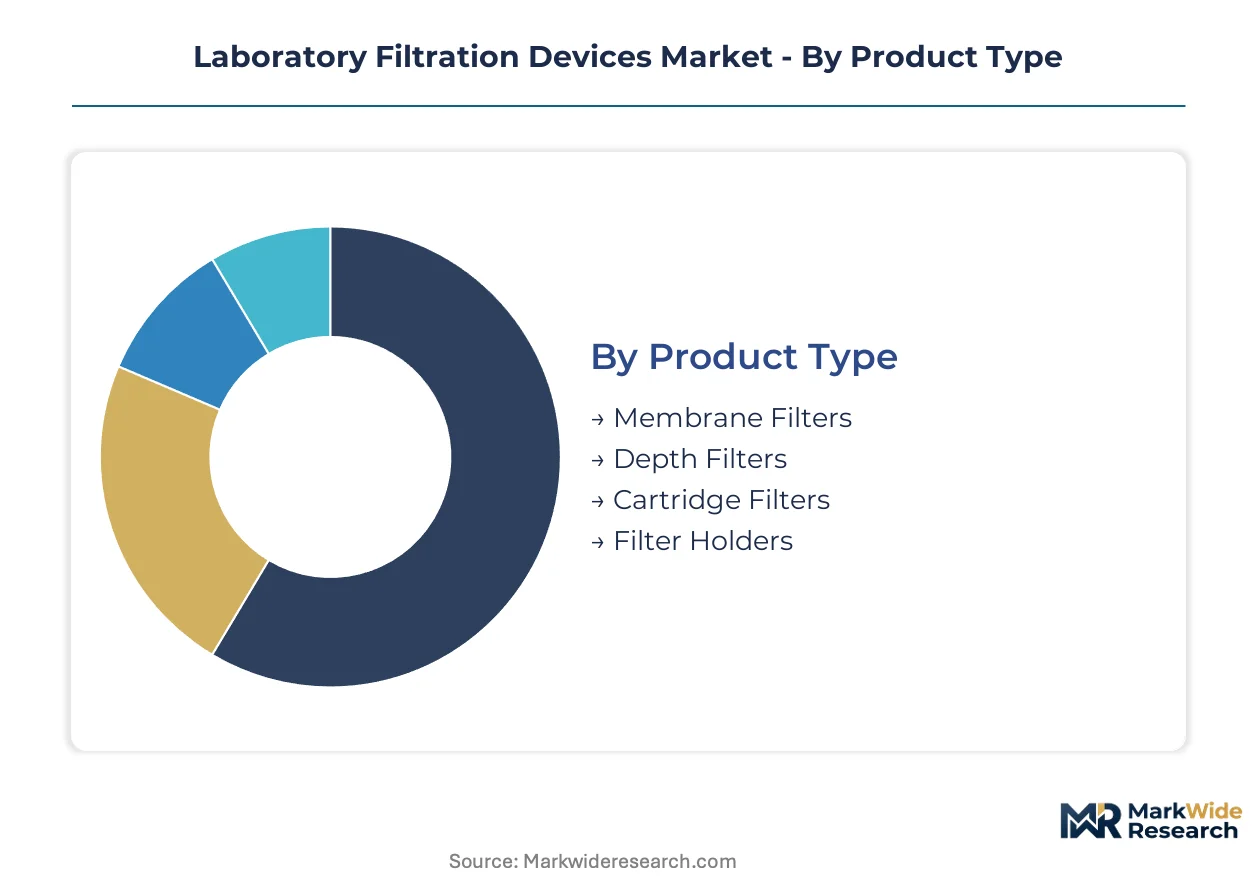
Segmentation in laboratory filtration devices reveals how capital deployment, regulatory compliance burdens, and application specificity fragment purchasing behavior across end-use environments. Capital intensity varies dramatically by product architecture and sterilization validation requirements.
Product Type:
Capital intensity peaks with membrane filters requiring precision manufacturing infrastructure, while depth filters demand lower fixed asset bases but higher consumables throughput.
- Membrane Filters:Manufactured through phase-inversion casting or track-etching to achieve defined pore ratings from 0.1 to 10 micrometers. Pharmaceutical quality-control laboratories in the United States concentrate demand as FDA 21 CFR Part 211 compliance tightens particulate contamination thresholds.
- Depth Filters:Constructed from bonded fiber matrices that capture particles throughout the medium thickness rather than just at the surface. Environmental testing facilities in Germany deploy these for high-particulate-load prefiltration where membrane fouling would accelerate operating costs.
- Cartridge Filters:Self-contained units with pleated or depth media designed for scalable flow rates in bioprocessing workflows.
- Filter Holders:Reusable hardware assemblies that secure disk or sheet media across multiple filtration cycles in academic research settings.
Most installed capacity flows through membrane filters. Expansion is steepest in cartridge formats as single-use bioprocessing displaces stainless-steel systems.
Application:
Application segmentation tracks how sterility assurance levels and analytical precision requirements stratify procurement budgets across laboratory types.
- Microbiological Analysis:Requires absolute retention of bacterial and fungal contaminants for sterility testing and environmental monitoring. EMA Annex 1 revision mandates continuous particulate monitoring in European sterile processing facilities, expanding validation documentation for filter suppliers.
- Chemical Analysis:Demands chemical compatibility and extractables control for HPLC sample preparation and solvent filtration. Pharmaceutical development labs in Switzerland prioritize inert membrane chemistries that withstand aggressive organic solvents.
- Liquid Filtration:Encompasses general clarification and sterilization of aqueous and non-aqueous fluids across research and manufacturing.
- Air Filtration:Protects sterile workspaces and equipment through hydrophobic membrane venting and HEPA-grade environmental control.
Microbiological analysis commands the highest unit economics. Chemical analysis is climbing fastest as biologics manufacturing expands analytical testing volumes.
End User:
End user segmentation reflects divergent procurement authority structures, with pharmaceutical labs consolidating through group purchasing organizations while academic institutions fragment across individual principal investigator budgets.
- Pharmaceutical Labs:GMP-certified manufacturing and quality-control facilities with validated supply chain requirements and sterile packaging mandates. China's NMPA certification pathways for imported devices create whitespace for membrane suppliers building local technical service capabilities.
- Environmental Labs:Regulatory compliance testing for water, soil, and air quality with standardized method requirements.
- Food Testing Labs:Pathogen detection and quality assurance for beverage and ingredient safety under FSMA and EU food law.
- Academic Research:Method development and fundamental science with price-sensitive purchasing and diverse application needs.
Pharmaceutical labs anchor revenue concentration. Academic research shows the steepest expansion trajectory as cell and gene therapy research multiplies demand for novel nanofiltration formats.
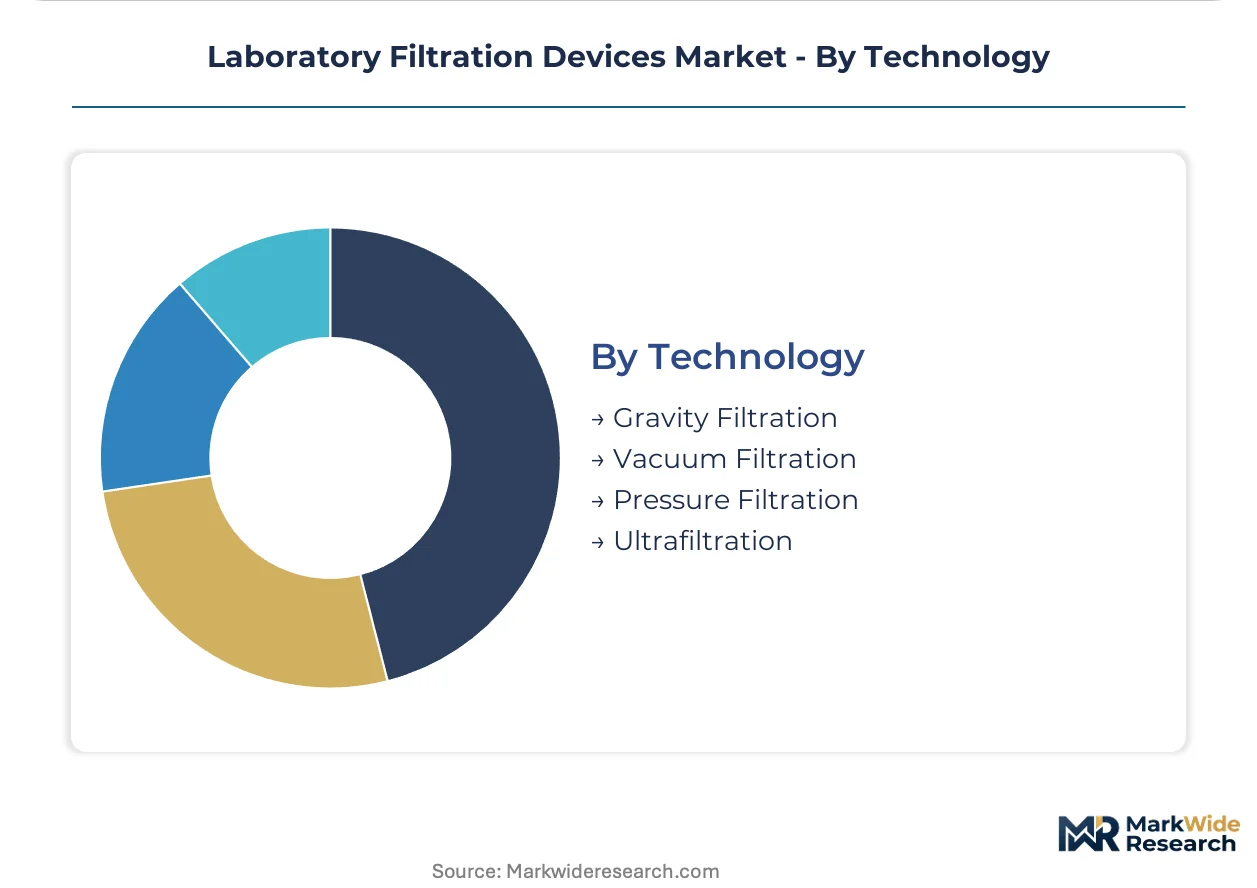
Technology:
Technology segmentation distinguishes between gravity-driven simplicity and pressure-assisted performance, with automation integration driving capital allocation toward advanced formats.
- Ultrafiltration:Employs molecular weight cut-off membranes for protein concentration, buffer exchange, and viral vector purification. Contract development and manufacturing organizations adopt disposable ultrafiltration formats fastest as contamination risk reduction outweighs capital equipment depreciation concerns.
- Vacuum Filtration:Applies negative pressure to accelerate flow rates for high-throughput sample processing in microbiological testing.
- Pressure Filtration:Utilizes positive pressure systems for viscous samples or sterile filtration of large volumes in biopharmaceutical production.
- Gravity Filtration:Relies on hydrostatic head for simple clarification without equipment investment in teaching and routine screening labs.
Pressure filtration retains the largest installed base. Ultrafiltration gains share fastest as monoclonal antibody production scales and diafiltration protocols multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor concentrates the densest cluster of FDA-regulated pharmaceutical quality-control laboratories in North America, anchoring demand for membrane filtration validation services.
United States
Contract development and manufacturing organizations in Massachusetts and California drive single-use filtration assembly procurement as contamination risk reduction outweighs capital depreciation. FDA 21 CFR Part 211 enforcement tightens particulate thresholds for sterile processing. The Research Triangle Park in North Carolina hosts expanding viral vector purification facilities demanding novel nanofiltration formats.
Germany
EMA Annex 1 revision mandates continuous particulate monitoring in sterile processing, expanding validation documentation requirements for filter suppliers serving GMP-certified facilities. REACH restrictions on per- and polyfluoroalkyl substances force accelerated R&D timelines for PFAS-free membrane alternatives. The Rhine-Main biotech cluster around Frankfurt anchors European demand for hydrophobic venting applications.
China
NMPA certification pathways for imported filtration devices create whitespace for membrane suppliers establishing local technical service capabilities. Biologics manufacturing expansion in Shanghai and Suzhou compresses filtration validation cycles while scaling protein concentration protocols. The Zhangjiang Hi-Tech Park concentrates monoclonal antibody production facilities driving ultrafiltration adoption.
Switzerland
Pharmaceutical development laboratories in Basel prioritize inert membrane chemistries withstanding aggressive organic solvents for HPLC sample preparation. Swissmedic maintains alignment with EMA standards while preserving distinct national pharmacopeia requirements. The Lake Geneva biotech corridor hosts contract manufacturing organizations adopting disposable filtration formats fastest.
United Kingdom
Academic research institutions in Cambridge and Oxford migrate from catalog distributors to sole-source agreements with membrane specialists for cell and gene therapy research. MHRA post-Brexit regulatory divergence creates friction in multinational supplier qualification protocols. The Golden Triangle research cluster multiplies demand for novel nanofiltration formats in emerging biologics modalities.
Laboratory Filtration Devices Market Competitive Landscape
Global majors compete with regional champions across polymer supply chain integration and sterile packaging capabilities, producing a tiered structure where integrated chemical conglomerates anchor premium membrane production while specialized filtration fabricators capture niche application segments. Market concentration reflects validation documentation barriers rather than manufacturing scale alone. Three archetypes dominate: polymer-integrated conglomerates with captive raw material supply, single-use assembly specialists competing against stainless-steel incumbents, and precision track-etching houses serving analytical instrumentation OEMs. Competitive moves center on backward integration into specialty polymer production and sterile packaging capacity expansion near pharmaceutical manufacturing clusters.
Within the polymer-integrated tier, Merck KGaA exemplifies European supply chain control, while Danaher Corporation anchors North American distribution density. Sartorius AG occupies a position as the single-use assembly archetype competing directly with traditional reusable systems. These three represent distinct strategic postures: captive chemical supply, channel dominance, and disposable format specialization respectively.
| Leading Market Players |
|---|
| Merck KGaA |
| Danaher Corporation |
| Sartorius AG |
| 3M |
| Thermo Fisher Scientific Inc. |
| GVS SpA |
| Agilent Technologies Inc. |
| Cole-Parmer Instrument LLC |
| Parker Hannifin |
| Others |
Supply & Pricing Matrix
Single-use assembly adoption in bioprocessing workflows simultaneously compresses per-unit filtration economics and concentrates supply relationships around vendors with integrated polymer production and sterile packaging capabilities. Contract development and manufacturing organizations now prioritize validated supply security over catalog pricing, reshaping how membrane suppliers structure long-term offtake agreements and regional service investments.
Pricing Analysis
Polyethersulfone and polytetrafluoroethylene input cost pass-through dominates pricing dynamics for premium membrane tiers, with fluorochemical supply constraints compressing margins for track-etched and phase-inversion cast products. Three-tier pricing structure across premium, standard, and economy levels differentiates by validation documentation depth and ISO 13485 certification status rather than pore rating alone. Pricing pressure stems from consolidated purchasing through group procurement organizations in North American hospital networks. Academic research institutions exhibit highest price sensitivity, while GMP-certified pharmaceutical quality-control laboratories absorb premium tiers for regulatory risk mitigation.
Supply Chain Analysis
Dual-sourcing requirements mandated by FDA 21 CFR Part 211 compliance force pharmaceutical manufacturers to qualify multiple membrane suppliers for critical sterile processing steps, fragmenting volume concentration despite supplier consolidation at the polymer level. Manufacturing concentrates in Germany, the United States, and China as these countries host dense clusters of GMP-certified production and track-etching infrastructure. Specialty fluoropolymer feedstocks and precision casting equipment constitute critical input dependencies. Single-source vulnerability in high-pore-density track-etching capacity constrains rapid scaling for diagnostic OEM contracts. Distribution runs through direct manufacturer partnerships and validated sterile packaging logistics rather than traditional catalog intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ultrafiltration technology tiers and PFAS-free membrane reformulations, where REACH compliance timelines and biologics manufacturing expansion simultaneously elevate pricing power and compress competitor R&D cycles.
For Market Incumbents: To counter stainless-steel system incumbency in large-volume bioprocessing, deepen sterile packaging capabilities near pharmaceutical manufacturing clusters in Massachusetts and North Carolina while securing captive supply of polyethersulfone alternatives to stabilize input cost volatility. Backward integration into specialty polymer production anchors margin defense against fluorochemical supply constraints. For New Entrants and Emerging Players: Nanofiltration format innovation for viral vector purification in cell and gene therapy workflows offers the most penetrable white-space, as established suppliers lag in selectivity specifications for emerging biologics modalities. Target China's NMPA certification pathways by establishing local technical service capabilities in Shanghai and Suzhou. Position through ISO 13485 pre-qualification to bypass group procurement organization gatekeeping in European tenders. For Investors and Strategic Acquirers: Valuations sit cheapest among precision track-etching houses serving analytical instrumentation OEMs, where manufacturing scale barriers and long equipment lead times protect niche positioning. Long-term viability favors suppliers with integrated polymer supply chains and sterile packaging assets across multiple regulatory jurisdictions. Watch EMA-FDA endotoxin testing harmonization progress as the inflection signal for multinational supplier qualification protocol consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Membrane Reformulation | REACH restrictions in Germany and Switzerland accelerate R&D timelines for hydrophobic venting alternatives without moisture barrier degradation. |
| Single-Use Assembly Capacity Expansion | Disposable format adoption in contract development and manufacturing organizations displaces stainless-steel installed base in clinical-scale production. |
| ISO 13485 Certification Investment | Diagnostic laboratory procurement frameworks in Europe and North America increasingly gate access through quality management pre-qualification. |
| Local Technical Service Buildout in China | NMPA certification pathways for imported devices create whitespace for membrane suppliers establishing regional validation support capabilities. |
| Ultrafiltration Technology Platform Extension | Monoclonal antibody production scaling and diafiltration protocol multiplication drive fastest-expanding technology segment in biopharmaceutical development. |
Research Methodology
Multiple input streams — regulatory filing analysis, supply chain documentation, and procurement pattern assessment — were reconciled through structured primary interviews with filtration product managers, GMP facility quality officers, diagnostic laboratory procurement leads, and polymer supply chain directors. Secondary validation drew from FDA 21 CFR guidance documents, EMA Annex 1 revision texts, ISO 13485 certification registries, and customs trade data for specialty fluoropolymer movements. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates against capacity disclosures from track-etching and phase-inversion manufacturing infrastructure.
Historical shipment data and expert panel input were cross-referenced to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product architecture, sterilization validation requirements, application specificity, and end-user procurement authority structures. CAGRs were derived from installed base turnover rates and replacement demand curves tied to biologics manufacturing expansion. Forecast inputs included EMA-FDA regulatory divergence scenarios and REACH enforcement timeline assumptions for PFAS-containing membrane chemistries.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluorochemical supply disruptions, endotoxin testing standard harmonization failures, and stainless-steel system retention in large-volume bioprocessing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Total Nucleic Acid Extraction Kits Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Laboratory Andrology Equipment Market
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Global Bovine Serum Albumin Market
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Global Bioprocess Analyzers Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Life Science Instrumentation Market