
 Ireland Facility Management Market | 2026-2036
Ireland Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Facility Management Market Outlook
Integrated service delivery is rotating toward premium-certified FM bundles that bundle compliance, sustainability, and digital asset monitoring under single accountability. Noonan Services anchors its position through deep public sector relationships and nationwide coverage density. Mitie Group differentiates via technology-led service models that embed IoT diagnostics into hard FM contracts. Sodexo Group competes on workplace experience design, leveraging its food services heritage to capture integrated soft FM mandates.
Facility management encompasses the professional coordination of building operations, maintenance, cleaning, security, and environmental systems to ensure functional, safe, and efficient built environments. The discipline applies technical protocols including HVAC performance benchmarking, energy management systems, and preventive maintenance scheduling to sustain asset lifecycle value across commercial and institutional portfolios. Hard FM services—specifically maintenance and security—command the largest revenue pools due to regulatory compliance burdens and specialized labor requirements. Soft FM segments, led by cleaning and landscaping, face margin compression from labor cost inflation but retain volume growth through outsourcing conversion in the public sector and healthcare estates.
The Health and Safety Authority enforces workplace facility standards that mandate risk assessment protocols and contractor competency verification, directly shaping procurement specifications for industrial and healthcare sites. The Sustainable Energy Authority of Ireland administers building energy rating obligations and retrofit grant schemes that redirect FM spending toward energy efficiency upgrades and decarbonization compliance. The National Standards Authority of Ireland certifies quality management systems that filter vendor eligibility for public contracts. Stakeholders must weigh the capital requirements of building management system modernization against the operational savings and compliance certainty that integrated technology platforms deliver.
Market Dynamics
The Irish Building Control (Amendment) Regulations are compressing capital planning cycles for estate managers, forcing simultaneous compliance retrofitting and digital infrastructure deployment across aging commercial and healthcare portfolios.
Growth Catalysts
- Healthcare estate modernization:Acute care facilities in Dublin and Cork are consolidating fragmented maintenance contracts into integrated hard FM bundles to meet Health and Safety Authority risk assessment mandates.
- SEAI retrofit grants:The Sustainable Energy Authority of Ireland's building energy rating obligations are redirecting capital expenditure toward energy management system upgrades and HVAC performance benchmarking.
- Logistics corridor density:Warehouse and distribution center construction along the M50 and M7 corridors is generating demand for security and preventive maintenance services at scale.
Market Restraints
- Specialized labor scarcity:Certified HVAC technicians and building automation engineers command premium wages that compress margins on fixed-price maintenance contracts.
- Supply concentration in Dublin:Three-quarters of qualified FM contractors maintain headquarters within the capital, creating service delivery friction for rural healthcare estates in the Midlands and Northwest.
- Regulatory compliance layering:Overlapping obligations from the Health and Safety Authority, SEAI, and National Standards Authority of Ireland inflate administrative overhead for multi-site operators.
Strategic Opportunities
- Primary care estate outsourcing:Community healthcare centers in Galway, Limerick, and Waterford remain underpenetrated by integrated soft FM providers.
- IoT-enabled predictive maintenance:Convergence of wireless sensor networks and cloud-based asset monitoring platforms allows remote diagnostics of building systems across dispersed portfolios.
- Public sector framework consolidation:The Office of Government Procurement is streamlining vendor panels, creating entry points for technology-certified operators.
Industry Challenges
- Building management system integration:Legacy HVAC controls in 1990s-era commercial stock resist seamless connection to modern energy management platforms without costly hardware replacement.
- Competency verification timelines:Contractor certification under Health and Safety Authority protocols delays mobilization for urgent maintenance callouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Facility Management Market |
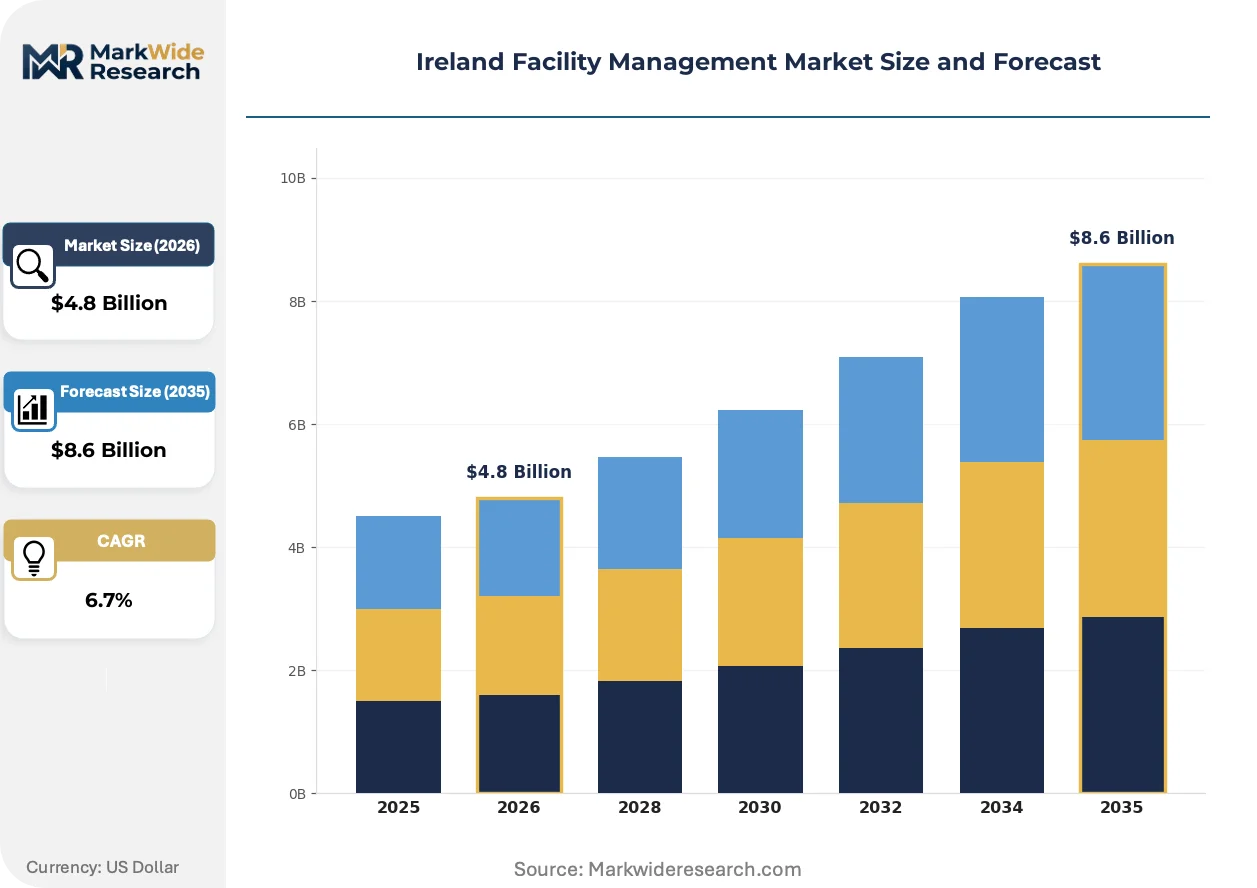
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Commercial Buildings, Industrial Facilities, Educational Institutions, Healthcare Facilities Facility Type: Office Spaces, Retail Centers, Manufacturing Plants, Public Facilities Contract Type: Outsourced, In-house, Hybrid, Short-term |
| Companies Covered | Noonan Services, Apleona Ireland, Mitie Group, OCS Group, Sodexo Group, CBRE Group Inc, Cushman & Wakefield PLC, Sensori Facilities Management, Kier Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Facility Management Market Strategic Shifts
Digital instrumentation is penetrating building infrastructure at accelerating pace, compressing the traditional separation between operational technology and information technology layers in facility management delivery models.
Wireless sensor networks for real-time HVAC performance monitoring are miniaturizing installation footprints and reducing commissioning costs. Pharmaceutical manufacturing sites in Cork and Dublin are deploying these systems at pilot scale before portfolio-wide rollout. The technology is miniaturizing the capital barrier to condition-based maintenance, enabling mid-sized estate operators to access predictive capabilities previously reserved for large integrated contracts.
The EU Energy Performance of Buildings Directive, transposed through Irish building control regulations, mandates operational energy disclosure for commercial premises over 1000 square meters. This obligation is forcing asset managers to deploy sub-metering infrastructure and automated reporting dashboards. Industrial and logistics facilities face the steepest compliance timelines, with many engaging FM providers to assume data collection and verification responsibilities.
Buyers are unbundling long-term integrated contracts into modular service components with discrete performance metrics. Healthcare estates now separate hard FM maintenance from soft FM cleaning and catering, awarding these to specialized operators rather than single-source integrators. This fragmentation is most pronounced in the Greater Dublin Area, where estate managers possess sufficient procurement capacity to coordinate multiple vendor relationships.
Ireland Facility Management Market Segmentation
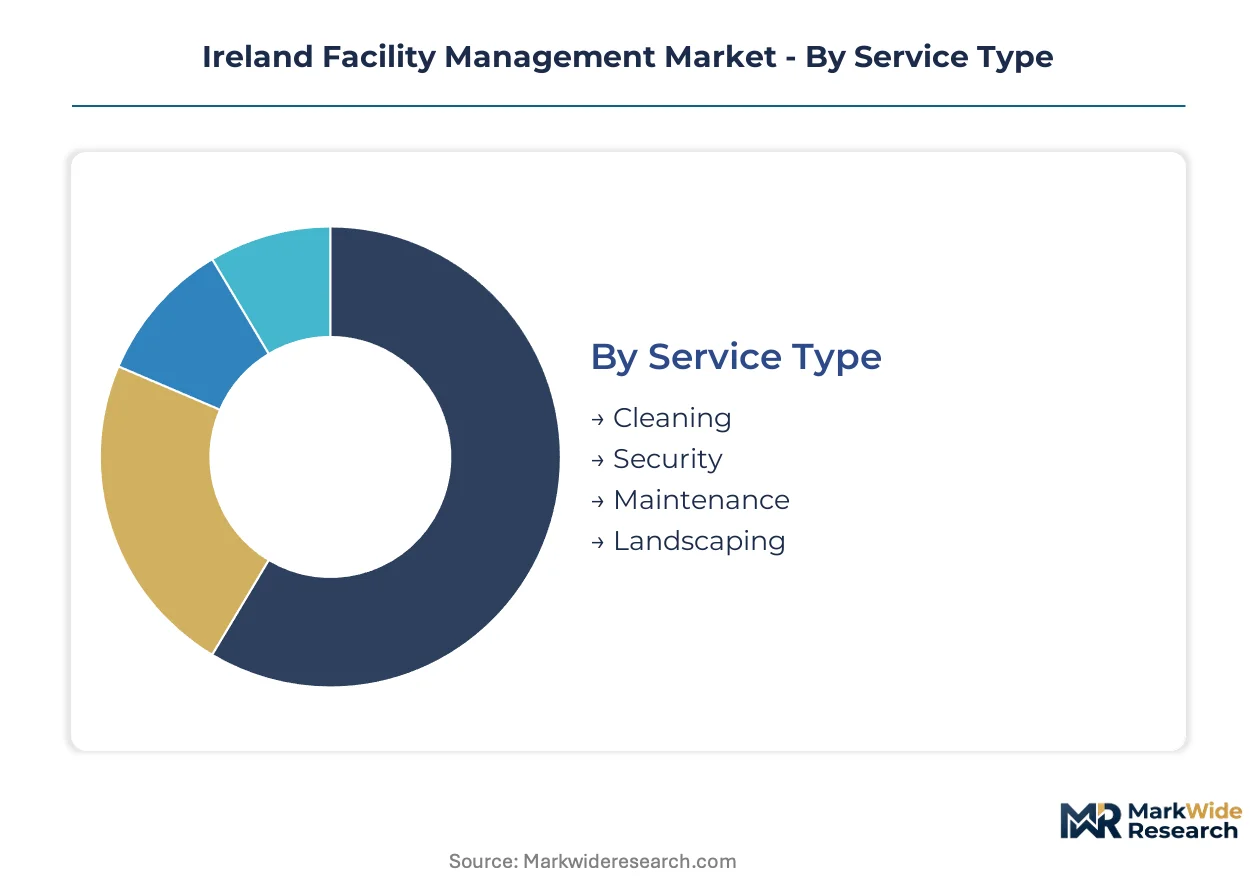
Service differentiation in Irish facility management follows distinct procurement logics across hard and soft FM categories. Regulatory mandates from the Health and Safety Authority and SEAI reshape contract specifications differently for each segment tier.
Service Type:
The Health and Safety Authority enforces divergent competency standards across technical and non-technical service lines.
- Cleaning:Specialized disinfection protocols for healthcare estates require ISO-certified processes under National Standards Authority of Ireland oversight. Dublin's acute care facilities drive premium demand for terminal cleaning services that meet infection control mandates.
- Security:Electronic access control and manned guarding integrate with building management systems for real-time threat response. Logistics corridors along the M50 generate concentrated demand for 24/7 perimeter monitoring and cargo protection services.
- Maintenance:Hard FM contracts bundle HVAC, electrical, and mechanical services under preventive scheduling frameworks.
- Landscaping:Grounds maintenance for commercial campuses and public facilities follows seasonal contracting patterns with sustainability specifications.
Maintenance handles the majority of throughput; Security is expanding most quickly on share.
End User:
Capital intensity and compliance layering vary sharply across estate types, redirecting vendor selection criteria.
- Commercial Buildings:Dublin's Grade A office stock demands integrated soft FM bundles combining cleaning, reception, and workplace experience services. SEAI energy rating obligations force simultaneous HVAC upgrades and sub-metering installations across 1990s-era commercial portfolios.
- Healthcare Facilities:Acute and primary care estates consolidate fragmented contracts into single-accountability hard FM arrangements. The Health and Safety Authority's risk assessment mandates drive specialized procurement for clinical engineering and medical gas maintenance.
- Industrial Facilities:Manufacturing plants in Cork and Galway require process-critical maintenance with minimal production downtime.
- Educational Institutions:Universities and schools balance budget constraints against extended facility operating hours.
Commercial Buildings dominates contract value; Healthcare Facilities is climbing the fastest on share.
Facility Type:
Asset vintage and tenant mix reshape service delivery models across the built environment.
- Office Spaces:Flexible workspace operators demand modular FM contracts with usage-variable pricing. Dublin's commercial core concentrates demand for premium integrated services that bundle digital asset monitoring with traditional hard FM.
- Manufacturing Plants:Pharmaceutical and medical device facilities in Cork enforce GMP-aligned maintenance protocols with full audit trails. Process equipment reliability requirements compress mean-time-to-repair targets below standard commercial benchmarks.
- Retail Centers:Shopping malls and retail parks prioritize customer-facing cleanliness and security visibility.
- Public Facilities:Government buildings and civic infrastructure operate under Office of Government Procurement framework agreements.
Office Spaces generates the largest contract pipeline; Manufacturing Plants shows the steepest expansion trajectory.
Contract Type:
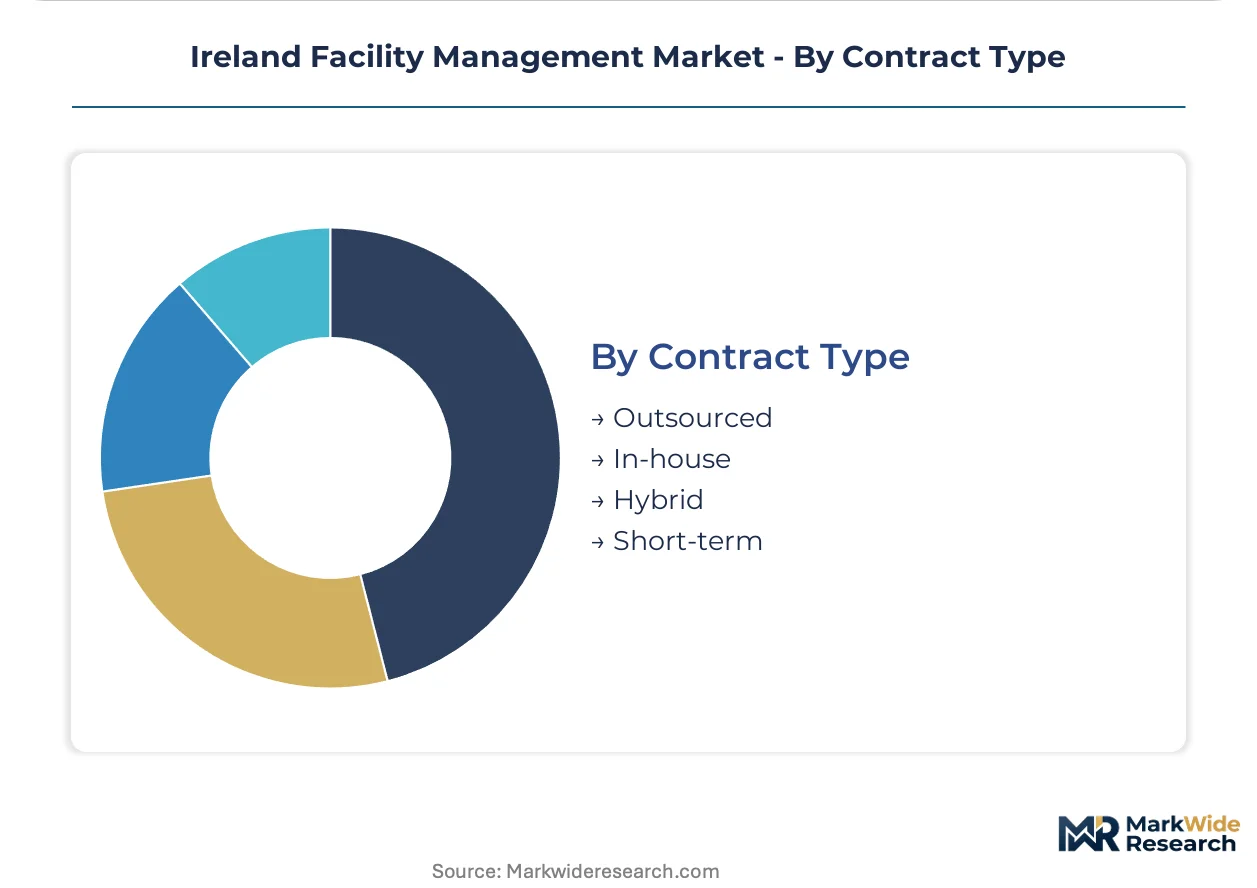
Procurement flexibility and risk allocation determine contract structure selection across estate portfolios.
- Outsourced:Third-party FM providers assume full operational responsibility with performance-based KPIs. Healthcare estates in Dublin and Cork are migrating from fragmented in-house teams to integrated outsourced bundles.
- In-house:Direct employment models persist in specialized industrial facilities with proprietary process equipment. Retained technical teams handle critical maintenance while ancillary services shift to contracted suppliers.
- Hybrid:Split arrangements combine in-house supervisory staff with outsourced delivery crews.
- Short-term:Project-based contracts address surge capacity needs and transitional estate phases.
Outsourced commands the dominant share; Hybrid is gaining adoption fastest among mid-sized portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ireland's facility management sector operates as a net service importer, with specialized technical competencies and digital platform capabilities flowing primarily from the United Kingdom while indigenous providers dominate public sector and healthcare delivery. Dublin's commercial density concentrates contract value, creating pronounced regional asymmetries in vendor availability and pricing power.
Dublin and the East Coast
Grade A office stock and pharmaceutical manufacturing clusters in Dublin, Cork, and Waterford drive premium integrated FM demand. The Health and Safety Authority enforces workplace facility standards that mandate risk assessment protocols across acute care estates. Dublin's commercial core concentrates three-quarters of qualified FM contractors, creating service delivery friction for rural healthcare facilities.
Cork and the South-West
Pharmaceutical manufacturing sites in Cork deploy wireless sensor networks for real-time HVAC performance monitoring at pilot scale. The Sustainable Energy Authority of Ireland administers building energy rating obligations that redirect capital expenditure toward energy management system upgrades. Process-critical maintenance requirements in pharmaceutical facilities compress mean-time-to-repair targets below standard commercial benchmarks.
Galway and the West
Medical device manufacturing and expanding logistics corridors generate demand for security and preventive maintenance services. Community healthcare centers remain underpenetrated by integrated soft FM providers despite rising outsourcing conversion. The Office of Government Procurement framework agreements create standardized entry points for technology-certified operators seeking public sector mandates.
Limerick and the Mid-West
Industrial estates and distribution centers along the M7 corridor require scaled security and building automation services. The Irish Building Control (Amendment) Regulations tighten energy performance standards for existing commercial stock, forcing simultaneous compliance retrofitting and digital infrastructure deployment. Mid-sized estate operators in this region access predictive maintenance capabilities through cloud-based asset monitoring platforms.
Belfast and Northern Ireland Cross-Border
All-island service providers leverage operational scale across the Dublin-Belfast economic corridor for specialized technical labor pools. UK-based FM contractors maintain service delivery infrastructure that supports cross-border healthcare and commercial contracts. Regulatory divergence between Irish and UK building control standards creates compliance complexity for multi-site operators spanning both jurisdictions.
Ireland Facility Management Market Competitive Environment
Concentration sits with diversified service integrators that bundle hard FM maintenance, soft FM cleaning and catering, and digital asset monitoring under single accountability structures. The vendor base spans three distinct tiers: global property consultancies with FM divisions, specialized Irish-owned service providers with deep public sector relationships, and UK-headquartered contractors leveraging cross-border operational scale. Strategic moves center on technology certification for public procurement eligibility and selective M&A to fill geographic or competency gaps in healthcare and pharmaceutical verticals.
Among Ireland-based specialists, Noonan Services anchors the indigenous tier through nationwide coverage density and entrenched public sector relationships. UK-headquartered contractors Mitie Group and Sodexo Group occupy positions on the technology-led and workplace experience vectors respectively, with Mitie exemplifying IoT-embedded service delivery and Sodexo representing integrated soft FM bundling that leverages food services heritage. These three names illustrate the competitive archetypes—indigenous scale, technology differentiation, and experience design—that define procurement alternatives for Irish estate managers.
| Leading Market Players |
|---|
| Noonan Services |
| Apleona Ireland |
| Mitie Group |
| OCS Group |
| Sodexo Group |
| CBRE Group Inc |
| Cushman & Wakefield PLC |
| Sensori Facilities Management |
| Kier Group PLC |
| Others |
Value Chain & Pricing Dynamics
The Health and Safety Authority's contractor competency verification gates both vendor qualification and rate differentiation across the Irish facility management sector. Estate managers face simultaneous certification premiums and compliance overhead that compress procurement flexibility while rewarding accredited operators.
Pricing Analysis
Industrial OEM buyers anchor contract pricing through multi-year framework agreements that bundle preventive maintenance with energy management system upgrades. Three-tier pricing structure across premium-certified, standard-compliant, and economy-basic service levels reflects divergent Health and Safety Authority audit trails and SEAI energy rating alignment. Cost compression in the economy tier is intensifying because uncertified labor pools compete on hourly rates without warranty backing. Healthcare estates exhibit lowest price sensitivity due to clinical risk exposure, while logistics operators in the M50 corridor negotiate hardest on security service unit costs.
Supply Chain Analysis
Just-in-time labor deployment dominates facility management delivery, with qualified HVAC technicians and building automation engineers mobilized through regional contractor networks rather than permanent employment pools. Supply concentrates in the United Kingdom for digital platform capabilities and specialized pharmaceutical maintenance protocols, while indigenous Irish providers control public sector and healthcare estate relationships. Critical input dependencies include wireless sensor hardware, cloud-based asset monitoring software licenses, and certified technical labor pools. Single-source vulnerability sits with UK-headquartered technology vendors subject to post-Brexit regulatory divergence. Distribution runs through Dublin-based service hubs that dispatch crews to Cork, Galway, and Limerick corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated healthcare estates and pharmaceutical manufacturing clusters that command volume leverage over fragmented FM vendor bases. The Office of Government Procurement's framework consolidation amplifies this concentration.
For Market Incumbents: Secure technology certification for public procurement eligibility before framework renewal cycles close. Invest in IoT-enabled predictive maintenance capabilities to defend against UK-headquartered contractors with superior digital platforms. Deepen relationships with the Sustainable Energy Authority of Ireland to anchor retrofit grant-funded contract pipelines. For New Entrants and Emerging Players: Anchor in community healthcare centers across Galway, Limerick, and Waterford where integrated soft FM penetration remains underdeveloped. Target primary care estates with modular service bundles that separate cleaning and catering from hard FM maintenance. Pursue technology certification through the National Standards Authority of Ireland as the primary go-to-market credential. For Investors and Strategic Acquirers: The EU Energy Performance of Buildings Directive transposition through Irish building control regulations reshapes the acquisition landscape toward technology-certified operators with sub-metering and automated reporting capabilities. Viability over the coming decade hinges on regulatory compliance infrastructure rather than scale alone. Target mid-sized Irish specialists with entrenched public sector relationships and incomplete digital capability stacks. Watch SEAI retrofit grant disbursement velocity as the signal indicating capital commitment timing from estate managers.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Certification Investment | National Standards Authority of Ireland quality management certification filters vendor eligibility for Office of Government Procurement frameworks. |
| IoT Platform Integration | Wireless sensor networks for HVAC performance monitoring compress commissioning costs and enable condition-based maintenance at mid-sized estates. |
| Healthcare Estate Specialization | Clinical engineering and medical gas maintenance competencies address Health and Safety Authority risk assessment mandates in acute care facilities. |
| Regional Coverage Expansion | Service delivery infrastructure in Cork, Galway, and Limerick corridors captures logistics corridor security and preventive maintenance demand. |
| Energy Retrofit Capability Buildout | SEAI building energy rating obligations redirect capital expenditure toward HVAC upgrades and sub-metering installations across commercial portfolios. |
Study Parameters
A spread of perspectives from estate managers, facilities directors at pharmaceutical manufacturing sites, procurement officers within the Office of Government Procurement, and technical directors at FM contractors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Health and Safety Authority enforcement data, SEAI grant disbursement records, and National Standards Authority of Ireland certification registries. Bottom-up contract value estimates triangulated against top-down sector expenditure benchmarks.
Segmentation dimensions modeled span service type, end user vertical, facility category, and contract structure across the analysis window. Hard FM maintenance, soft FM cleaning, security services, and integrated bundled offerings were tracked separately. Healthcare, commercial, industrial, and educational end-use patterns were distinguished. CAGRs derived from regression against macroeconomic indicators and regulatory compliance timeline acceleration. Forecast inputs included SEAI retrofit grant pipeline velocity and Health and Safety Authority audit frequency trends.
Material uncertainties — regulatory enforcement intensity, specialized labor wage inflation, and UK-Ireland service flow friction — sit outside the modeled envelope. Forecasts reflect assumptions about continued outsourcing conversion in public sector estates and sustained pharmaceutical manufacturing investment in Cork and Dublin. Revision becomes warranted when SEAI grant allocation crosses thresholds that materially accelerate or decelerate estate manager capital commitment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Romania Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
Japan Facility Management Market