
 Switzerland Facility Management Market | 2026-2036
Switzerland Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Facility Management Market Analytics
ISO 41001 certification is unwinding competitive barriers across Swiss facility management, forcing smaller operators toward accreditation investments that mid-tier rivals struggle to fund. ISS Switzerland AG leverages its Nordic-origin compliance protocols to anchor premium contracts in Geneva's pharmaceutical corridor. SPIE Switzerland competes through energy management system integration, while Sodexo SA sustains institutional scale across Lausanne's university and hospital clusters. Honegger AG differentiates via alpine-region maintenance specialization where geographic fragmentation rewards local presence.
Facility management encompasses the coordinated delivery of hard services (mechanical, electrical, HVAC) and soft services (cleaning, security, catering) to ensure built environments meet operational, safety, and occupant-experience standards. The discipline relies on SLAs defining response times, uptime thresholds, and energy performance benchmarks tailored to asset criticality. Maintenance Services commands the largest value pool given Switzerland's aging commercial stock and stringent cantonal building codes, while Integrated Workplace Management represents the fastest-expanding technology segment as hybrid work patterns reshape space utilization. Corporate Offices drive outsized demand within the End User dimension, though Healthcare Facilities offer superior margin profiles tied to regulatory complexity.
Swissmedic standards for healthcare facility hygiene and the Swiss Society of Engineers and Architects (SIA) energy codes jointly elevate service specifications and vendor qualification burdens across the market. The Federal Office for the Environment (FOEN) carbon reduction mandates for commercial buildings further tighten operational compliance requirements, directing procurement toward technology-enabled FM providers. Stakeholders must weigh whether to build in-house digital capabilities or partner with platform-integrated specialists as compliance automation becomes inseparable from contract viability.
Market Dynamics
ISO 41001 certification mandates are compressing vendor viability windows across Switzerland, forcing capital-constrained operators into accreditation investments that reshape competitive tiers before contract renewal cycles complete.
Growth Catalysts
- Swissmedic compliance automation:Healthcare facilities face escalating hygiene audit frequencies, driving outsourced FM contracts toward technology-integrated providers capable of real-time documentation.
- Alpine commercial stock aging:Cantonal building codes mandate energy retrofit timelines for structures exceeding 25 years, expanding maintenance service addressable demand.
- Zurich workplace densification:Hybrid work patterns concentrate premium tenants into Class A commercial cores, elevating integrated workplace management platform requirements.
Market Restraints
- Specialized technician scarcity:HVAC and building automation skill gaps in Ticino and Graubünden extend response time SLAs beyond competitive thresholds.
- Energy input cost volatility:Commercial electricity rate fluctuations in Vaud and Geneva compress fixed-price contract margins for mid-tier operators.
- Cantonal regulatory fragmentation:Divergent enforcement interpretations of SIA energy codes across 26 cantons inflate compliance overhead for national-scale providers.
Strategic Opportunities
- Basel pharmaceutical corridor expansion:Life sciences manufacturing growth creates demand for GMP-aligned facility management with contamination control specialization.
- FOEN carbon mandate acceleration:Federal building performance standards tighten operational emission thresholds, positioning energy management system integrators for premium pricing.
- IoT-BIM convergence:Digital twin deployment for predictive maintenance opens service differentiation pathways beyond traditional SLA competition.
Industry Challenges
- ISO 41001 certification timeline compression:Three-year accreditation cycles strain smaller operators balancing audit preparation against active contract delivery.
- Legacy BMS integration friction:Proprietary building management protocols in 1990s-era commercial stock impede sensor network standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Facility Management Market |
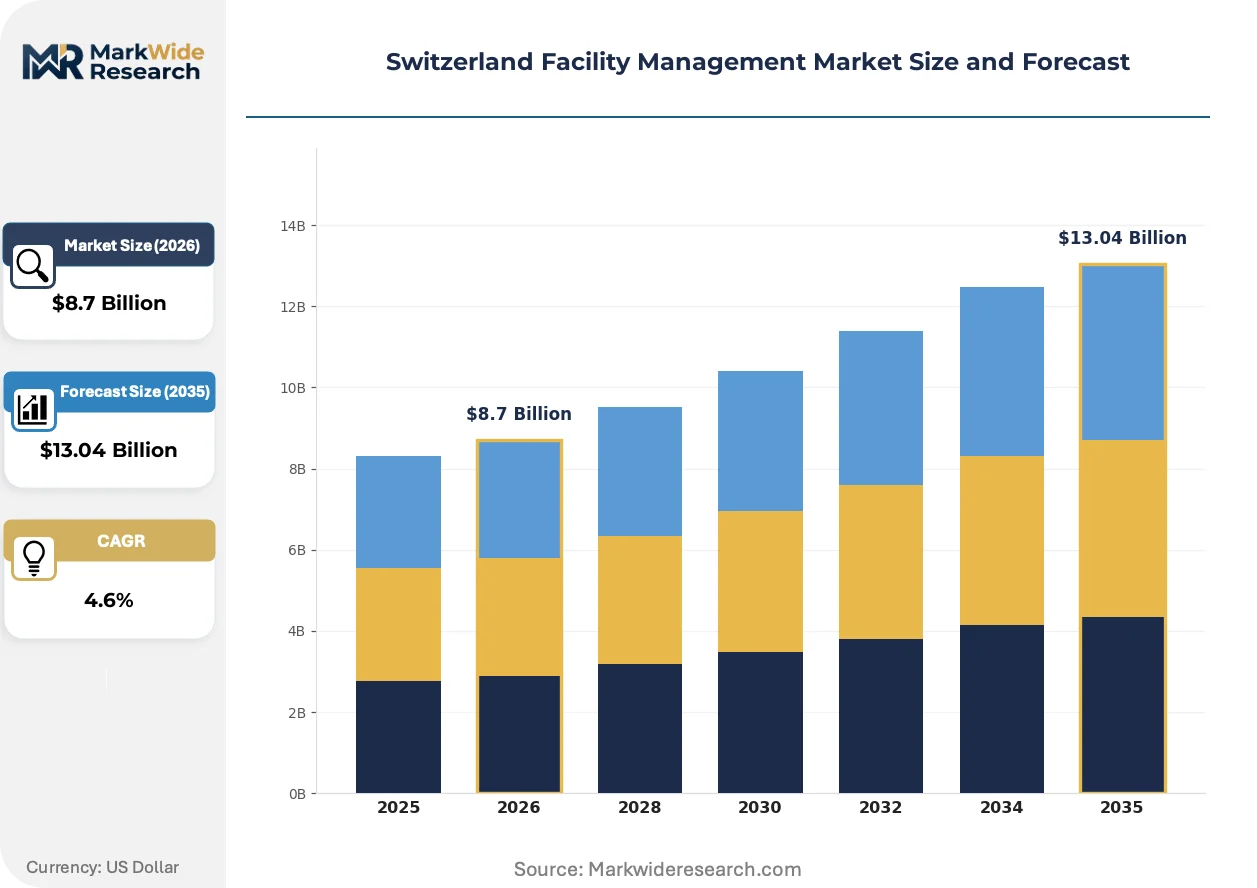
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
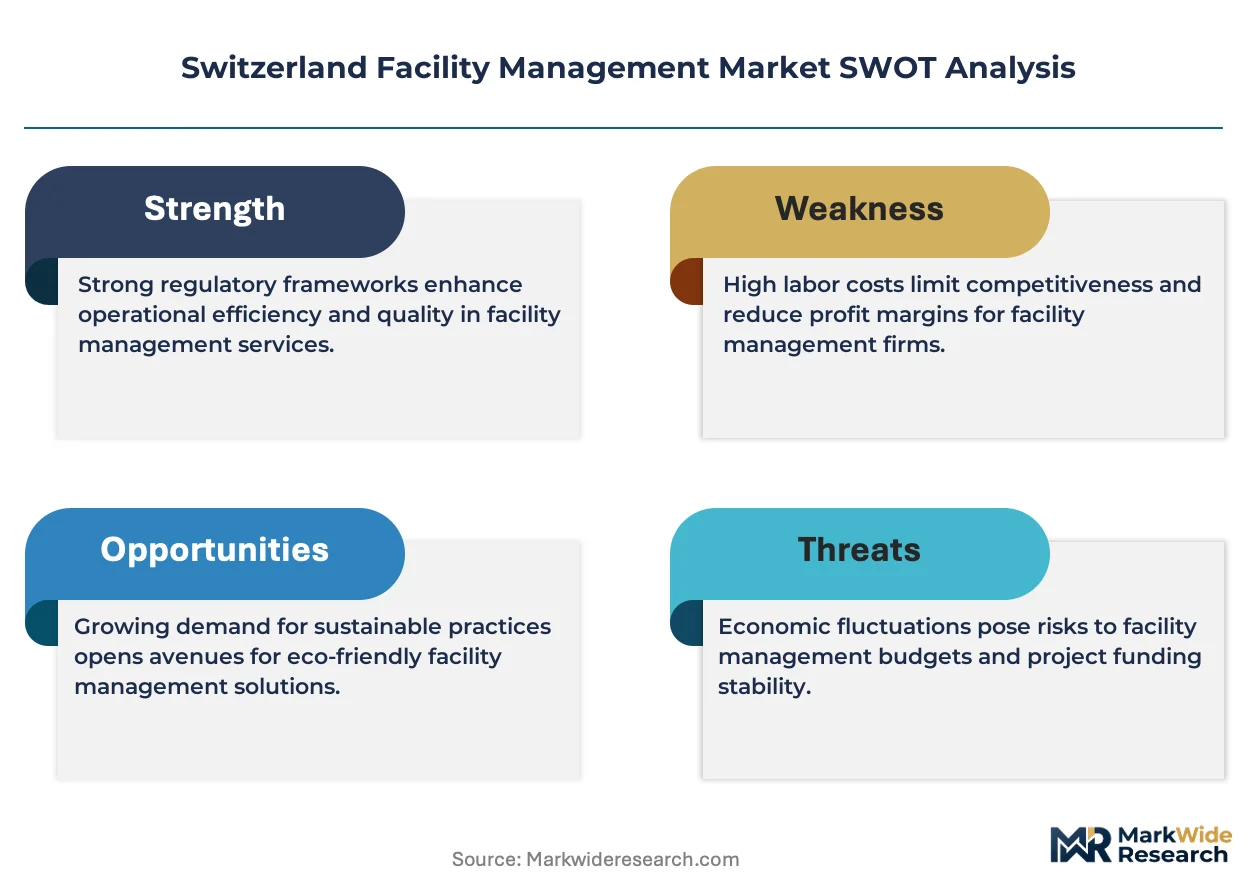
| Segmentation | Service Type: Cleaning Services, Maintenance Services, Security Services, Landscape Management End User: Corporate Offices, Educational Institutions, Healthcare Facilities, Government Buildings Technology: Building Automation, Energy Management Systems, Smart Lighting, Integrated Workplace Management Facility Type: Commercial Spaces, Residential Complexes, Industrial Properties, Hospitality Locations |
| Companies Covered | ISS Switzerland AG, Honegger AG, Swiss FM AG, Livit FM Services Ltd., PHM Group, SPIE Switzerland, Sodexo SA, Apleona Switzerland Ltd, CBRE Group, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Facility Management Market Evolving Landscape
Facility management technology deployment is splitting along capability lines, separating platform-integrated operators from labor-dependent competitors as compliance automation becomes a contract prerequisite rather than a value-add.
Integrated workplace management systems are bifurcating competitive positioning across Swiss commercial real estate. These platforms consolidate space booking, asset tracking, and energy analytics into unified dashboards. Zurich and Geneva corporate occupiers now mandate IWMS integration in RFPs for contracts exceeding five years. This capability divide is compressing viable vendor pools toward technology-capable specialists while marginalizing traditional service bundlers.
Swiss Society of Engineers and Architects energy code revisions are tightening operational performance thresholds for commercial buildings. The 2024 SIA 380/1 updates mandate granular energy reporting that legacy manual systems cannot satisfy. Basel and Bern healthcare facilities face the steepest compliance ramps, accelerating procurement shifts toward providers with automated metering infrastructure.
Hybrid work permanence is reshaping space utilization analytics demand across Lausanne and Zürich corporate portfolios. Occupancy sensor networks now anchor contract negotiations, replacing fixed cleaning schedules with usage-triggered service delivery. Financial services tenants in Paradeplatz and St. Galler Kantonalbank headquarters drive this behavioral shift, unbundling traditional bundled service pricing into consumption-indexed structures.
Switzerland Facility Management Market Segmentation
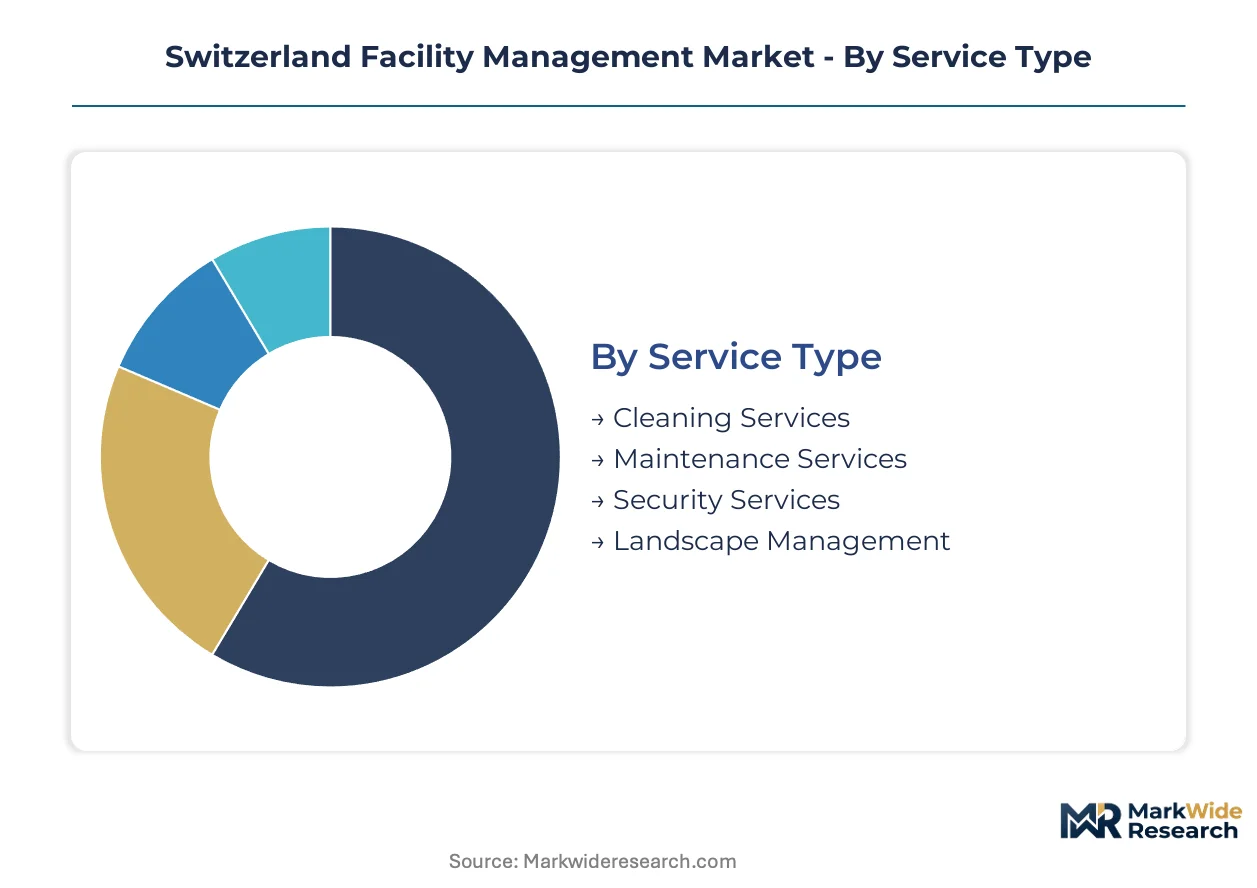
Service differentiation across Swiss facility management hinges on compliance automation capabilities and cantonal regulatory alignment. Segmentation reveals where technology-enabled operators capture premium pricing versus labor-dependent competitors facing margin compression.
Service Type:
Margin pools concentrate in technical services where certification barriers and equipment intensity protect pricing power from commoditization pressures.
- Maintenance Services:Encompasses mechanical, electrical, and HVAC systems upkeep governed by SIA energy codes and cantonal building regulations. Demand clusters in Zurich and Basel commercial cores where aging stock exceeds 25 years and retrofit timelines compress vendor selection windows.
- Cleaning Services:Covers daily hygiene operations, waste management, and specialized decontamination for healthcare environments. Swissmedic audit frequency escalation in Geneva and Lausanne hospital clusters is pushing contracts toward providers with real-time documentation platforms.
- Security Services:Physical access control, surveillance systems, and emergency response coordination.
- Landscape Management:Alpine-region grounds maintenance and seasonal snow removal operations.
Maintenance Services holds installed capacity. Integrated Workplace Management is rotating up the share rankings.
End User:
Customer concentration patterns split between volume-driven corporate portfolios and margin-rich regulated environments.
- Healthcare Facilities:Hospitals, clinics, and pharmaceutical manufacturing sites requiring GMP-aligned contamination control and Swissmedic hygiene compliance. Basel's life sciences corridor and Zurich university hospitals anchor demand for specialized FM with audit-ready documentation systems.
- Corporate Offices:Class A commercial towers and hybrid-work-optimized spaces across Paradeplatz and St. Galler Kantonalbank headquarters. IWMS platform mandates in RFPs for contracts exceeding five years are filtering vendor pools toward technology-integrated specialists.
- Educational Institutions:Universities and research facilities with seasonal occupancy variability.
- Government Buildings:Federal and cantonal administrative facilities subject to FOEN carbon reduction mandates.
Corporate Offices command transaction volume. Healthcare Facilities are climbing the fastest on margin contribution.
Technology:
Technology deployment separates platform-integrated operators from labor-dependent service bundlers as compliance automation becomes a contract prerequisite.
- Integrated Workplace Management:Unified dashboards consolidating space booking, asset tracking, and energy analytics. Zurich and Geneva occupiers now mandate IWMS integration for premium contracts, marginalizing traditional operators lacking digital infrastructure.
- Energy Management Systems:Automated metering infrastructure and consumption analytics enabling SIA 380/1 compliance reporting. Basel and Bern healthcare facilities face the steepest regulatory ramps, accelerating procurement shifts toward system-integrated providers.
- Building Automation:Sensor networks and control systems for HVAC and lighting optimization.
- Smart Lighting:Occupancy-triggered illumination systems reducing energy expenditure.
Building Automation holds legacy deployment base. Energy Management Systems are gaining share fastest on regulatory tailwinds.
Facility Type:
Asset class characteristics dictate service specification intensity and contract duration patterns across the vendor base.
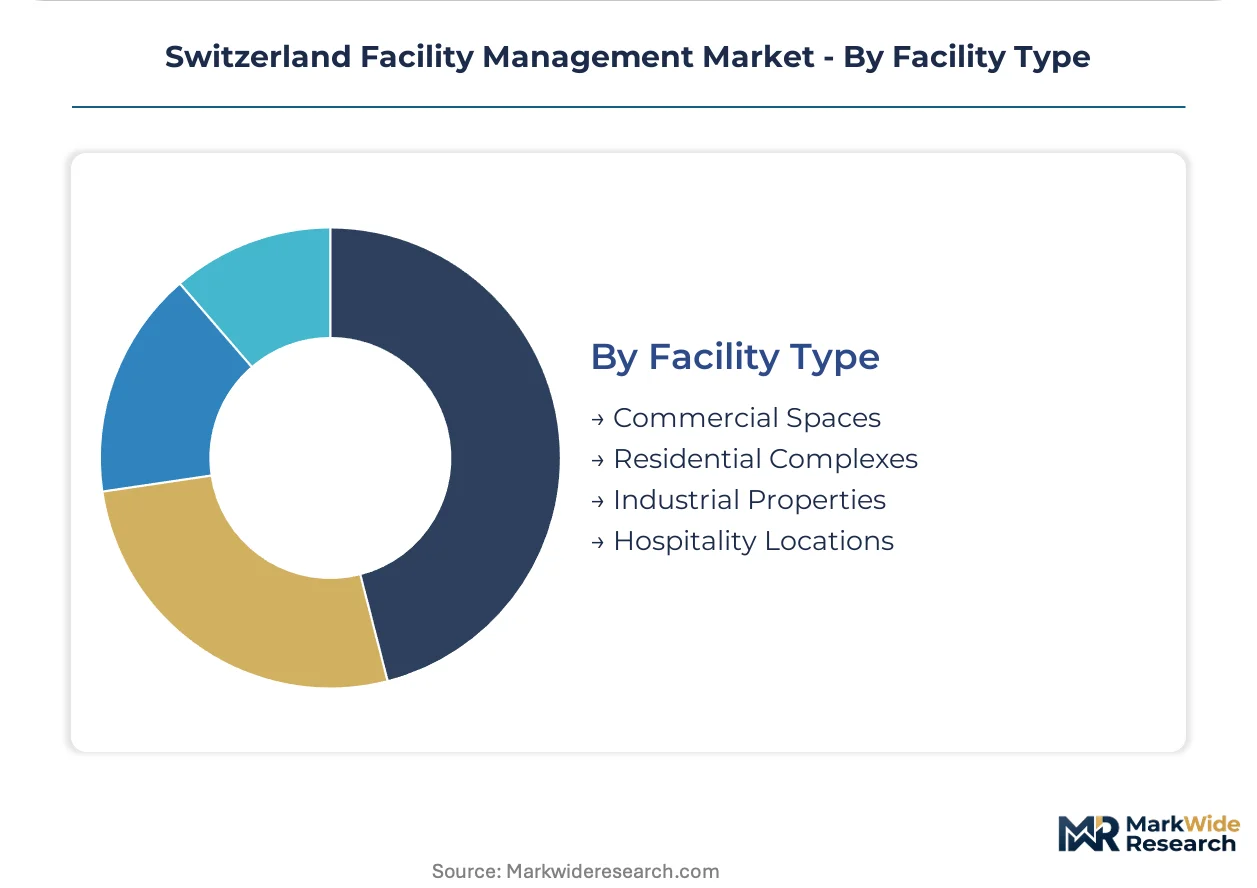
- Commercial Spaces:Office towers, retail centers, and mixed-use developments in Zurich's financial district. Hybrid work permanence is reshaping space utilization analytics demand, with occupancy sensor networks now anchoring contract negotiations and unbundling fixed-price structures.
- Industrial Properties:Manufacturing facilities and logistics hubs requiring specialized maintenance protocols. Ticino and Graubünden technician scarcity for HVAC and building automation extends response time SLAs beyond competitive thresholds in these locations.
- Residential Complexes:Multi-unit housing with standardized service requirements.
- Hospitality Locations:Hotels and conference centers with seasonal demand fluctuations.
Commercial Spaces anchor contract value. Industrial Properties are expanding most quickly on pharmaceutical corridor growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal cantonal energy mandates and Swissmedic hygiene standards are redistributing facility management procurement across Switzerland's linguistic and economic regions, concentrating contracts with technology-enabled providers capable of automated compliance documentation.
Zurich and Zug
Class A commercial towers in Paradeplatz and St. Galler Kantonalbank headquarters anchor Integrated Workplace Management demand. Hybrid work permanence is reshaping space utilization analytics, with occupancy sensor networks now unbundling fixed-price cleaning schedules into consumption-indexed service structures.
Basel
Life sciences manufacturing growth creates demand for GMP-aligned facility management with contamination control specialization. Swissmedic audit frequency escalation in pharmaceutical corridors pushes contracts toward providers with real-time documentation platforms and automated metering infrastructure.
Geneva
International organization headquarters and luxury hospitality clusters drive premium service specifications. FOEN carbon reduction mandates for commercial buildings tighten operational emission thresholds, directing procurement toward energy management system integrators.
Lausanne and Bern
University hospital clusters and federal administrative facilities subject to SIA 380/1 energy code revisions face steep compliance ramps. Healthcare facilities here accelerate procurement shifts toward providers with automated metering infrastructure capable of granular energy reporting.
Ticino and Graubünden
Alpine-region maintenance specialization rewards local presence where geographic fragmentation elevates response time requirements. HVAC and building automation skill gaps extend SLAs beyond competitive thresholds, creating defensive moats for established operators with technician retention programs.
Switzerland Facility Management Market Competitive Landscape
Listed leaders compete with private specialists across technology integration capabilities, with publicly traded operators leveraging capital market access for platform investments while family-owned cantonal providers defend share through relationship density and alpine-region technician networks. The vendor base stratifies into three tiers: multinational platform-integrated operators, mid-tier accreditation-chasing specialists, and geographic niche defenders. Competitive moves concentrate on ISO 41001 certification acceleration and IWMS platform partnerships.
Within the multinational tier, ISS Switzerland AG and Sodexo SA exemplify scale-driven operators leveraging Nordic-origin compliance protocols and institutional scale respectively. SPIE Switzerland occupies a position among energy management system integrators competing through technical service intensity. These three represent contrasting archetypes: compliance-anchored premium positioning, volume-driven institutional coverage, and engineering-specialized energy performance contracting.
| Leading Market Players |
|---|
| ISS Switzerland AG |
| Honegger AG |
| Swiss FM AG |
| Livit FM Services Ltd. |
| PHM Group |
| SPIE Switzerland |
| Sodexo SA |
| Apleona Switzerland Ltd |
| CBRE Group, Inc. |
| Others |
Value Network & Pricing Analysis
Thirty-to-forty-five-day certification lead times for ISO 41001 auditors in Switzerland concentrate pricing power among pre-accredited operators while compressing margins for latecomers chasing compliance windows. This inventory-of-capacity dynamic shapes how procurement teams weight vendor qualification status against unit service costs across cantonal contracts.
Pricing Analysis
Certification level creates the primary spread between premium and standard service tiers in Swiss facility management. Three-tier pricing structure across certified-integrated, accredited-basic, and non-certified labor-dependent levels dominates contract structures. Price differentiation stems from Swissmedic audit-readiness technology and SIA energy code reporting automation. Cost compression in the non-certified tier is intensifying because FOEN carbon mandate acceleration forces retrospective platform investments. Healthcare facilities show least price sensitivity given contamination control liability exposure, while municipal government buildings drive hardest bargain terms.
Supply Chain Analysis
Just-in-time technician deployment preferences dominate Swiss facility management, though alpine-region operators maintain strategic stockpiles of HVAC components given Graubünden and Ticino access constraints. Geographic supply concentrates in Germany for building automation hardware, Italy for HVAC equipment, and domestic Swiss sources for compliance-certified maintenance consumables. Raw material dependencies span copper wiring, refrigerants, and IoT sensor arrays. Single-source vulnerability runs through German-engineered BMS controllers given proprietary protocol lock-in. Distribution runs through cantonal procurement consortia with Zurich and Geneva anchoring volume allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent facility management operators face substitution pressure from software-native workplace platform providers unbundling traditional service bundles into consumption-indexed digital contracts.
For Market Incumbents: Secure ISO 41001 certification acceleration ahead of contract renewal cycles in Basel and Zurich healthcare corridors. Lock in technician retention programs for Graubünden and Ticino where HVAC skill scarcity extends competitor response times beyond SLA thresholds. Backward integration into energy management system development defends margin position against SPIE Switzerland's engineering-specialized positioning.
For New Entrants and Emerging Players: Lead with IoT-BIM convergence offerings targeting 1990s-era commercial stock in Bern and Lausanne where legacy BMS integration friction marginalizes established operators. White-space concentration sits in pharmaceutical manufacturing facility management around Basel's life sciences corridor where GMP-aligned contamination control specialization commands premium pricing. Channel strategy should prioritize direct engagement with university hospital procurement committees bypassing incumbent relationship density.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across Integrated Workplace Management platform segments as IWMS integration becomes mandatory in RFPs. Long-term viability favors operators with installed technician networks in alpine regions where geographic fragmentation creates defensive moats. Acquisition target archetype: cantonal specialists with Swissmedic audit-ready documentation systems and FOEN compliance automation capabilities. Signal to watch is FOEN carbon mandate enforcement acceleration triggering procurement preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 41001 Certification Acceleration | Swissmedic tightening compliance standards forces accreditation investments before contract renewal windows close. |
| IWMS Platform Partnership | Zurich and Geneva occupiers mandate integrated workplace management integration for premium commercial contracts. |
| Energy Management System Integration | FOEN carbon reduction mandates position automated metering infrastructure providers for premium pricing power. |
| Alpine-Region Technician Network Expansion | Graubünden and Ticino HVAC skill gaps extend response time SLAs beyond competitive thresholds. |
| Pharmaceutical Corridor Specialization | Basel life sciences manufacturing growth creates demand for GMP-aligned contamination control facility management. |
Research Methodology
Desk research of Swiss regulatory filings, SIA energy code documentation, and cantonal procurement records preceded structured interviews with facility management operations directors, healthcare estate managers, pharmaceutical manufacturing site directors, and commercial real estate portfolio managers. Primary fieldwork combined with secondary validation against FOEN carbon mandate publications, Swissmedic hygiene audit protocols, and ISO 41001 certification body records. Bottom-up service-type demand modeling and top-down macroeconomic triangulation anchored value estimates.
Variance decomposition across service type, end user, technology deployment, and facility type segmentation dimensions shaped analytical framework construction throughout the forecast period. CAGRs derived from installed base aging curves, regulatory compliance timeline acceleration, and hybrid work pattern permanence assumptions. Forecast inputs incorporated SIA 380/1 energy code revision enforcement schedules and Swissmedic audit frequency escalation trajectories.
The analysis sits within stated boundaries; outcomes outside sustained FOEN mandate enforcement or Swissmedic audit standardization would require recalibration. Forecasts reflect documented assumptions regarding technician labor market tightness and IWMS platform adoption curves. Revision becomes warranted when ISO 41001 certification timeline compression crosses thresholds forcing mass operator consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Norway Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Asia-Pacific Soft Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
Austria Facility Management Market
Facility Management
Portugal Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Bulgaria Facility Management Market