
 Oman Facility Management Market | 2026-2036
Oman Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Facility Management Market Analytics
ISO-certified integrated facility management is collapsing the gap between basic maintenance and full-service asset stewardship across Oman's commercial property base. Renaissance Services SAOG leverages its oilfield heritage to dominate industrial facility contracts in Sohar and Duqm. Al Nab'a Holding anchors government and healthcare portfolios through long-term service agreements. Qurum Business Group competes on technology-enabled cleaning and security bundles for hospitality clients in Muscat.
Facility management encompasses the professional coordination of building operations, maintenance, and support services to ensure functional, safe, and efficient built environments, typically governed by service level agreements specifying response times, uptime thresholds, and compliance metrics. Its primary purpose is to preserve asset value while reducing operational lifecycle costs for property owners and occupiers. Maintenance and security services command the largest revenue pools due to mandatory regulatory compliance and round-the-clock operational requirements. IoT and building automation segments are expanding fastest as property managers deploy sensor networks and predictive analytics to reduce energy waste and equipment downtime.
Oman's Ministry of Regional Municipalities and Water Resources and the Directorate General of Specifications and Measurements enforce building codes and energy efficiency standards that mandate regular facility audits and sustainable operations. Compliance with these frameworks shapes procurement decisions, particularly for government and healthcare end users seeking certified service providers. Stakeholders must monitor evolving green building mandates and digital twin adoption requirements as these will determine qualification for premium contracts and public-private partnership opportunities.
Market Dynamics
Oman's facility management sector is being restructured by mandatory energy audit requirements under the Ministry of Regional Municipalities and Water Resources building codes, which force commercial property owners toward certified integrated service providers.
Growth Catalysts
- National health infrastructure expansion:Healthcare facilities are extending outsourced maintenance contracts as Oman builds new hospitals and specialty clinics under Vision 2040 targets.
- ISO 41001 certification mandate:Government procurement frameworks now require facility management contractors to hold asset management certification, filtering out informal operators.
- Muscat hospitality clustering:Hotel and resort developments in the capital are bundling cleaning, security, and engineering services into single-source contracts.
Market Restraints
- Specialized technician scarcity:HVAC and building automation expertise concentrates in Muscat, leaving interior regions dependent on fly-in contractors.
- Import dependency for smart building components:IoT sensors and energy management systems rely on suppliers from the UAE and Europe, exposing contracts to currency fluctuation.
- Duqm industrial zone distance:Remote project sites face 500+ kilometer supply chains from established service hubs, inflating mobilization costs.
Strategic Opportunities
- Salalah port zone development:The southern logistics corridor lacks established facility management capacity, creating first-mover positioning for integrated operators.
- Predictive maintenance convergence:Machine learning diagnostics combined with drone-based building inspections can compress response times for coastal industrial clients.
- Green building incentive alignment:Oman's national energy efficiency program offers tariff rebates for properties achieving LEED or Estidama certification, pulling demand toward audited service packages.
Industry Challenges
- BIM integration complexity:Digital twin adoption for existing government buildings requires retrofitting legacy asset databases, extending contract onboarding timelines.
- Multi-site workforce coordination:Managing simultaneous operations across Muscat, Sohar, and Duqm demands real-time Arabic-English dispatch systems that few regional providers have deployed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Facility Management Market |
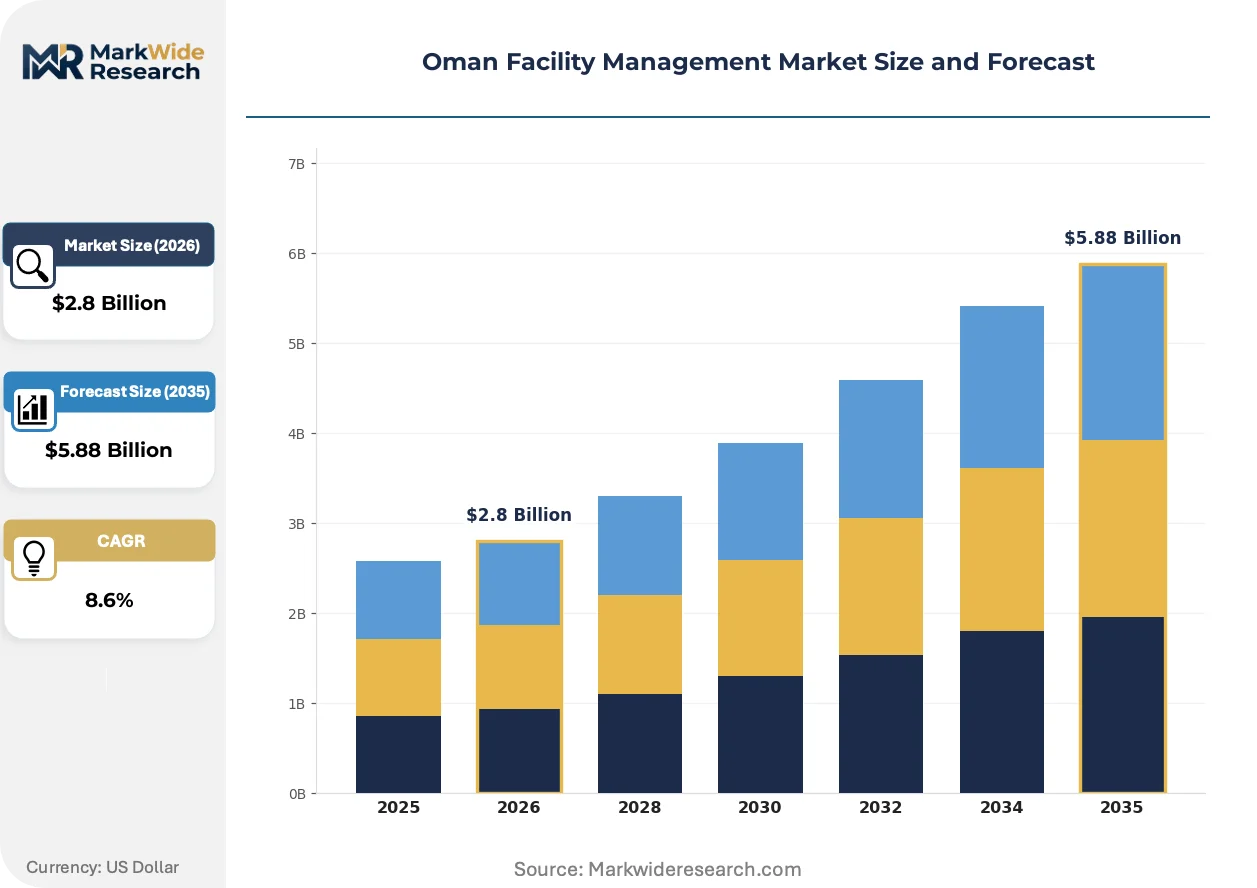
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Government, Healthcare, Hospitality, Education Technology: CMMS, IoT, Building Automation, Energy Management Deployment: In-house, Outsourced, Hybrid, Integrated |
| Companies Covered | Al Nab'a Holding, COMO Oman, Renaissance Services SAOG, ACCIONA, Omdaad, G4S Limited, Oman International Group SAOC, Al Khidr Trading & Contracting, Qurum Business Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Facility Management Market Evolving Landscape
Facility management in Oman is pivoting from reactive maintenance toward sensor-driven asset stewardship, with technology vendors and service integrators competing to own the data layer between buildings and their operators.
Cloud-based energy management platforms are supplanting manual meter-reading and spreadsheet-based tracking in commercial properties. Muscat-based hotel operators and government complexes are adopting these systems fastest, drawn by real-time visibility into consumption patterns. The shift is compressing margins for traditional maintenance-only contractors while elevating technology-enabled service bundles.
The Ministry of Regional Municipalities and Water Resources is tightening enforcement of building energy codes that mandate annual audits and corrective action plans. Property managers now face fines for non-compliance, driving procurement toward certified auditors with integrated remediation capabilities. Healthcare and education facilities are responding by embedding compliance costs into multi-year service agreements.
Buyers are consolidating vendor relationships from fragmented specialty contracts toward single-source integrated agreements. Hospitality groups in Muscat and industrial operators in Sohar are leading this consolidation, replacing separate cleaning, security, and engineering contracts with unified SLAs. The compression is most visible in government tendering, where bundled technical and soft services now dominate scoring criteria.
Oman Facility Management Market Segmentation
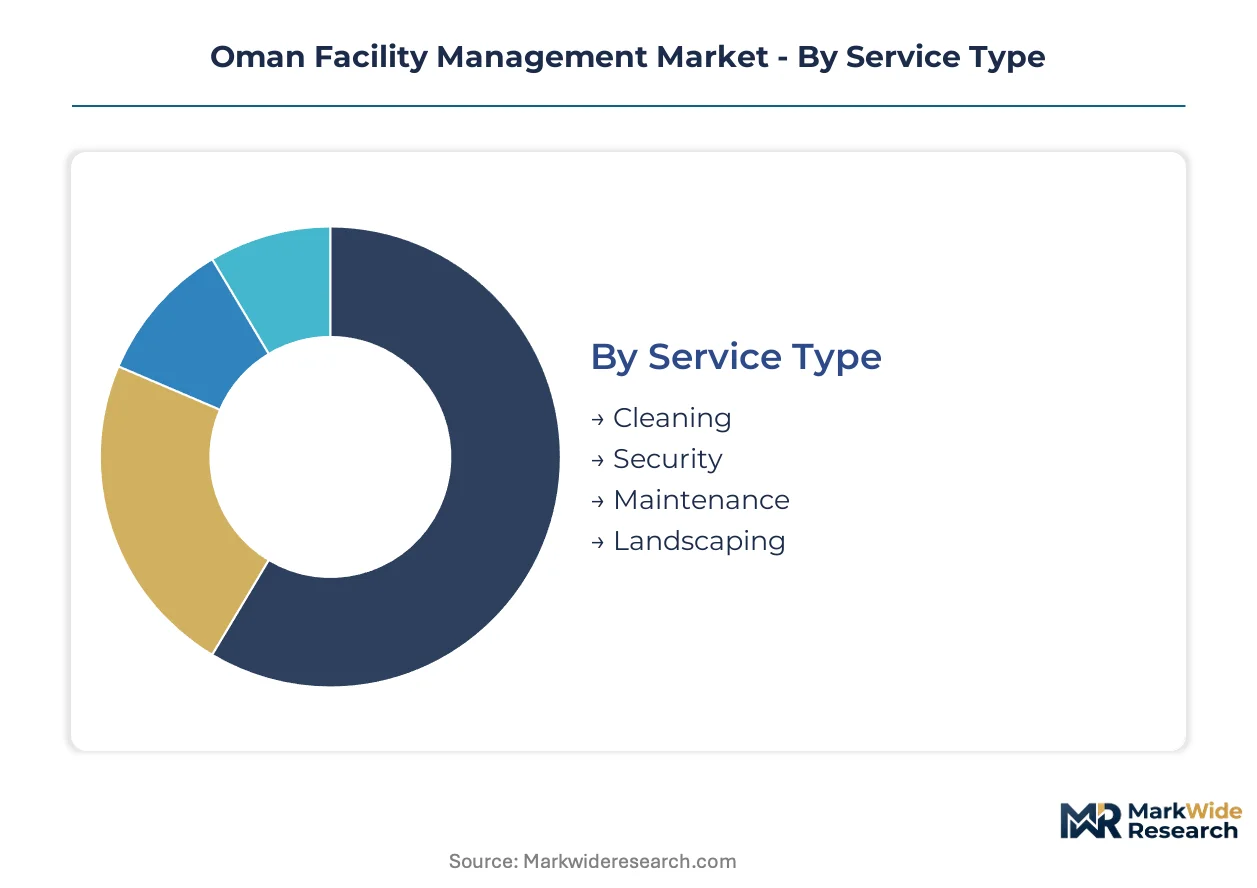
Facility management procurement in Oman fragments across service maturity levels and asset complexity tiers. Understanding these divisions reveals where ISO 41001 certification creates competitive moats versus where informal operators still compete on price.
Service Type:
Geographic concentration varies sharply: maintenance and security contracts concentrate in Muscat's government and hospitality clusters, while landscaping demand spreads across coastal tourism developments and interior municipal contracts.
- Maintenance:Encompasses HVAC, electrical, and mechanical systems upkeep with mandatory response-time SLAs. Demand concentrates in healthcare facilities under Oman's national health infrastructure expansion, where uptime thresholds are non-negotiable and penalties for failure are severe.
- Security:Includes manned guarding, access control, and surveillance systems deployment. Government complexes and hospitality clusters in Muscat drive volume, with integrated security-technology bundles displacing standalone guarding contracts.
- Cleaning:Covers janitorial, specialized healthcare sanitation, and industrial cleaning protocols. Hotels and resorts in the capital bundle this with security under single-source agreements.
- Landscaping:Comprises grounds maintenance, irrigation systems, and hardscape preservation for commercial properties. Municipal contracts in regional centers and tourism zone developments in Salalah generate intermittent but high-value project demand.
Maintenance commands the established base. The steepest expansion runs through security as technology integration elevates contract values.
End User:
Cost tier stratification separates premium certified providers serving compliance-heavy sectors from price-competitive operators in less regulated segments.
- Government:Encompasses ministry buildings, military installations, and public infrastructure facilities. ISO 41001 certification is now mandatory for tender qualification, filtering procurement toward established integrated operators with multi-site capability.
- Healthcare:Covers hospitals, specialty clinics, and diagnostic centers with stringent infection control and equipment uptime requirements. New hospital construction under Vision 2040 targets is extending outsourced maintenance contract durations.
- Hospitality:Includes hotels, resorts, and conference facilities requiring 24/7 operational continuity. Muscat's clustering of international hotel brands is consolidating vendor relationships toward bundled technical and soft services.
- Education:Comprises schools, universities, and training institutions with seasonal occupancy patterns and budget-constrained procurement cycles. Facility audits mandated by the Ministry of Regional Municipalities are pulling this sector toward certified providers.
Government contracts anchor the revenue base. Healthcare is climbing the fastest as infrastructure expansion outpaces in-house technical capacity.
Technology:
Application maturity separates legacy-dependent segments from predictive platforms gaining traction in premium commercial properties.
- IoT:Sensor networks for occupancy detection, equipment monitoring, and environmental tracking. Muscat-based hotel operators and government complexes are deploying these systems to compress energy waste and maintenance response times.
- Building Automation:Integrated control systems for HVAC, lighting, and security with centralized monitoring dashboards. New commercial developments in Muscat and Sohar specify these as baseline requirements, retrofitting demand lags in existing stock.
- CMMS:Computerized maintenance management systems for work order tracking and asset lifecycle documentation. Healthcare and government facilities use these to satisfy audit requirements and demonstrate compliance to regulators.
- Energy Management:Platforms for consumption monitoring, tariff optimization, and renewable integration. Properties pursuing LEED or Estidama certification deploy these to capture tariff rebates under national energy efficiency programs.
CMMS holds the installed base. IoT is gaining share fastest as sensor costs decline and cloud platforms simplify deployment.
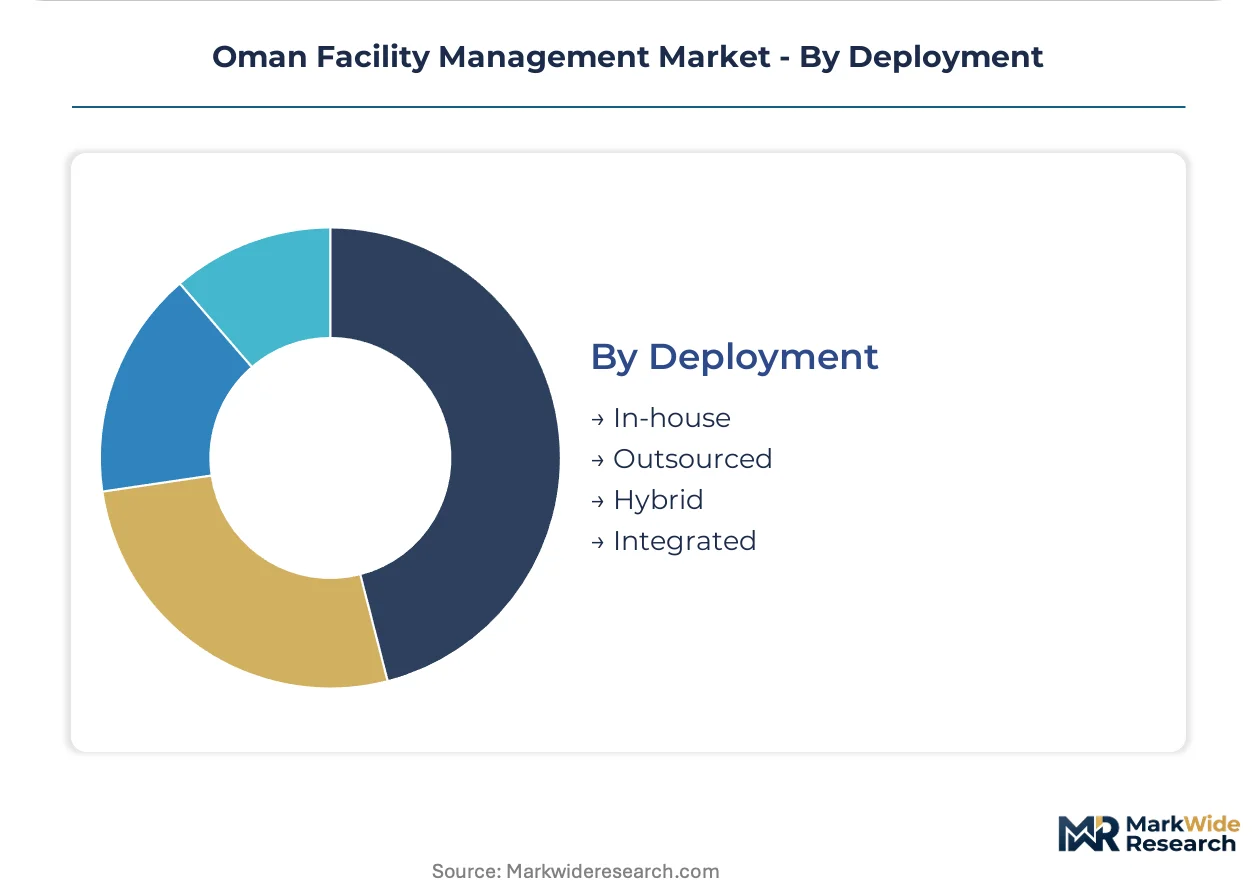
Deployment:
Customer type and asset scale determine whether owners retain capability in-house or externalize to specialized operators.
- Integrated:Single-source contracts bundling hard and soft services under unified SLAs with technology-enabled reporting. Government tendering now scores bundled technical and soft services highest, displacing fragmented procurement.
- Outsourced:Full externalization of facility operations to third-party providers with performance-based compensation. Hospitality groups in Muscat and industrial operators in Sohar favor this model to focus capital on core operations.
- Hybrid:Retained in-house oversight with contracted specialty services for technical disciplines like HVAC or security systems. Regional healthcare facilities use this to maintain clinical engineering expertise while outsourcing non-critical functions.
- In-house:Direct employment of maintenance and operations staff with limited contractor supplementation. Budget-constrained education facilities and legacy government buildings persist with this model despite compliance pressures.
Outsourced deployment dominates current contract value. Integrated agreements are expanding most quickly as procurement frameworks reward bundled service delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider networks concentrate along Oman's northern corridor, with established operators anchoring operations in Muscat and extending reach toward industrial zones in Sohar and Duqm. Interior regions remain dependent on fly-in technical teams due to sparse permanent infrastructure.
Muscat Governorate
Government complexes and hospitality clusters drive integrated facility services procurement under unified SLAs. The Ministry of Regional Municipalities and Water Resources enforces building energy codes mandating annual audits for commercial properties. City-center hotel operators are consolidating vendor relationships toward bundled technical and soft services.
Al Batinah South Governorate
Industrial facilities in Sohar Port and Freezone generate demand for heavy-asset maintenance and security services. The Special Economic Zone Authority regulates operational standards for manufacturing tenants. Sohar's aluminum smelter and petrochemical complexes anchor long-term outsourced maintenance contracts.
Al Wusta Governorate
Duqm Special Economic Zone construction is outstripping local facility management capacity, forcing 500-kilometer supply chains from Muscat service hubs. The Public Authority for Special Economic Zones and Free Zones mandates compliance frameworks for zone operators. Remote project sites face inflated mobilization costs and extended response times.
Dhofar Governorate
Salalah port zone and logistics corridor development lacks established integrated facility operators, creating positioning opportunities for first movers. The Special Economic Zone Authority at Duqm extends regulatory oversight to southern corridor planning. Tourism zone developments along the coast generate intermittent high-value landscaping and grounds maintenance demand.
Ad Dakhiliyah Governorate
Healthcare and education facilities in Nizwa and regional centers operate under budget-constrained procurement cycles with seasonal occupancy patterns. The Ministry of Health's regional directorates enforce infection control standards for hospital maintenance. Facility audits mandated by national building codes are pulling this interior zone toward certified service providers.
Oman Facility Management Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Oman's facility management sector. ISO 41001-certified integrated operators capture premium government and healthcare contracts through compliance capabilities, while price-competitive specialists retain footholds in less regulated segments. Three archetypes dominate: oilfield heritage industrial specialists, government-anchored diversified holding groups, and hospitality-focused technology bundlers. Competitive moves center on single-source contract consolidation and predictive maintenance platform deployment.
Among Omani holding groups, Al Nab'a Holding and Qurum Business Group exemplify divergent specialization paths—one anchoring government portfolios through long-term agreements, the other competing on technology-enabled service bundles for capital-based clients. Renaissance Services SAOG represents the oilfield heritage archetype, leveraging industrial asset expertise toward facility contracts in remote zones. These three occupy positions across the certification-tiered competitive map without overlapping core segments.
| Leading Market Players |
|---|
| Al Nab'a Holding |
| COMO Oman |
| Renaissance Services SAOG |
| ACCIONA |
| Omdaad |
| G4S Limited |
| Oman International Group SAOC |
| Al Khidr Trading & Contracting |
| Qurum Business Group |
| Others |
Value Network & Pricing Analysis
Scale economies in integrated service delivery concentrate pricing power among ISO 41001-certified operators while compressing margins for fragmented maintenance-only contractors across Muscat and Sohar. The Ministry of Regional Municipalities and Water Resources mandates energy audit compliance for commercial properties, creating tiered procurement thresholds that filter informal operators from government and healthcare contracts.
Pricing Analysis
ISO 41001 certification dictates the pricing tier structure across Oman's facility management sector, separating premium integrated operators from price-competitive specialists. Three-tier pricing structure across certified premium, compliance-standard, and informal economy levels reflects audit capability, technology bundling, and multi-site coordination scale. Pricing pressure stems from hospitality procurement consolidation in Muscat, where bundled technical and soft service contracts compress standalone maintenance margins. Government and healthcare buyers demonstrate lowest price sensitivity due to mandatory uptime SLAs and penalty structures, while education facilities remain most cost-constrained.
Supply Chain Analysis
Strategic stockpiling of IoT sensors and building automation components dominates inventory strategy as lead times from UAE and European suppliers expose contracts to currency fluctuation. Component sourcing concentrates in the UAE, Germany, and China for energy management systems, HVAC controls, and security technology hardware. Raw material dependencies span aluminum enclosures, semiconductor chips, and specialized cabling for industrial zone deployments. Single-source vulnerability runs through UAE-based sensor distributors serving the Muscat-Sohar corridor. Distribution runs through certified integrators who bundle hardware procurement with installation and compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified technician scarcity across HVAC and building automation disciplines constrains expansion capacity for operators seeking to capture healthcare and industrial contracts under Vision 2040 infrastructure targets.
For Market Incumbents: Compound technology-enabled service differentiation by deploying predictive maintenance platforms and drone-based inspection capabilities before emerging technology bundlers capture hospitality and coastal industrial accounts. Defend government portfolio positions through accelerated BIM integration for legacy asset digitization, as tender scoring increasingly weights digital twin readiness. Vertical integration into in-house technician training programs addresses fly-in contractor dependency for Duqm and Salalah remote site mobilization. For New Entrants and Emerging Players: Lead with Salalah port zone and southern logistics corridor positioning where established Muscat-based operators lack permanent infrastructure and face 500-kilometer supply chain disadvantages. Target first-mover integrated service contracts in Dhofar Governorate tourism developments and emerging logistics facilities before incumbent network extension. Pursue technology-forward positioning through cloud-based CMMS and Arabic-English dispatch system deployment to differentiate from legacy operators in regional healthcare and education procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ISO 41001-certified integrated operators with multi-site capability and established government relationships over fragmented maintenance specialists facing margin compression. Long-term viability rests on predictive analytics platform ownership and compliance audit capability as regulatory enforcement tightens across the analysis window. Acquisition target archetype: mid-scale operators with healthcare or industrial sector presence lacking technology infrastructure but holding compliant contract backlogs. Watch for inflection when Ministry of Regional Municipalities mandates digital twin submission for commercial property licensing.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Machine learning diagnostics compress response times for Sohar industrial clients and Muscat hospitality clusters. |
| ISO 41001 Certification Investment | Mandatory tender qualification for government and healthcare procurement under Ministry of Regional Municipalities frameworks. |
| Salalah Geographic Expansion | First-mover positioning in southern logistics corridor where 500-kilometer supply chains disadvantage incumbent Muscat operators. |
| Technician Training Program Development | In-house HVAC and automation expertise reduces fly-in contractor dependency for remote Duqm project sites. |
| BIM Integration for Legacy Assets | Digital twin capability elevates tender scoring for government building retrofits and public-private partnership opportunities. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings on procurement framework evolution and compliance mandate enforcement. Facility management executives, healthcare infrastructure planners, Ministry of Regional Municipalities compliance officers, hospitality procurement directors, and industrial zone operators provided operational perspective on contract structuring and technology adoption patterns. Secondary sources include Ministry of Regional Municipalities building code documentation, Directorate General of Specifications and Measurements energy efficiency standards, Vision 2040 infrastructure planning disclosures, and Special Economic Zone Authority operational regulations. Bottom-up service provider capability mapping triangulates against top-down contract value estimation across deployment models.
Sensitivity analysis on technician availability, currency fluctuation exposure, and regulatory enforcement timing shapes the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type maturity, end-user compliance tier, technology application level, and deployment model concentration. CAGRs derive from installed base expansion rates and new contract formation velocity by governorates. Forecast inputs incorporate healthcare infrastructure construction pipelines under Vision 2040 targets and hospitality development clustering patterns in Muscat.
The analysis sits within stated boundaries; outcomes outside sustained government infrastructure expenditure and regulatory enforcement continuity would require recalibration. Forecasts reflect assumptions on certification mandate adherence rates and technology platform adoption curves across commercial property segments. Revision becomes warranted when Ministry procurement framework modifications or Special Economic Zone regulatory shifts cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Facility Management Services Market
Facility Management
Soft Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Canada Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Greece Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Asia-Pacific Hard Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Argentina Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Global Facility Management Software Market