
 Singapore Facility Management Market | 2026-2036
Singapore Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Facility Management Market Outlook
Integrated energy management as a subscription layer is consolidating how facility operators package and sell ongoing building performance. Sodexo Singapore Pte. Ltd. leverages its food and facilities integration to anchor long-term corporate campus contracts. CBRE Group Inc. competes through technology-led asset management platforms that extend client retention across commercial portfolios. ENGIE Services Singapore dominates district cooling and energy performance contracting, positioning its engineering heritage against pure-play competitors.
Facility management encompasses the professional coordination of building operations, maintenance, and support services to ensure optimal functionality of physical infrastructure, typically governed by service level agreements specifying response times, uptime thresholds, and energy efficiency benchmarks. Its primary commercial purpose centers on reducing total cost of ownership for real estate assets while ensuring regulatory compliance and occupant productivity. Maintenance and cleaning services within the Service Type dimension represent mature, high-volume revenue pools where margin compression drives consolidation among mid-tier operators. IOT Solutions and Software Platforms across the Technology dimension capture the fastest expansion trajectory as building owners mandate predictive analytics and automated fault detection to meet tightening sustainability benchmarks.
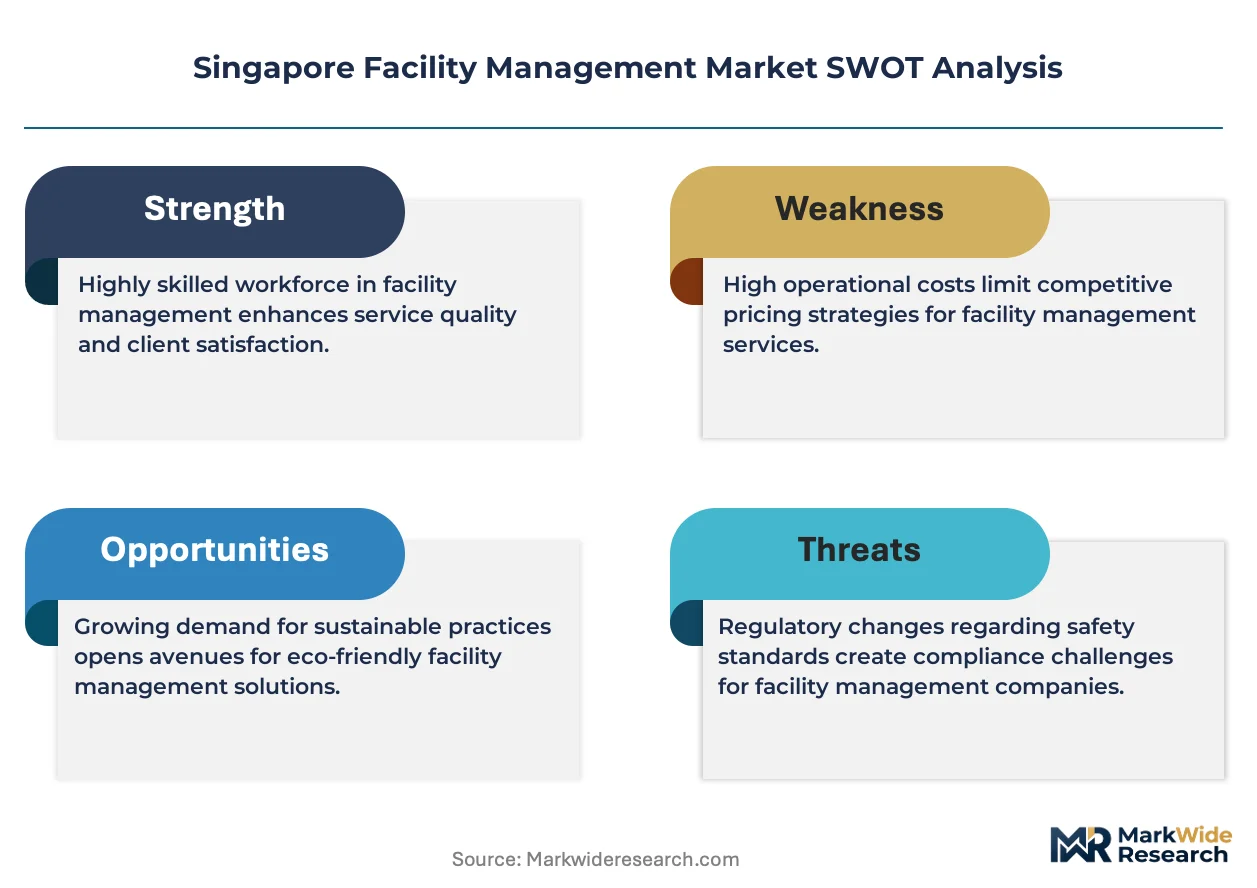
Singapore's Building and Construction Authority enforces Green Mark standards that compel facility managers to document energy performance and carbon reduction pathways, directly shaping procurement criteria for new service contracts. The country's national cybersecurity regulator imposes data protection requirements on connected building systems, restricting vendor selection to providers with certified information security management. The Energy Market Authority further influences demand through progressive grid integration rules that reward buildings with active load management capabilities. Stakeholders must weigh capital deployment across digital infrastructure against the operational flexibility required by evolving district-level energy regulations.
Market Dynamics
Singapore's Building and Construction Authority Green Mark certification mandates are compressing procurement cycles for facility management contracts, forcing operators to bundle energy performance guarantees with traditional maintenance services. This regulatory pressure is restructuring how contracts are awarded and priced across commercial developments.
Growth Catalysts
- Jurong Lake District mixed-use developments:Large-scale integrated projects require unified facilities oversight spanning office, retail, and residential functions, creating bundled service demand.
- Green Mark Platinum standards:The Building and Construction Authority's highest certification tier mandates documented carbon reduction pathways, compelling owners to contract for ongoing energy optimization.
- Internet of Things sensor networks:Predictive maintenance platforms using automated fault detection are reducing unplanned downtime in premium commercial assets.
Market Restraints
- Skilled technician shortage:Singapore's tight labor market limits availability of certified building systems engineers, constraining service expansion capacity.
- District cooling infrastructure concentration:Dependence on centralized plant operators in Marina Bay and Jurong creates single-point vulnerability for integrated energy contracts.
- Cybersecurity compliance costs:The national cybersecurity regulator's data protection requirements for connected building systems impose certification burdens that exclude smaller vendors.
Strategic Opportunities
- One-North research precinct:Biotech and infocomm facilities in this western corridor present specialized cleanroom and precision climate management demand.
- Energy Market Authority demand response incentives:Buildings with active load management capabilities qualify for grid integration rewards, creating performance contracting opportunities.
- Subscription-based energy management:Monthly service layers replacing capital-intensive equipment upgrades appeal to asset-light REIT structures.
Industry Challenges
- Building Management System integration complexity:Legacy BACnet and proprietary protocols resist seamless connection to cloud analytics platforms, delaying smart building deployments.
- Green Mark certification timeline pressure:Developers facing completion deadlines struggle to document performance benchmarks before occupancy certificates are issued.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Facility Management Market |
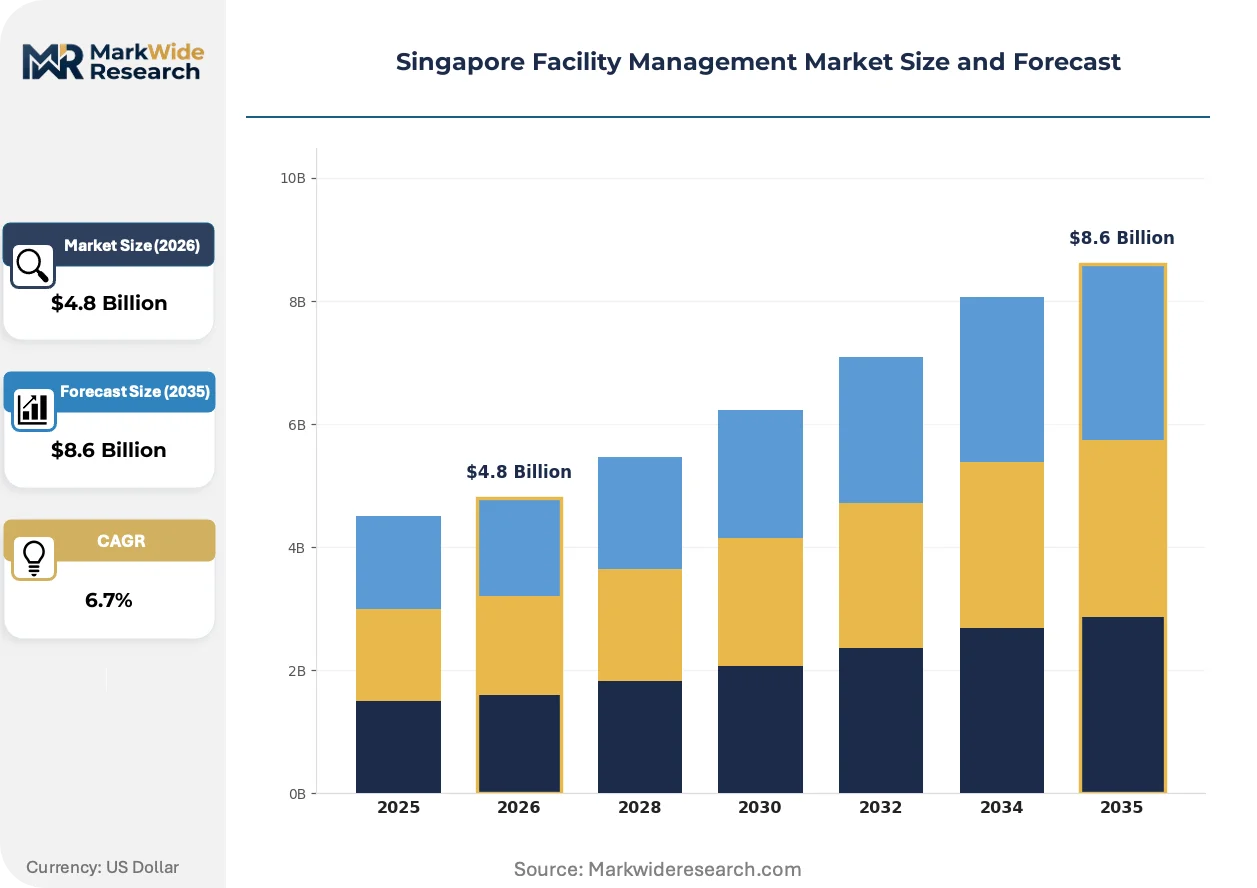
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Cleaning, Security, Waste Management Industry Vertical: Healthcare, Retail, Education, Hospitality End User: Corporates, Government, Residential, Institutions Technology: IOT Solutions, Automated Systems, Energy Management, Software Platforms |
| Companies Covered | Sodexo Singapore Pte. Ltd., Certis CISCO Security Pte. Ltd, CBRE Group Inc., Savills Singapore, Jones Lang LaSalle Incorporated, ISS A/S, CBM Pte Ltd, Compass Group PLC, ENGIE Services Singapore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Facility Management Market Strategic Shifts
Facility operators are reconfiguring service delivery around data-centric performance models rather than scheduled maintenance routines. This shift is compressing traditional contract structures and elevating technology partnerships over labor arbitrage.
Digital twin technology for building systems is modularizing how facility managers design, simulate, and optimize mechanical and electrical infrastructure before physical deployment. Commercial developers in Marina Bay are adopting these virtual replicas during pre-construction phases to validate energy performance assumptions. The technology is modularizing service contracts into discrete simulation, implementation, and optimization phases that can be unbundled or recombined.
The Building and Construction Authority's enhanced Green Mark 2021 standards impose stricter embodied carbon reporting requirements on facility management procurement. Building owners must now document whole-life carbon impacts across maintenance materials and replacement cycles. Commercial office portfolios are responding by embedding lifecycle assessment clauses into multi-year service agreements.
Corporate real estate teams are consolidating vendor relationships from multiple single-service contracts to integrated facilities partnerships. This concentration is displacing fragmented cleaning, security, and maintenance suppliers with unified platform operators. The shift is most visible among multinational headquarters relocating to Singapore's central business district, where single-point accountability reduces coordination overhead.
Singapore Facility Management Market Segmentation
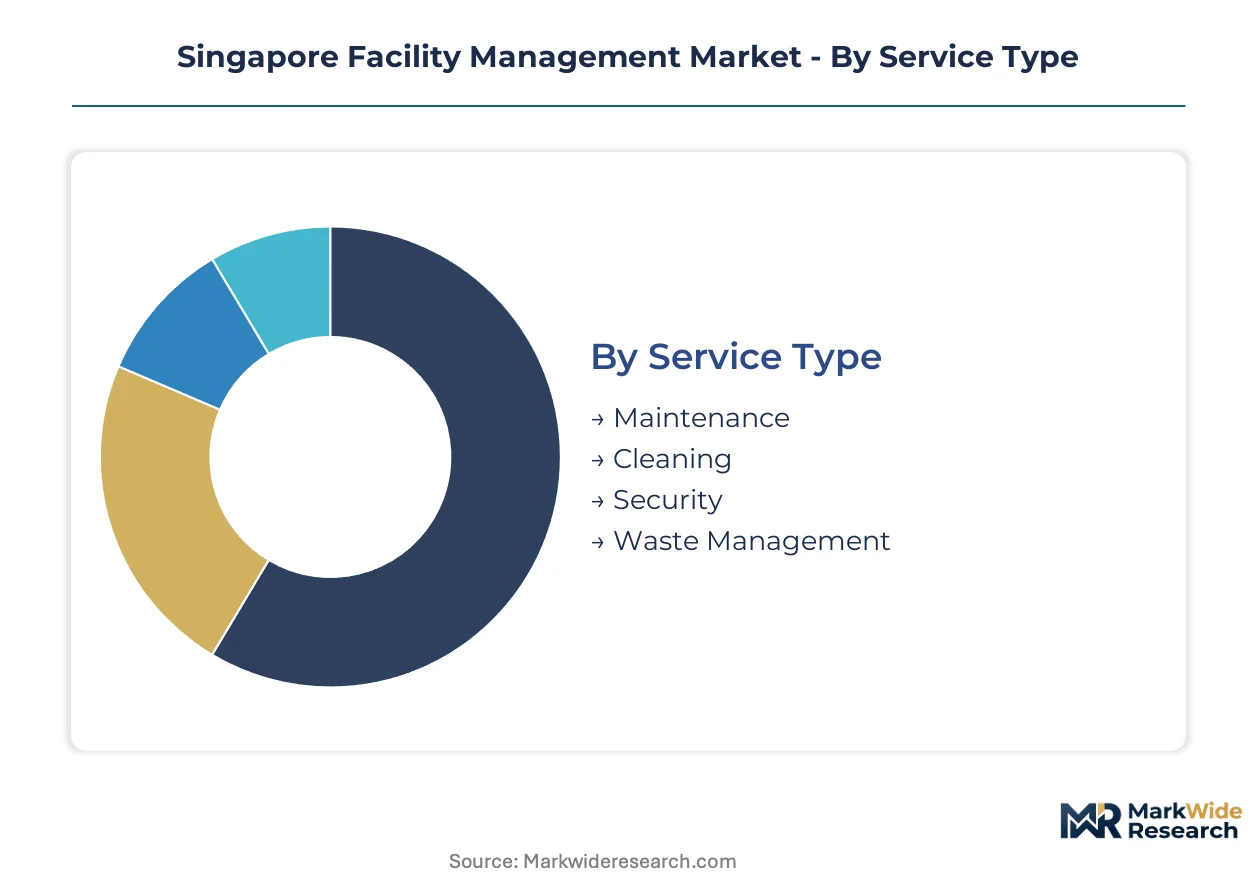
Segmentation in Singapore's facility management market reveals how procurement patterns split between legacy maintenance contracts and technology-enabled service bundles. Understanding these divisions exposes where margin pressure concentrates and which service configurations align with the Building and Construction Authority's tightening compliance frameworks.
Service Type:
Supply concentration in technical maintenance services creates pricing power for specialized mechanical and electrical contractors, while commoditized cleaning and security segments fragment across labor-intensive operators.
- Maintenance:Mechanical, electrical, and plumbing systems upkeep governed by service level agreements specifying response times and uptime thresholds. Demand concentrates in Jurong Lake District mixed-use developments where integrated plant rooms require unified technical oversight under Green Mark certification timelines.
- Cleaning:Janitorial and specialized sanitation services including infection control protocols for healthcare-adjacent facilities. Contracts in Marina Bay commercial towers now bundle daytime cleaning with nighttime disinfection cycles to minimize occupant disruption.
- Security:Access control, surveillance monitoring, and physical guarding services.
- Waste Management:Collection, segregation, and disposal coordination aligned with Singapore's zero-waste masterplan targets.
Today's leader: Maintenance. Tomorrow's challenger: Cleaning services bundled with health compliance documentation.
Industry Vertical:
Application-specific requirements reshape service delivery models, with healthcare and hospitality demanding precision environmental controls that retail and education segments rarely match.
- Healthcare:Sterile processing, isolation room pressure differentials, and medical waste chain-of-custody protocols. One-North research precinct biotech facilities require cleanroom certification maintenance that generalist operators cannot provision.
- Hospitality:Guest experience-centered facilities oversight spanning front-of-house presentation and back-of-house logistics. Integrated resorts in Marina Bay mandate 24/7 engineering response to protect gaming and entertainment revenue streams.
- Retail:High-traffic public space maintenance with brand-aligned aesthetic standards.
- Education:Seasonal demand fluctuation tied to academic calendars and campus safety compliance.
Healthcare commands premium pricing. Hospitality offers volume scale.
End User:
Customer type determines contract structure complexity, with government and corporate clients driving standardization while residential and institutional buyers tolerate fragmented supplier relationships.
- Corporates:Multi-site portfolio contracts with centralized vendor management and unified reporting dashboards. Multinational headquarters relocating to Singapore's central business district consolidate single-point accountability to reduce coordination overhead.
- Government:Public tender processes with mandated local workforce quotas and sustainability disclosure requirements. The Building and Construction Authority's own facilities demonstrate Green Mark Platinum compliance that vendors must replicate across public sector contracts.
- Residential:Condominium management council procurement with high price sensitivity and service fragmentation.
- Institutions:University and cultural facility contracts with irregular capital renewal cycles.
Corporate contracts anchor revenue stability. Government tenders shape compliance standards industry-wide.
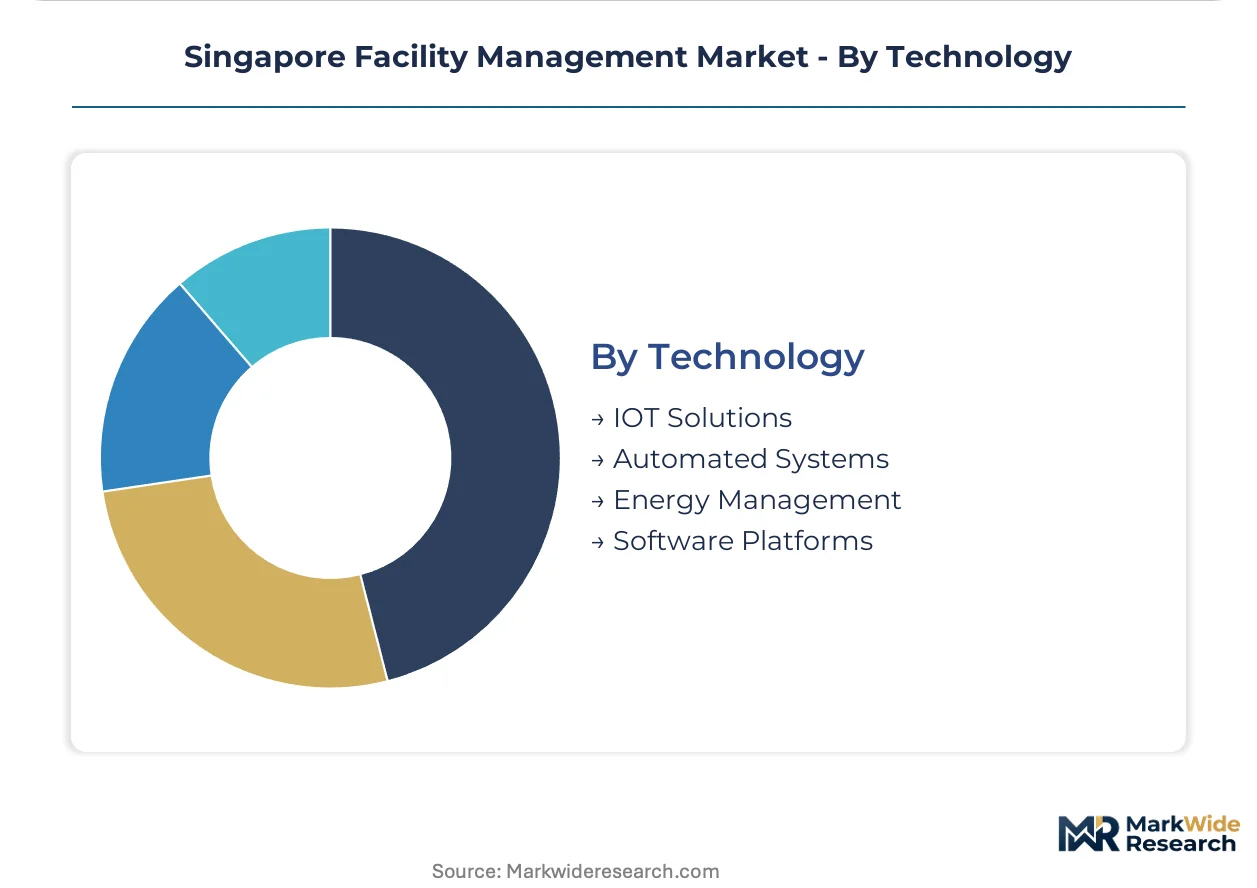
Technology:
Margin structure inverts across this dimension, with capital-light software platforms capturing recurring revenue while hardware-dependent automated systems require heavy deployment investment.
- IOT Solutions:Sensor networks enabling predictive maintenance through automated fault detection and real-time environmental monitoring. Premium commercial assets in Marina Bay deploy these systems to reduce unplanned downtime and satisfy insurer risk assessments.
- Software Platforms:Cloud-based work order management, asset registry, and vendor coordination portals. Asset-light REIT structures favor subscription-based deployment to avoid capital-intensive equipment ownership.
- Automated Systems:Robotic cleaning, drone inspection, and autonomous security patrol integration.
- Energy Management:Active load management and demand response coordination with the Energy Market Authority's grid integration incentives.
Software Platforms scale fastest. IOT Solutions defend incumbency through data lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility management procurement in Singapore diverges sharply from neighboring Malaysia's fragmented vendor landscape, where single-service contracts dominate and integrated offerings remain underdeveloped. Singapore's concentrated commercial real estate stock and stringent certification requirements create fundamentally different contract economics across the city-state.
Jurong Lake District
Mixed-use developments spanning office, retail, and residential functions drive bundled service demand for unified facilities oversight. The Building and Construction Authority's Green Mark Platinum standards mandate documented carbon reduction pathways that compress procurement cycles. Integrated plant rooms in this western corridor require technical maintenance contracts with guaranteed energy performance.
Marina Bay
Premium commercial towers and integrated resorts command 24/7 engineering response to protect gaming and entertainment revenue streams. Cybersecurity compliance costs from the national cybersecurity regulator's data protection requirements restrict vendor selection to certified providers. District cooling infrastructure concentration creates single-point vulnerability for energy performance contracts.
One-North Research Precinct
Biotech and infocomm facilities generate specialized cleanroom and precision climate management demand beyond generalist operator capabilities. The Energy Market Authority's demand response incentives reward buildings with active load management capabilities. Precision engineering clusters in this western corridor anchor premium-priced technical maintenance contracts.
Central Business District
Multinational headquarters consolidating vendor relationships favor single-point accountability over fragmented supplier management. Asset-light REIT structures drive subscription-based energy management adoption to avoid capital-intensive equipment ownership. Corporate real estate teams mandate unified reporting dashboards across multi-site portfolios.
Singapore Facility Management Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated platform operators capturing corporate campus contracts while labor-intensive cleaning and security vendors fragment across price-sensitive residential management councils. The market structure concentrates around three archetypes: food-facilities integrators leveraging meal service anchors, technology-led asset managers deploying predictive analytics platforms, and engineering heritage operators dominating district cooling and energy performance contracting. Competitive moves center on bundling energy guarantees with traditional maintenance and consolidating fragmented single-service relationships into unified partnerships.
Within the integrated services tier, Sodexo Singapore Pte. Ltd. and ENGIE Services Singapore exemplify contrasting heritage strategies—one anchored in food service integration, the other in district cooling engineering—while CBRE Group Inc. occupies a position representing technology-led asset management platforms. These three players illustrate how contract economics diverge between meal-service anchors, engineering-intensive energy performance, and software-centric client retention models across Singapore's commercial real estate stock.
| Leading Market Players |
|---|
| Sodexo Singapore Pte. Ltd. |
| Certis CISCO Security Pte. Ltd |
| CBRE Group Inc. |
| Savills Singapore |
| Jones Lang LaSalle Incorporated |
| ISS A/S |
| CBM Pte Ltd |
| Compass Group PLC |
| ENGIE Services Singapore |
| Others |
Value Chain & Pricing Dynamics
Integrated energy management platforms are compressing traditional facility management margins while simultaneously concentrating procurement power among operators with certified cybersecurity credentials. This technology shift elevates software-enabled service tiers above labor-intensive maintenance contracts, reshaping how vendors compete on cost and capability across Singapore's Green Mark-mandated developments.
Pricing Analysis
Capacity additions in cloud-based work order management are reshaping price floors for mid-tier facility operators unable to fund platform development. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification tier and portfolio scale. Cost compression in standard-tier cleaning and security bundles is intensifying because labor-intensive operators face margin erosion without technology differentiation. Residential condominium management councils exhibit highest price sensitivity, while corporate REITs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Skilled technician shortages in Singapore, Malaysia, and the Philippines are constraining service expansion capacity for specialized mechanical and electrical contractors. Facility management supply chains draw from imported IoT sensor hardware, proprietary building management software licenses, and certified engineering labor pools. Single-source vulnerability concentrates around district cooling plant operators in Marina Bay and Jurong. Distribution runs through direct enterprise sales teams for corporate portfolios and subcontractor networks for fragmented residential contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's facility management market functions as a geographic-arbitrage play where Green Mark certification requirements and cybersecurity compliance costs create entry barriers unmatched in neighboring Southeast Asian markets.
For Market Incumbents: Hedge against margin erosion in commoditized cleaning services by deepening vertical integration into IoT-enabled predictive maintenance platforms. Acquire certified cybersecurity credentials to defend corporate campus contracts against technology-led competitors. Prioritize subscription-based energy management layers that lock in REIT clients through performance data continuity.
For New Entrants and Emerging Players: Capture white-space opportunity in One-North research precinct biotech facilities requiring cleanroom certification maintenance beyond generalist capabilities. Target government tender processes where mandated local workforce quotas and sustainability disclosure requirements filter out unqualified competitors. Lead with specialized precision climate management expertise rather than bundled commodity services.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier maintenance operators facing labor cost pressure without technology differentiation. Five-to-ten year viability favors engineering-heritage operators with district cooling infrastructure and energy performance contracting capabilities. Watch Energy Market Authority demand response incentive expansion as inflection signal for active load management service premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented cleaning, security, and maintenance contracts under single accountability for corporate REITs. |
| Green Certification Program | Documents whole-life carbon impacts across maintenance materials to satisfy Building and Construction Authority mandates. |
| Strategic Partnership | Combines food service integration with facilities oversight to anchor long-term corporate campus contracts. |
| Geographic Expansion | Extends Jurong Lake District bundled service models into emerging mixed-use developments. |
| Acquisition of Specialist Firm | Adds cleanroom certification capabilities for One-North biotech and infocomm facility demand. |
Study Parameters
Multiple input streams — facility management contract documentation, Building and Construction Authority regulatory filings, and Energy Market Authority grid integration records — were reconciled with primary interviews across the analysis window. Conversations with corporate real estate directors, government procurement officers, building systems engineers, and REIT asset managers informed service bundling trends and pricing dynamics. Secondary validation drew from Building and Construction Authority Green Mark certification databases, national cybersecurity regulator compliance registries, and commercial real estate transaction records. Bottom-up contract value aggregation and top-down market sizing triangulated segment-level estimates.
Data-stream reconciliation anchored volume projections to modeled adoption curves across service type, industry vertical, end user, and technology dimensions. CAGRs were derived from regression analysis of historical contract awards against regulatory milestone timing. Forecast inputs incorporated Green Mark 2021 embodied carbon reporting requirements, progressive grid integration rules, and IoT sensor network deployment trajectories throughout the projection horizon.
Regulatory enforcement delays, skilled labor immigration policy shifts, and district cooling infrastructure reliability events are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions regarding sustained Green Mark compliance timelines and cybersecurity certification maintenance. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Bahrain Facility Management Market
Facility Management
Japan Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
UK Facility Management Market
Facility Management
Denmark Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Albania Facility Management Market
Facility Management
Nigeria Facility Management Services Market
Facility Management
China Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Warehouse Management Service Market
Facility Management
Global Facility Management Software Market