
 North America Hard Facility Management Market | 2026-2036
North America Hard Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hard Facility Management Market Analytics
Canadian mechanical contractors and US HVAC specialists is rebalancing capacity toward integrated building systems. EMCOR Facilities Services Inc. leverages its electrical and mechanical contracting heritage to capture bundled hard FM contracts. Johnson Controls International PLC sustains technology leadership through its building automation and fire suppression integration. CBRE Group Inc. anchors its position with facility engineering services embedded inside broader real estate management mandates.
North America Hard Facility Management encompasses the physical maintenance, repair, and replacement of building infrastructure including HVAC systems, electrical distribution, plumbing, fire protection, and structural elements, typically governed by ASHRAE standards and local mechanical codes that specify equipment lifecycle thresholds and energy performance baselines. Its primary purpose ensures operational continuity, occupant safety, and regulatory compliance across commercial and industrial properties. Maintenance services within the Service Type dimension occupy the largest revenue pool due to recurring contractual obligations and penalty structures for downtime, while IoT Solutions within the Technology dimension represent the fastest structural expansion as sensor networks enable predictive rather than reactive equipment intervention.
OSHA workplace safety mandates, ASHRAE ventilation standards, and the US Inflation Reduction Act's building efficiency incentives collectively shape equipment upgrade cycles and contractor qualification requirements across the region. The US Department of Energy and Canada's National Research Council enforce diverging but increasingly stringent energy codes that filter market access for non-compliant service providers. Stakeholders must monitor how jurisdictional code harmonization and federal retrofit funding flows redistribute contract opportunities between national integrators and regional specialists.
Market Dynamics
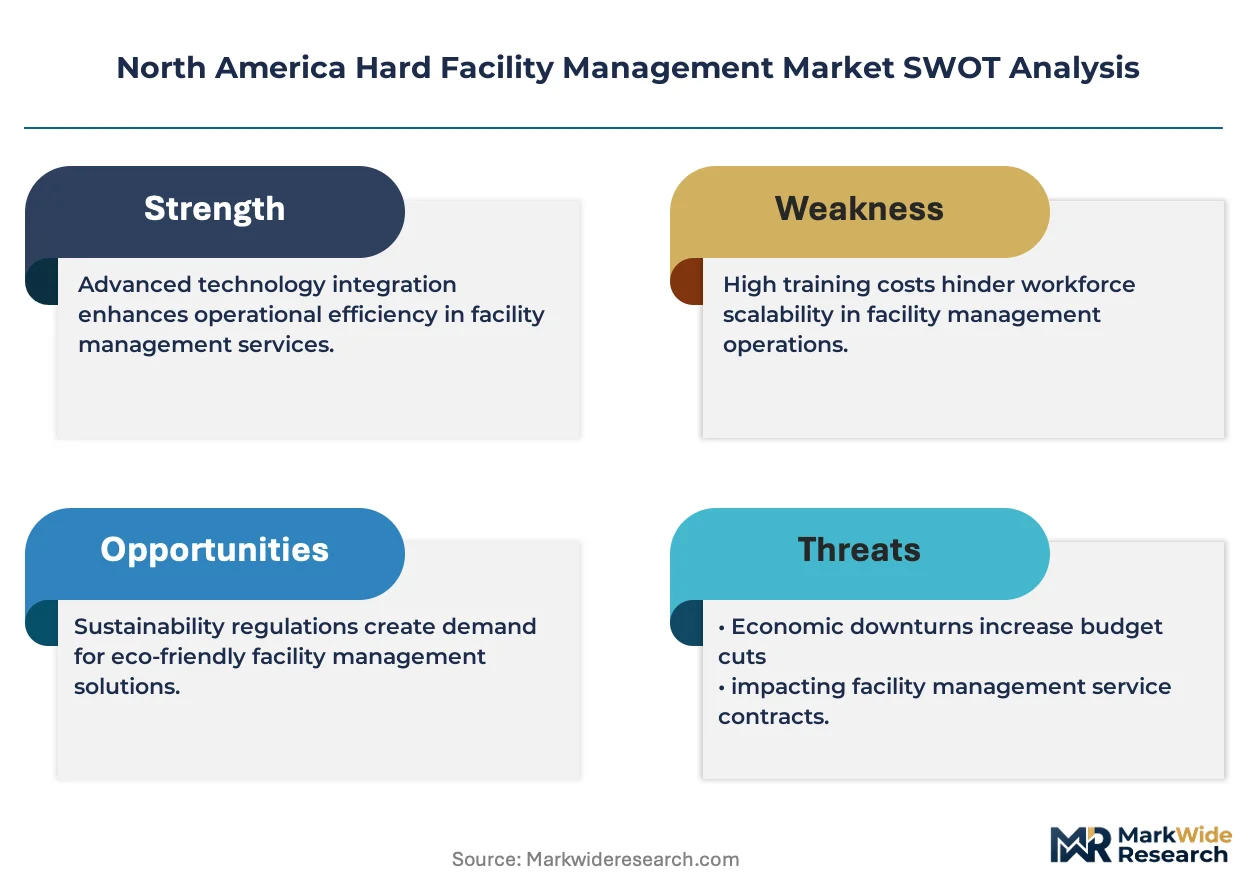
Integrated building automation systems are compressing service delivery models across North American commercial portfolios, forcing mechanical contractors to absorb digital capabilities or cede bundled contracts to technology-enabled competitors.
Growth Catalysts
- US Inflation Reduction Act:Federal tax credits for building energy retrofits accelerate HVAC replacement cycles and incentivize comprehensive system upgrades across aging commercial stock.
- Healthcare Facilities:Hospital and clinic operators demand single-source accountability for critical infrastructure uptime, consolidating previously fragmented mechanical, electrical, and fire protection contracts.
- IoT sensor networks:Predictive maintenance algorithms reduce unplanned equipment failures by enabling real-time vibration, temperature, and pressure monitoring across distributed building portfolios.
Market Restraints
- Skilled technician shortage:Licensed HVAC, electrical, and plumbing trades face demographic contraction as retirement outpaces apprenticeship pipeline replenishment across the US and Canada.
- Copper and aluminum volatility:Raw material price swings for electrical distribution components and refrigeration systems compress fixed-price contract margins and deter long-term commitments.
- ASHRAE 90.1 stringency:Escalating energy code compliance thresholds require capital-intensive equipment upgrades that strain owner budgets and delay maintenance contract renewals.
Strategic Opportunities
- Texas commercial construction pipeline:Austin, Dallas, and Houston metro areas sustain elevated Class-A office and industrial development, creating concentrated demand for integrated hard FM commissioning and ongoing service.
- Digital twin convergence:Building information modeling and real-time operational data integration enable remote diagnostics and virtual commissioning, reducing truck rolls and technician dispatch costs.
- Canadian federal retrofit incentives:Canada's National Research Council funding streams for public building efficiency upgrades expand addressable market for energy performance contracting in Ontario and British Columbia.
Industry Challenges
- Cross-trade certification complexity:Jurisdictional licensing fragmentation between electrical, mechanical, and fire protection trades obstructs workforce mobility and integrated service team assembly.
- Legacy BAS integration:Proprietary building automation protocols from 1990s and 2000s installations resist interoperability with modern IoT platforms, requiring costly gateway infrastructure or full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hard Facility Management Market |
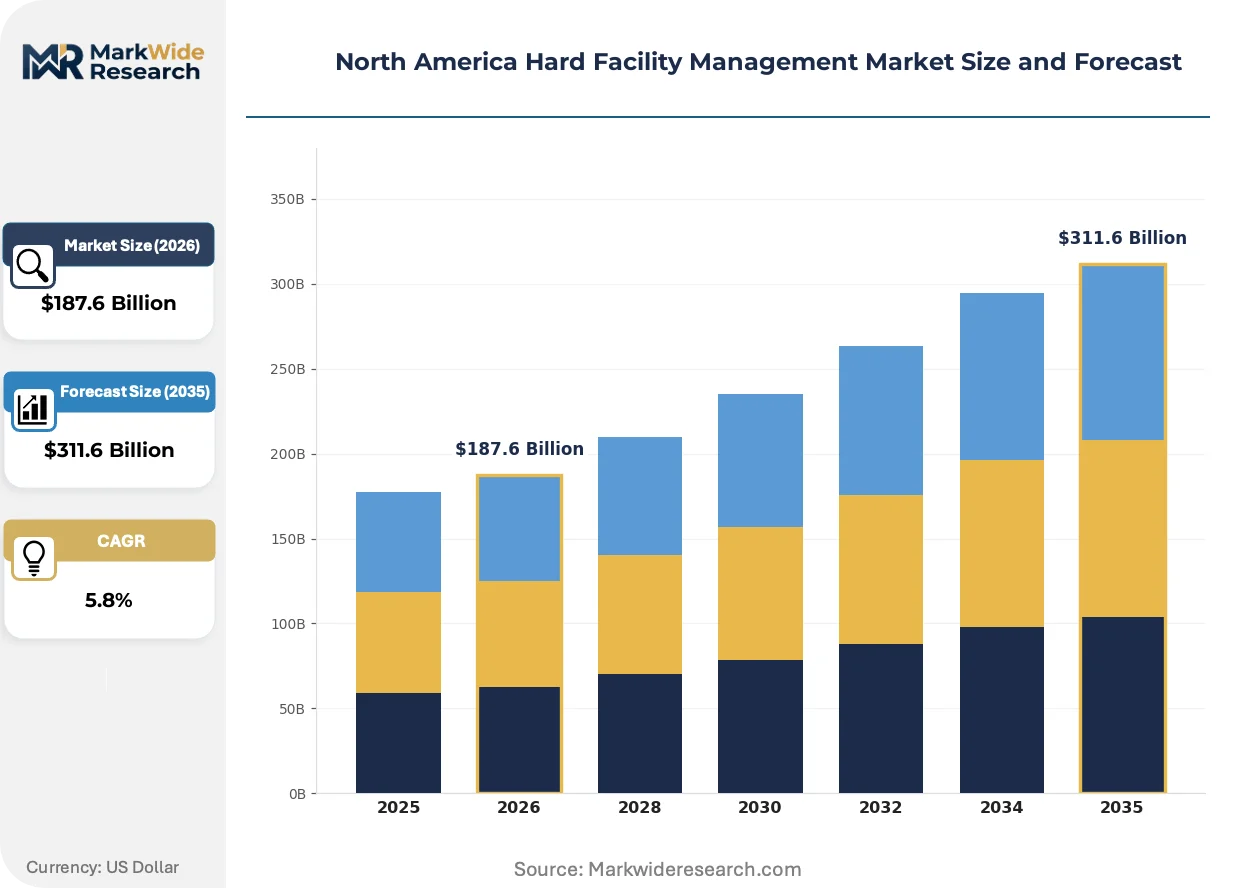
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Cleaning, Security, Landscaping End User: Corporate Offices, Manufacturing Units, Educational Institutions, Healthcare Facilities Technology: Building Management Systems, IoT Solutions, Energy Management Software, CMMS Application: Asset Management, Space Optimization, Compliance Management, Sustainability Programs |
| Companies Covered | Jacobs Solutions Inc., CBRE Group Inc., Sodexo, EMCOR Facilities Services Inc., Jones Lang LaSalle Incorporated, Johnson Controls International PLC, AECOM, Cushman & Wakefield PLC, Carrier Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hard Facility Management Market Evolving Landscape
Sensor-enabled predictive maintenance is displacing scheduled preventive programs across North American facility portfolios, compressing service intervals while extending equipment lifecycles through data-driven intervention timing.
Cloud-native building operating systems are unifying previously siloed HVAC, lighting, and security control layers into single-pane dashboards. Large commercial real estate investment trusts deploy these platforms across multi-site portfolios to standardize performance benchmarking and reduce vendor management overhead. This convergence is collapsing the traditional separation between facilities engineering and information technology functions.
The US Inflation Reduction Act's efficiency incentives are accelerating heat pump and thermal storage adoption in commercial retrofits. Building owners combine federal tax credits with utility demand-response programs to offset capital costs for electrification projects. Cold-climate heat pump performance thresholds specified in ASHRAE standards are driving equipment specification changes across Minnesota, Wisconsin, and Ontario markets.
Asset owners are consolidating vendor relationships from specialized single-trade contractors toward integrated facilities engineering partners. Healthcare systems and data center operators lead this consolidation, seeking unified accountability for uptime metrics and regulatory compliance. California and Texas markets exhibit the most pronounced supplier base rationalization as portfolio-scale procurement teams centralize contract authority.
North America Hard Facility Management Market Segmentation
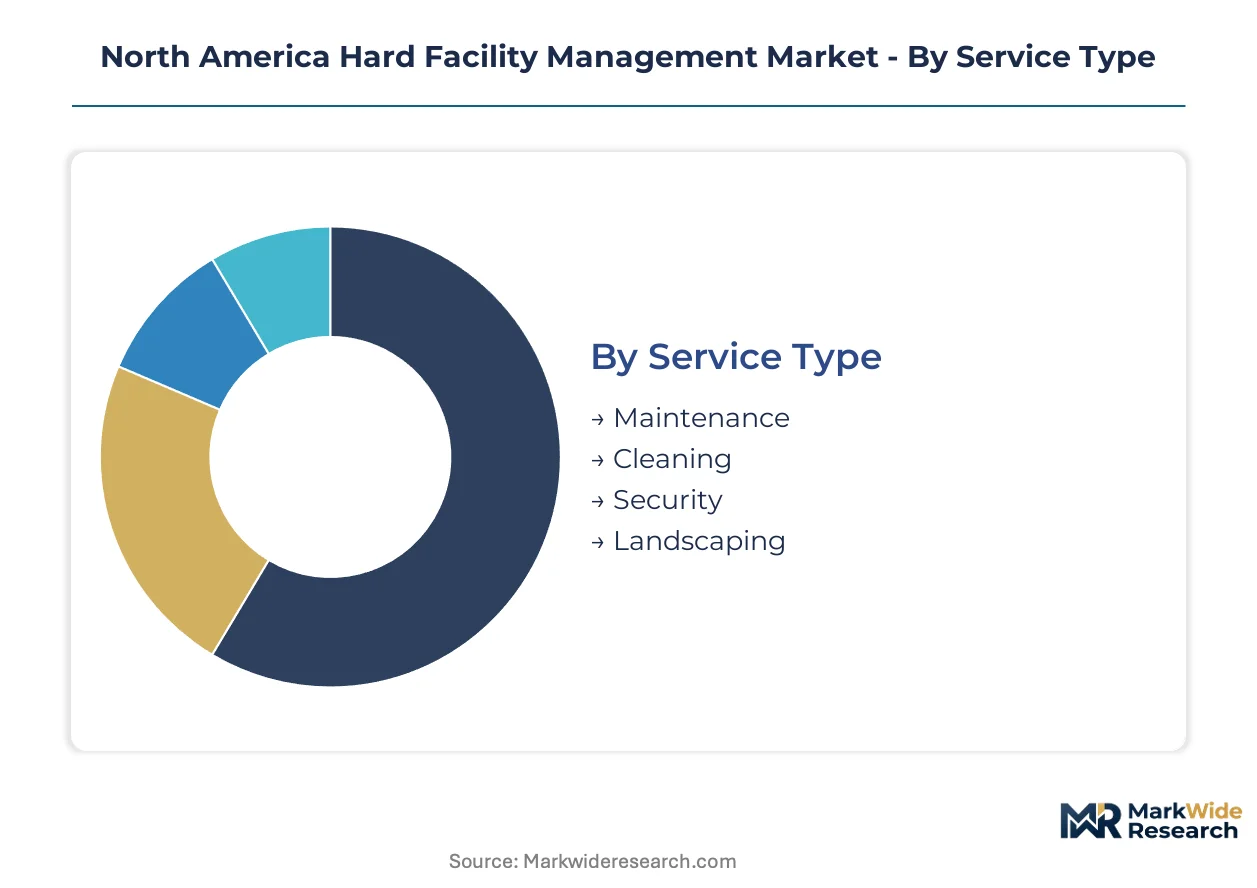
Hard facility management segmentation reveals diverging margin profiles across service delivery models and technology intensity. Service type splits expose recurring revenue concentration versus project-based volatility, while end-user composition tracks construction cycle exposure and regulatory compliance burdens.
Service Type:
Volume concentrates in recurring maintenance contracts, while premium margins attach to specialized cleaning and integrated security services.
- Maintenance:Scheduled and corrective repair of HVAC, electrical, plumbing, and structural systems governed by ASHRAE lifecycle thresholds. Healthcare Facilities in Texas and California drive contract consolidation as hospital operators seek single-source accountability for critical infrastructure uptime.
- Cleaning:Specialized surface treatment and contamination control for controlled environments including cleanrooms and surgical suites. Manufacturing Units in Ontario and pharmaceutical clusters demand certified protocols that command price premiums over standard janitorial services.
- Security:Physical access control, surveillance systems, and perimeter protection integrated with building automation platforms.
- Landscaping:Grounds maintenance, irrigation systems, and exterior hardscape preservation for commercial portfolios.
Today's leader: Maintenance. Tomorrow's challenger: Security.
End User:
Corporate offices generate baseline volume, while healthcare and manufacturing end users impose specialized compliance requirements that reshape contractor capabilities.
- Corporate Offices:Class-A commercial buildings and multi-tenant facilities requiring standardized HVAC, lighting, and access control maintenance. Austin, Dallas, and Houston metro areas sustain concentrated demand as development pipelines in Texas absorb integrated hard FM commissioning.
- Healthcare Facilities:Hospitals, clinics, and long-term care operators with zero-tolerance downtime requirements and Joint Commission accreditation standards. California and Ontario markets exhibit pronounced vendor consolidation as health systems centralize procurement authority.
- Manufacturing Units:Industrial facilities with process-critical environmental controls and hazardous material handling protocols.
- Educational Institutions:K-12 districts and university campuses with seasonal occupancy patterns and deferred maintenance backlogs.
Healthcare Facilities command the steepest expansion trajectory as regulatory pressure intensifies.
Technology:
Legacy building management systems anchor current installed base, while cloud-native platforms and sensor networks capture incremental investment.
- IoT Solutions:Distributed sensor networks enabling predictive maintenance through real-time vibration, temperature, and pressure monitoring. Commercial real estate investment trusts across Minnesota, Wisconsin, and Ontario deploy these platforms to standardize performance benchmarking and reduce vendor management overhead.
- Building Management Systems:Centralized control platforms integrating HVAC, lighting, and security layers. Proprietary protocols from 1990s installations in US commercial stock resist interoperability, requiring costly gateway infrastructure or full replacement cycles.
- Energy Management Software:Analytics platforms tracking consumption patterns and utility demand-response participation.
- CMMS:Computerized maintenance management systems for work order tracking and asset lifecycle documentation.
Building Management Systems retain installed base dominance. IoT Solutions are climbing the fastest.
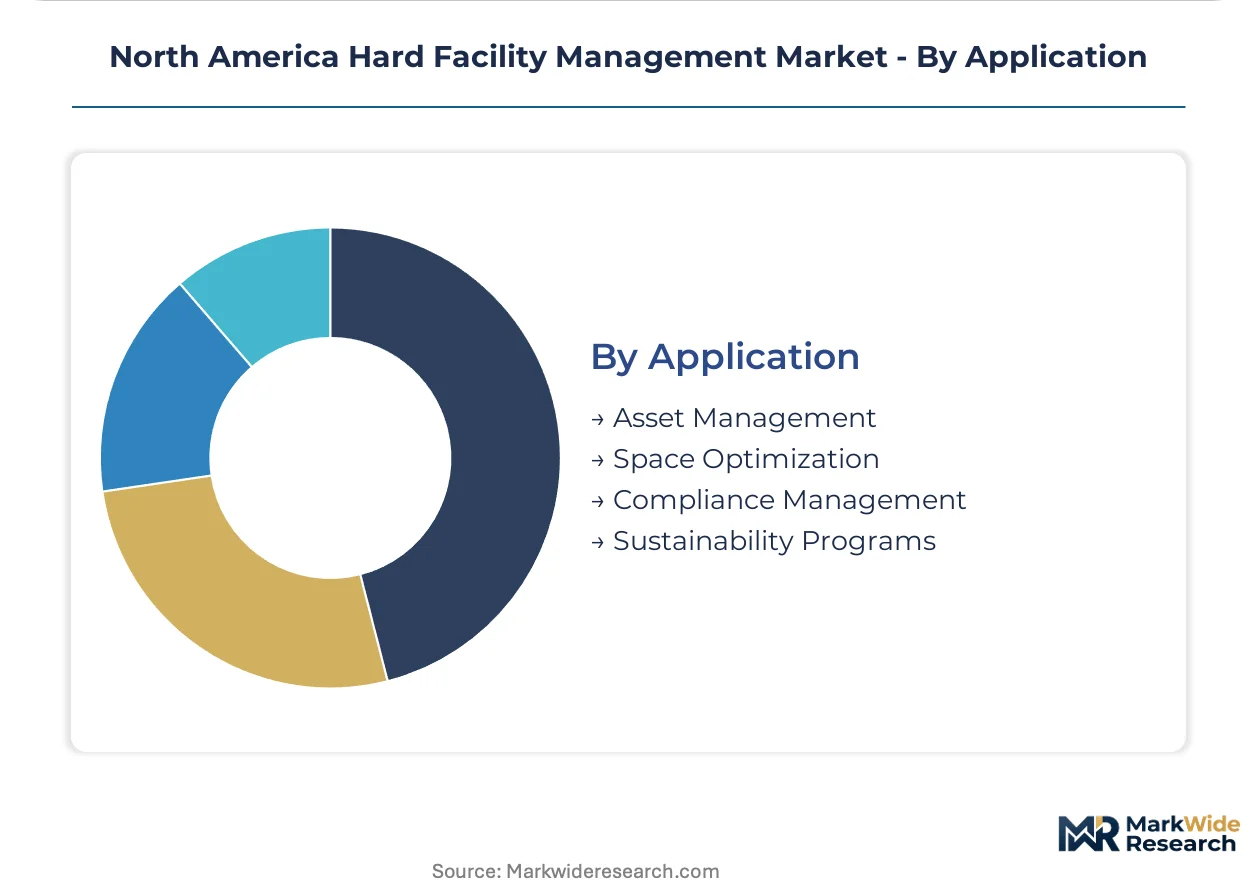
Application:
Compliance and asset management absorb current spending, while sustainability programs capture efficiency incentive flows.
- Asset Management:Lifecycle planning, replacement forecasting, and capital budgeting for building infrastructure components. US Inflation Reduction Act tax credits accelerate HVAC replacement cycles and incentivize comprehensive system upgrades across aging commercial stock.
- Sustainability Programs:Carbon accounting, electrification roadmaps, and green building certification maintenance. Canada's National Research Council funding streams for public building efficiency upgrades expand addressable market for energy performance contracting in British Columbia.
- Compliance Management:Regulatory documentation, inspection scheduling, and code violation remediation.
- Space Optimization:Occupancy analytics and floor plan reconfiguration for hybrid work patterns.
Asset Management holds current priority. Sustainability Programs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between US federal efficiency mandates and Canadian provincial retrofit programs creates compliance-cost arbitrage that shapes contractor mobility and contract migration patterns across the continent. The Inflation Reduction Act's tax credit thresholds and Health Canada's building performance standards establish divergent incentive landscapes that redistribute service demand.
United States
Healthcare systems in Texas and California consolidate vendor relationships under single-source accountability models for critical infrastructure uptime. OSHA workplace safety mandates and ASHRAE 90.1 energy code stringency filter market access for non-compliant service providers. Austin, Dallas, and Houston metro areas sustain concentrated demand as Class-A office and industrial development pipelines absorb integrated hard FM commissioning.
Canada
Ontario and British Columbia public building efficiency upgrades expand addressable market for energy performance contracting. Canada's National Research Council funding streams and diverging provincial mechanical codes shape contractor qualification requirements. Toronto and Vancouver clusters concentrate demand for bundled mechanical, electrical, and fire protection services as health systems centralize procurement authority.
Mexico
Nearshoring manufacturing expansion in Nuevo León and Baja California generates demand for industrial facility maintenance and process-critical environmental controls. Federal energy efficiency standards and state-level environmental regulations establish compliance frameworks for cross-border service providers. Monterrey and Tijuana industrial corridors attract integrated facilities engineering partners seeking unified accountability for uptime metrics.
North America Hard Facility Management Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue technology-enabled predictive maintenance platforms as differentiation vectors. The market exhibits moderate consolidation with national integrators capturing bundled contracts across multi-site portfolios while regional specialists retain position in single-trade maintenance. Three archetypes dominate: electrical-mechanical contracting heritage players, real estate services firms with embedded engineering capabilities, and building automation technology providers. Competitive moves concentrate on M&A absorption of digital capabilities and strategic partnerships bridging proprietary BAS protocols with cloud-native platforms.
Within the integrated services tier, EMCOR Facilities Services Inc. and Johnson Controls International PLC exemplify archetypes combining contracting execution with technology infrastructure. CBRE Group Inc. anchors the real estate-embedded engineering segment. These three occupy positions that represent distinct pathways for capability accumulation: mechanical-electrical heritage, building automation integration, and portfolio-scale procurement centralization.
| Leading Market Players |
|---|
| Jacobs Solutions Inc. |
| CBRE Group Inc. |
| Sodexo |
| EMCOR Facilities Services Inc. |
| Jones Lang LaSalle Incorporated |
| Johnson Controls International PLC |
| AECOM |
| Cushman & Wakefield PLC |
| Carrier Global Corporation |
| Others |
Value Network & Pricing Analysis
Copper futures volatility cascades through North American hard FM supply chains, compressing margins for electrical contractors while amplifying pricing power for vertically integrated mechanical-electrical specialists who captive-source refrigeration components and HVAC coils.
Pricing Analysis
Direct-to-portfolio discount structures dominate multi-site commercial real estate contracts, with three-tier pricing stratification across premium technology-enabled, standard scheduled-maintenance, and economy break-fix service levels. Price differentiation hinges on ASHRAE certification tiers and IoT sensor density, with healthcare systems in California and Texas exhibiting lowest price sensitivity due to Joint Commission uptime mandates. Pricing pressure stems from skilled technician wage inflation, while educational institutions and municipal buildings represent the most price-sensitive buyer segment.
Supply Chain Analysis
Freight cost absorption from Mexico and China shapes component landed costs for HVAC compressors, electrical distribution panels, and fire suppression hardware. Manufacturing concentrates in Mexico, China, and domestic US facilities for refrigeration systems, with copper tubing and aluminum coil stock drawing from Chilean and Canadian mining operations. Single-source vulnerability persists for proprietary building automation controllers from 1990s-era installations. Distribution runs through mechanical-electrical distributor networks and direct OEM channels to national integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Inflation Reduction Act compounds regulatory-driven demand for building energy retrofits, creating sustained contract flow for qualified hard FM providers across federal incentive windows.
For Market Incumbents: Anticipate margin compression from IoT-native competitors by accelerating sensor network deployment across existing maintenance contracts and securing backward integration into HVAC equipment refurbishment capabilities. The threat of technology-enabled regional specialists capturing bundled healthcare contracts in Texas and California demands defensive certification investment in ASHRAE 90.1 compliance auditing.
For New Entrants and Emerging Players: Cloud-native platform partnerships with commercial real estate investment trusts offer the lowest-friction customer acquisition path in this market. White-space opportunity concentrates in digital twin integration for aging Class-B office stock in secondary Midwest markets, with virtual commissioning capabilities as the differentiated entry wedge against incumbent truck-roll economics.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap mechanical contractors possessing electrical licensing cross-certification and established healthcare facility relationships. Long-term viability favors platforms with recurring maintenance revenue exceeding project-based volatility. Watch for OSHA enforcement intensity around skilled technician training requirements as the inflection signal for contract consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Network Deployment | Enables predictive maintenance contracts that extend equipment lifecycles beyond traditional preventive schedules. |
| Cross-Trade Certification Investment | Builds workforce mobility across electrical, mechanical, and fire protection trades required for integrated service delivery. |
| Backward Integration into Equipment Refurbishment | Captures margin from HVAC coil and compressor remanufacturing while reducing copper price exposure. |
| Healthcare System Partnership | Locks in multi-year single-source accountability contracts with Joint Commission compliance requirements. |
| Digital Twin Platform Development | Reduces truck-roll costs through remote diagnostics and virtual commissioning across distributed portfolios. |
Research Methodology
Multiple input streams — facility management executives, mechanical contracting operations directors, healthcare system procurement officers, and commercial real estate portfolio managers — were reconciled against secondary validation from ASHRAE technical standards, OSHA enforcement databases, US Department of Energy efficiency program filings, and Canadian National Research Council funding disclosures. Bottom-up contract value aggregation and top-down market sizing triangulation anchored volume estimates.
Data-stream reconciliation across service type, end-user vertical, technology deployment, and application purpose generated segmentation-level outputs over the projection horizon. CAGRs derived from equipment replacement cycle analysis, federal incentive program duration, and construction pipeline absorption rates. Forecast inputs incorporated IoT sensor adoption curves and skilled labor demographic projections.
The model assumes a particular technology adoption path; alternative pathways for cloud-native building operating systems would alter the outlook if proprietary BAS interoperability barriers persist longer than projected. Forecasts reflect assumptions about IRA incentive continuity and ASHRAE code harmonization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Europe Hard Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
Ireland Facility Management Market
Facility Management
Africa Facility Management Market
Facility Management
Thailand Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Belgium Facility Management Market
Facility Management
Oman Facility Management Market
Facility Management
United Arab Emirates Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Bahrain Facility Management Market