
 Latin America Facility Management Market | 2026-2036
Latin America Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Facility Management Market Foresight
REACH is repositioning chemical safety protocols for cleaning and maintenance consumables across Latin American import supply chains. CBRE Group, Inc. leverages its cross-border property platform to anchor premium commercial contracts in Mexico City and São Paulo. ISS A/S competes through specialized industrial facility protocols that dominate Brazil's manufacturing belt. Sodexo, Inc. extends integrated service bundles across healthcare and education campuses, controlling multi-site accounts with standardized KPI frameworks.
Facility management encompasses the coordinated delivery of hard services (mechanical, electrical, plumbing maintenance) and soft services (cleaning, security, catering) through structured operational frameworks, typically governed by SLAs measuring response times, uptime percentages, and energy consumption baselines. Its primary purpose is to preserve asset value, ensure occupant safety, and optimize lifecycle costs for built environments. Cleaning Services and Maintenance Services occupy the largest share of contract value, reflecting labor-intensive requirements across aging commercial stock in São Paulo and Buenos Aires. IoT Solutions and Energy Management Systems represent the fastest-expanding technology category, displacing reactive maintenance models with sensor-driven predictive protocols that reduce unplanned downtime.
Brazil's ANVISA sanitary surveillance standards shape cleaning chemical formulations and disinfection frequencies in healthcare and food-processing facilities. Mexico's CONUEE energy efficiency certification and Argentina's IRAM building standards mandate systematic energy audits, redirecting procurement toward technology-enabled vendors with certified measurement capabilities. Stakeholders must weigh the capital requirements of CMMS and cloud-based platform deployment against the operational savings these systems generate across multi-site portfolios.
Market Dynamics
IoT-enabled predictive maintenance protocols are compressing response times across Brazilian healthcare and industrial facilities, forcing incumbent operators to retool service delivery models or lose multi-year contracts to technology-enabled competitors.
Growth Catalysts
- ANVISA Sanitary Standards:Brazil's healthcare regulator mandates hospital-grade disinfection frequencies and chemical formulations, creating recurring demand for certified facility management vendors in São Paulo's hospital corridor.
- Manufacturing Belt Expansion:Brazil's southeastern industrial zones require specialized industrial cleaning and hazardous waste protocols that only certified operators can deliver under strict environmental compliance timelines.
- CONUEE Energy Certification:Mexico's national energy efficiency commission requires systematic building audits, redirecting procurement toward vendors with certified measurement and verification capabilities.
Market Restraints
- Imported Equipment Cost Volatility:CMMS platforms and IoT sensor hardware denominated in US dollars expose Mexican and Argentine operators to exchange rate risk that compresses margin on fixed-price contracts.
- Skilled Technician Concentration:Certified HVAC and electrical specialists cluster in São Paulo and Mexico City, leaving secondary markets like Monterrey and Curitiba underserved and driving labor cost premiums.
- Legacy Infrastructure Compatibility:Aging building management systems in Buenos Aires commercial stock lack API connectivity, blocking seamless integration with cloud-based monitoring platforms.
Strategic Opportunities
- Colombian Market Underpenetration:Bogotá and Medellín healthcare facilities show sub-15 percent outsourcing rates versus Brazilian benchmarks, offering first-mover expansion paths for certified operators.
- IRAM Building Standards Compliance:Argentina's national standards institute mandates energy audits for public buildings, creating procurement windows for technology-enabled vendors with certified reporting capabilities.
- CMMS-IoT Convergence:Integrated platforms combining computerised maintenance management with real-time sensor feeds enable outcome-based pricing models that align vendor incentives with uptime guarantees.
Industry Challenges
- Certified Energy Auditor Shortage:Mexico's CONUEE and Argentina's IRAM both require licensed professionals to execute mandated audits, but training pipeline capacity lags contract volume by approximately three years.
- Multi-Site Integration Complexity:Healthcare chains operating across São Paulo, Rio de Janeiro, and Belo Horizonte struggle to standardise KPI frameworks and SLA enforcement across heterogeneous legacy building systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Facility Management Market |
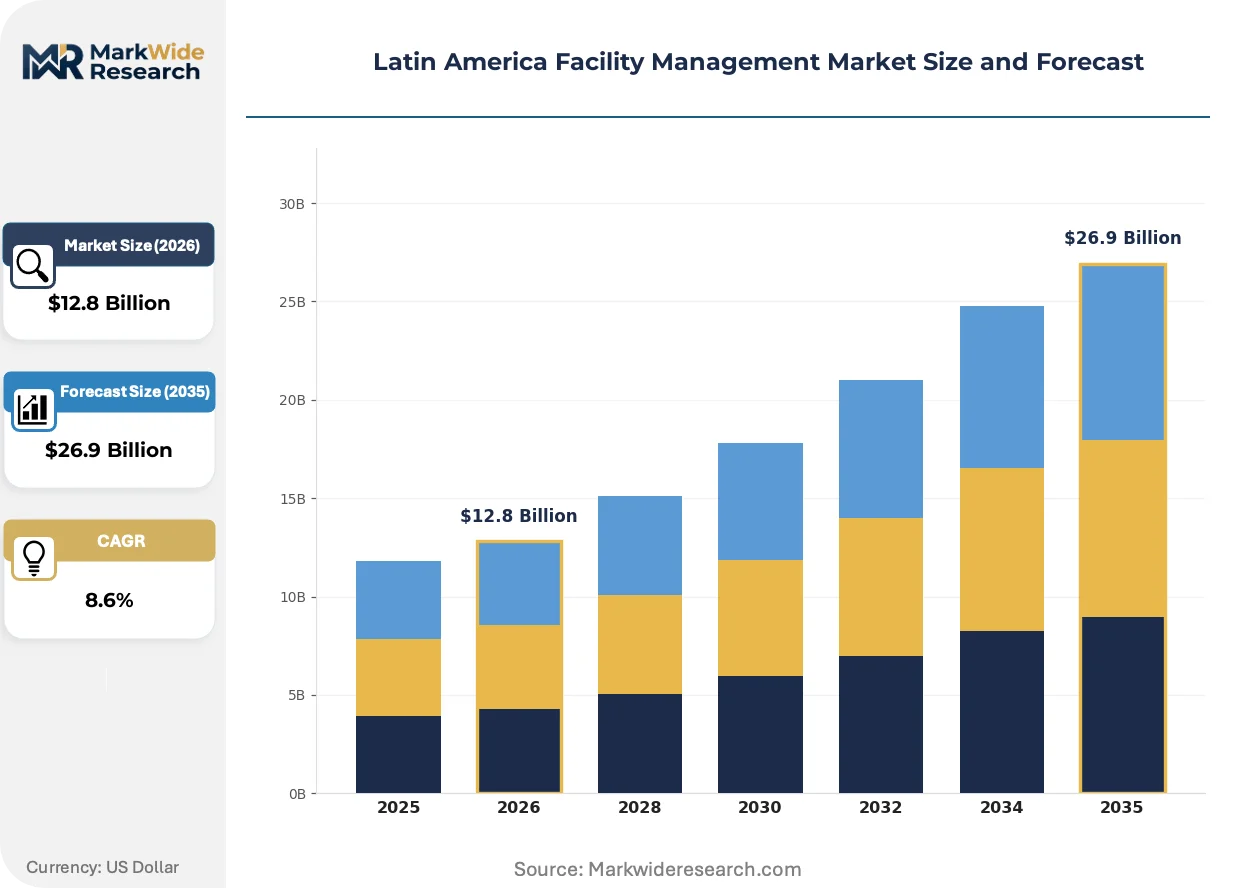
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning Services, Security Services, Maintenance Services, Landscaping Services End User: Commercial Buildings, Residential Properties, Educational Institutions, Industrial Facilities Technology: IoT Solutions, Computerized Maintenance Management Systems, Energy Management Systems, Cloud-based Platforms Application: Energy Management, Waste Management, Risk Management, Space Management |
| Companies Covered | Cushman & Wakefield plc, Ecolab Inc., CBRE Group, Inc., GPS Group, Aramark Corporation, ISS A/S, Jones Lang LaSalle IP, Inc., Brasanitas Group, Sodexo, Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Facility Management Market Shifts & Advancements
Sensor-driven operational models are supplanting scheduled maintenance across Latin American commercial portfolios, compressing the competitive window for labour-intensive service providers who lack technology infrastructure.
Digital twin technology is rewriting how facility operators simulate HVAC and electrical system performance before deploying physical maintenance crews. Brazilian hospital networks in São Paulo and Rio de Janeiro are piloting these virtual replicas to pre-empt equipment failures during critical care hours. The technology is compressing mean time to repair by enabling remote diagnostics that eliminate unnecessary site visits.
CONUEE's updated energy efficiency codes for commercial buildings mandate systematic measurement and verification protocols that only certified vendors can satisfy. Industrial consequences include procurement disqualification for operators lacking certified energy auditor staff or calibrated metering equipment. Mexico City commercial landlords are responding by bundling energy performance guarantees into facility management contracts, transferring operational risk to service providers.
Healthcare procurement officers are consolidating multi-site contracts under single vendors who can deliver standardized KPI reporting across dispersed campuses. This concentration is displacing fragmented local operators in São Paulo's hospital corridor and Mexico City's medical district. The shift is most visible in tertiary care networks seeking ISO 41001-compliant facility management frameworks that satisfy joint commission accreditation requirements.
Latin America Facility Management Market Segmentation
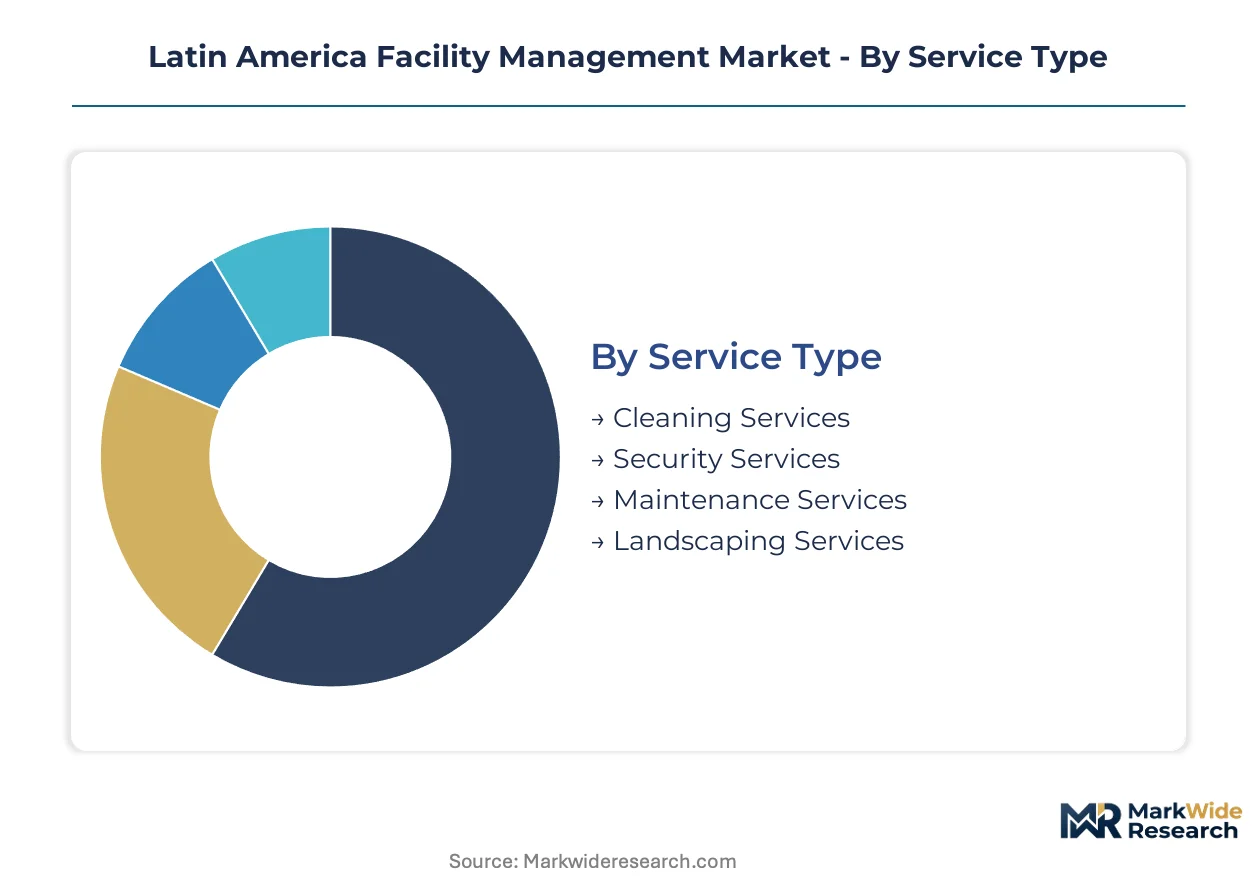
Facility management procurement in Latin America fragments across service intensity, asset complexity, and regulatory exposure. Buyers select service bundles based on whether they prioritize labor arbitrage, technology integration, or compliance certification.
Service Type:
Customization spans from standardized janitorial contracts to highly specialized industrial protocols requiring certified technicians and hazardous materials handling.
- Cleaning Services:Labor-intensive operations covering daily janitorial, disinfection, and healthcare-grade sanitization under ANVISA protocols. São Paulo's hospital corridor and Mexico City's medical district concentrate demand as healthcare procurement officers consolidate multi-site contracts under standardized KPI frameworks.
- Maintenance Services:Hard services encompassing mechanical, electrical, and plumbing systems governed by SLAs measuring response times and uptime percentages. Brazil's southeastern industrial zones require specialized hazardous waste protocols that only certified operators deliver under strict environmental compliance timelines.
- Security Services:Personnel-based access control and surveillance systems for commercial and residential portfolios.
- Landscaping Services:Exterior grounds maintenance with seasonal variability across tropical and temperate climate zones.
Leading the category by volume: Cleaning Services. Growing fastest: Maintenance Services.
End User:
Cost tier stratification separates premium-grade healthcare and industrial contracts from commoditized residential and educational accounts.
- Commercial Buildings:Office towers and retail centers requiring integrated hard and soft service bundles with energy performance guarantees. Mexico City landlords bundle CONUEE compliance into contracts, transferring operational risk to vendors with certified measurement capabilities.
- Industrial Facilities:Manufacturing plants and distribution centers demanding specialized cleaning, hazardous waste management, and predictive maintenance protocols. Brazil's manufacturing belt drives adoption of IoT-enabled monitoring to compress unplanned downtime.
- Educational Institutions:Campuses seeking standardized service delivery across dispersed buildings with seasonal occupancy fluctuations.
- Residential Properties:Condominium and multi-family housing with price-sensitive procurement favoring local operators over national platforms.
Commercial Buildings command the highest contract values. Industrial Facilities show the steepest technology adoption curve.
Technology:
Application maturity separates legacy CMMS deployments from emerging sensor-driven architectures that enable outcome-based pricing.
- IoT Solutions:Sensor networks delivering real-time equipment health monitoring and predictive failure alerts. Brazilian hospital networks pilot digital twin technology to simulate HVAC performance before deploying physical crews, compressing mean time to repair.
- Energy Management Systems:Platforms tracking consumption baselines and automating demand response for CONUEE and IRAM compliance. Procurement disqualification threatens operators lacking certified energy auditor staff or calibrated metering equipment.
- Computerized Maintenance Management Systems:Work order tracking and asset lifecycle databases that standardize KPI reporting across multi-site portfolios.
- Cloud-based Platforms:Remote monitoring infrastructure enabling centralized oversight of dispersed facilities without on-premise server deployment.
CMMS platforms dominate installed base. IoT Solutions are climbing the fastest as sensor hardware costs decline.
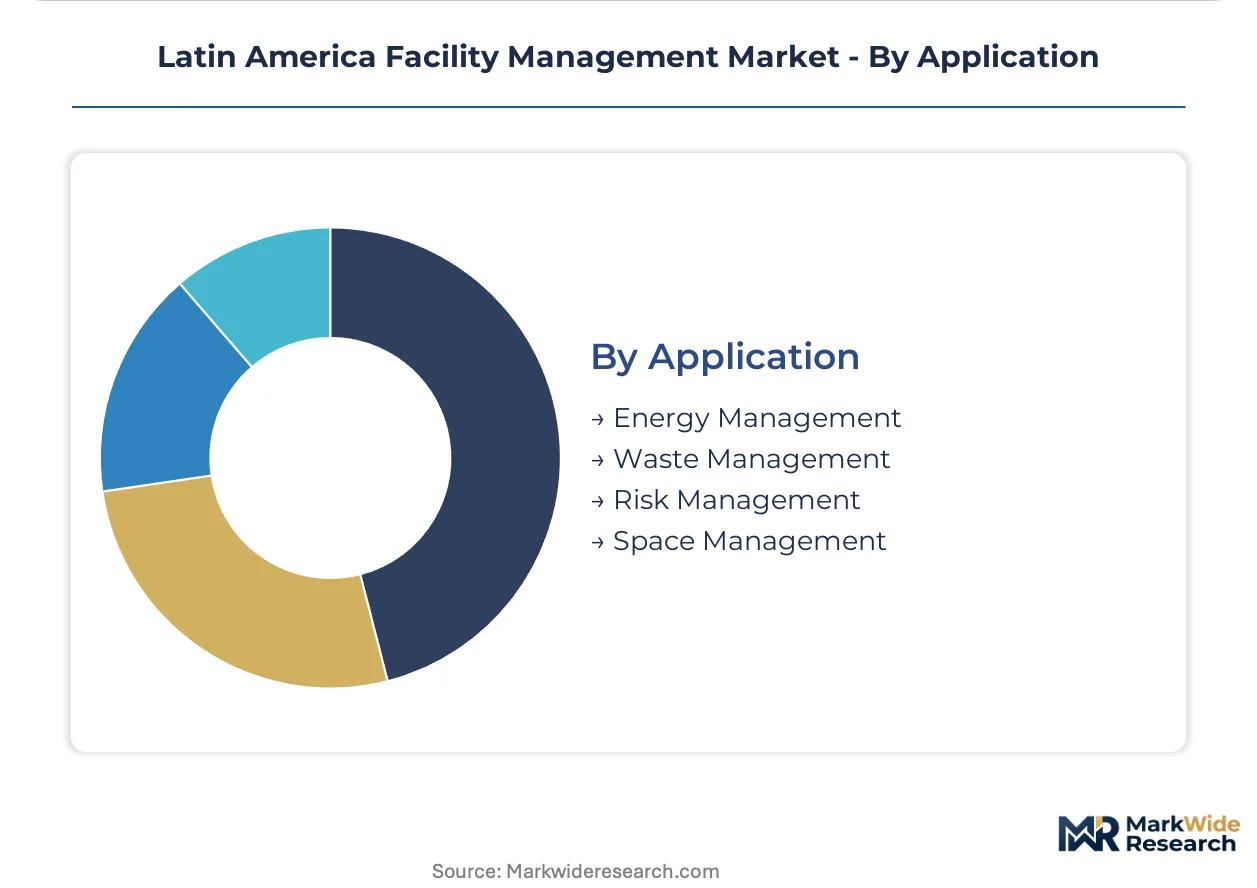
Application:
Customer type specialization separates risk-averse healthcare procurement from efficiency-focused commercial real estate and sustainability-driven public sector mandates.
- Energy Management:Systematic audit and optimization protocols mandated by Mexico's CONUEE certification and Argentina's IRAM building standards. Vendors must demonstrate certified measurement and verification capabilities to qualify for public building contracts.
- Waste Management:Industrial hazardous waste handling and healthcare biohazard disposal requiring specialized certifications and chain-of-custody documentation.
- Risk Management:Business continuity planning and emergency response protocols for critical infrastructure including data centers and tertiary care hospitals.
- Space Management:Occupancy optimization and workplace reconfiguration services gaining traction as hybrid work patterns reshape commercial real estate utilization.
Energy Management leads procurement priority. Space Management is expanding most quickly post-pandemic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives concentrate industrial facility management demand in Brazil's northern corridor. Mexico's IMMEX maquiladora program drives cross-border service standardization. Argentina's Tierra del Fuego special economic zone shapes southern logistics infrastructure requirements.
Brazil
São Paulo's hospital corridor and Rio de Janeiro's commercial towers generate concentrated demand for ANVISA-certified disinfection protocols. Brazil's sanitary regulator mandates chemical formulations and frequency standards that only certified vendors satisfy. Southeast manufacturing zones around Campinas and Sorocaba require specialized industrial cleaning under strict environmental timelines.
Mexico
Mexico City commercial landlords and Monterrey industrial parks drive adoption of CONUEE-compliant energy audit services. Mexico's national energy efficiency commission mandates systematic measurement protocols that disqualify uncertified operators. Northern border states under IMMEX program require cross-standardized facility protocols matching US operational requirements.
Argentina
Buenos Aires aging commercial stock and Córdoba industrial complexes create retrofit-driven maintenance demand. Argentina's IRAM building standards mandate energy audits for public buildings, redirecting procurement toward technology-enabled vendors. Secondary markets like Rosario and Mendoza remain underserved due to certified technician concentration in capital corridors.
Colombia
Bogotá healthcare facilities and Medellín manufacturing zones show sub-15 percent outsourcing rates versus Brazilian benchmarks. Colombia's national infrastructure agency promotes public-private facility partnerships for hospital networks. Caribbean port cities including Barranquilla and Cartagena concentrate logistics facility demand requiring specialized maintenance protocols.
Chile
Santiago's mining headquarters and Antofagasta extraction zones drive specialized industrial facility services. Chile's environmental superintendent enforces tailings facility management standards that extend to remote operational sites. Southern hydroelectric corridors require predictive maintenance capabilities for distributed generation assets.
Latin America Facility Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's facility management landscape. Market structure shows moderate consolidation around integrated service platforms capable of multi-site standardization. Three archetypes dominate: global real estate service conglomerates, specialized industrial cleaning operators, and technology-enabled energy management platforms. M&A activity concentrates on acquiring certified energy auditor capabilities and CMMS-IoT platform integration.
Within the global real estate services tier, CBRE Group, Inc. and Cushman & Wakefield plc occupy positions exemplifying cross-border property platform leverage. ISS A/S and Sodexo, Inc. represent the integrated service bundle archetype, anchoring multi-site healthcare and education campus contracts through standardized KPI frameworks. These players illustrate how technology infrastructure and regulatory certification combine to determine competitive positioning.
| Leading Market Players |
|---|
| Cushman & Wakefield plc |
| Ecolab Inc. |
| CBRE Group, Inc. |
| GPS Group |
| Aramark Corporation |
| ISS A/S |
| Jones Lang LaSalle IP, Inc. |
| Brasanitas Group |
| Sodexo, Inc. |
| Others |
Supply & Pricing Matrix
Healthcare procurement officers across São Paulo's hospital corridor and Mexico City's medical district concentrate contract volume, anchoring a contract-based long-term pricing model that rewards ANVISA-certified vendors with multi-year retention premiums while penalizing uncertified operators through procurement disqualification.
Pricing Analysis
Short lead-time delivery commands premium positioning in Brazilian metropolitan corridors where certified technician scarcity compresses response windows. Three-tier pricing structure across premium, standard, and economy levels separates ANVISA-certified healthcare protocols from commercial janitorial bundles and spot-market residential assignments. Price differentiation rests on certification grade and geographic delivery cost, with São Paulo-Rio de Janeiro corridor operators extracting location premiums against underserved secondary markets. Cost compression in economy-tier residential contracts is intensifying because local operators lack CMMS-IoT infrastructure to match national platform efficiency. Residential condominium associations show highest price sensitivity; tertiary care hospital networks least.
Supply Chain Analysis
Dual-sourcing requirements from Mexico City commercial landlords and Brazilian healthcare networks mandate multi-supplier qualification for CMMS platforms and IoT sensor hardware. Geographic supply concentration draws from United States, China, and Germany for sensor hardware; Brazil and Mexico for labor-intensive service delivery. Raw material dependencies center on lithium-ion sensor batteries, cloud computing infrastructure, and REACH-compliant cleaning chemical formulations. Single-source vulnerability runs through US-dollar-denominated hardware procurement exposed to exchange rate volatility. Distribution runs through direct vendor-client contracts for large healthcare and commercial portfolios, with regional subcontractor networks penetrating secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over certified energy auditor talent and CMMS-IoT platform development determines margin capture across multi-site healthcare contracts.
For Market Incumbents: Deepen backward integration into certified training pipelines to lock ANVISA and CONUEE auditor supply against emerging technology-enabled competitors. Anchor multi-site standardization capabilities to defend against pure-play IoT vendors displacing labor-intensive operators through predictive maintenance protocols. Prioritize CMMS-IoT convergence investments that enable outcome-based pricing aligned with uptime guarantees. For New Entrants and Emerging Players: Secondary healthcare markets in Colombia's Bogotá-Medellín corridor offer sub-15 percent outsourcing penetration versus Brazilian benchmarks, creating first-mover expansion paths for certified operators. Target industrial facility protocols in Brazil's southeastern manufacturing zones where hazardous waste compliance requirements filter out unqualified competitors. Lead with certified energy audit capabilities bundled into facility management contracts to bypass procurement disqualification thresholds. For Investors and Strategic Acquirers: Distressed-cycle entries favor technology-enabled mid-cap specialists in Argentina's Buenos Aires corridor where IRAM compliance mandates redirect procurement toward certified vendors. Long-term viability centers on platforms combining CMMS deployment with real-time sensor infrastructure across multi-site portfolios. Watch CONUEE and IRAM audit volume acceleration as inflection indicator for certified vendor consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| CMMS-IoT Platform Integration | Unified sensor-feed and work-order systems enable outcome-based pricing tied to uptime guarantees. |
| Certified Energy Auditor Acquisition | CONUEE and IRAM compliance mandates create three-year talent shortage arbitrage for qualified vendors. |
| Multi-Site Standardization | Healthcare procurement consolidation favors vendors delivering KPI uniformity across dispersed campuses. |
| Backward Integration into Training | In-house certification pipelines lock scarce ANVISA and CONUEE auditor supply against competitors. |
| Geographic Expansion to Colombia | Bogotá and Medellín healthcare outsourcing rates trail Brazilian benchmarks by substantial margins. |
Research Methodology
Independent corroboration across facility management executives, healthcare procurement officers, and industrial plant managers underwrites the qualitative findings presented. Primary interviews with ANVISA compliance leads, CONUEE-certified energy auditors, and CMMS platform engineers combined with secondary validation from ANVISA regulatory filings, CONUEE audit databases, and SEC disclosures from listed service providers. Bottom-up contract value aggregation and top-down market sizing triangulation anchored regional estimates.
Comparable-period anchoring to historical facility outsourcing penetration rates and technology adoption curves structured the projection framework across the analysis window. Segmentation dimensions modeled include service type intensity, end-user regulatory exposure, technology deployment maturity, and application specialization. CAGRs derived from weighted average of bottom-up contract growth trajectories and top-down macroeconomic drivers. Forecast inputs incorporated IoT sensor cost decline curves and certified auditor training pipeline capacity constraints.
Revisions become necessary when exchange rate volatility exceeds historical bands, regulatory audit mandates accelerate beyond training pipeline capacity, or IoT platform consolidation alters competitive dynamics. Deviation in certified energy auditor availability or CMMS-IoT platform interoperability standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Croatia Facility Management Market
Facility Management
France Facility Management Market
Facility Management
Sweden Facility Management Market
Facility Management
Panama Facility Management Market
Facility Management
Asia Pacific Facility Management Market
Facility Management
Romania Facility Management Market
Facility Management
Egypt Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Mexico Facility Management Market
Facility Management
GCC Facility Management Market
Facility Management
Hungary Facility Management Market
Facility Management
Malta Facility Management Market
Facility Management
Germany Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Italy Facility Management Services Market
Facility Management
Philippines Facility Management Market