
 Norway Facility Management Market | 2026-2036
Norway Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Facility Management Market Analytics
Heat pump technology is realigning thermal service economics in Norwegian buildings as electric district heating yields to decentralized renewable sources. ISS Facility Services leverages its Nordic technical workforce to dominate complex HVAC retrofit portfolios. GK Gruppen AS anchors its position through in-house refrigeration and climate expertise tied to supermarket chains. Coor Service Management competes via integrated workplace management platforms spanning Oslo and Bergen commercial districts.
Facility management encompasses the professional coordination of maintenance, cleaning, security, and technical building services to ensure operational continuity and asset longevity across commercial and public infrastructure. Norwegian FM providers deploy IoT-enabled condition monitoring with temperature, humidity, and vibration sensors to predict equipment failures before disruption occurs. Maintenance services command the largest revenue pool given Norway's aging public building stock and stringent uptime requirements in healthcare and maritime sectors. Cloud-based CMMS platforms represent the fastest-expanding technology segment as municipal clients mandate digital work-order transparency and energy compliance reporting.
The Norwegian Building Authority enforces TEK17 energy standards that compel FM providers to document thermal performance upgrades and ventilation system efficiency. The EU Energy Performance of Buildings Directive, transposed into Norwegian law through the EEA agreement, tightens inspection intervals and disclosure obligations for commercial assets. Stakeholders must monitor how upcoming BREEAM-NOR certification revisions will reshape service scope definitions and contractor qualification thresholds across the country's property portfolio.
Market Dynamics
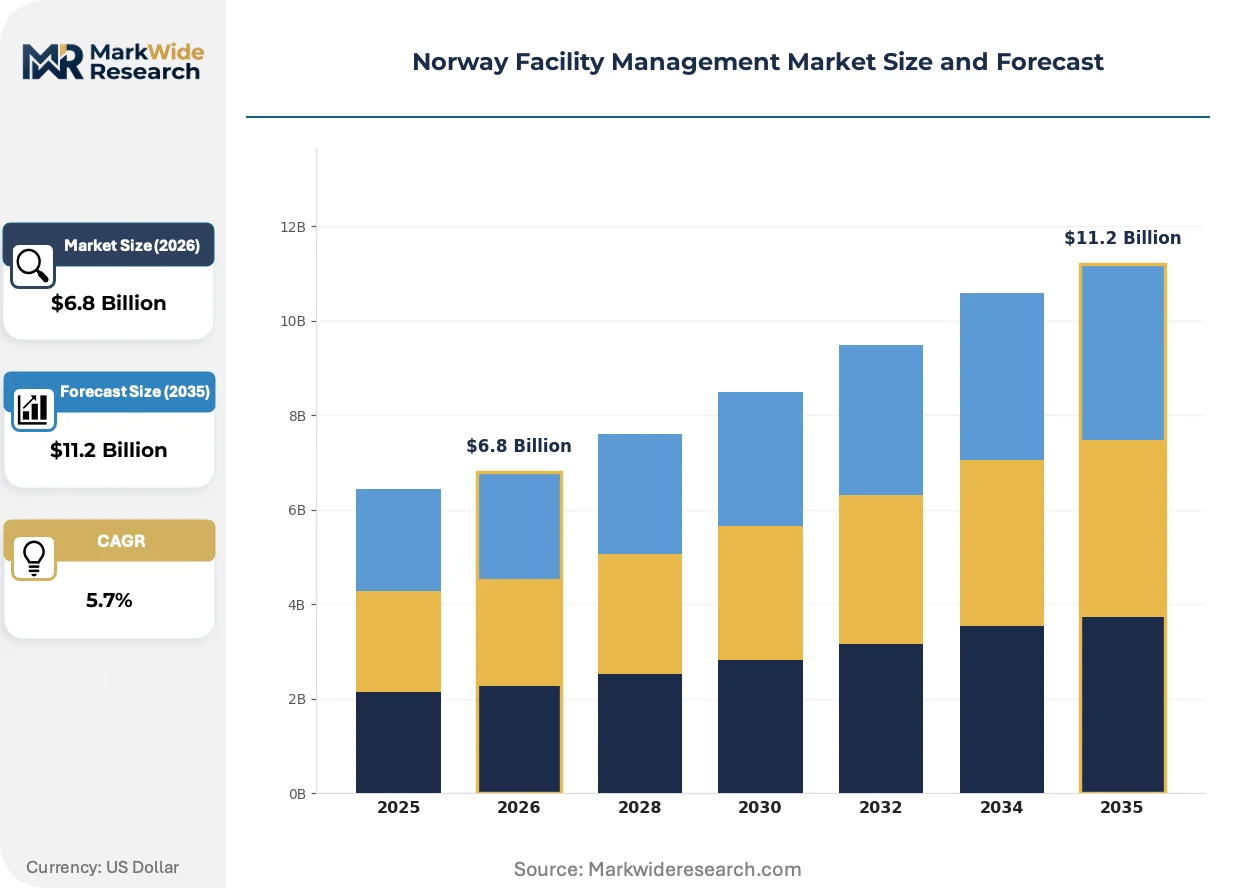
EU Green Deal building efficiency mandates are compressing contract renewal cycles across Norway's public and commercial property portfolio. Heat pump retrofits and IoT-enabled predictive maintenance are reconfiguring service provider capabilities and client procurement criteria.
Growth Catalysts
- TEK17 Energy Standards:The Norwegian Building Authority's thermal performance mandates require documented ventilation upgrades, expanding technical service contracts in municipal and healthcare buildings.
- Hospital Network Outsourcing:Healthcare facilities across Norway's regional health authorities are consolidating non-clinical operations under integrated FM contracts spanning maintenance, cleaning, and security.
- Heat Pump Technology:Decentralized renewable heating systems are displacing electric district heating, creating specialized maintenance demand for refrigeration circuits and thermal storage.
Market Restraints
- Skilled Technician Scarcity:Norway's HVAC and refrigeration certification pipeline cannot match retrofit-driven demand, inflating labor costs for complex building system upgrades.
- Supply Concentration in Oslo:Technical maintenance contracts cluster disproportionately in the capital region, leaving secondary cities underserved and compressing margins through geographic overextension.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants restricts equipment refurbishment options and accelerates capital replacement timelines for climate service providers.
Strategic Opportunities
- Bergen Commercial District Expansion:Western Norway's second-largest city shows underpenetrated integrated workplace management adoption compared to Oslo's mature market.
- BREEAM-NOR Certification Revisions:Upcoming sustainability scoring updates will reshape contractor qualification thresholds and premium service scope definitions.
- Cloud CMMS Platforms:Municipal clients now mandate digital work-order transparency, creating first-mover advantage for providers with native energy compliance reporting capabilities.
Industry Challenges
- IoT-Legacy System Integration:Vibration and temperature sensors must interface with decades-old building automation infrastructure, complicating deployment and data standardization.
- Certification Timeline Compression:EU Energy Performance of Buildings Directive inspection intervals are tightening, straining provider capacity to document thermal upgrades across dispersed portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Facility Management Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Cleaning, Security, Landscaping End User: Corporate, Healthcare, Education, Retail Technology: IoT Solutions, Cloud-Based Systems, CMMS, Energy Management Asset Type: Buildings, Equipment, Infrastructure, Grounds |
| Companies Covered | Toma Facility Services AS, Ability FM, ISS Facility Services, Apleona HSG, GK Gruppen AS, Coor Service Management, Sodexo, CBRE Norway, Compass Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Facility Management Market Evolving Landscape
Digital condition monitoring and predictive algorithms are compressing maintenance response times while regulatory disclosure requirements expand service documentation scope. Three developments are reshaping competitive positioning.
IoT-enabled predictive maintenance is consolidating technical service economics across Norway's aging public building stock. Municipal and healthcare clients now require temperature, humidity, and vibration sensor networks that anticipate equipment failures before operational disruption occurs. This capability compression favors providers with in-house data analytics infrastructure over traditional time-based maintenance contractors.
EU Green Deal building efficiency mandates, transposed through Norway's EEA obligations, are tightening energy performance disclosure requirements for commercial assets. The Energy Performance of Buildings Directive now demands more frequent inspections and public benchmarking, forcing FM providers to document thermal upgrades and ventilation efficiency in standardized formats. Oslo's concentrated commercial real estate absorbs the largest compliance burden, with property managers selecting contractors based on native reporting platform compatibility.
Integrated workplace management platforms are displacing siloed single-service contracts across Norway's corporate and public sectors. Buyers now bundle cleaning, security, technical maintenance, and space optimization under unified vendor relationships with outcome-based performance metrics. Bergen and Stavanger commercial districts show accelerating adoption as regional headquarters seek cost transparency and reduced vendor management overhead.
Norway Facility Management Market Segmentation
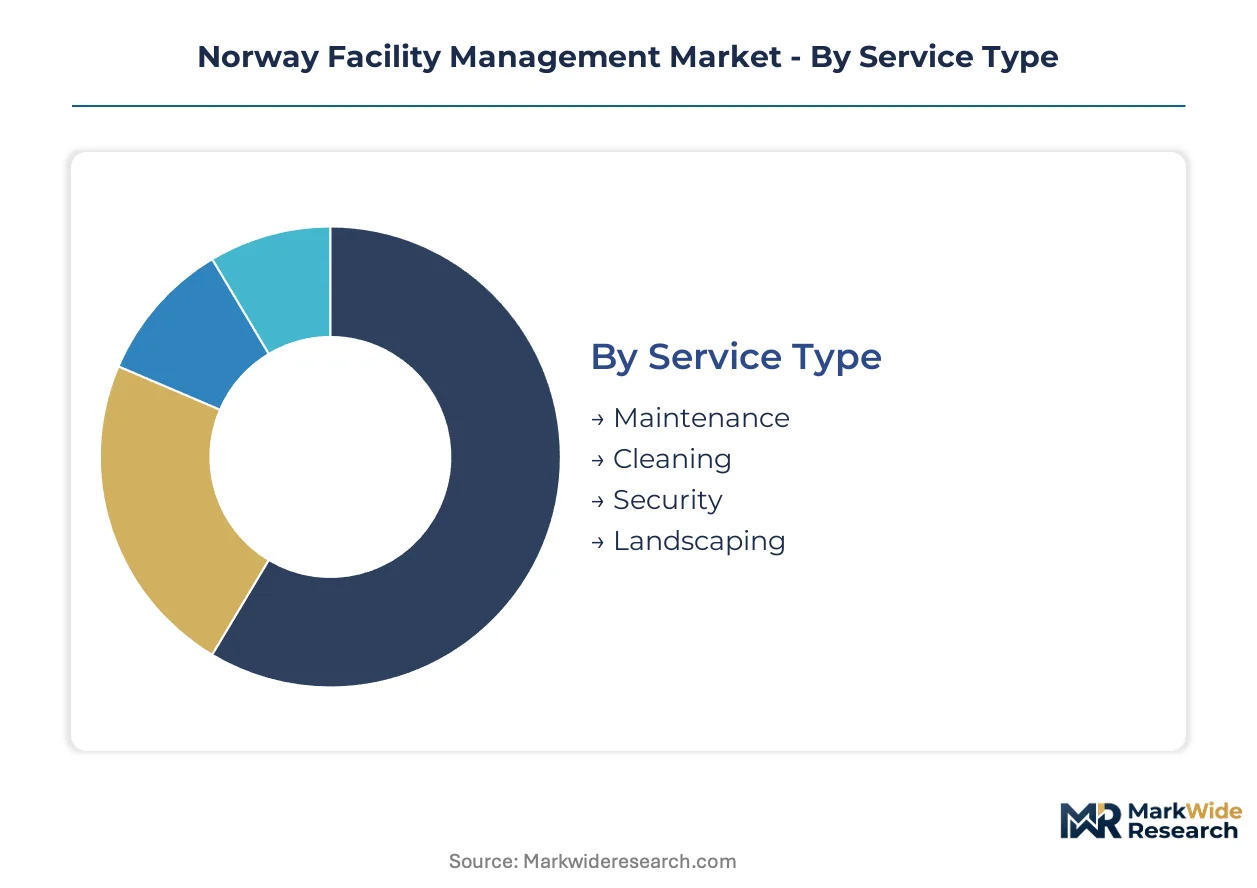
Facility management providers in Norway configure service portfolios around distinct operational risk profiles and asset ownership structures. Procurement patterns diverge sharply between public healthcare networks with stringent uptime mandates and commercial real estate portfolios optimizing for energy disclosure compliance.
Service Type:
Supply concentration tilts toward technical capabilities that satisfy TEK17 documentation requirements and EU energy performance mandates.
- Maintenance:Technical building services encompassing HVAC, electrical, and mechanical systems with predictive algorithms layered atop vibration and temperature sensor networks. Demand concentrates in Oslo's hospital network and aging municipal building stock where downtime carries regulatory or clinical penalties. TEK17 thermal performance mandates expand contract scope to include ventilation efficiency documentation.
- Cleaning:Janitorial and specialized hygiene services for healthcare and commercial environments. Bergen's expanding corporate district shows accelerating integrated procurement alongside technical maintenance.
- Security:Physical access control, surveillance systems, and personnel guarding. Demand clusters in healthcare campuses and critical infrastructure facilities.
- Landscaping:Grounds maintenance, snow removal, and seasonal vegetation management for commercial and public properties.
Maintenance absorbs the bulk of installed capacity; cleaning is expanding most quickly through integrated workplace management bundling.
End User:
Cost tier differentiation separates premium technical service buyers from price-sensitive standardized cleaning contracts.
- Healthcare:Norway's regional health authorities operate hospitals and clinics with 24/7 operational continuity requirements. Outsourcing consolidation spans non-clinical functions under unified FM contracts with outcome-based performance metrics.
- Corporate:Commercial real estate in Oslo and Bergen drives integrated workplace management adoption. EU Green Deal disclosure obligations favor providers with native energy compliance reporting platforms.
- Education:Municipal school portfolios with seasonal occupancy patterns and standardized maintenance protocols.
- Retail:Supermarket chains with specialized refrigeration and climate control requirements.
Healthcare commands premium pricing for technical uptime guarantees; corporate is climbing the fastest through BREEAM-NOR certification-driven procurement.
Technology:
Application maturity varies from established CMMS platforms to emerging sensor networks requiring legacy system integration.
- IoT Solutions:Condition monitoring through temperature, humidity, and vibration sensors that anticipate equipment failures. Deployment concentrates in municipal and healthcare buildings where operational disruption carries high costs. Legacy building automation infrastructure complicates standardized data protocols.
- Cloud-Based Systems:Remote access platforms for work-order management and contractor coordination. Oslo's concentrated commercial real estate absorbs the largest deployment base.
- CMMS:Computerized maintenance management systems with digital work-order transparency now mandated by municipal clients.
- Energy Management:Platforms documenting thermal performance upgrades and ventilation efficiency for EU Energy Performance of Buildings Directive compliance.
CMMS holds the deepest installed base; IoT solutions are gaining share fastest as predictive capabilities compress maintenance response times.
Asset Type:
Customer type segmentation separates public infrastructure with mandated transparency from private equipment with proprietary maintenance protocols.
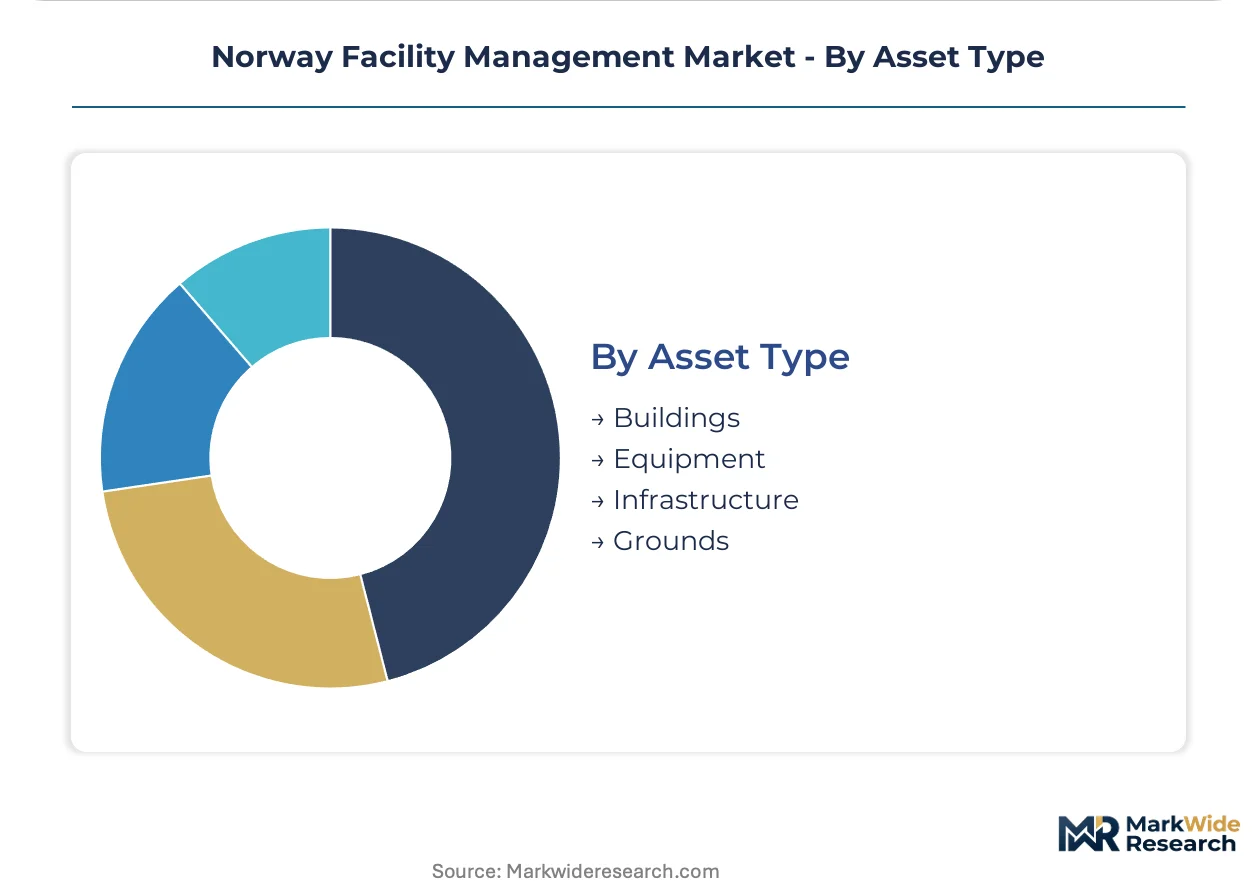
- Buildings:Commercial, healthcare, and educational structures subject to TEK17 energy standards and periodic inspection requirements. Norway's aging public building stock sustains the largest revenue pool.
- Equipment:HVAC, refrigeration, and mechanical systems with specialized technician certification requirements. Heat pump retrofits are displacing electric district heating and reshaping service skill demands.
- Infrastructure:Transportation, utilities, and critical public facilities with security and continuity mandates.
- Grounds:Exterior property maintenance including parking, landscaping, and access routes.
Buildings represent the dominant asset category; equipment is expanding most quickly through heat pump technology transitions and F-Gas Regulation-driven replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oslo absorbs the largest share of technical maintenance contracts nationally, with secondary cities showing significant underpenetration in integrated workplace management services. Norway's regional health authorities and municipal building portfolios drive demand concentration across distinct geographic clusters.
Oslo and Viken
Oslo's commercial real estate concentration dominates national FM contract value, with hospital networks and municipal buildings requiring TEK17-compliant thermal performance documentation. The Norwegian Building Authority enforces stringent ventilation upgrade mandates across this corridor. Akershus municipalities are accelerating cloud-based CMMS adoption for digital work-order transparency.
Bergen and Western Norway
Bergen's expanding corporate district shows accelerating integrated procurement of cleaning and technical maintenance services. Healthcare facilities in Hordaland are consolidating non-clinical operations under unified FM contracts. The city's port infrastructure and maritime clusters generate specialized equipment maintenance demand.
Trøndelag
Trondheim's university hospital network and public building stock sustain technical service contracts with stringent uptime requirements. Municipal clients in this region mandate energy compliance reporting for aging infrastructure. Stjørdal's logistics hubs create secondary demand nodes for facility services.
Stavanger and Rogaland
Stavanger's energy sector headquarters drive premium integrated workplace management adoption with outcome-based performance metrics. The region's industrial facilities require specialized HVAC and refrigeration expertise. Sandnes commercial developments are expanding FM service procurement.
Troms and Finnmark
Northern Norway's dispersed healthcare facilities face geographic overextension challenges for technical maintenance response times. Arctic climate conditions accelerate building envelope deterioration and heating system degradation. Bodø's municipal building portfolio is piloting IoT-enabled condition monitoring for predictive maintenance.
Norway Facility Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated workplace management platforms consolidating procurement decisions toward fewer vendor relationships. The vendor base clusters around three capability tiers: Nordic technical workforce specialists, in-house refrigeration and climate experts, and digital platform integrators. Dominant competitive moves include portfolio diversification into energy compliance reporting and geographic expansion from Oslo into secondary cities.
Within the Nordic technical specialist tier, ISS Facility Services and GK Gruppen AS occupy anchor positions. ISS represents the scale-driven archetype with broad HVAC retrofit capabilities, while GK exemplifies vertical climate expertise tied to retail refrigeration chains. Coor Service Management sits within the digital-first tier, leveraging integrated workplace management platforms across Oslo and Bergen commercial districts. Sodexo and Compass Group represent the global diversified services archetype competing through bundled non-technical service offerings.
| Leading Market Players |
|---|
| Toma Facility Services AS |
| Ability FM |
| ISS Facility Services |
| Apleona HSG |
| GK Gruppen AS |
| Coor Service Management |
| Sodexo |
| CBRE Norway |
| Compass Group |
| Others |
Value Network & Pricing Analysis
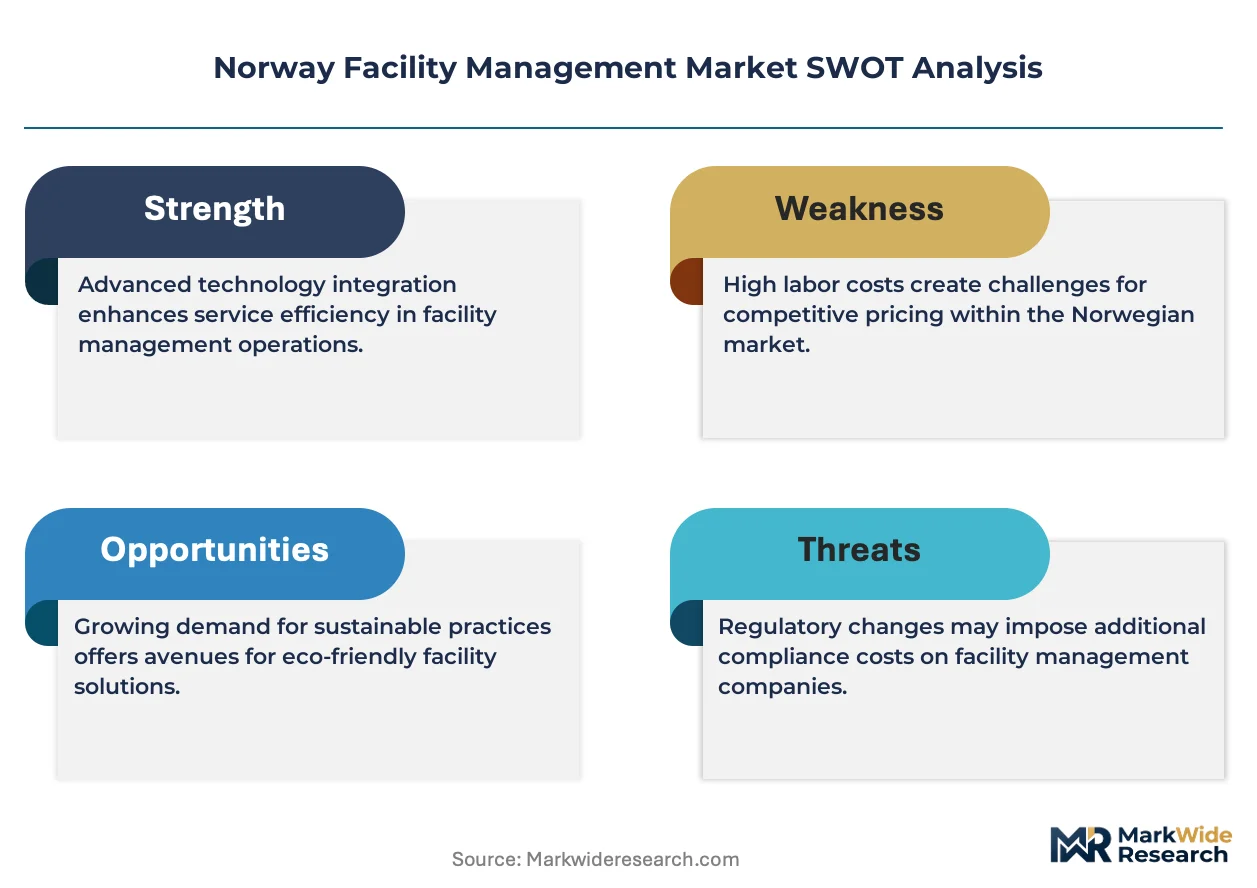
Private-equity-rolled-up specialists across Norway's facility management sector compress contract margins through standardized service bundles while sovereign-backed municipal clients enforce cost transparency via digital procurement platforms. This ownership-financing duality concentrates pricing power with scale players who can absorb TEK17 compliance documentation costs, forcing mid-tier contractors toward niche technical specializations or geographic retreat.
Pricing Analysis
Volume-driven maintenance contracts trade margin for portfolio scale while premium integrated workplace management bundles capture pricing power through outcome-based performance guarantees. Three-tier pricing structure across premium, standard, and economy levels separates BREEAM-NOR certified providers from municipal baseline contractors and spot-market cleaning vendors. Cost compression in standard-tier technical services intensifies because Oslo's hospital networks consolidate procurement under framework agreements. Corporate real estate buyers in Bergen and Stavanger show lowest price sensitivity for native energy compliance reporting platforms, while municipal education portfolios drive hardest bargain on standardized cleaning scope.
Supply Chain Analysis
Single-source vulnerability sits with German HVAC component manufacturers who dominate heat pump refrigeration circuit supplies into Norwegian retrofit projects. Equipment sourcing draws from Germany, Sweden, and Denmark for climate systems, with sensor hardware anchored in South Korea and Taiwan for IoT condition monitoring deployments. Tariff exposure runs through EU F-Gas Regulation phasedown timelines that restrict hydrofluorocarbon refrigerant availability and accelerate capital replacement cycles. Distribution runs through regional service depots in Oslo, Bergen, and Trondheim with technician dispatch radii constrained by Norway's dispersed geography and Arctic climate access challenges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's facility management market operates as a cost-of-compliance story where TEK17 energy standards and EU Energy Performance of Buildings Directive documentation requirements erect barrier-to-entry moats favoring incumbent providers with certified technical workforces and native digital reporting infrastructure.
For Market Incumbents: Anchor market position through captive supply of HVAC and refrigeration technician certification programs, countering skilled labor scarcity that threatens service quality commitments. Defend against emerging digital-native competitors by deepening backward integration into IoT sensor deployment and data analytics capabilities rather than outsourcing predictive maintenance algorithms to third-party platforms. For New Entrants and Emerging Players: The premium-to-economy price-point gap in integrated workplace management services creates entry opportunity for mid-tier providers who bundle cleaning and technical maintenance without full BREEAM-NOR certification overhead. Target Bergen's underpenetrated corporate district with hybrid digital-physical service models that undercut Oslo-scale incumbents on vendor management overhead while matching their energy compliance reporting capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional FM specialists with concentrated municipal healthcare contracts in Trøndelag and Western Norway who face succession liquidity events but retain irreplaceable technical workforce relationships. Watch for inflection signals in EU Green Deal building efficiency mandate enforcement intensity, which will accelerate consolidation pressure on non-compliant mid-cap contractors unable to fund thermal upgrade documentation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | Captures scarce HVAC and refrigeration labor capacity before TEK17 retrofit demand peaks. |
| Cloud CMMS Platform Development | Meets municipal client mandates for digital work-order transparency and energy compliance reporting. |
| Heat Pump Service Capability Expansion | Positions providers for decentralized renewable heating transition displacing electric district heating. |
| Geographic Expansion to Secondary Cities | Accesses Bergen and Stavanger commercial districts with lower competitive intensity than Oslo. |
| IoT-Legacy System Integration Partnership | Solves deployment friction from decades-old building automation infrastructure in municipal portfolios. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across facility management executives, municipal procurement officers, healthcare estates directors, and HVAC technician training program administrators. Norwegian Building Authority TEK17 documentation, EU Energy Performance of Buildings Directive transposition texts, and regional health authority contract award notices supplemented operational metrics. Bottom-up service provider revenue estimates triangulated against top-down building stock maintenance spend projections.
Segment-level granularity modeled service type, end user, technology deployment, and asset category dimensions across the projection horizon, with regional splits calibrated to Oslo-Viken, Bergen-Western Norway, Trøndelag, Stavanger-Rogaland, and Troms-Finnmark clusters. CAGRs derived from fitted growth curves accounting for TEK17 enforcement timelines, hospital network outsourcing waves, and heat pump technology penetration rates. Forecast inputs incorporated technician certification pipeline constraints and EU F-Gas Regulation equipment replacement cycles.
Inputs from municipal procurement databases and healthcare contract registries were available through the study window; gaps in private commercial real estate service spend introduce uncertainty bands around corporate segment projections. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Croatia Facility Management Market
Facility Management
India Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
Bahrain Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Kuwait Facility Management Market
Facility Management
North America Soft Facility Management Market
Facility Management
UK Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
South Africa Facility Management Market
Facility Management
Saudi Arabia Soft Facility Management Market