
 Kuwait Facility Management Market | 2026-2036
Kuwait Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Facility Management Market Foresight
Expatriate technical labor availability is rotating through cyclical tightening phases that directly shape service delivery capacity across Kuwait. Kharafi National FM leverages its long-standing government relationships to secure infrastructure-linked contracts. ENGIE Services General Contracting for Buildings Company WLL sustains competitive advantage through technology-forward energy management integration. Tanzifco Company W.L.L. anchors its position in the cleaning and hospitality support segment with specialized workforce training programs.
Facility management encompasses the integrated operation, maintenance, and optimization of built environments including HVAC, electrical, plumbing, and safety systems with performance benchmarks tied to occupancy uptime and energy intensity per square meter. The discipline serves commercial, institutional, and residential assets by ensuring regulatory compliance, operational continuity, and lifecycle cost control. Maintenance services command the largest revenue share due to mandatory equipment upkeep requirements in Kuwait's extreme climate conditions. Smart Building Systems represent the fastest-expanding technology category as developers embed IoT infrastructure into new construction. Performance-Based Contracts are gaining traction as clients shift from input-based payments to measurable outcome frameworks.
Kuwait's Ministry of Electricity and Water enforces building energy codes that mandate efficient system operation, while the Public Authority for Industry oversees standards compliance through periodic facility audits. The country's national fire safety regulator imposes strict maintenance protocols on commercial and residential high-rises, creating recurring inspection and certification demand. Stakeholders must monitor how Kuwait's ongoing infrastructure privatization reshapes contract structures and vendor qualification requirements.
Market Dynamics
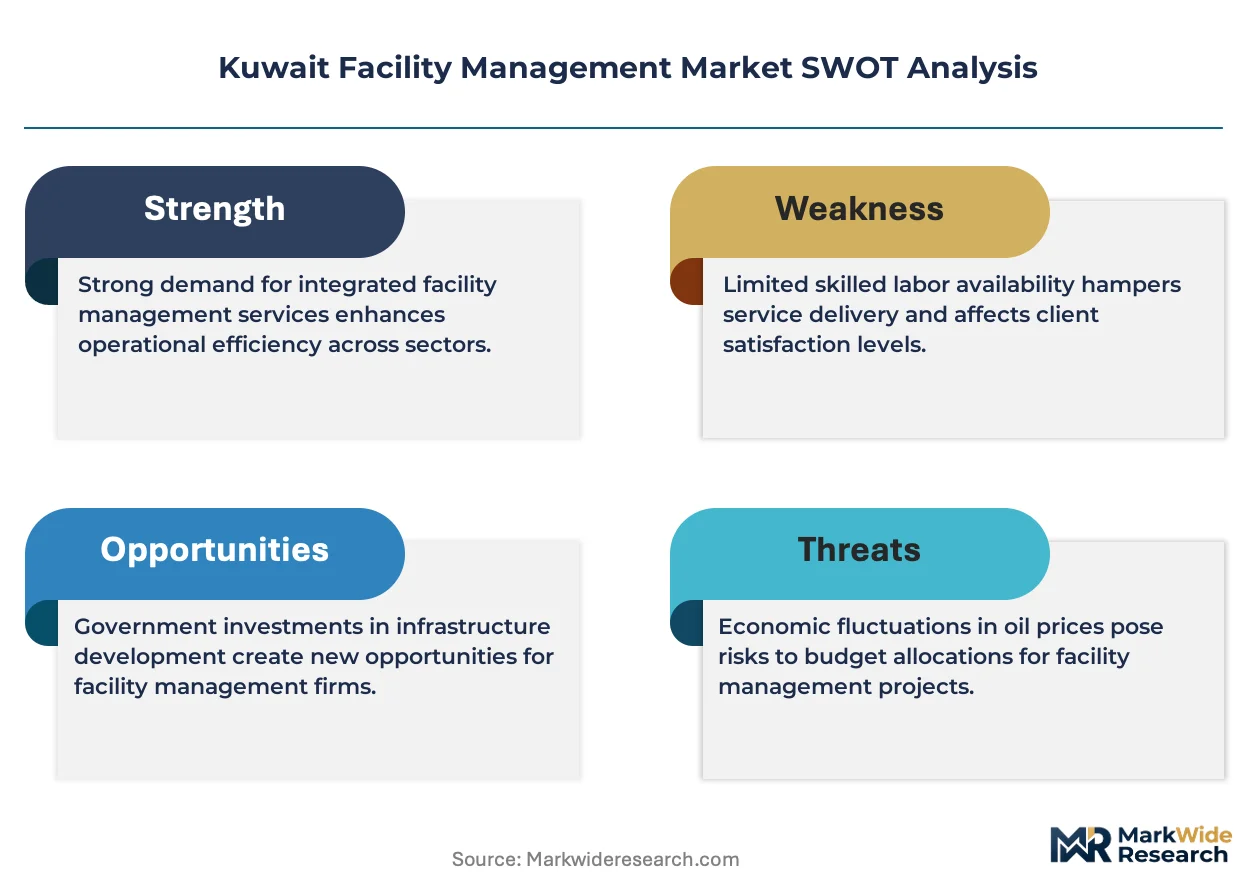
Energy efficiency mandates from Kuwait's Ministry of Electricity and Water are compressing operational margins while forcing asset owners toward integrated service models that bundle maintenance with consumption optimization.
Growth Catalysts
- New Construction Codes:Kuwait's Ministry of Electricity and Water mandates real-time energy monitoring in commercial buildings above 10,000 square meters, creating mandatory retrofit demand across aging stock.
- Smart Building Infrastructure:IoT sensor networks embedded during construction of Kuwait City mega-projects generate recurring data-analytics service contracts for facility operators.
- Fire Safety Enforcement:The national fire safety regulator's annual certification requirements for high-rise residential towers sustain inspection and maintenance revenue pools.
Market Restraints
- Technical Labor Scarcity:Cyclical tightening in expatriate visa approvals restricts field technician availability during peak summer maintenance windows.
- Imported Equipment Dependence:HVAC and BMS hardware concentrates in European and East Asian supply chains, exposing operators to freight cost volatility and extended lead times.
- Regulatory Fragmentation:Overlapping authority between the Public Authority for Industry and municipal building departments creates compliance timeline uncertainty for multi-site operators.
Strategic Opportunities
- Jahra Governorate Expansion:New residential city developments west of Kuwait City lack established FM vendor relationships, creating first-mover positioning for integrated service providers.
- Performance Contracting Models:Kuwait's infrastructure privatization framework enables energy savings performance contracts where operators capture upside from consumption reductions.
- Predictive Maintenance Convergence:Machine learning analytics layered atop existing BMS infrastructure is compressing equipment failure rates and extending asset lifecycles for early adopters.
Industry Challenges
- Multilingual Workforce Coordination:Field teams span Arabic, Hindi, Tagalog, and English, complicating safety protocol adherence and quality standard documentation.
- Legacy System Integration:1990s-era building automation protocols in Kuwait City commercial stock resist seamless connectivity with cloud-based analytics platforms.
- Certification Bottlenecks:The Public Authority for Industry's equipment calibration approval queues extend project commissioning timelines by six to eight weeks during peak periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Facility Management Market |
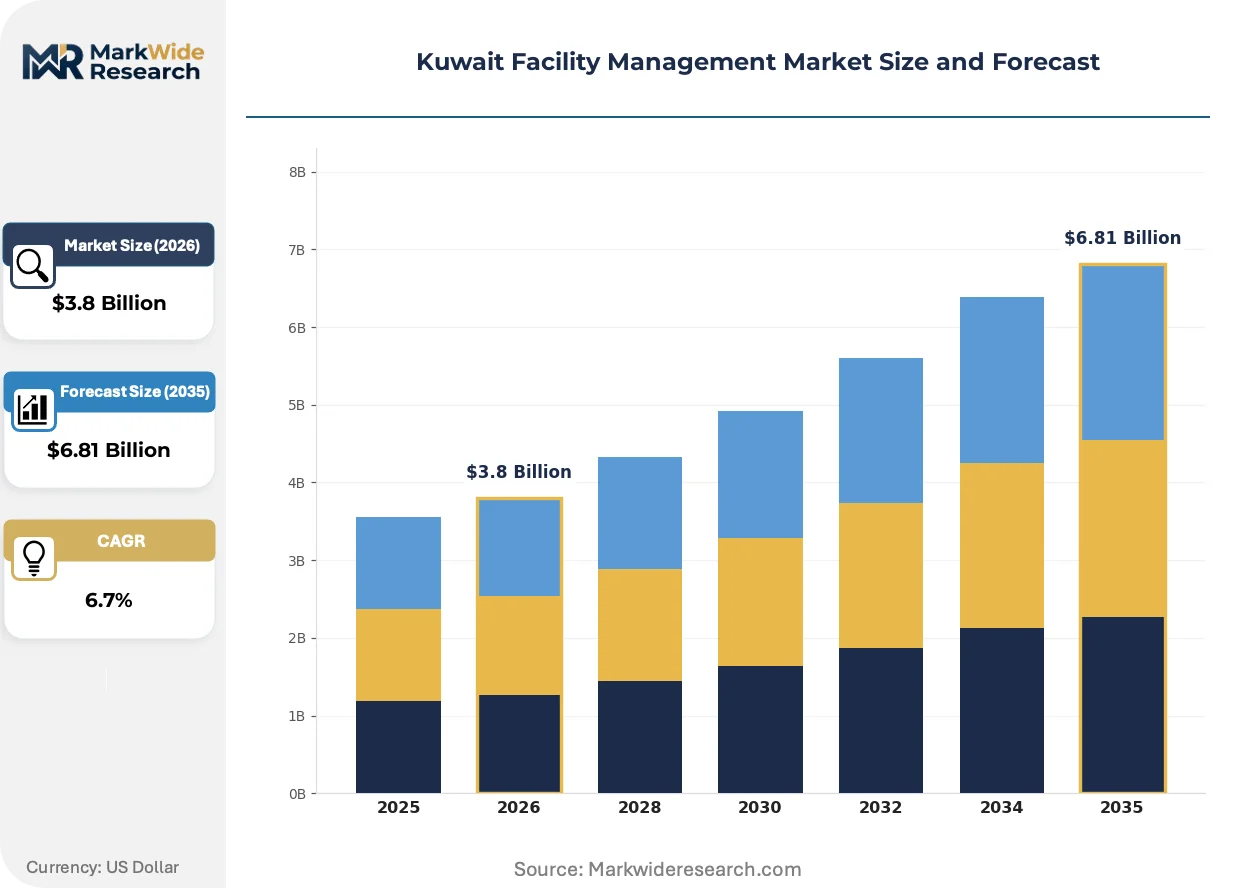
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
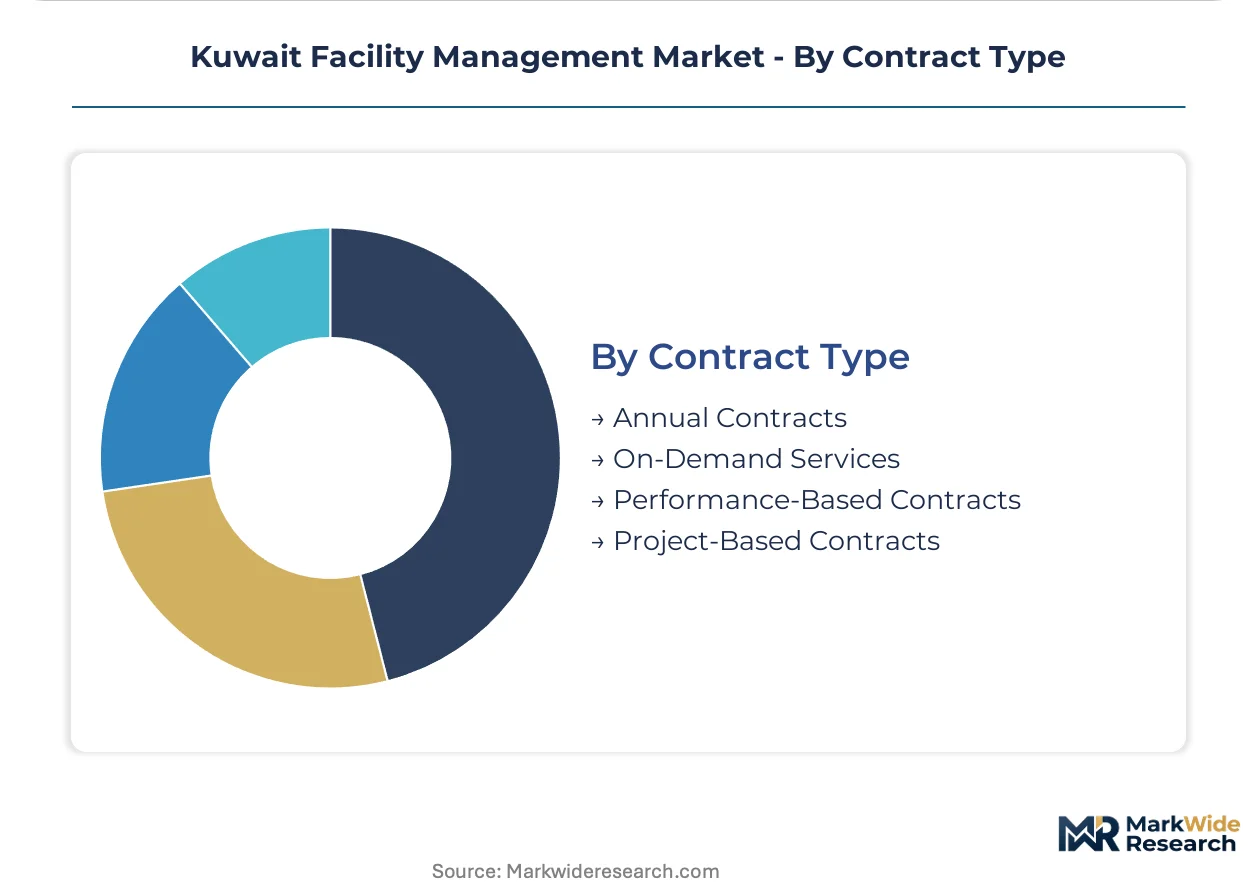
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping End User: Corporate Offices, Residential Buildings, Shopping Malls, Educational Institutions Technology: IoT Solutions, Energy Management Systems, Smart Building Systems, Automated Control Systems Contract Type: Annual Contracts, On-Demand Services, Performance-Based Contracts, Project-Based Contracts |
| Companies Covered | Al Mazaya Holding Company KSCP, United Facilities Management Company (UFM), PIMCO Kuwait, Alghanim International General Trading & Contracting Co. W.L.L., RS Public Facilities Management W.L.L, Kharafi National FM, ENGIE Services General Contracting for Buildings Company WLL, Tanzifco Company W.L.L., EcovertFM Kuwait, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Facility Management Market Shifts & Advancements
Digital infrastructure is compressing traditional maintenance cycles while regulatory pressure on consumption intensity forces convergence between operational technology and enterprise software layers.
Cloud-native building management platforms are displacing on-premise SCADA installations in Kuwait's new commercial developments. Property developers at Al Shaheed Park and Kuwait Finance House headquarters have specified API-first systems during construction. This architecture is displacing five-year hardware refresh cycles with continuous software update models that shift capital expenditure to operational budgets.
Kuwait's Ministry of Electricity and Water revised building energy codes in 2024 to mandate automated fault detection for HVAC systems above 100 kilowatts. The regulation requires continuous commissioning rather than annual inspection, forcing facility operators to deploy permanent sensor networks. Commercial real estate in Kuwait City and Hawally Governorate faces the steepest compliance cost escalation, with landlords passing retrofit investments through service charge rebalancing.
Asset owners are unbundling maintenance contracts from single-source facilities operators, instead awarding specialized scopes to certified niche providers. Cleaning and security services now frequently separate from technical maintenance in tender structures. This fragmentation is most pronounced in Kuwait City financial district towers, where sovereign wealth fund landlords demand granular performance visibility by trade discipline rather than consolidated reporting.
Kuwait Facility Management Market Segmentation
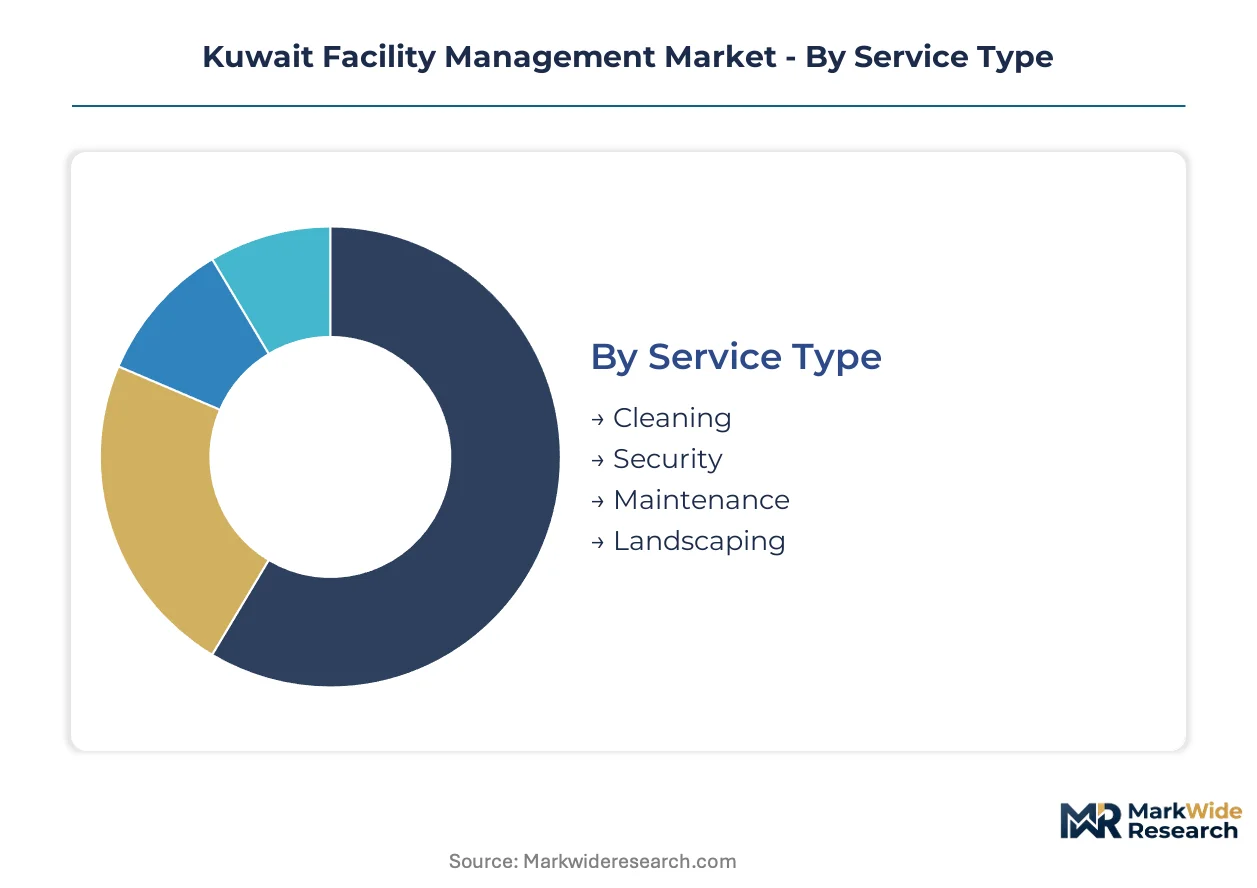
Segmentation in Kuwait's facility management market reveals how service providers must align capabilities with distinct procurement patterns, technology adoption curves, and compliance requirements across asset classes. Understanding these divides enables vendors to position against substitute threats from in-house operations and adjacent service categories.
Service Type:
Cleaning services face the strongest substitution pressure from in-house staffing models, particularly among government entities and large corporate occupiers seeking direct labor control.
- Maintenance:Encompasses HVAC, electrical, plumbing, and mechanical system upkeep with mandatory inspection protocols tied to fire safety and energy efficiency certifications. Demand concentrates in Kuwait City commercial towers where the Ministry of Electricity and Water enforces continuous commissioning requirements, and extreme climate conditions accelerate equipment degradation cycles.
- Security:Includes manned guarding, access control, surveillance systems, and emergency response coordination. Corporate offices in the financial district and high-rise residential towers drive procurement, with landlords unbundling these services from integrated FM contracts to gain granular performance visibility.
- Cleaning:Covers daily janitorial, deep sanitization, and specialized surface treatment for commercial and healthcare environments. Kuwait City shopping malls and educational institutions sustain volume, though labor cost pressures erode margins against in-house alternatives.
- Landscaping:Encompasses irrigation, hardscape maintenance, and vegetation management for commercial exteriors and public spaces. Al Shaheed Park developments and new residential city projects in Jahra Governorate generate project-based demand with seasonal variation.
Maintenance anchors the volume base while smart building integration is gaining share at the steepest rate.
End User:
Corporate offices command premium pricing tiers due to specialized service level agreements and technology integration requirements that residential buildings rarely match.
- Corporate Offices:Financial district towers and sovereign wealth fund headquarters demand integrated FM with real-time energy analytics and automated fault detection. Kuwait City landlords specify API-first building management platforms during construction, creating recurring software service contracts.
- Residential Buildings:High-rise towers require fire safety certification maintenance and common area upkeep under building management committee oversight. Hawally Governorate and Salmiya clusters face compliance cost escalation as energy codes tighten.
- Shopping Malls:Extended operating hours and high foot traffic drive cleaning frequency and HVAC load management requirements. The Avenues Mall and 360 Mall anchor demand for specialized retail FM providers.
- Educational Institutions:Universities and K-12 facilities require seasonal maintenance windows and safety protocol adherence across multilingual workforces. Kuwait University campuses and private school networks sustain project-based contracting.
Corporate offices dominate value capture while educational institutions expand procurement most quickly.
Technology:
Technology deployment correlates directly with building vintage, creating a bifurcated market where new construction commands connected systems and aging stock resists integration.
- Smart Building Systems:Integrated platforms combining HVAC, lighting, and security control with centralized dashboards. New Kuwait City mega-projects embed these during construction, displacing legacy SCADA with cloud-native architectures.
- IoT Solutions:Sensor networks for occupancy detection, air quality monitoring, and predictive maintenance trigger generation. The Ministry of Electricity and Water mandates real-time energy monitoring for commercial buildings above specified thresholds.
- Energy Management Systems:Software layers optimizing consumption patterns against tariff structures and demand response programs. Commercial landlords pass retrofit investments through service charge rebalancing.
- Automated Control Systems:Programmable logic controllers and building automation protocols managing mechanical equipment operation. Legacy 1990s-era installations in Kuwait City commercial stock resist seamless cloud connectivity.
Smart Building Systems anchor installed base expansion while IoT Solutions climb the fastest.
Contract Type:
Contract structure selection reflects client sophistication, with institutional landlords leading the shift from input-based to outcome-based commercial terms.
- Annual Contracts:Fixed-scope, fixed-price agreements covering recurring maintenance and cleaning services. Traditional landlords and government entities prefer budget certainty over performance risk transfer.
- Performance-Based Contracts:Outcome frameworks tying vendor compensation to energy savings, uptime metrics, or service level achievement. Infrastructure privatization enables operators to capture upside from consumption reductions.
- On-Demand Services:Ad-hoc procurement for emergency repairs, specialized cleaning, or seasonal landscaping. Smaller commercial occupiers and residential building committees utilize this for non-core requirements.
- Project-Based Contracts:Discrete scopes for system upgrades, retrofit installations, or new construction commissioning. Equipment calibration approval queues from the Public Authority for Industry extend timelines.
Annual Contracts sustain volume foundations while Performance-Based Contracts accelerate adoption most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Public Authority for Industry anchors regulatory oversight across Kuwait's governorates, with energy efficiency mandates from the Ministry of Electricity and Water driving differential compliance costs across sub-regional markets.
Kuwait City
Financial district towers and sovereign wealth fund headquarters concentrate demand for integrated FM with real-time energy analytics. The Ministry of Electricity and Water enforces continuous commissioning requirements for commercial buildings above 10,000 square meters. Al Shaheed Park developments and Kuwait Finance House headquarters embed API-first building management platforms during construction.
Hawally Governorate
High-rise residential clusters face escalating compliance costs as energy codes tighten and fire safety certification requirements expand. The national fire safety regulator mandates annual inspection protocols for towers above specified height thresholds. Salmiya's commercial corridors sustain volume for specialized retail FM providers serving extended operating hours.
Jahra Governorate
New residential city developments west of Kuwait City lack established vendor relationships, creating first-mover positioning opportunities for integrated service providers. Infrastructure privatization frameworks enable energy savings performance contracts in emerging districts. Suburban commercial zones generate project-based demand with seasonal variation in landscaping and irrigation services.
Ahmadi Governorate
Industrial facilities and oil sector adjacent operations require specialized maintenance protocols distinct from commercial asset management. The Public Authority for Industry oversees equipment calibration approval queues that extend project commissioning timelines. Mina Al-Ahmadi port proximity creates logistics advantages for imported HVAC and BMS hardware distribution.
Kuwait Facility Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with contract unbundling trends fragmenting procurement across trade-specific vendors. Consolidation pressure concentrates among technology-forward operators capable of bundling maintenance with consumption optimization. Two strategic archetypes dominate: government-linked infrastructure specialists and energy management integrators. Competitive moves center on securing mega-project construction-linked contracts and deploying predictive maintenance analytics atop existing BMS infrastructure.
Within the integrated infrastructure tier, Kharafi National FM and ENGIE Services General Contracting for Buildings Company WLL exemplify divergent positioning strategies. Kharafi National FM occupies a position anchored by long-standing government relationships securing infrastructure-linked contracts. ENGIE Services General Contracting for Buildings Company WLL represents the technology-forward archetype through energy management integration capabilities. Tanzifco Company W.L.L. sits within the specialized workforce training segment, anchoring cleaning and hospitality support services with differentiated labor development programs.
| Leading Market Players |
|---|
| Al Mazaya Holding Company KSCP |
| United Facilities Management Company (UFM) |
| PIMCO Kuwait |
| Alghanim International General Trading & Contracting Co. W.L.L. |
| RS Public Facilities Management W.L.L |
| Kharafi National FM |
| ENGIE Services General Contracting for Buildings Company WLL |
| Tanzifco Company W.L.L. |
| EcovertFM Kuwait |
| Others |
Supply & Pricing Matrix
Kuwait's Ministry of Electricity and Water certification requirements for continuous commissioning systems simultaneously gate vendor qualification and stratify service pricing across integrated and standalone maintenance providers. The Public Authority for Industry equipment calibration approval queues compress margins for operators unable to front-load certification costs, while asset owners pass compliance investments through service charge rebalancing.
Pricing Analysis
Kuwait City commands 15-25% pricing premiums over Jahra Governorate for equivalent integrated FM scopes due to sovereign wealth fund landlord sophistication and technology integration mandates. Three-tier pricing structure across premium, standard, and economy levels separates API-first building management platforms from legacy SCADA maintenance and basic cleaning services. Price differentiation rests on certification tier and real-time energy analytics capability. Cost compression in the standard tier intensifies because unbundling trends fragment procurement volumes. Government entities exhibit highest price sensitivity; financial district corporate offices least.
Supply Chain Analysis
Mina Al-Ahmadi port congestion on European and East Asian trade lanes elevates inbound logistics costs for HVAC and BMS hardware by 8-12% during peak summer maintenance windows. Equipment concentrates in Germany, Japan, and South Korea for building automation systems; China and India for sensor components and programmable logic controllers. Raw material dependencies span copper for electrical infrastructure, semiconductors for IoT sensor networks, and specialized refrigerants for HVAC systems. Single-source vulnerability concentrates in European BMS protocol licensors. Distribution runs through Kharafi National FM and ENGIE Services General Contracting for Buildings Company WLL for integrated projects, with specialized cleaning and security vendors handling unbundled scopes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's facility management market presents a defensive-moat story anchored in regulatory entrenchment. The Ministry of Electricity and Water continuous commissioning mandates and Public Authority for Industry certification requirements create switching costs that protect incumbent positions.
For Market Incumbents: Consolidate technology-forward capabilities through predictive maintenance analytics deployment atop existing BMS infrastructure. Acquire specialized cleaning or security operators to recapture volumes lost to contract unbundling. Vertical integration into IoT sensor installation and commissioning protects margins against hardware supply volatility. For New Entrants and Emerging Players: Anchor in Jahra Governorate new residential city developments where established vendor relationships remain unformed. Target energy savings performance contracts enabled by infrastructure privatization frameworks. Deploy machine learning analytics as differentiated go-to-market positioning against legacy maintenance operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional FM platforms seeking exit liquidity to global infrastructure funds. Long-term viability hinges on technology integration depth rather than labor scale. Acquisition target archetype: mid-cap operators with API-first building management platform deployments and Ministry of Electricity and Water certification pipelines. Monitor Jahra Governorate residential city commissioning timelines as inflection indicator for contract award velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Machine learning analytics atop BMS infrastructure compresses equipment failure rates for Kuwait City commercial towers. |
| Energy Savings Performance Contracting | Infrastructure privatization frameworks enable operators to capture upside from Ministry of Electricity and Water consumption reductions. |
| Specialized Workforce Certification Investment | Public Authority for Industry calibration approval capabilities shorten project commissioning timelines by six to eight weeks. |
| Jahra Governorate First-Mover Positioning | New residential city developments lack established FM vendor relationships, creating contract origination advantages. |
| API-First Building Management Integration | Cloud-native platforms displace legacy SCADA installations at Al Shaheed Park and Kuwait Finance House headquarters. |
Research Methodology
Desk research of trade association filings, customs records, and regulatory gazettes preceded structured interviews with facility management executives, building automation engineers, sovereign wealth fund asset managers, and Public Authority for Industry certification officers. Primary fieldwork combined with secondary validation against Ministry of Electricity and Water mandate documentation, national fire safety regulator protocols, and commercial real estate leasing databases. Bottom-up service provider revenue modeling triangulated against top-down construction spend allocation across Kuwait's governorates.
Variance decomposition across service type, end user, technology, and contract type segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from equipment replacement cycles, regulatory compliance phase-in schedules, and mega-project construction timelines. Industry-specific forecast inputs incorporated continuous commissioning mandate enforcement intensity and expatriate technical labor visa approval cyclicality.
Decision-makers should treat outputs as directional under sustained Ministry of Electricity and Water energy code enforcement and stable expatriate labor policy; material deviation would warrant model refresh. Specific risks include regulatory fragmentation escalation between Public Authority for Industry and municipal departments, or abrupt visa restriction tightening during peak maintenance windows. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
United States Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Norway Facility Management Market
Facility Management
Soft Facility Management Market
Facility Management
Central and Eastern Europe (CEE) Facility Management Market
Facility Management
Vietnam Facility Management Market
Facility Management
Refrigerated Warehousing Market
Facility Management
Global Unified Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Austria Facility Management Market
Facility Management
Facility Management Services Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Brazil Facility Management Market