
 Latin America Soft Facility Management Market | 2026-2036
Latin America Soft Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Soft Facility Management Market Foresight
Biodegradable cleaning chemistry is pivoting away from petrochemical surfactants in soft facility management contracts across Latin America. Sodexo Inc. leverages its integrated service platforms to bundle cleaning with catering and security across Brazilian corporate campuses. CBRE Group Inc. anchors its regional position through technology-enabled facility oversight, while ISS A/S competes via specialized healthcare sanitation protocols that meet stringent hospital accreditation standards.
Soft facility management encompasses non-technical building services including cleaning, security, landscaping, and routine maintenance, typically delivered through labor-intensive workflows with increasing sensor-based performance verification. Its primary purpose is sustaining occupant health, safety, and productivity in commercial and institutional environments without altering building infrastructure. Cleaning services dominate contract value across Latin America due to recurring daily labor requirements and regulatory hygiene mandates, while smart building systems represent the fastest-expanding technology segment as property managers deploy IoT-enabled occupancy sensors to optimize janitorial scheduling and reduce waste. Facility management software is capturing margin concentration through subscription-based analytics platforms that demonstrate measurable cost reductions to procurement officers.
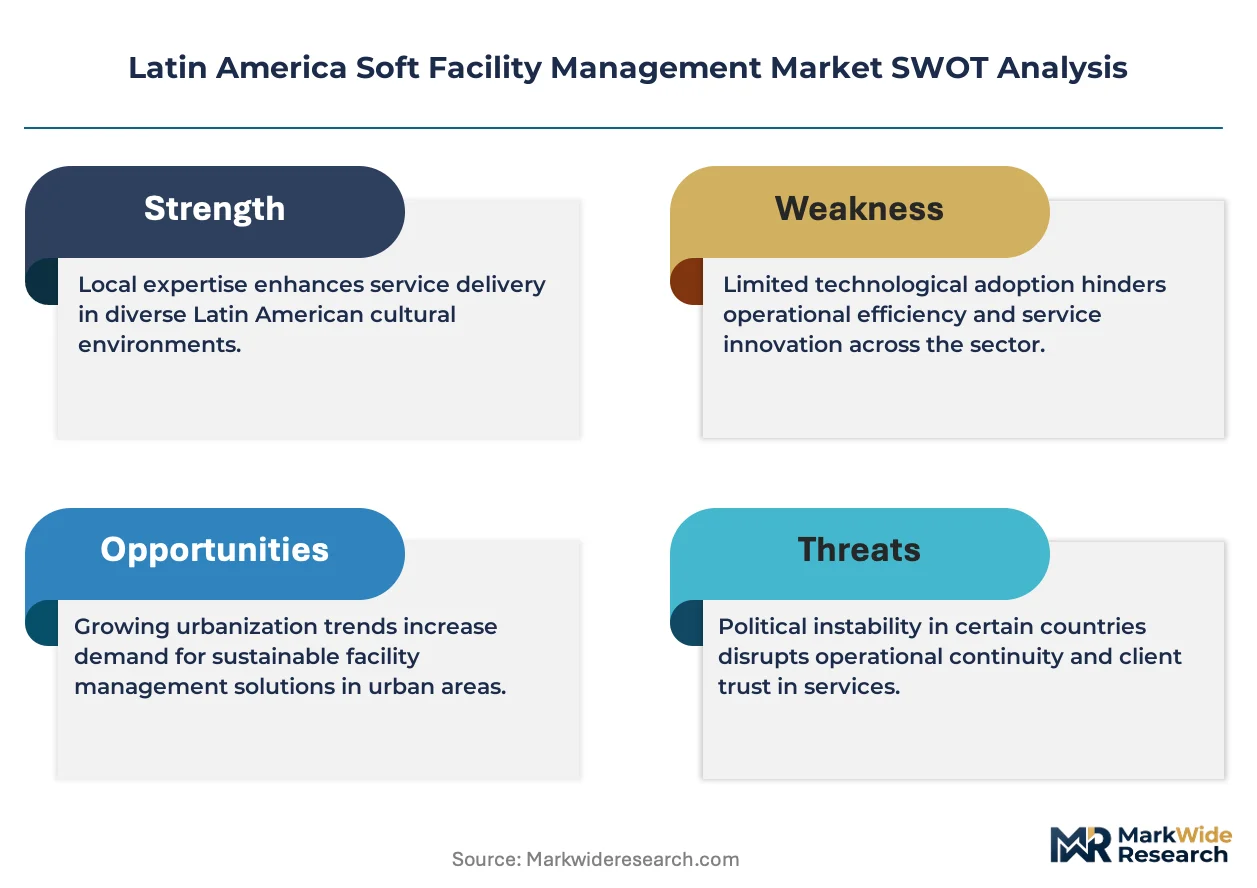
ANVISA sanitation protocols, Mexico's Federal Commission for Protection against Health Risks (COFEPRIS) commercial hygiene standards, and ISO 41001 facility management frameworks collectively shape service specifications and vendor qualification criteria across the region. These regulatory layers elevate compliance costs for smaller operators while creating certification barriers that favor established providers with dedicated quality assurance infrastructure. Stakeholders must monitor how evolving ESG disclosure requirements in Brazil and Mexico will reshape procurement criteria for outsourced facility services, particularly carbon accounting for cleaning supply chains and fair-wage verification for subcontracted janitorial labor.
Market Dynamics
ANVISA sanitation protocols are compressing vendor qualification timelines across Brazilian commercial real estate, forcing facility service providers to restructure quality assurance infrastructure ahead of contract renewals.
Growth Catalysts
- ISO 41001 facility management frameworks:Certification mandates from multinational corporate headquarters are standardizing procurement criteria across São Paulo and Mexico City office complexes.
- IoT-enabled occupancy sensors:Property managers in the São Paulo-Rio de Janeiro corridor deploy real-time janitorial scheduling systems to reduce labor waste and demonstrate cost accountability.
- Healthcare sanitation protocols:Hospital accreditation standards across Brazil and Mexico require specialized cleaning chemistry that commands premium contract values.
Market Restraints
- Biodegradable surfactant cost premiums:Petrochemical-free cleaning chemistry inputs trade at 15-40% above conventional formulations, compressing margins for mid-tier operators.
- Subcontractor wage verification infrastructure:ESG disclosure requirements demand traceable payroll systems that smaller Brazilian providers lack capital to deploy.
- COFEPRIS compliance documentation:Mexico's Federal Commission for Protection against Health Risks imposes extended product registration timelines for imported cleaning agents.
Strategic Opportunities
- Colombian secondary cities:Bogotá and Medellín commercial development lags São Paulo and Mexico City by 7-10 years in outsourced facility management penetration.
- Carbon accounting integration:Brazil's emerging corporate ESG mandates create first-mover advantage for providers with supply chain emissions tracking.
- Catering-security-cleaning bundling:Integrated service platforms reduce procurement friction for corporate campus managers seeking single-vendor accountability.
Industry Challenges
- Janitorial workforce certification pipelines:ANVISA-mandated sanitation training programs face 6-12 month backlogs in Brazilian metropolitan labor markets.
- Legacy CMMS integration:Computerized maintenance management systems from prior decades resist API connectivity with modern IoT sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Soft Facility Management Market |
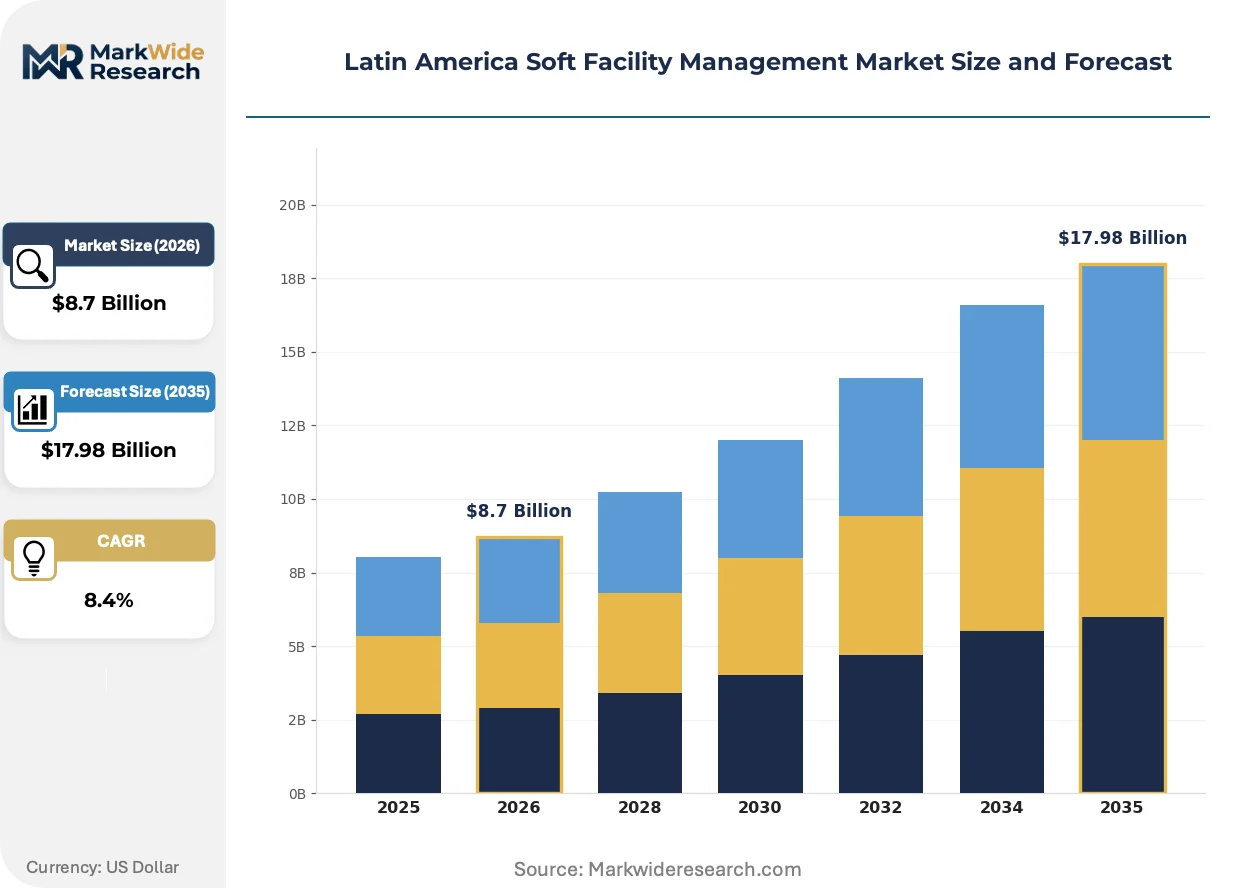
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Landscaping, Maintenance Customer Type: Corporates, Educational Institutions, Healthcare Facilities, Retail Outlets Service Mode: In-House, Third-Party, Hybrid, Outsourced Technology: Smart Building Systems, IoT Solutions, Automation Tools, Facility Management Software |
| Companies Covered | CBRE Group Inc., Cushman & Wakefield plc, Sodexo Inc., Ecolab Inc., ISS A/S, Brasanitas Group, Facility Service SA, Leadec Brazil, Brazil Cleaning Services, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Soft Facility Management Market Shifts & Advancements
Facility management software is capturing procurement influence through subscription analytics platforms that translate sensor data into measurable cost reductions for corporate real estate officers.
Sensor-based performance verification is consolidating vendor accountability across Latin American commercial contracts. Property technology platforms aggregate occupancy data to optimize cleaning crew deployment in real time. Corporate real estate managers in São Paulo and Mexico City now demand dashboard-accessible proof of service completion. This transparency layer is consolidating contract renewals toward technology-enabled providers with demonstrable labor efficiency gains.
ANVISA sanitation protocols are tightening chemical disclosure requirements for commercial cleaning agents sold in Brazil. The regulator now mandates ingredient transparency documentation that exceeds previous voluntary industry standards. Facility service providers must requalify supply chains or risk contract disqualification. Healthcare and food-service verticals face the most immediate compliance deadlines.
Corporate procurement officers now unbundle facility service specifications into discrete performance metrics rather than bundled hourly labor rates. Real estate managers in the São Paulo-Rio de Janeiro corridor negotiate contracts based on measurable outcomes: occupant complaint resolution times, infection prevention audit scores, and energy-adjusted cleaning costs per square meter. This specification shift favors providers with operational data infrastructure over traditional labor brokers.
Latin America Soft Facility Management Market Segmentation
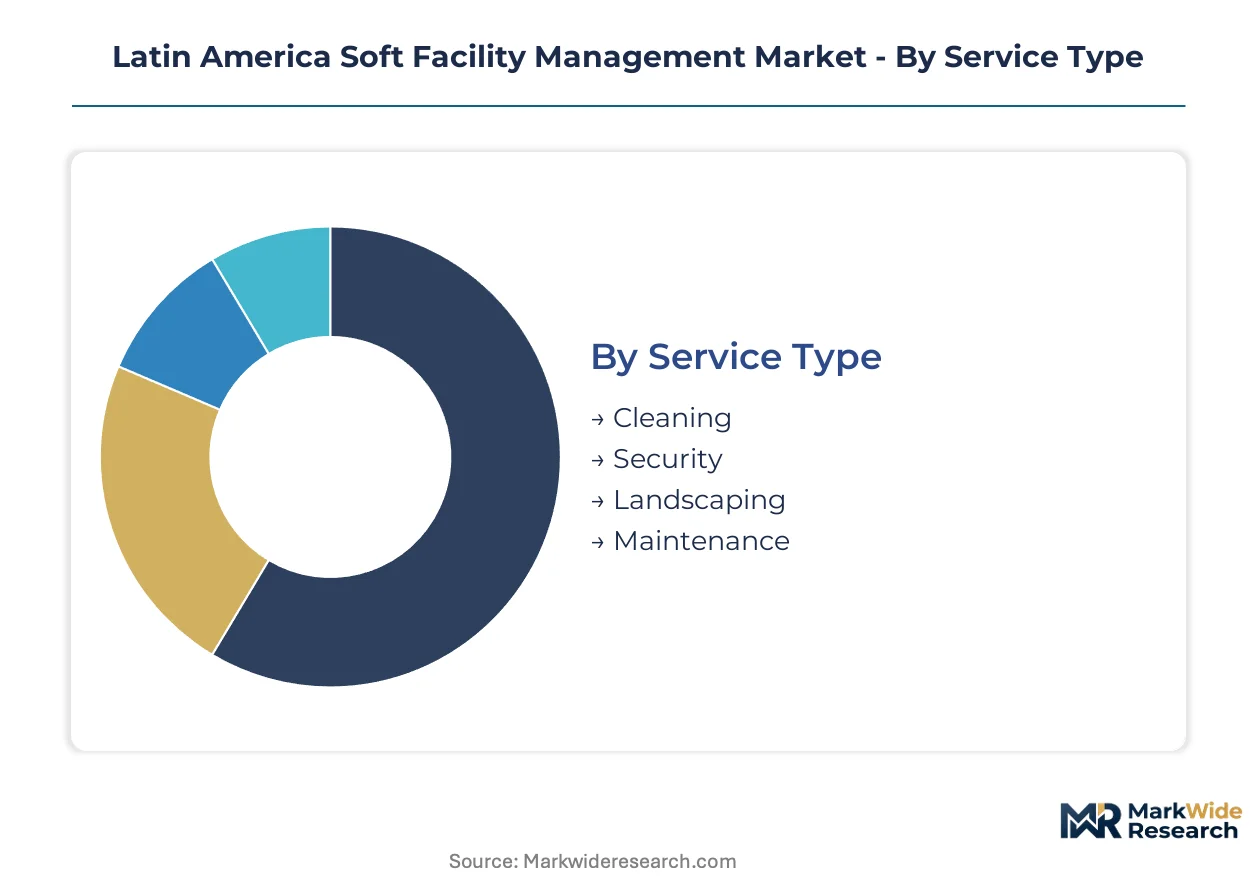
Segmentation in Latin American soft facility management reveals how service bundling, technology adoption, and procurement preferences fragment contract structures across São Paulo-Rio de Janeiro corridor real estate. Each dimension exposes distinct margin profiles and vendor qualification barriers that reshape competitive positioning.
Service Type:
Supply concentration in cleaning chemistry manufacturing drives contract economics across Brazilian and Mexican metropolitan markets.
- Cleaning:Daily labor-intensive workflows dominate contract value through recurring janitorial staffing mandates and ANVISA sanitation protocol compliance. São Paulo corporate campuses concentrate demand as premium commercial real estate development outpaces other Latin American clusters, with biodegradable surfactant premiums compressing mid-tier operator margins.
- Security:Personnel-based guarding services integrate with access control technology on Brazilian corporate campuses. Mexico City financial district towers drive specialized demand for concierge-security hybrid staffing that commands premium hourly rates above standard commercial guarding.
- Landscaping:Exterior grounds maintenance contracts cluster around industrial parks and corporate headquarters in Brazil's southeastern states.
- Maintenance:Routine non-technical upkeep covers HVAC filter replacement, lighting fixture servicing, and minor repairs across commercial portfolios.
Today's leader: Cleaning. Tomorrow's challenger: Security.
Customer Type:
Cost tier differentiation separates procurement specifications between premium-grade healthcare accreditation requirements and standard commercial service levels.
- Corporates:São Paulo-Rio de Janeiro corridor office complexes drive integrated service bundling that combines cleaning with catering and security under single-vendor accountability. ISO 41001 certification mandates from multinational headquarters standardize procurement criteria and elevate compliance documentation requirements.
- Healthcare Facilities:Hospital accreditation standards across Brazil and Mexico demand specialized sanitation chemistry with ingredient transparency documentation exceeding voluntary industry norms. ANVISA-mandated training backlogs create 6-12 month workforce certification pipelines that constrain vendor capacity.
- Educational Institutions:University campuses and K-12 facilities in Colombian secondary cities represent underpenetrated contract opportunities.
- Retail Outlets:Shopping mall operators prioritize flexible staffing models that scale with foot traffic fluctuations.
Today's leader: Corporates. Tomorrow's challenger: Healthcare Facilities.
Service Mode:
Volume concentration in outsourced contracts reflects procurement officers' preference for outcome-based performance metrics over hourly labor rate negotiations.
- Outsourced:Third-party facility service providers capture procurement influence through subscription analytics platforms demonstrating measurable cost reductions. São Paulo property managers demand dashboard-accessible proof of service completion, consolidating renewals toward technology-enabled vendors.
- Third-Party:Specialized healthcare and food-service verticals require dedicated quality assurance infrastructure that smaller Brazilian providers lack capital to deploy.
- In-House:Legacy corporate real estate portfolios maintain direct janitorial employment in select Mexican industrial facilities.
- Hybrid:Mixed staffing models combine internal supervision with contracted labor for non-core functions.
Today's leader: Outsourced. Tomorrow's challenger: Third-Party.
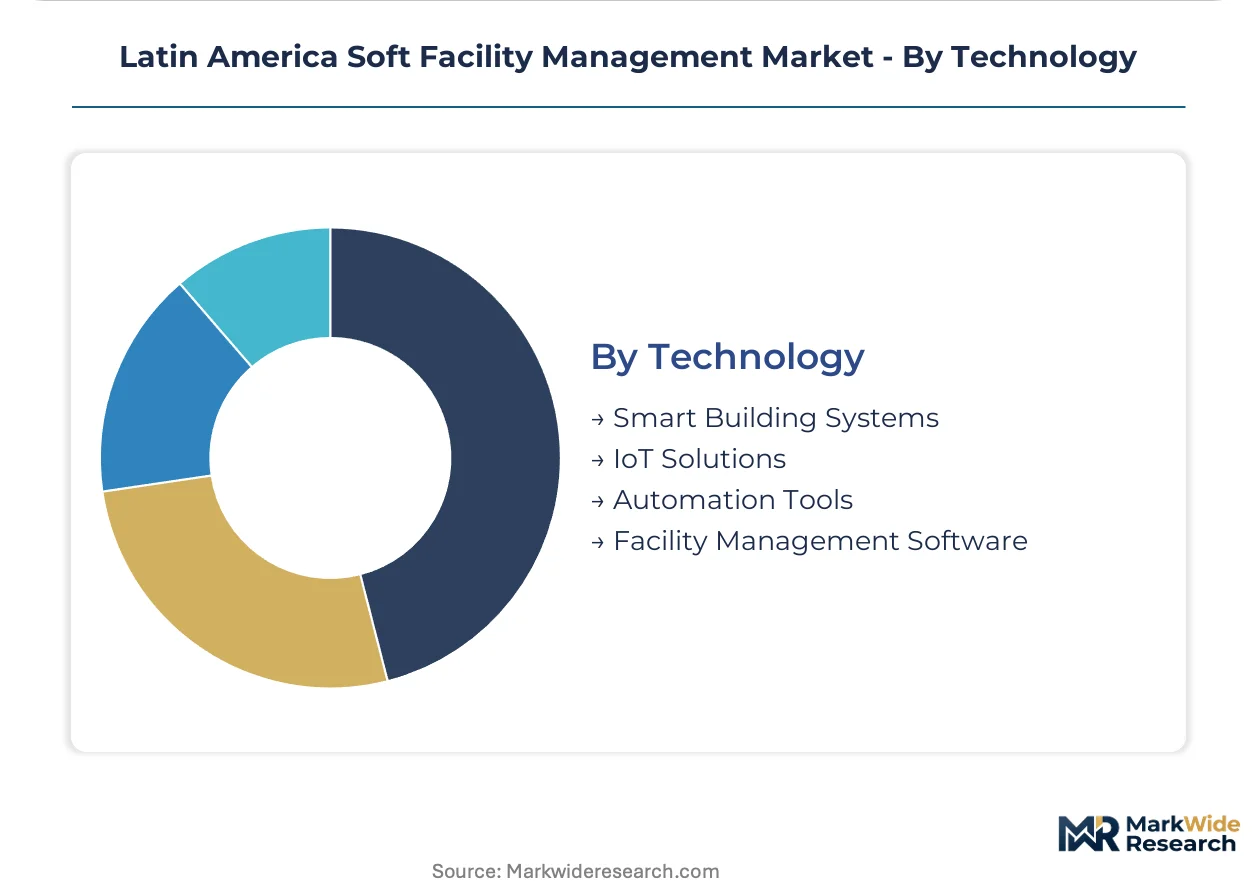
Technology:
Margin capture concentrates in software subscriptions that translate sensor data into procurement-verifiable labor efficiency gains.
- Facility Management Software:Analytics platforms aggregate occupancy data to optimize cleaning crew deployment in real time. Corporate real estate managers negotiate contracts based on measurable outcomes including infection prevention audit scores and energy-adjusted cleaning costs per square meter.
- IoT Solutions:Sensor-based performance verification consolidates vendor accountability through real-time janitorial scheduling systems that reduce labor waste. Property technology platforms in São Paulo and Mexico City now require API connectivity with modern sensor networks.
- Smart Building Systems:Integrated environmental controls expand fastest as property managers deploy occupancy-driven automation.
- Automation Tools:Robotic cleaning equipment penetrates large-format retail and airport terminal contracts.
Today's leader: Facility Management Software. Tomorrow's challenger: IoT Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The São Paulo-Rio de Janeiro corridor anchors Latin American soft facility management demand through premium commercial real estate development outpacing other metropolitan clusters. Corporate office complexes across this corridor are expanding integrated service contracts for cleaning and security operations. ANVISA sanitation protocols are tightening compliance requirements for facility service providers throughout Brazilian commercial spaces.
Brazil
São Paulo corporate campuses concentrate demand for bundled cleaning, catering, and security services under single-vendor contracts. ANVISA sanitation protocols mandate ingredient transparency documentation for commercial cleaning agents that exceeds previous voluntary industry standards. The São Paulo-Rio de Janeiro corridor drives premium contract values as property managers deploy IoT-enabled occupancy sensors for real-time janitorial scheduling.
Mexico
Mexico City financial district towers generate specialized demand for concierge-security hybrid staffing commanding premium hourly rates. COFEPRIS commercial hygiene standards impose extended product registration timelines for imported cleaning agents. Corporate procurement officers in Mexico City negotiate outcome-based contracts using measurable metrics rather than bundled hourly labor rates.
Colombia
Bogotá and Medellín commercial development lags São Paulo and Mexico City by 7-10 years in outsourced facility management penetration. University campuses and K-12 facilities represent underpenetrated contract opportunities for integrated service providers. Colombian secondary cities are attracting regional facility service providers seeking expansion beyond saturated Brazilian and Mexican markets.
Chile
Santiago corporate real estate managers are adopting ISO 41001 facility management frameworks following certification mandates from multinational headquarters. Mining and industrial facility operators in northern Chile require specialized maintenance contracts combining routine upkeep with security services. The Santiago metropolitan area is consolidating procurement toward technology-enabled providers with demonstrable labor efficiency gains.
Argentina
Buenos Aires commercial property managers face cost pressures that favor flexible staffing models scaling with occupancy fluctuations. Federal hygiene regulations for commercial spaces are elevating documentation requirements for facility service contracts. The Buenos Aires metropolitan corridor maintains significant in-house facility staffing despite regional trends toward outsourcing.
Latin America Soft Facility Management Market Competitive Landscape
Global majors compete with regional champions across integrated service platforms and technology-enabled oversight capabilities. The market structures around three tiers: multinational providers with subscription analytics platforms, mid-tier operators with specialized vertical expertise, and local labor brokers competing on cost. Strategic archetypes include integrated service bundlers, healthcare sanitation specialists, and property technology enablers. Dominant competitive moves encompass M&A for geographic expansion and strategic partnerships for IoT sensor network deployment.
Within the integrated service tier, Sodexo Inc. and CBRE Group Inc. exemplify contrasting approaches to Latin American market development. Sodexo leverages bundled catering-security-cleaning platforms to reduce procurement friction for corporate campus managers seeking single-vendor accountability. CBRE anchors its regional position through technology-enabled facility oversight with dashboard-accessible proof of service completion. ISS A/S occupies a specialized position via healthcare sanitation protocols that meet stringent hospital accreditation standards across Brazil and Mexico.
| Leading Market Players |
|---|
| CBRE Group Inc. |
| Cushman & Wakefield plc |
| Sodexo Inc. |
| Ecolab Inc. |
| ISS A/S |
| Brasanitas Group |
| Facility Service SA |
| Leadec Brazil |
| Brazil Cleaning Services |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up facility service specialists dominate Brazil's southeastern corridor, concentrating pricing power among consolidated operators while compressing margins for fragmented labor brokers competing on hourly rates. Their capital discipline shapes supply behavior through long-term chemical procurement contracts and captive training infrastructure that smaller rivals cannot replicate.
Pricing Analysis
Input-cost pass-through from biodegradable surfactant premiums flows unevenly across service tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 41001-certified providers from uncertified labor brokers, with certification grade and volume scale driving differentiation. Pricing pressure stems from ANVISA-mandated chemical disclosure requirements that force supply chain requalification. Corporate campus managers in São Paulo show least price sensitivity, while retail mall operators in Colombian secondary cities resist premium tier migration.
Supply Chain Analysis
Freight costs from cleaning chemistry manufacturing centers in Brazil, Mexico, and Argentina shape regional contract economics through diesel price exposure and last-mile labor logistics. Supply draws from petrochemical feedstocks, imported enzyme formulations, and locally compounded surfactant blends. Single-source vulnerability concentrates in specialized healthcare sanitation inputs subject to COFEPRIS registration delays. Distribution runs through integrated service platforms that bundle procurement with technology-enabled performance verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as corporate procurement officers shift specifications toward outcome-based metrics and ANVISA-compliant chemical transparency, favoring providers with demonstrable compliance infrastructure over cost-driven labor brokers.
For Market Incumbents: Acquire IoT sensor network capabilities to anchor technology-enabled contract renewals in the São Paulo-Rio de Janeiro corridor. Consolidate mid-tier operators in Colombian secondary cities before regional champions establish scale. Threat substitution from property technology platforms demands API-ready workforce management systems as a defensive lever. For New Entrants and Emerging Players: Colombian university campuses and K-12 facilities represent underserved buyer archetypes with minimal outsourced facility management penetration. Healthcare sanitation specialization offers the most penetrable vertical given ANVISA-mandated training backlogs that constrain incumbent capacity. Lead with carbon accounting integration to capture Brazil's emerging ESG procurement mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among family-owned Brazilian labor brokers lacking ANVISA compliance documentation infrastructure. Long-term viability hinges on regulatory certification moats widening through successive protocol tightening. Watch for ISO 41001 certification mandates spreading from multinational headquarters to domestic corporate procurement criteria as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Integration | API connectivity with IoT sensor networks consolidates contract renewals toward data-verified providers in São Paulo. |
| Healthcare Sanitation Specialization | ANVISA-mandated chemical transparency documentation creates certification barriers that protect premium contract values. |
| Geographic Expansion to Colombia | Bogotá and Medellín commercial development lag offers first-mover positioning before market saturation. |
| Backward Integration into Training | Captive workforce certification pipelines resolve ANVISA-mandated sanitation program backlogs constraining rival capacity. |
| Carbon Accounting Capability Buildout | Brazil's corporate ESG disclosure requirements create procurement preference for supply chain emissions tracking. |
Research Methodology
Direct dialogue with facility service procurement officers, corporate real estate managers, ANVISA compliance consultants, and cleaning chemistry supply directors grounded qualitative findings in operational reality. Secondary validation drew from ANVISA regulatory filings, COFEPRIS product registration databases, ISO certification registries, and commercial real estate development permits. Bottom-up contract value estimates triangulated against top-down market sizing from regional facility management association reports.
Segment-level outputs across service type, customer vertical, delivery mode, and technology adoption were generated through the projection horizon. CAGRs derived from regression analysis of contract renewal rates, pricing trend trajectories, and regulatory implementation timelines. Forecast inputs incorporated IoT sensor deployment curves, ANVISA inspector staffing expansion plans, and multinational corporate ISO 41001 rollout schedules.
Inputs from regulatory filing databases and commercial real estate transaction records were available through the study window; gaps in subcontractor wage verification system penetration introduce uncertainty bands around ESG compliance cost estimates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Lithuania Facility Management Market
Facility Management
Australia Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
United Kingdom (UK) Facility Management Market
Facility Management
Finland Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Cold Storage Warehouse Market
Facility Management
Austria Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
Refrigerated Warehousing Market
Facility Management
Romania Facility Management Market
Facility Management
India Integrated Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Saudi Arabia Facility Management Market
Facility Management
Europe Soft Facility Management Market