
 Paper Cones Market | 2026-2036
Paper Cones Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Cones Market Analytics
Indian specialty paperboard producers is realigning capacity toward cone-grade kraft as domestic textile mills expand yarn output. Conitex Sonoco leverages its integrated fiber-to-cone operations across Latin American markets. Sonoco Products Company anchors North American supply through dedicated converting lines for industrial yarn carriers. Smurfit Kappa Group extends its recycled paper expertise into cone applications for European spinning houses.
Paper cones are rigid, tapered cylinders manufactured from kraft or recycled paperboard, typically featuring a specified wall thickness and internal diameter calibrated to match textile spindles or food service dispensing equipment. These structures serve primarily as yarn carriers in textile manufacturing and as disposable containment vessels in food service applications. Kraft paper dominates industrial yarn cone production due to its burst strength and moisture resistance, while recycled paper grades gain share in food service display cones as ESG procurement criteria tighten. Food service chains represent the fastest-growing end user segment, driven by ice cream and snack dispensing formats in quick-service restaurant expansion.
India's BIS certifies dimensional tolerances for textile cones used in export-oriented spinning mills, while the EU REACH framework governs chemical treatments in coated food-contact variants. The US FDA regulates paper cone materials intended for direct food contact under 21 CFR standards. Stakeholders must monitor how divergent recyclability mandates across these jurisdictions reshape material specifications and sourcing strategies.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing cone manufacturers to reconfigure fiber sourcing toward post-consumer recycled content, compressing margins for virgin kraft-dependent mills while creating entry points for integrated recyclers.
Growth Catalysts
- REACH chemical compliance:European spinning houses now mandate coated food-contact cones meet ECHA substance restrictions, pulling certified converters into premium supply tiers.
- Tamil Nadu cluster expansion:Integrated spinning mills in South India's textile belt are scaling domestic cone procurement as yarn export volumes rise.
- Quick-service restaurant formats:Ice cream and snack dispensing chains are adopting paper cones as disposable containment standardizes across franchise rollouts.
Market Restraints
- Pulp cost volatility:Unbleached kraft fiber prices fluctuate with Nordic softwood supply disruptions, squeezing converter margins unpredictably.
- Recycled fiber availability:Post-consumer paperboard collection rates in Eastern Europe lag Western EU targets, constraining PPWR-compliant raw material access.
- Plastic cone substitution:Polypropylene yarn carriers persist in high-speed spinning applications where moisture resistance exceeds paperboard performance thresholds.
Strategic Opportunities
- Bangladesh textile ascent:Export-oriented spinning capacity in Dhaka-Chittagong corridor lacks domestic cone supply, creating import substitution openings for regional producers.
- EU Green Deal procurement:Public sector food service contracts now embed recycled content minimums, advantaging certified cone suppliers in institutional bidding.
- Digital printing integration:Direct-to-cone branding technology enables batch-size-one customization for boutique ice cream and specialty coffee chains.
Industry Challenges
- Dimensional certification timelines:India's BIS tolerance testing for export-grade textile cones extends qualification cycles for new supplier entry.
- Legacy equipment retrofit costs:Converting lines designed for virgin kraft require capital modification to handle variable recycled fiber grammages without quality drift.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Cones Market |
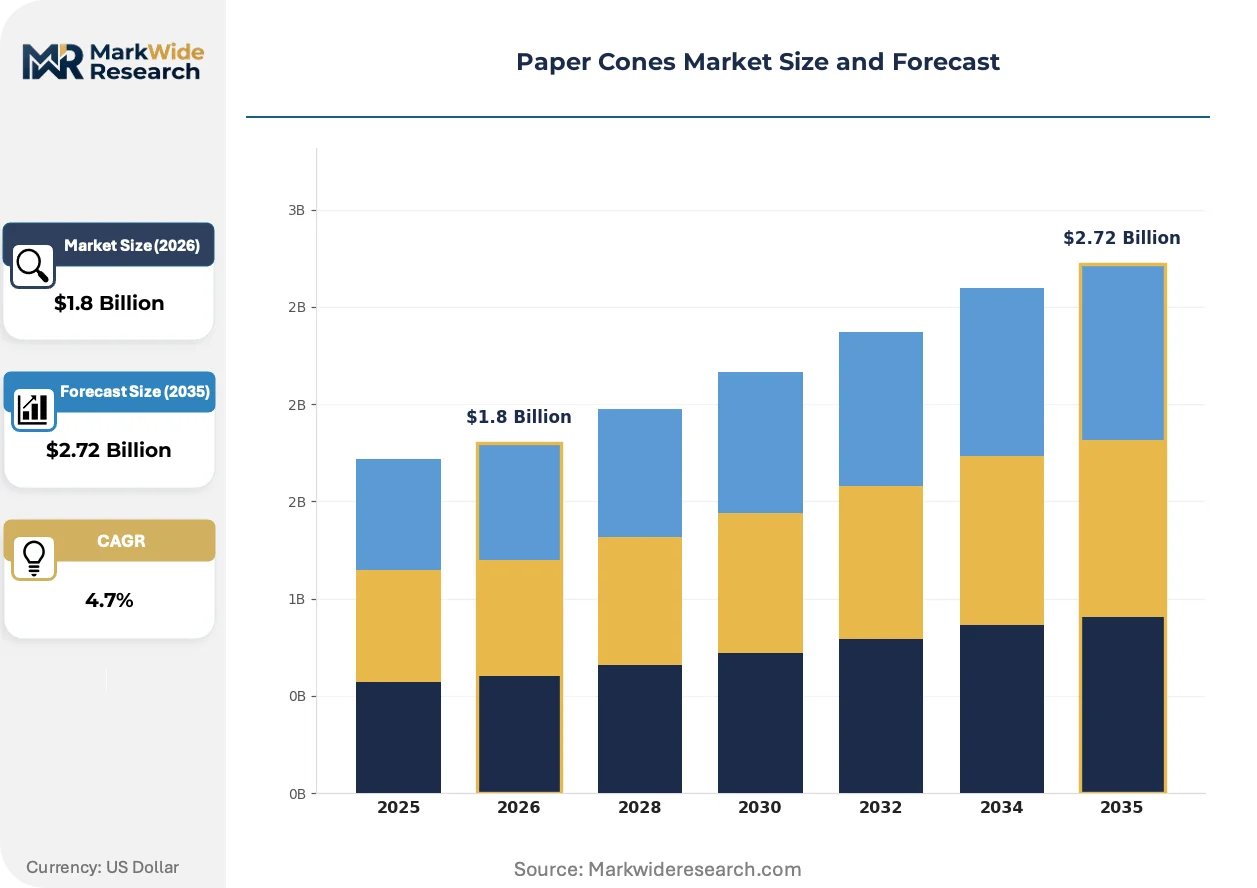
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream Cones, Packing Cones, Display Cones, Food Cones Material: Recycled Paper, Virgin Paper, Coated Paper, Kraft Paper End User: Food Service Chains, Retail Stores, Food Manufacturers, Event Organizers Distribution Channel: Online Retail, Supermarkets, Wholesalers, Specialty Stores |
| Companies Covered | Conitex Sonoco, Sonoco Products Company, SKS Paper Products, Pacific Paper Products, Hilmarton, Shree Umiya Paper Cone, Smurfit Kappa Group, Mondi Group, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Cones Market Evolving Landscape
Active reshaping in paper cones stems from three vectors: production technology adaptation to fiber variability, regulatory chemistry constraints on food-contact surfaces, and procurement consolidation among multinational quick-service chains.
Water-based barrier coatings are modularizing cone manufacturing by enabling on-machine application of moisture-resistant layers without separate lamination stages. Food service converters in North America are adopting these systems to compress lead times for seasonal promotional runs. The technology is modularizing supply chains by allowing regional converters to serve national chains without centralized coating capacity.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant treatments from European food-contact cones. Industrial consequence includes accelerated R&D spending on cellulose-based barrier alternatives and silicone-modified coatings. Quick-service restaurant procurement teams in Germany and France are now requiring substance declarations upstream of contract awards.
Consolidated buying by multinational food service chains is compressing supplier rosters and lengthening contract durations. Regional cone converters face displacement by vertically integrated packaging houses capable of pan-European logistics and centralized quality auditing. This concentration is most visible in the Benelux region, where distribution hubs serve cross-border franchise networks.
Paper Cones Market Segmentation
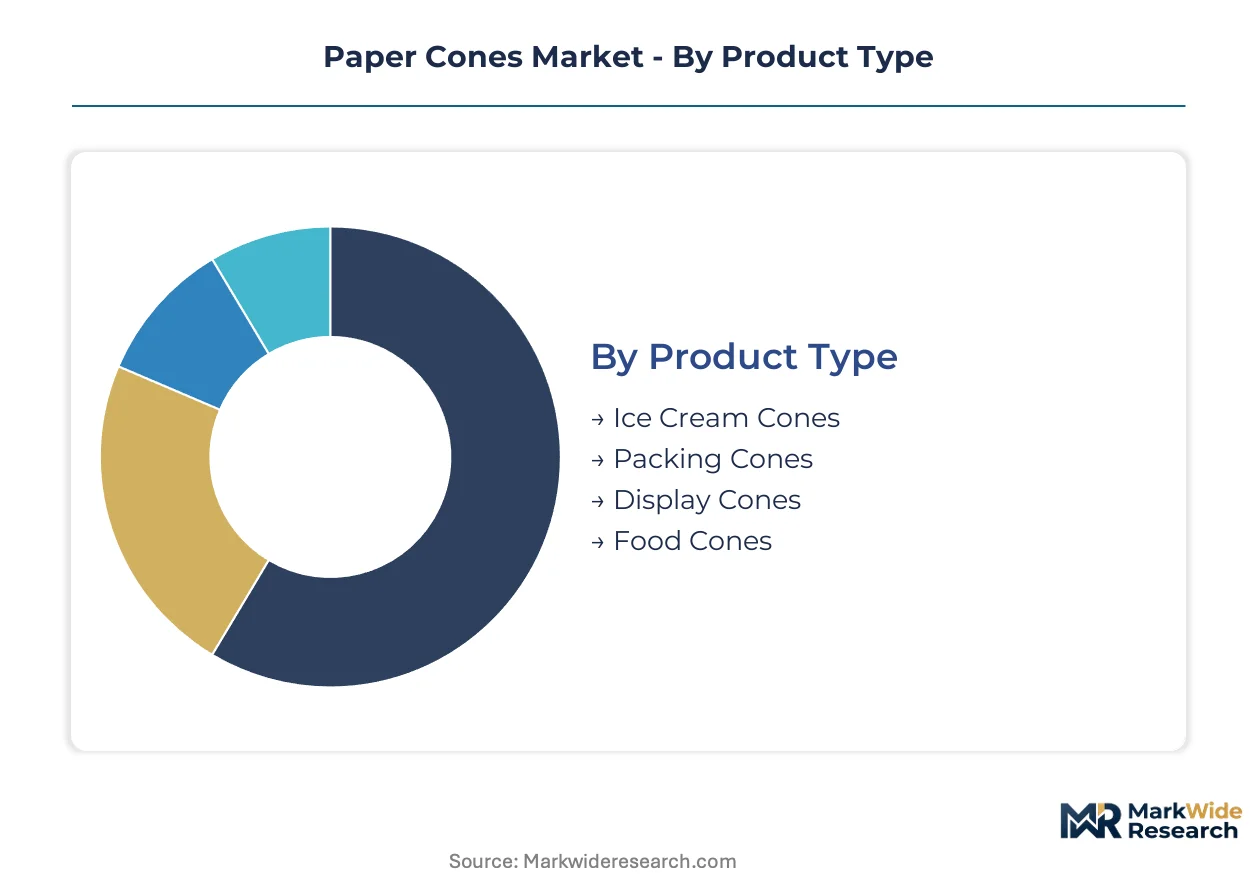
Paper cone procurement splits sharply between industrial yarn carriers demanding dimensional precision and food service disposables prioritizing barrier performance. Material certification requirements and end-use durability thresholds create distinct specification tiers that reshape supplier positioning across each segment boundary.
Product Type:
Buyers prioritize functional durability against moisture exposure and structural load requirements when selecting cone formats.
- Ice Cream Cones:Rolled wafer structures with moisture-resistant barrier coatings prevent sogginess during frozen dessert dispensing. Quick-service restaurant chains in North America and Western Europe specify these for franchise-standardized serving formats.
- Packing Cones:Rigid kraft cylinders engineered to textile spindle tolerances carry yarn through high-speed winding operations. Tamil Nadu spinning mills source these domestically as export-oriented yarn production scales.
- Display Cones:Lightweight paperboard shells with printed branding surfaces serve snack presentation in retail environments.
- Food Cones:Grease-resistant treated paperboard contains hot or oily finger foods at stadium and festival venues.
Packing cones lead on scale; ice cream cones lead on momentum.
Material:
Fiber sourcing decisions hinge on regulatory compliance thresholds and end-use moisture resistance requirements.
- Kraft Paper:Unbleached sulfate pulp delivers burst strength and dimensional stability for industrial textile applications. Nordic softwood supply disruptions periodically constrain availability for cone-grade specifications.
- Recycled Paper:Post-consumer fiber content satisfies EU Packaging and Packaging Waste Regulation mandates for food service procurement. Collection rate gaps in Eastern Europe limit compliant supply access.
- Virgin Paper:Controlled fiber length and cleanliness suit medical and premium food-contact applications requiring batch consistency.
- Coated Paper:Extruded or aqueous barrier layers extend moisture resistance for frozen dessert and hot food containment.
Kraft paper dominates industrial volume; recycled grades are climbing the fastest on regulatory pull.
End User:
Volume concentration and contract duration vary sharply across buyer categories with differing procurement centralization.
- Food Service Chains:Multinational quick-service operators consolidate supplier rosters through pan-regional contracts with centralized quality auditing. These buyers mandate REACH-compliant coatings and recycled content minimums in EU tenders.
- Food Manufacturers:Packaged goods producers specify custom-printed cones for seasonal promotional SKUs with shorter lead time requirements.
- Retail Stores:Supermarket private label programs source display cones through regional converters with flexible batch sizing.
- Event Organizers:Stadium and festival operators purchase food cones on spot contracts with limited specification stringency.
Food service chains anchor contract value; food manufacturers show steepest expansion trajectory on promotional format proliferation.
Distribution Channel:
Channel selection reflects order fragmentation tolerance and logistics infrastructure requirements.
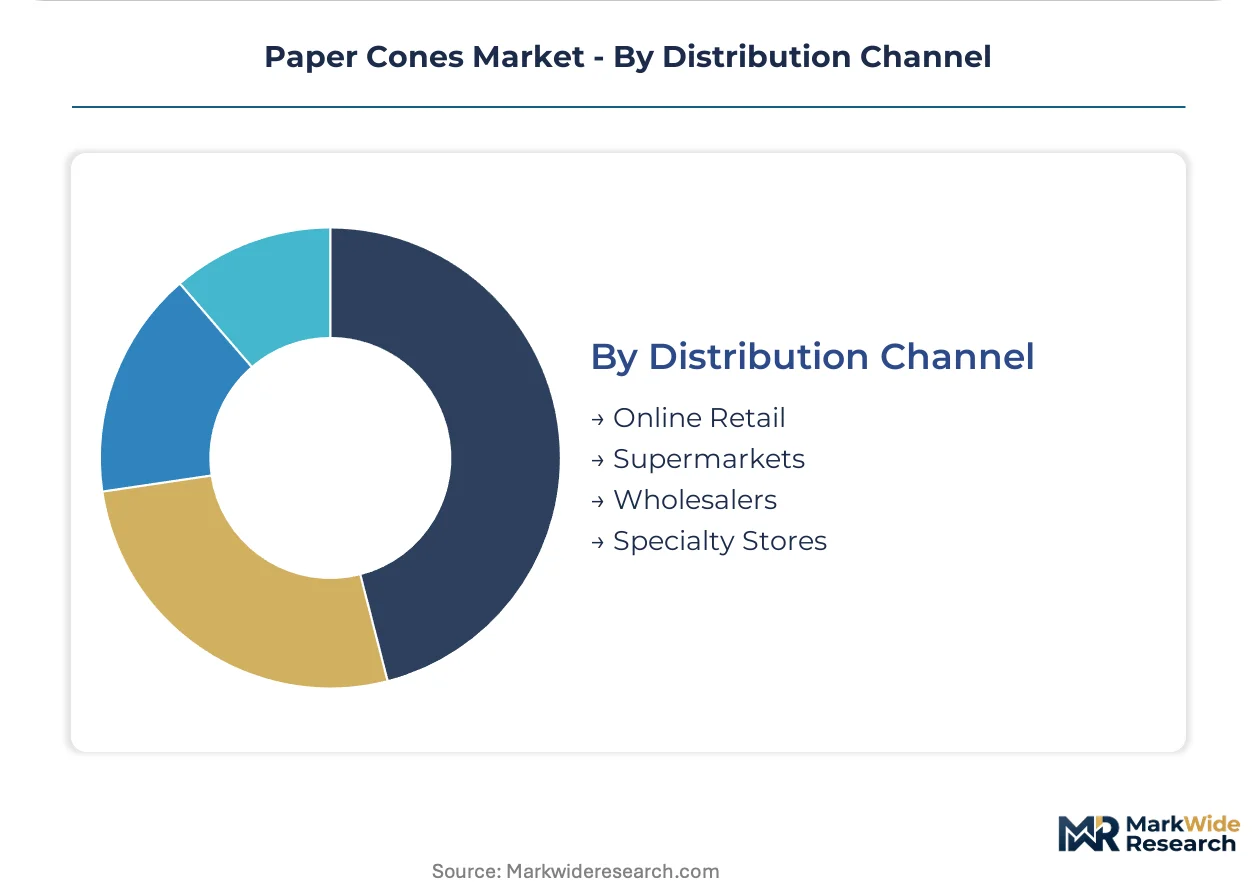
- Wholesalers:Bulk pallet distribution serves textile mills and large food manufacturers with predictable replenishment cycles. These intermediaries stock standard cone dimensions for immediate availability.
- Online Retail:E-commerce platforms enable small-batch procurement for boutique ice cream chains and event operators requiring customized branding. Digital channels gain share as direct-to-cone printing technology reduces minimum order thresholds.
- Supermarkets:Mass retail distribution moves consumer-packed display cones for home entertaining and party supply segments.
- Specialty Stores:Restaurant supply depots and packaging distributors serve independent food service operators with mixed-product orders.
Wholesalers retain volume leadership; online retail is gaining share fastest on customization demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting paper cone production toward jurisdictions with lower compliance costs for virgin kraft sourcing, even as EU recycled-content mandates reshape procurement patterns for food-contact grades.
India
Tamil Nadu's textile belt drives industrial cone consumption as spinning mills scale yarn exports to Bangladesh and Vietnam. BIS dimensional tolerance certifications for export-grade cones extend supplier qualification timelines. Coimbatore and Tiruppur clusters source domestically, reducing import dependence for high-speed winding operations.
Germany
REACH Annex XVII restrictions on PFAS grease-resistant coatings are eliminating legacy treatments from food-contact cone production. ECHA substance declarations now precede quick-service restaurant contract awards. The Benelux distribution hub serves cross-border franchise networks with centralized quality auditing.
United States
FDA 21 CFR standards govern direct food-contact paper cone materials for ice cream and snack dispensing chains. Water-based barrier coating adoption compresses lead times for seasonal promotional runs. Regional converters in the Midwest serve national quick-service operators without centralized lamination capacity.
China
MIIT industrial standards for packaging materials influence cone specifications for textile machinery exports. Yangtze River Delta converters supply both domestic spinning mills and Southeast Asian yarn producers. Dual carbon goals are pressuring mills toward recycled fiber integration in food service grades.
Brazil
ANVISA food-contact regulations shape barrier coating requirements for quick-service restaurant cone imports. São Paulo state packaging converters serve Mercosur textile markets with kraft-grade yarn carriers. Domestic spinning capacity expansion in Minas Gerais is pulling regional cone procurement northward.
Paper Cones Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital printing integration and recycled fiber specialization. The vendor base spans integrated paperboard mills, dedicated cone converters, and diversified packaging houses with cone-adjacent capacity. Three archetypes dominate: fiber-integrated multinationals with captive pulp supply, regional specialists serving textile clusters, and food service-focused converters with barrier coating expertise. Capacity modification for variable recycled fiber grammages and pan-regional logistics contracts constitute the primary competitive moves.
Among fiber-integrated multinationals, Smurfit Kappa Group and Mondi Group exemplify the archetype of recycled paperboard expertise extending into cone applications. Sonoco Products Company occupies a position representing North American supply anchoring through dedicated industrial yarn carrier lines. These three sit within distinct geographic and capability tiers rather than direct overlap.
| Leading Market Players |
|---|
| Conitex Sonoco |
| Sonoco Products Company |
| SKS Paper Products |
| Pacific Paper Products |
| Hilmarton |
| Shree Umiya Paper Cone |
| Smurfit Kappa Group |
| Mondi Group |
| International Paper Company |
| Others |
Value Network & Pricing Analysis
EU Packaging and Packaging Waste Regulation compliance gates qualified supply access and premium-tier pricing power for converters serving institutional food service contracts. Recycled fiber certification tiers separate compliant suppliers from virgin kraft-dependent mills facing margin compression.
Pricing Analysis
Distributor margins absorb logistics complexity for regional converters serving pan-European quick-service restaurant networks. Three-tier pricing structure across premium REACH-certified, standard BIS-compliant, and economy non-certified levels reflects certification investment and fiber sourcing costs. Pricing pressure stems from Nordic softwood pulp volatility squeezing kraft-grade cone margins. Food service chains show lowest price sensitivity due to contract consolidation and ESG procurement mandates, while event operators and independent retailers drive spot-market competition.
Supply Chain Analysis
Freight costs from Nordic pulp ports to South Asian converting clusters determine landed cost competitiveness for Tamil Nadu textile mills. Raw material sourcing draws from Swedish and Finnish softwood pulp, Indian domestic kraft paperboard, and post-consumer fiber collection networks in Western Europe. Single-source vulnerability concentrates in Nordic unbleached kraft supply for industrial yarn carrier specifications. Distribution runs through wholesale pallet networks for textile mills and direct-to-chain contracts for multinational food service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory compliance costs exceed South Asian production economics by a structural margin that widens with each REACH chemical restriction expansion.
For Market Incumbents: Lock in backward integration into post-consumer fiber collection networks to secure PPWR-compliant raw material access before Eastern European collection infrastructure matures. Defend position by retrofitting legacy converting lines for variable recycled fiber grammages, eliminating quality drift that emerging entrants exploit. Prioritize certification investment in BIS dimensional tolerance testing to extend qualification timelines for new supplier entry. For New Entrants and Emerging Players: Launch via online retail channels enabling batch-size-one customization for boutique ice cream and specialty coffee chains with direct-to-cone digital printing technology. Target Bangladesh's Dhaka-Chittagong corridor where export-oriented spinning capacity lacks domestic cone supply, creating import substitution openings. Penetrate through barrier coating specialization for grease-resistant food-contact applications where REACH Annex XVII restrictions eliminate legacy suppliers. For Investors and Strategic Acquirers: Roll-up economics work for regional cone converters with food service barrier coating expertise because multinational quick-service chain procurement consolidation compresses supplier rosters and extends contract durations. Long-term viability centers on pan-European logistics capability and centralized quality auditing infrastructure. Watch ECHA substance declaration requirements as the inflection indicator for premium-tier pricing expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Secures PPWR-compliant raw material access ahead of Eastern European collection rate improvements. |
| Digital Printing Technology Deployment | Enables batch-size-one customization for boutique ice cream chains reducing minimum order thresholds. |
| REACH-Compliant Barrier Coating R&D | Replaces eliminated PFAS treatments with cellulose-based alternatives for European food-contact contracts. |
| Pan-European Logistics Network Buildout | Serves cross-border franchise networks through centralized quality auditing and distribution hubs. |
| BIS Certification Investment | Extends supplier qualification timelines for Tamil Nadu export-grade textile cone procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with textile mill procurement managers, food service chain packaging directors, cone converting plant engineers, and barrier coating R&D specialists with secondary validation. Secondary sources included customs and trade data for pulp and paperboard flows, BIS certification registries, ECHA substance restriction databases, and SEC filings from integrated packaging houses. Bottom-up demand modeling across yarn carrier and food service segments triangulated against top-down macroeconomic drivers.
Historical reference periods anchored the projection horizon to observed fiber cost cycles, regulatory implementation timelines, and textile capacity expansion patterns. Segmentation dimensions modeled included product type, material grade, end-user category, and distribution channel complexity. CAGRs derived from volume-weighted growth rates across these segments incorporated Nordic softwood supply elasticity, EU recycled content mandate phase-ins, and quick-service restaurant format proliferation as core inputs.
Several conditions sit outside the modeled scope, including unannounced trade policy shifts affecting pulp imports, breakthrough barrier coating technologies eliminating current material constraints, and spinning mill automation reducing per-unit cone consumption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
Kitchen Roll Market
Paper & Paperboard Packaging
Global Window Cake Box Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Corrugated Shippers Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Paper Edge Protectors Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Anti-Slip Coated Paper Market
Paper & Paperboard Packaging
Corrugated Mailers Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Food Contact Paper and Board Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Paper Canisters Market