
 Kinase Inhibitor in Autoimmune Diseases Market | 2026-2036
Kinase Inhibitor in Autoimmune Diseases Market Size, Share, and Industry Trends Forecast 2026-2036
Kinase Inhibitor in Autoimmune Diseases Market Foresight
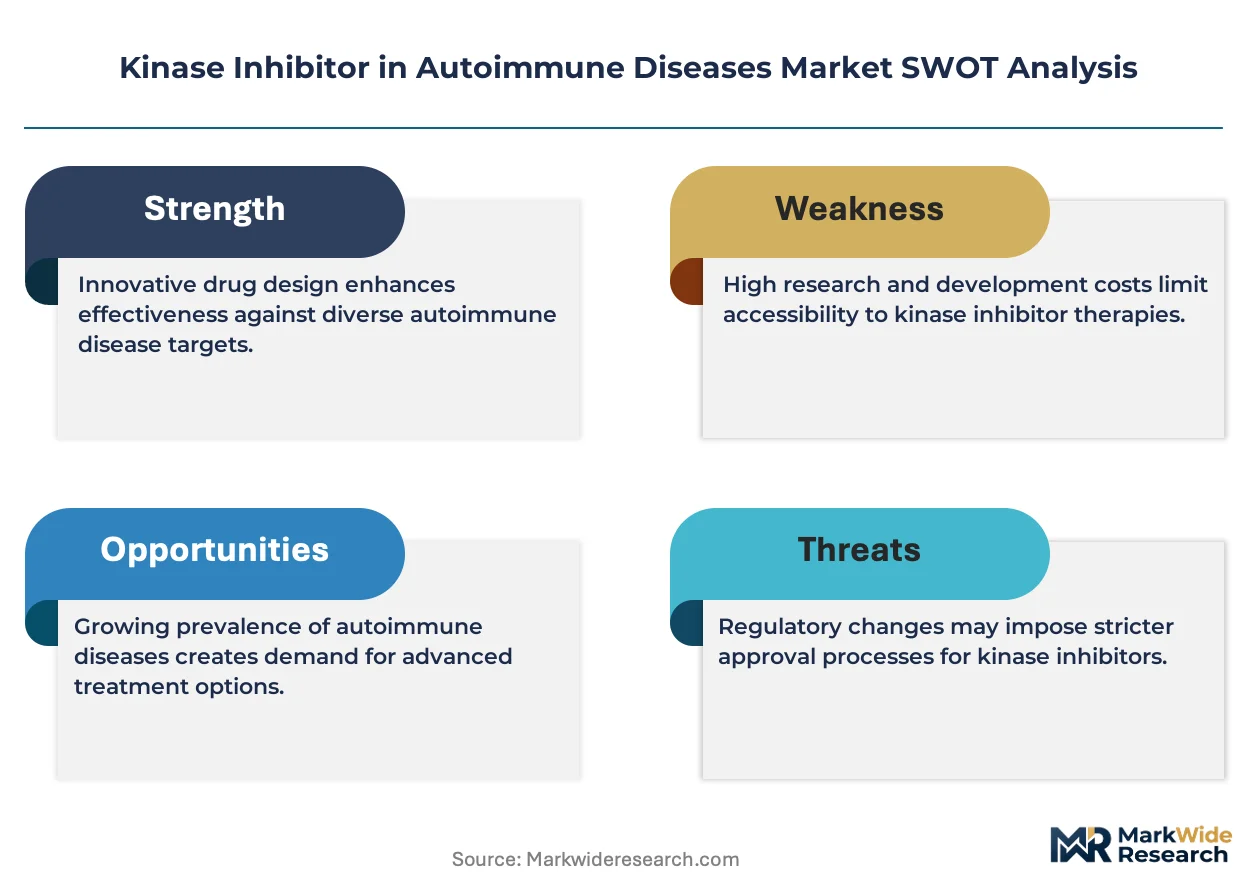
Next-generation kinase selectivity profiling is fragmenting traditional development pipelines into precision-targeted and broad-spectrum camps. Pfizer leverages its established inflammation franchise to sustain manufacturing scale across oral and injectable formats. AbbVie anchors its immunology portfolio through deep clinical investment in JAK and BTK pathways. Incyte Corporation competes by concentrating on selective inhibition profiles that differentiate safety databases.
Kinase inhibitors in autoimmune diseases constitute small-molecule therapeutics that modulate intracellular signaling cascades by blocking ATP-binding sites on specific kinase enzymes, typically achieving IC50 values in the nanomolar range against targets such as JAK1, JAK3, SYK, or BTK. These agents interrupt cytokine-mediated inflammation and serve primarily as alternatives or successors to biologic disease-modifying antirheumatic drugs. Janus kinase inhibitors occupy the largest revenue pool due to entrenched formulary positioning across rheumatoid arthritis and psoriasis. SYK inhibitors represent the fastest-evolving segment as clinicians seek options with distinct mechanistic profiles for refractory lupus and inflammatory bowel disease. Oral delivery mode commands disproportionate margin attention because patient preference and pharmacy benefit structures favor self-administered tablets over infusion center dependence.
FDA, EMA, and Japan's PMDA collectively govern approval pathways, with each agency tightening cardiovascular and thromboembolic surveillance requirements that reshape clinical trial designs and post-market commitments. The EU AI Act and GDPR additionally constrain real-world evidence collection strategies that sponsors use to support label expansion. Stakeholders must monitor evolving regulatory divergence on long-term safety databases as these standards determine which kinase programs secure priority review and which face extended development timelines.
Market Dynamics
Oral JAK inhibitors are displacing biologic infusions across rheumatology clinics, compressing treatment protocols from infusion-center dependency to pharmacy-dispensed tablets. This delivery-mode shift is restructuring reimbursement pathways and manufacturing scale requirements simultaneously.
Growth Catalysts
- FDA label expansions:Broader indications for existing molecules accelerate off-label protocol adoption in United States academic medical centers.
- Rheumatology clinics:Patient preference for self-administered tablets over infusion center visits drives formulary prioritization of oral kinase inhibitors.
- Japan's PMDA streamlined pathways:Established reimbursement for targeted immunomodulators reduces time-to-market for novel selective inhibitors.
Market Restraints
- Cardiovascular surveillance mandates:FDA and EMA thromboembolic monitoring requirements extend clinical trial durations and inflate development costs.
- Input concentration in active pharmaceutical ingredients:Specialty kinase inhibitor precursors rely on concentrated Asian manufacturing bases, exposing supply chains to geopolitical friction.
- Biologic substitution threat:Biosimilar TNF-alpha inhibitors retain entrenched payer contracts and physician familiarity in established rheumatoid arthritis populations.
Strategic Opportunities
- Germany's outpatient pharmacy networks:Direct-to-patient oral dispensing models bypass hospital procurement bottlenecks and capture margin previously allocated to infusion logistics.
- SYK inhibitor applications:Refractory lupus and inflammatory bowel disease represent mechanistically distinct therapeutic white spaces beyond saturated JAK pathways.
- EU AI Act real-world evidence frameworks:Permitted algorithmic safety surveillance enables post-market differentiation through differentiated risk profiling.
Industry Challenges
- Kinase selectivity assay expertise:Nanomolar IC50 profiling against off-target enzymes requires specialized enzymology talent pools concentrated in Boston and Basel clusters.
- Legacy biologic integration:Infusion center infrastructure investments create organizational resistance to oral therapeutic transitions within integrated health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kinase Inhibitor in Autoimmune Diseases Market |
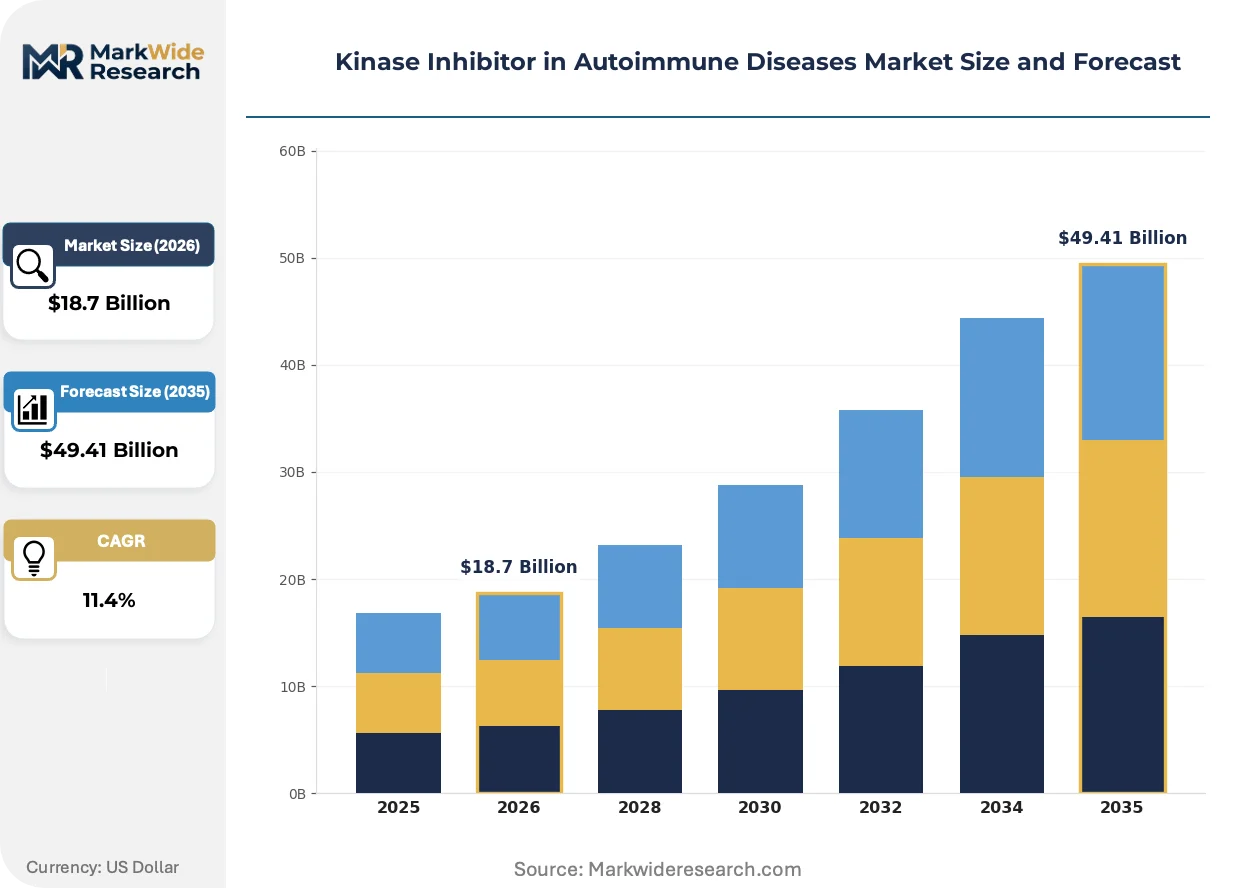
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Janus Kinase Inhibitors, SYK Inhibitors, BTK Inhibitors, Others Indication: Rheumatoid Arthritis, Psoriasis, Inflammatory Bowel Disease, Lupus Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Pfizer, Eli Lilly, Incyte Corporation, AbbVie, Gilead Sciences, Astellas Pharma, Bristol Myers Squibb, Galapagos NV, Reistone Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kinase Inhibitor in Autoimmune Diseases Market Shifts & Advancements
Next-generation development pipelines are fragmenting into precision-targeted versus broad-spectrum camps, reshaping competitive positioning around safety database differentiation rather than efficacy alone.
Allosteric kinase inhibition is hybridizing traditional ATP-competitive drug design, enabling selective targeting of conformational states rather than conserved binding pockets. Biotechnology firms in Cambridge and Basel are advancing these candidates through preclinical stages. This approach is hybridizing the competitive landscape by creating mechanistic categories that escape direct head-to-head comparison with first-generation JAK inhibitors.
EMA's tightened cardiovascular outcome requirements are forcing sponsors to embed thromboembolic adjudication into phase III protocols, extending trial timelines by twelve to eighteen months. German and French regulators are applying these standards through national scientific advice procedures. Small-molecule developers targeting United States and European Union markets simultaneously must harmonize divergent safety database expectations.
Hospital procurement committees are consolidating formulary decisions across oral and injectable immunomodulators, compressing vendor access to individual physician prescribing autonomy. Integrated delivery networks in California and Texas are piloting therapeutic-class budgeting that caps total kinase inhibitor spend regardless of delivery mode. This concentration is most visible in United States Medicare Advantage contracts where pharmacy and medical benefits are administratively unified.
Kinase Inhibitor in Autoimmune Diseases Market Segmentation
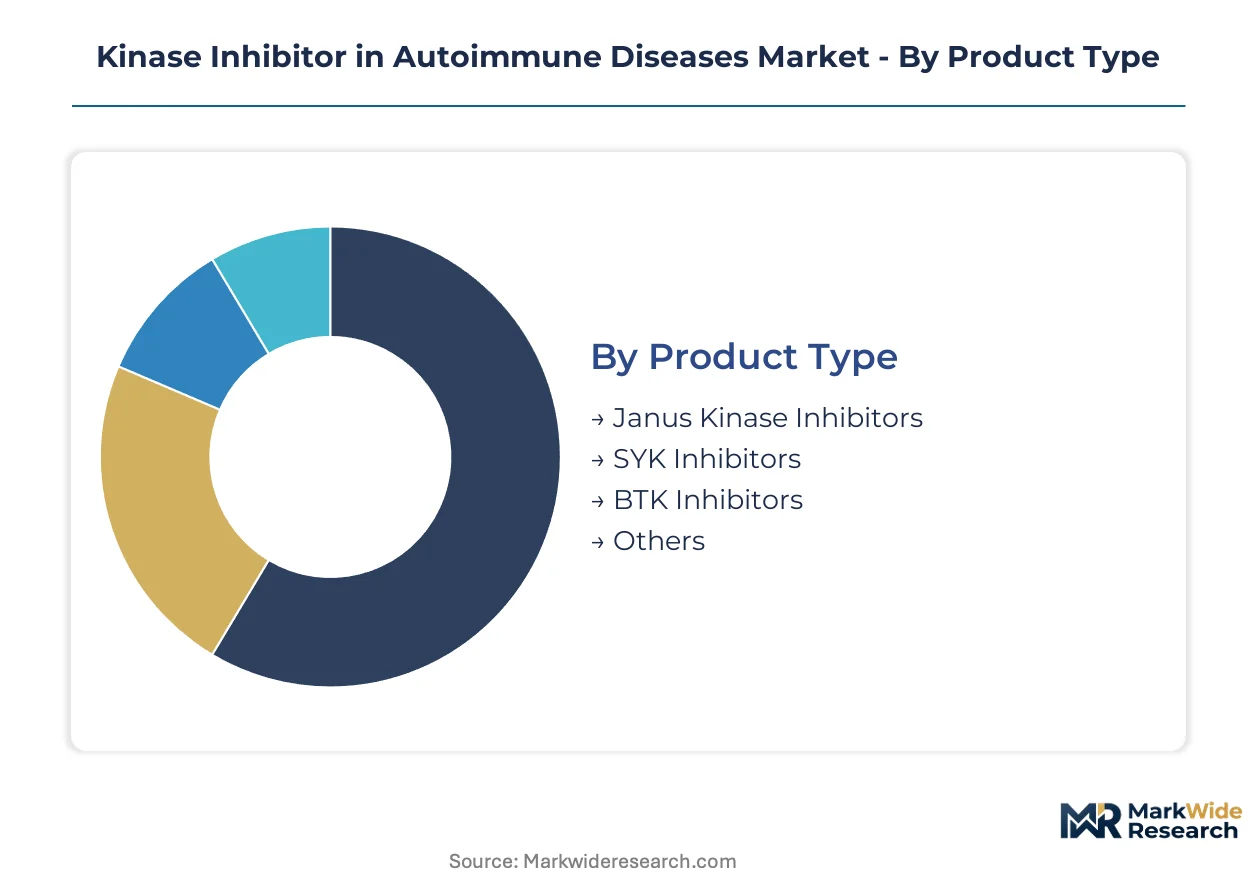
Kinase inhibitor markets fragment across mechanistic pathways, therapeutic targets, and care delivery settings. Each segmentation axis reveals distinct margin structures, regulatory exposure, and competitive entry barriers that reshape portfolio allocation decisions.
Product Type:
Mature ATP-competitive platforms anchor current revenue while next-generation allosteric approaches redraw selectivity boundaries.
- Janus Kinase Inhibitors:First-generation JAK1/JAK3 inhibitors dominate rheumatology formularies with established cardiovascular surveillance databases. United States Medicare Advantage plans prioritize these agents for rheumatoid arthritis after biologic failure, though FDA thromboembolic warnings constrain expansion into lower-risk populations.
- SYK Inhibitors:Selective spleen tyrosine kinase blockers target Fc-receptor signaling with mechanistic profiles distinct from JAK cytokine inhibition. Clinicians in Germany and Japan are adopting these for refractory lupus nephritis where JAK inhibitors lack label coverage, creating demand concentration in academic medical centers.
- BTK Inhibitors:Bruton tyrosine kinase inhibitors extend from oncology into autoimmune applications through B-cell receptor pathway modulation.
- Others:Emerging targets include TYK2 allosteric inhibitors and IRAK4 degraders in early-phase development.
Janus Kinase Inhibitors retain volume leadership; SYK Inhibitors hold the steepest expansion curve.
Indication:
Cost tier stratification separates saturated TNF-alpha successor markets from premium-priced refractory categories.
- Rheumatoid Arthritis:The largest addressable population with entrenched payer step-therapy protocols requiring biologic failure before kinase inhibitor access. United States commercial insurers and Germany's statutory health funds apply distinct prior authorization criteria that fragment pricing power.
- Psoriasis:Oral JAK inhibitors compete against established IL-17 and IL-23 biologics in dermatology clinics. Patient preference for self-administered tablets drives formulary positioning in Japan's outpatient pharmacy networks where injection avoidance carries quality-of-life weight.
- Inflammatory Bowel Disease:Mechanistic heterogeneity across Crohn's disease and ulcerative colitis creates subpopulation targeting opportunities.
- Lupus:High unmet need and failed biologic development history position selective kinase inhibitors for premium pricing if FDA approves based on organ-specific endpoints.
Rheumatoid Arthritis commands the deepest prescriber penetration; Lupus offers the highest pricing elasticity for successful entrants.
Delivery Mode:
Application context determines whether convenience premiums offset manufacturing complexity differentials.
- Oral:Immediate-release and extended-release tablet formulations capture pharmacy benefit reimbursement with patient self-administration. California and Texas integrated delivery networks are piloting therapeutic-class budgets that cap total oral immunomodulator spend.
- Injectable:Prefilled syringe and autoinjector formats bridge oral gaps in acute flare management.
- Intravenous:Hospital-administered infusion preserves medical benefit reimbursement pathways.
- Subcutaneous:Self-administered injection competes with oral tablets on convenience while retaining biologic-like pharmacokinetics.
Oral formulations dominate patient preference metrics; Subcutaneous delivery is gaining share fastest in biologic-experienced populations seeking injection familiarity without infusion center dependency.
End User:
Customer type concentration shapes contracting leverage and real-world evidence collection infrastructure.
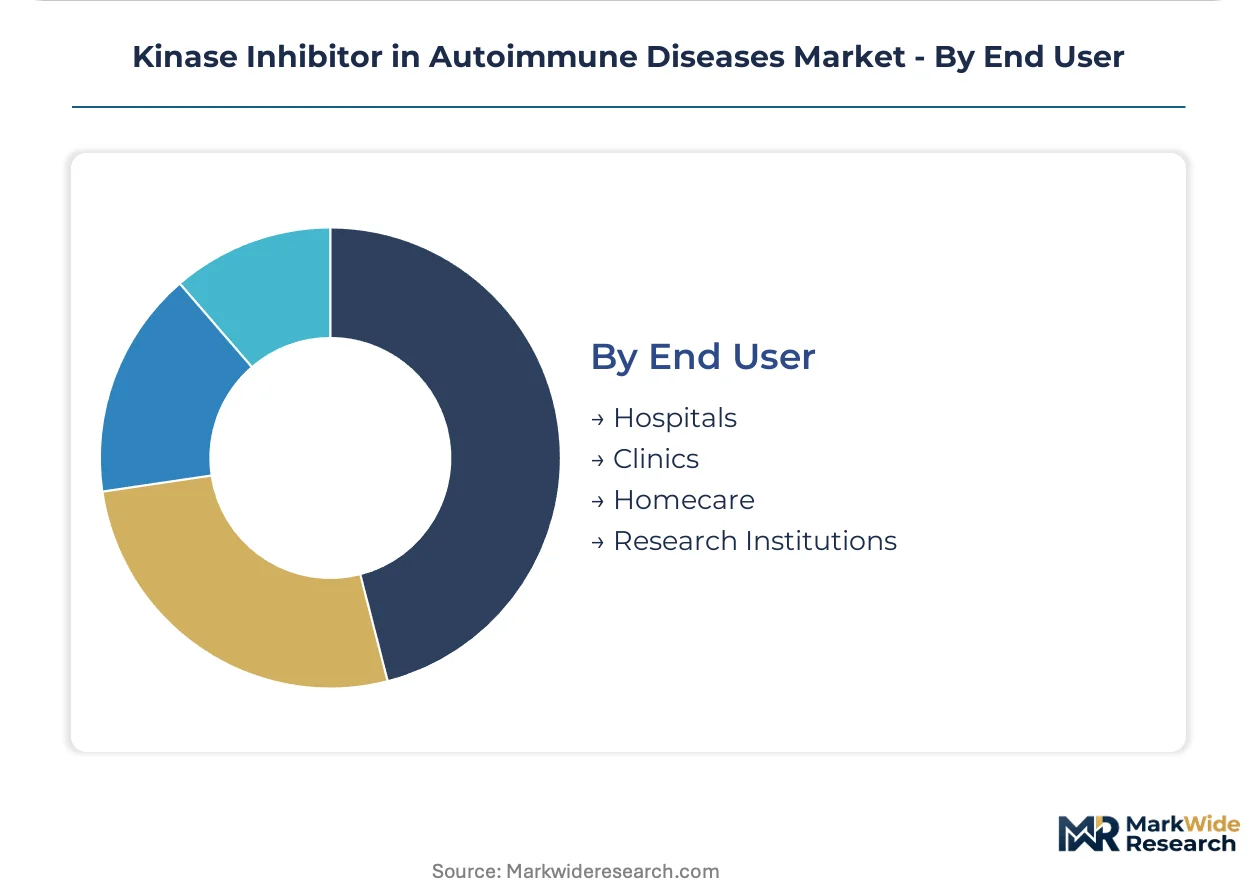
- Hospitals:Academic medical centers in Boston and Basel clusters drive off-label protocol adoption and post-market surveillance studies. Procurement committee consolidation across oral and injectable immunomodulators compresses vendor access to individual physician autonomy.
- Clinics:Rheumatology and dermatology clinics represent the fastest-expanding channel as oral kinase inhibitors displace infusion-center dependency. Germany's outpatient pharmacy networks enable direct-to-patient dispensing that captures margin from hospital procurement.
- Homecare:Specialty pharmacy distribution for self-administered oral and subcutaneous agents.
- Research Institutions:Phase IV investigator-initiated trials and real-world evidence generation partnerships.
Clinics are capturing volume leadership from hospital-based infusion centers; Homecare holds the steepest expansion trajectory as pharmacy benefit structures favor mail-order dispensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheumatology clinics in the United States, Germany, and Japan concentrate purchasing authority for oral kinase inhibitors. Academic medical centers in these markets drive off-label protocol adoption and post-market surveillance studies. Reimbursement pathways for targeted immunomodulators remain most established in these three countries.
United States
Medicare Advantage plans prioritize JAK inhibitors for rheumatoid arthritis after biologic failure. FDA thromboembolic warnings constrain expansion into lower-risk populations. Boston academic medical centers drive off-label protocol adoption and investigator-initiated trials.
Germany
Statutory health funds apply distinct prior authorization criteria that fragment pricing power. EMA cardiovascular outcome requirements reshape clinical trial designs for sponsors targeting EU markets. Outpatient pharmacy networks in Bavaria and North Rhine-Westphalia enable direct-to-patient dispensing.
Japan
PMDA streamlined pathways reduce time-to-market for novel selective inhibitors. Reimbursement for targeted immunomodulators is established in outpatient pharmacy networks. Tokyo and Osaka clusters concentrate prescriber expertise in academic medical centers.
United Kingdom
NICE technology appraisals determine formulary access for oral kinase inhibitors in rheumatoid arthritis. NHS England procurement committees consolidate decisions across oral and injectable immunomodulators. London and Manchester academic centers drive real-world evidence generation partnerships.
Switzerland
Swissmedic approval pathways align with EMA standards while permitting earlier access through temporary authorization. Premium pricing for selective kinase inhibitors reflects high unmet need in refractory lupus. Basel clusters concentrate enzymology talent pools for nanomolar IC50 profiling.
Kinase Inhibitor in Autoimmune Diseases Market Competitive Landscape
Channel-controlling players compete with product-specialist players across oral and injectable formats. The market structures around three tiers: established inflammation franchises with manufacturing scale, selective inhibition specialists with differentiated safety databases, and emerging biotechnology firms with allosteric approaches. Strategic moves concentrate on label expansion through regulatory submissions and real-world evidence generation partnerships.
Among established inflammation franchises, Pfizer and AbbVie occupy positions sustained by manufacturing scale across delivery formats. Incyte Corporation sits within the selective inhibition specialist tier, exemplifying competitive positioning through differentiated safety profiling. These three anchors represent distinct strategic archetypes: scale-driven formulary penetration, portfolio depth across JAK and BTK pathways, and precision-targeted clinical investment.
| Leading Market Players |
|---|
| Pfizer |
| Eli Lilly |
| Incyte Corporation |
| AbbVie |
| Gilead Sciences |
| Astellas Pharma |
| Bristol Myers Squibb |
| Galapagos NV |
| Reistone Biopharma |
| Others |
Supply & Pricing Matrix
Basel and Boston enzymology clusters anchor active pharmaceutical ingredient capacity for nanomolar IC50 profiling, concentrating manufacturing expertise that downstream sponsors translate into premium pricing power for selective kinase inhibitors. This geographic concentration of specialized talent creates asymmetric negotiation leverage against contract manufacturers seeking entry into precision-targeted development pipelines.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate sponsor-CM relationships, with Pfizer and AbbVie leveraging volume scale to secure favorable terms. Price differentiation rests on selectivity grade and FDA cardiovascular surveillance tier, with first-generation JAK inhibitors facing compression from biosimilar TNF-alpha substitution while SYK inhibitors command premiums in refractory lupus. Pricing pressure intensifies in rheumatoid arthritis due to entrenched payer step-therapy protocols. Hospital procurement committees exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity for mechanistically distinct profiles.
Supply Chain Analysis
Contract manufacturing concentrates among WuXi AppTec, Lonza, and Samsung Biologics for kinase inhibitor API production, with Catalent and Thermo Fisher holding fill-finish capacity. Raw material dependencies center on specialty pyrimidine and purine scaffolds, palladium catalysts for cross-coupling, and high-purity solvents for chromatographic purification. Single-source vulnerability in Chinese precursor manufacturing exposes sponsors to geopolitical friction and tariff exposure. Distribution runs through specialty pharmacy networks for oral formulations and hospital-based infusion centers for remaining injectable volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network formulary consolidation in California and Texas, where therapeutic-class budgeting caps total immunomodulator spend regardless of delivery mode.
For Market Incumbents: Insulate cardiovascular surveillance databases through prospective thromboembolic adjudication investments that exceed FDA minimums, creating regulatory moats against emerging allosteric competitors. Deepen backward integration into specialty kinase inhibitor precursors to reduce WuXi AppTec concentration risk. Prioritize label expansion submissions in lupus nephritis where JAK inhibitors lack coverage and pricing elasticity remains highest. For New Entrants and Emerging Players: Pursue refractory inflammatory bowel disease and lupus nephritis as mechanistically underserved indications where established biologics have failed and clinicians seek distinct signaling pathway options. Germany's outpatient pharmacy networks offer the most penetrable geographic entry point due to direct-to-patient dispensing infrastructure. Lead with allosteric inhibition narratives that escape head-to-head comparison with entrenched ATP-competitive JAK inhibitors. For Investors and Strategic Acquirers: Long-term, this sits as a selectivity-specialist acquisition play because precision-targeted safety profiles command durable premium pricing as FDA and EMA tighten cardiovascular outcome requirements. Target biotechnology firms with TYK2 allosteric inhibitors or IRAK4 degrader platforms in preclinical stages. Monitor FDA advisory committee outcomes for thromboembolic risk stratification as the signal indicating which development pipelines secure priority review versus extended timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Cardiovascular Outcome Trial Advancement | EMA's tightened thromboembolic requirements extend phase III protocols by twelve to eighteen months for EU market access. |
| Allosteric Inhibitor Pipeline Diversification | Cambridge and Basel biotechnology firms escape direct JAK comparator trials through conformational-state targeting mechanisms. |
| Specialty API Backward Integration | Pfizer's inflammation franchise secures captive supply of pyrimidine scaffolds against WuXi concentration risk. |
| Outpatient Pharmacy Network Partnership | Germany's direct-to-patient dispensing captures margin from hospital procurement committees in Bavaria and North Rhine-Westphalia. |
| Real-World Evidence Generation Partnership | Boston academic medical centers enable post-market differentiation through investigator-initiated surveillance studies. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States Medicare Advantage plans, and hospital procurement managers in Germany's statutory health funds. Secondary validation drew from FDA filings, EMA scientific advice procedures, ClinicalTrials.gov protocols, and formulary database extracts. Bottom-up patient-flow modeling triangulated against top-down revenue reconciliation across the analysis window.
Calibration anchored quantitative outputs to historical prescription volume trajectories and reported revenue disclosures, with segmentation across mechanistic pathway, therapeutic indication, delivery mode, and regional regulatory cluster. CAGRs were derived from slope-intercept modeling of approved molecule expansion curves and pipeline probability-adjusted net present values. Forecast inputs incorporated PMDA streamlined pathway timelines and EU AI Act constraints on algorithmic safety surveillance.
Sensitivities concentrate around FDA advisory committee outcomes for thromboembolic risk, PMDA reimbursement decisions for novel selective inhibitors, and biosimilar TNF-alpha contract erosion in rheumatoid arthritis. Forecasts reflect documented assumptions on regulatory harmonization and payer step-therapy evolution. Quarterly review of FDA label expansion submissions, EMA national scientific advice trends, and integrated delivery network formulary consolidation metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
Stuttering Therapeutics Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Meningitis Treatment Market