
 Middle East and Africa Mammography Market | 2026-2036
Middle East and Africa Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Mammography Market Analytics
Saudi Arabia is rewriting the competitive map for mammography equipment distribution across the Middle East and Africa. Hologic Inc. leverages its installed base of 3D systems to sustain service revenue in Gulf Cooperation Council states. Siemens Healthineers anchors its position through localized technical training centers in Dubai and Johannesburg. GE Healthcare competes on financing structures tailored to public hospital budgets in Nigeria and Kenya.
Mammography encompasses X-ray imaging systems designed for breast tissue examination, utilizing low-dose ionizing radiation with target-filter combinations optimized for soft-tissue contrast at 25–35 kVp tube potential. The primary commercial purpose is early detection of malignant lesions before palpable symptoms develop. Digital mammography dominates current procurement flows due to superior dose efficiency and workstation integration, while 3D mammography captures the fastest expansion as breast imaging centers upgrade tomosynthesis capability for dense-tissue populations. Full-field digital technology leads technology segmentation by installed volume, though computed radiography persists in cost-constrained settings across sub-Saharan Africa.
South Africa's national health laboratory regulator shapes equipment specifications through mandatory quality assurance protocols, while Saudi Arabia's SFDA enforces pre-market registration timelines that filter non-compliant vendors. The EU MDR's extraterritorial influence reaches Middle Eastern import channels as distributors demand CE-marked documentation. Stakeholders must monitor how national insurance reimbursement frameworks for breast screening evolve alongside digital health infrastructure investments.
Market Dynamics
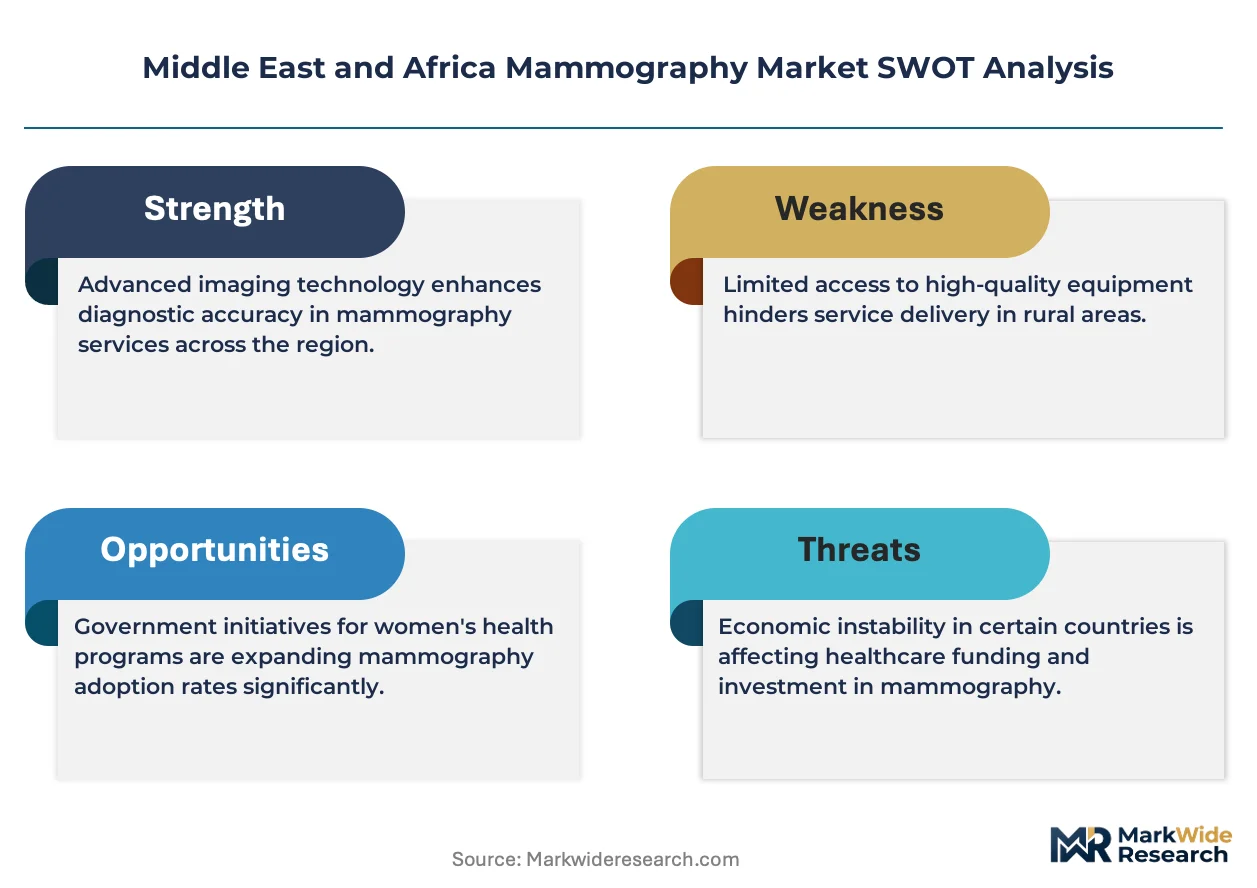
Saudi Arabia's Ministry of Health tender acceleration for women's health infrastructure is compressing procurement cycles across Gulf Cooperation Council states. Equipment vendors now face compressed bid-to-delivery timelines as public hospital screening programs expand digital mammography capacity ahead of regulatory deadlines.
Growth Catalysts
- SFDA Pre-Market Registration:Saudi Arabia's tightened device approval timelines are filtering non-compliant vendors, concentrating procurement flows toward certified suppliers with established Gulf distribution networks.
- Hospital-Based Screening Programs:Public health authorities in Egypt and Morocco are launching population-scale breast cancer detection initiatives, creating sustained equipment demand through multi-year procurement frameworks.
- 3D Tomosynthesis Upgrades:Breast imaging centers across the United Arab Emirates are replacing 2D systems with tomosynthesis-capable platforms to address dense-tissue diagnostic limitations.
Market Restraints
- Import Duty Volatility:Fluctuating customs tariffs on medical imaging equipment in Nigeria and Kenya are distorting landed cost calculations for public hospital budgets.
- Single-Source Detector Supply:Amorphous selenium flat-panel detector production concentrates in East Asian manufacturing hubs, exposing African distributors to extended lead times and currency risk.
- Radiologist Workforce Density:Sub-Saharan Africa averages below 0.5 breast imaging specialists per million population, constraining effective utilization of installed digital systems.
Strategic Opportunities
- Ethiopia Diagnostic Infrastructure:The country's national health transformation agenda has prioritized oncology service expansion, creating first-mover positioning for mobile screening unit deployments.
- AI-Assisted Detection Convergence:Integration of computer-aided diagnosis algorithms with digital mammography workstations is opening premium pricing tiers for equipment bundles in South African private hospital chains.
- Telemedicine-Enabled Second Opinion:Satellite-linked teleradiology networks are enabling centralized specialist review of screening images from remote clinics across Saudi Arabia's Northern Borders Province.
Industry Challenges
- Biomedical Engineering Talent Gap:Maintenance of digital mammography systems requires certified field engineers with specialized training in X-ray tube calibration and detector calibration protocols, skills scarce across North African service territories.
- Legacy CR System Integration:Public hospitals in Ghana and Tanzania retain computed radiography workflows that resist seamless data migration to PACS architectures required by full-field digital platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Mammography Market |
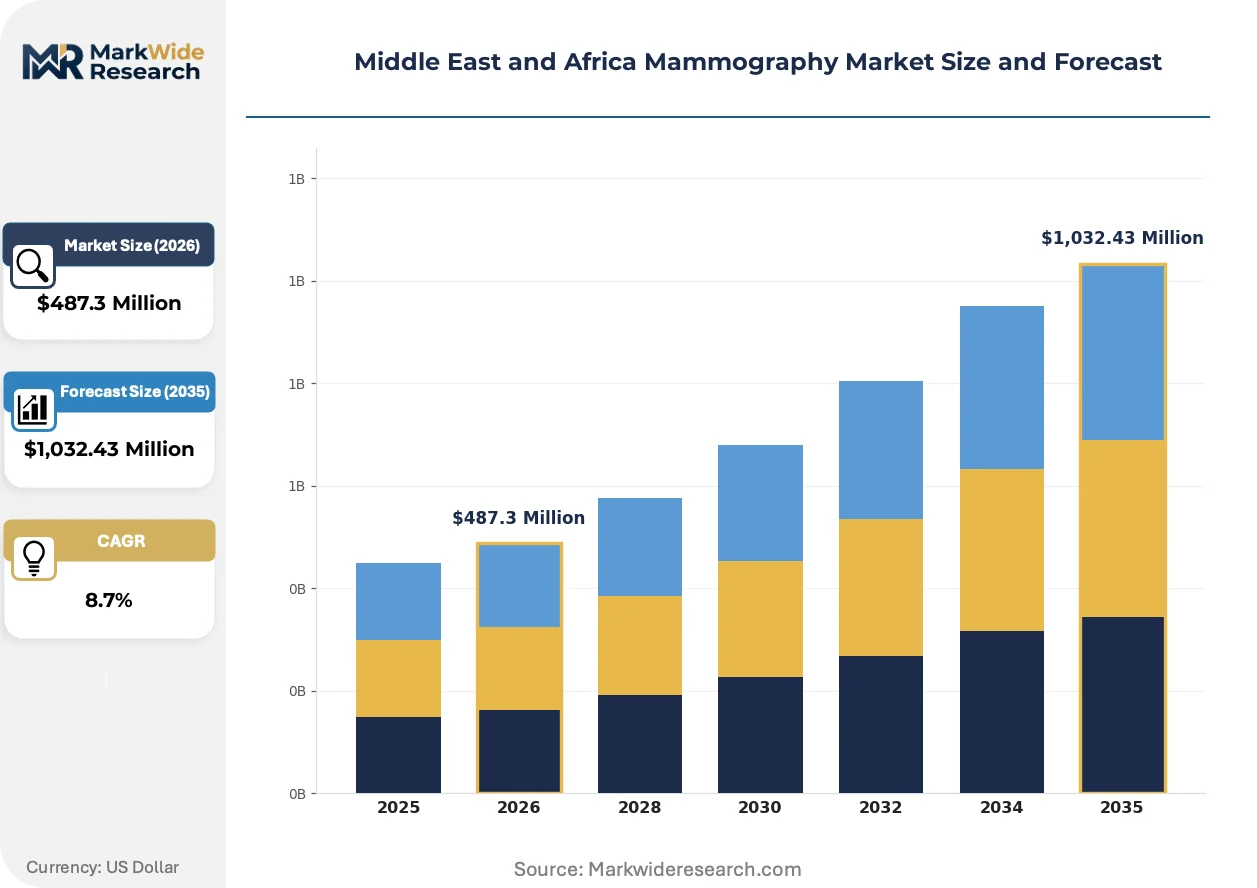
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, 3D Mammography, Analog Mammography, Breast MRI End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Technology: Full-Field Digital, Computed Radiography, Contrast-Enhanced, Ultrasonic Application: Screening, Diagnostic Imaging, Biopsy Guidance, Follow-Up |
| Companies Covered | Hologic Inc., Siemens Healthineers, GE Healthcare, Fujifilm Holdings Corporation, Koninklijke Philips NV, Canon Medical Systems Corporation, Metaltronica SpA, Planmed Oy, Konica Minolta Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Mammography Market Evolving Landscape
Digital breast tomosynthesis is compressing the technology lifecycle for conventional 2D mammography systems across Middle Eastern imaging networks. Equipment replacement cycles are shortening as diagnostic accuracy requirements tighten and reimbursement frameworks reward advanced imaging modalities.
Contrast-enhanced mammography is migrating from research settings into community breast imaging centers. Oncology departments at tertiary hospitals in Jordan and Lebanon are adopting iodinated contrast protocols for lesion characterization in dense breast tissue. The technique is enabling biopsy-free staging decisions that compress diagnostic pathways and reduce downstream MRI demand.
South Africa's national health laboratory regulator is mandating quality assurance protocols that exceed baseline ISO standards for medical imaging equipment. The framework requires quarterly phantom testing and annual physicist review of all screening installations. Private diagnostic chains are responding by embedding automated quality monitoring software into workstation architectures to reduce compliance labor.
Public hospital procurement committees are unbundling equipment purchase from long-term service agreements. Buyers in Nigeria and Kenya are negotiating separate maintenance contracts with third-party biomedical engineering firms rather than accepting captive service terms from original manufacturers. This disintermediation is most visible in Lagos and Nairobi, where independent service organizations have built detector repair capabilities that challenge factory-authorized pricing structures.
Middle East and Africa Mammography Market Segmentation
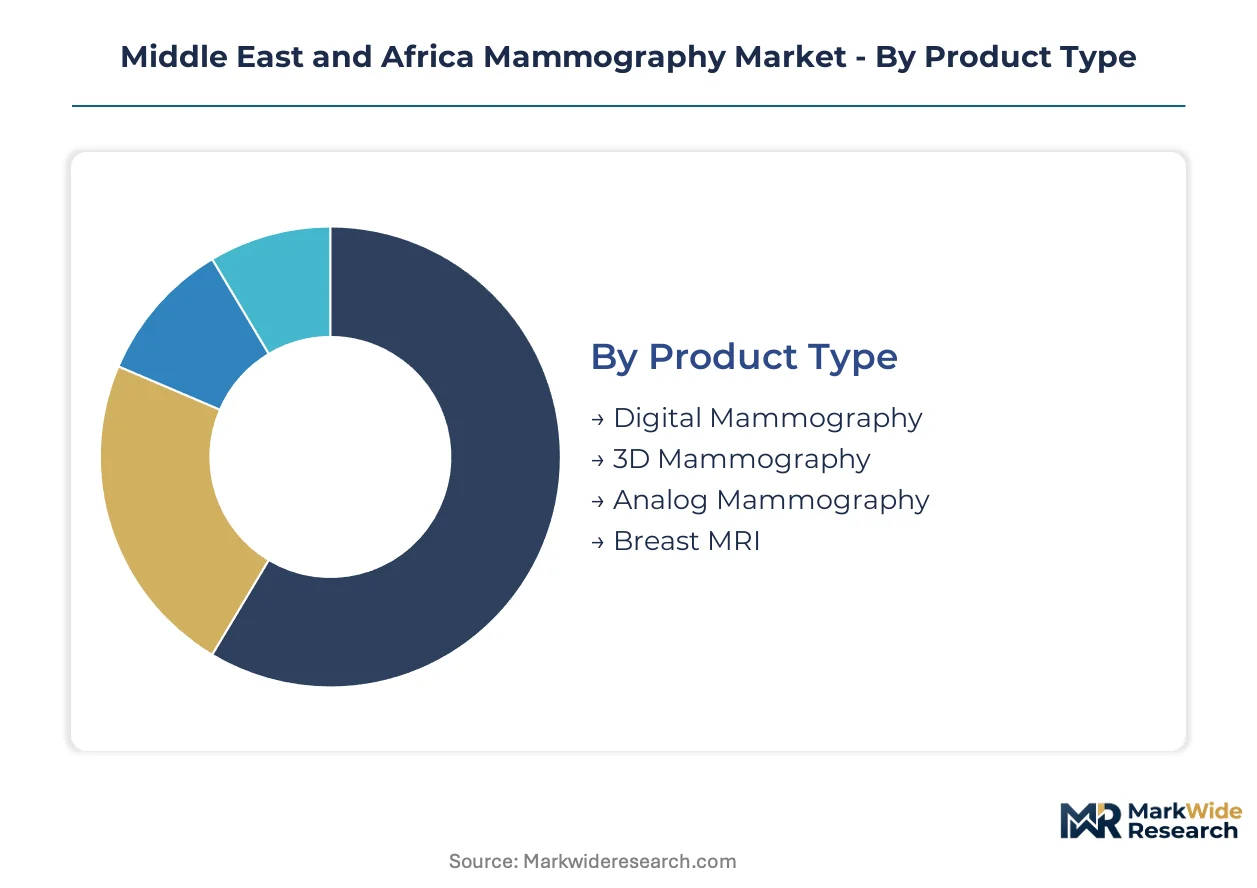
Mammography equipment procurement across the Middle East and Africa fragments across clinical settings, budget tiers, and regulatory maturity. Understanding these divisions reveals where capital concentrates and where upgrade cycles accelerate.
Product Type:
Clinical use-cases span population screening, dense-tissue diagnosis, and high-risk patient monitoring, each demanding distinct imaging architectures.
- Digital Mammography:Full-field systems employing amorphous selenium or silicon flat-panel detectors deliver superior dose efficiency and direct PACS integration. Public hospital screening programs in Egypt and Morocco anchor procurement volumes through multi-year tenders.
- 3D Mammography:Tomosynthesis platforms acquire multiple low-dose projections for volumetric breast reconstruction, addressing diagnostic limitations in dense tissue. Breast imaging centers across the United Arab Emirates are replacing 2D systems fastest here.
- Analog Mammography:Screen-film systems persist in cost-constrained environments with limited technical support infrastructure.
- Breast MRI:Magnetic resonance platforms serve high-risk patient surveillance and lesion staging at tertiary oncology centers.
Established volume favors Digital Mammography; emerging adoption favors 3D Mammography.
End User:
Customer types reflect divergent budget authority, patient throughput, and specialist availability across the region.
- Hospitals:Tertiary institutions combine screening programs with biopsy-capable interventional suites, requiring integrated diagnostic workflows. Saudi Arabia's Ministry of Health tenders are concentrating procurement here.
- Diagnostic Centers:Specialized breast imaging facilities optimize throughput and report turnaround for private-pay patients. South African private chains are embedding AI-assisted detection into workstation bundles.
- Research Institutions:Academic medical centers validate novel imaging protocols and train specialist radiologists.
- Outpatient Clinics:Community-based settings provide first-access screening in regions with limited hospital density.
Public budget flows concentrate in Hospitals; premium technology uptake concentrates in Diagnostic Centers.
Technology:
Technical architectures stratify by detector physics, image acquisition method, and contrast mechanism.
- Full-Field Digital:Direct-capture detectors convert X-ray photons to electrical signals without intermediate conversion steps, maximizing spatial resolution. This architecture leads installed base across Gulf Cooperation Council states.
- Computed Radiography:Photostimulable phosphor plates require laser scanning and erasure cycles, retaining presence where capital constraints dominate.
- Contrast-Enhanced:Iodinated contrast protocols enable vascular assessment of suspicious lesions, migrating from research into community practice in Jordan and Lebanon.
- Ultrasonic:Supplementary acoustic imaging aids cyst-solid differentiation and biopsy guidance in dense breast populations.
Full-Field Digital commands current procurement; Contrast-Enhanced is climbing the fastest.
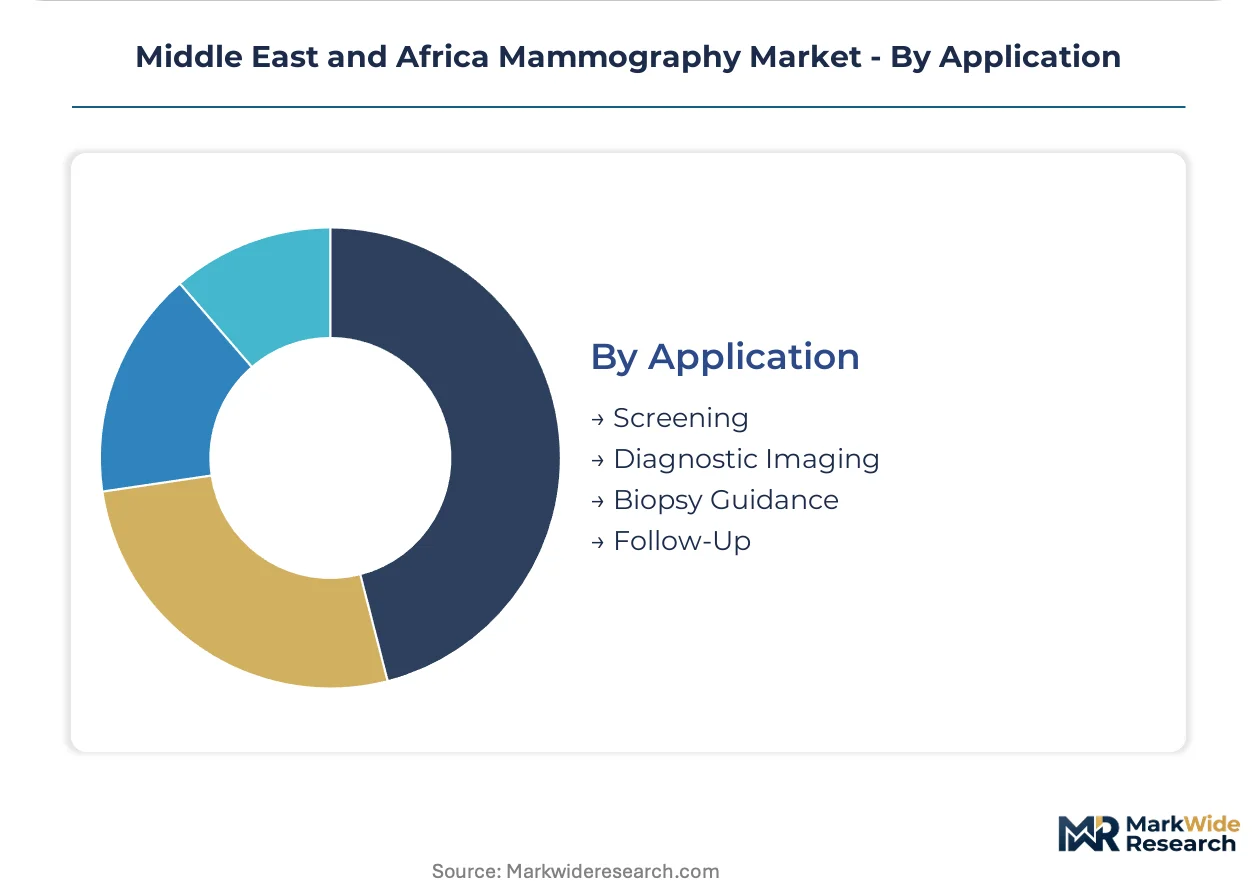
Application:
Clinical purpose determines equipment specification, throughput design, and regulatory classification.
- Screening:Asymptomatic population examination drives the highest volume utilization and strictest quality assurance protocols. South Africa's national health laboratory regulator mandates quarterly phantom testing here.
- Diagnostic Imaging:Symptomatic patient workup demands higher resolution and magnification capabilities for lesion characterization.
- Biopsy Guidance:Stereotactic and tomosynthesis-guided tissue sampling requires specialized add-on positioning systems.
- Follow-Up:Post-treatment surveillance generates recurring imaging demand with emphasis on longitudinal comparison.
Screening absorbs the largest capital allocation; Biopsy Guidance shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SFDA anchors procurement standards across the Middle East and Africa mammography market. Equipment vendors navigate divergent regulatory maturity, infrastructure readiness, and specialist density across national health systems.
Saudi Arabia
Ministry of Health tenders for women's health infrastructure are accelerating procurement cycles for digital and 3D systems. SFDA pre-market registration timelines filter non-compliant vendors, concentrating flows toward certified suppliers with established Gulf distribution networks. Riyadh and Jeddah anchor the kingdom's imaging network expansion.
United Arab Emirates
Breast imaging centers across Dubai and Abu Dhabi are replacing 2D systems with tomosynthesis-capable platforms to address dense-tissue diagnostic limitations. MOHAP enforces device quality standards that align with EU MDR documentation requirements. Dubai Healthcare City clusters tertiary oncology facilities adopting contrast-enhanced mammography protocols.
South Africa
The national health laboratory regulator mandates quarterly phantom testing and annual physicist review of all screening installations, exceeding baseline ISO standards. Private diagnostic chains embed automated quality monitoring software into workstation architectures. Johannesburg and Cape Town concentrate the country's breast imaging specialist workforce.
Egypt
Public health authorities are launching population-scale breast cancer detection initiatives, creating sustained equipment demand through multi-year procurement frameworks. The national medical device regulator requires import registration for all imaging systems. Cairo's tertiary hospital network anchors screening program deployment.
Nigeria
Fluctuating customs tariffs on medical imaging equipment distort landed cost calculations for public hospital budgets. Lagos teaching hospitals negotiate separate maintenance contracts with third-party biomedical engineering firms rather than accepting captive service terms. Independent service organizations have built detector repair capabilities challenging factory-authorized pricing.
Middle East and Africa Mammography Market Competitive Landscape
Capability concentration sits with premium-tier imaging specialists; scale advantage sits with diversified health technology conglomerates. The market structures around three archetypes: full-stack diagnostic platforms, precision breast imaging specialists, and regional service-integrated distributors. Dominant competitive moves include localized technical training center establishment and financing structure tailoring for public hospital budgets.
Among North American-based health technology conglomerates, Hologic Inc. and GE Healthcare occupy positions anchored by installed base scale and service revenue streams. Siemens Healthineers exemplifies the European diversified platform archetype with regional training infrastructure. Fujifilm Holdings Corporation represents the Asian precision imaging specialist tier with detector manufacturing integration.
| Leading Market Players |
|---|
| Hologic Inc. |
| Siemens Healthineers |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Metaltronica SpA |
| Planmed Oy |
| Konica Minolta Inc |
| Others |
Value Network & Pricing Analysis
Amorphous selenium flat-panel detector manufacturing concentrates in East Asian production hubs, anchoring margin capture with component suppliers while African distributors absorb currency risk and extended lead times. This upstream concentration shapes how equipment vendors structure financing terms for public hospital buyers across Nigeria and Kenya.
Pricing Analysis
Geographic price spreads of 25-40% separate Gulf Cooperation Council tenders from sub-Saharan procurement, reflecting divergent regulatory compliance burdens and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels dominates, with premium tiers commanding certification-grade ISO 13485 documentation and localized training commitments. Cost compression in economy tiers is intensifying because public hospitals in Ghana and Tanzania unbundle equipment purchase from captive maintenance contracts. Diagnostic centers in South African private chains show least price sensitivity, prioritizing AI-assisted detection integration over upfront capital outlay.
Supply Chain Analysis
Export control regimes restricting dual-use X-ray technology transfers limit certain detector architectures from reaching Iranian and Syrian markets, filtering supplier eligibility across Middle Eastern distribution channels. Manufacturing concentrates in Japan, South Korea, and Germany for precision detector arrays, while final assembly draws from China and Malaysia for cost-optimized units. Supply chain risk centers on single-source amorphous selenium substrate availability from Japanese chemical suppliers. Distribution runs through authorized Gulf distributors with SFDA registration credentials, bypassing direct manufacturer-to-hospital relationships in Saudi Arabia and UAE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across public hospital procurement committees, private diagnostic chains, and mobile screening operators creates multiple entry niches. Accelerating Ministry of Health tender fragmentation in Saudi Arabia and Egypt is splitting volume across regional distributors rather than concentrating with multinational direct sales.
For Market Incumbents: Pre-empt third-party service organization encroachment by embedding predictive maintenance software into detector calibration workflows, countering the threat of independent biomedical engineering firms in Lagos and Nairobi. Prioritize backward integration into detector refurbishment capabilities to defend service revenue pools against unbundled maintenance contracts. For New Entrants and Emerging Players: Ethiopia's diagnostic infrastructure expansion offers first-mover positioning for mobile screening unit deployments, with lowest competitive density among major African markets. Target outpatient clinic networks in Northern Borders Province of Saudi Arabia for telemedicine-enabled second opinion partnerships, leveraging satellite-linked teleradiology to bypass specialist workforce constraints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding SFDA registrations and Gulf hospital relationships but lacking 3D tomosynthesis technical capabilities. Five-to-ten year viability hinges on AI-assisted detection convergence with digital mammography workstations. Monitor SFDA pre-market registration timeline compression as inflection signal for vendor consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR documentation accelerates SFDA pre-market approval for Gulf market entry. |
| Hospital System Partnership | Multi-year tender frameworks with Egypt's public health authorities lock in replacement cycles. |
| Software Companion Development | AI-assisted detection algorithms embedded in South African private chain workstations command premium pricing. |
| Reimbursement Strategy | National insurance framework evolution for breast screening determines equipment upgrade timing. |
| Biomedical Engineering Training Center | Localized technical certification programs in Dubai and Johannesburg reduce field service dependency. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA device registration databases, EU MDR technical documentation, and hospital procurement tender records across Gulf Cooperation Council states. Interviews with biomedical engineering directors, GPO contracts managers, radiology department heads, and regional distributor principals combined with bottom-up installed base verification and top-down market size triangulation. Secondary sources include WHO cancer registry data, national health laboratory quality assurance protocols, and customs import records for medical imaging equipment.
Forecast inputs span product type segmentation across digital, 3D, and analog architectures; end-user categories from tertiary hospitals to outpatient clinics; technology tiers including full-field digital and contrast-enhanced systems; and application splits between screening and diagnostic imaging. CAGRs derive from regression against historical tender award volumes, projected Ministry of Health capital expenditure disclosures, and specialist workforce growth trajectories across the analysis window. Model sensitivity tests currency volatility effects on African distributor landed costs and SFDA registration timeline variations.
Practitioners should monitor Saudi Arabia's women's health infrastructure tender acceleration and South Africa's quality assurance protocol enforcement for early signals of demand inflection. Forecasts reflect assumptions around stable import duty regimes in Nigeria and Kenya, continued amorphous selenium substrate supply continuity, and radiologist workforce expansion rates in sub-Saharan Africa. Material shifts in Gulf Cooperation Council public hospital financing structures or EU MDR extraterritorial documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Dental X-Ray Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
South Africa Mammography Market
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Teleradiology Market
Medical Imaging
North America Digital Radiology Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market