
 HPLC Market | 2026-2036
HPLC Market Size, Share, and Industry Trends Forecast 2026-2036
HPLC Market Outlook
A shortage of trained chromatography specialists is bifurcating the HPLC market into premium automated systems and entry-level platforms. Waters Corporation leverages its installed base of compliance-ready software to sustain recurring revenue from regulated pharmaceutical clients. Agilent Technologies Inc. dominates the service and consumables channel through its global field engineer network. Danaher Corporation anchors its position via vertical integration across column chemistry and detection modules.
High-performance liquid chromatography separates, identifies, and quantifies mixture components by pumping pressurized liquid solvent containing the sample mixture through a column filled with solid adsorbent material, typically achieving resolution at pressures exceeding 5,000 psi. The technique serves as the analytical backbone for pharmaceutical quality control, environmental contaminant screening, and food safety verification. Columns represent the most recurring revenue segment due to disposable silica-based and polymeric stationary phases requiring regular replacement. Mass spectrometry detection technology commands the fastest expansion trajectory as hyphenated LC-MS systems displace single-detector configurations in complex biologics analysis. UV-VIS detection retains volume leadership in routine quality control applications where cost sensitivity prevails over sensitivity.
The FDA enforces Current Good Manufacturing Practice requirements that mandate validated HPLC methods for drug release testing, directly shaping instrument procurement specifications. EPA methods 525.3 and 608.3 prescribe HPLC with fluorescence or UV detection for drinking water and wastewater pollutant monitoring, creating compliance-driven replacement cycles. ISO 17025 accreditation standards for testing laboratories further tighten calibration and documentation protocols. Stakeholders must weigh capital deployment between modular upgrade paths and full system replacements as regulatory detection limits tighten and sample throughput requirements intensify.
Market Dynamics
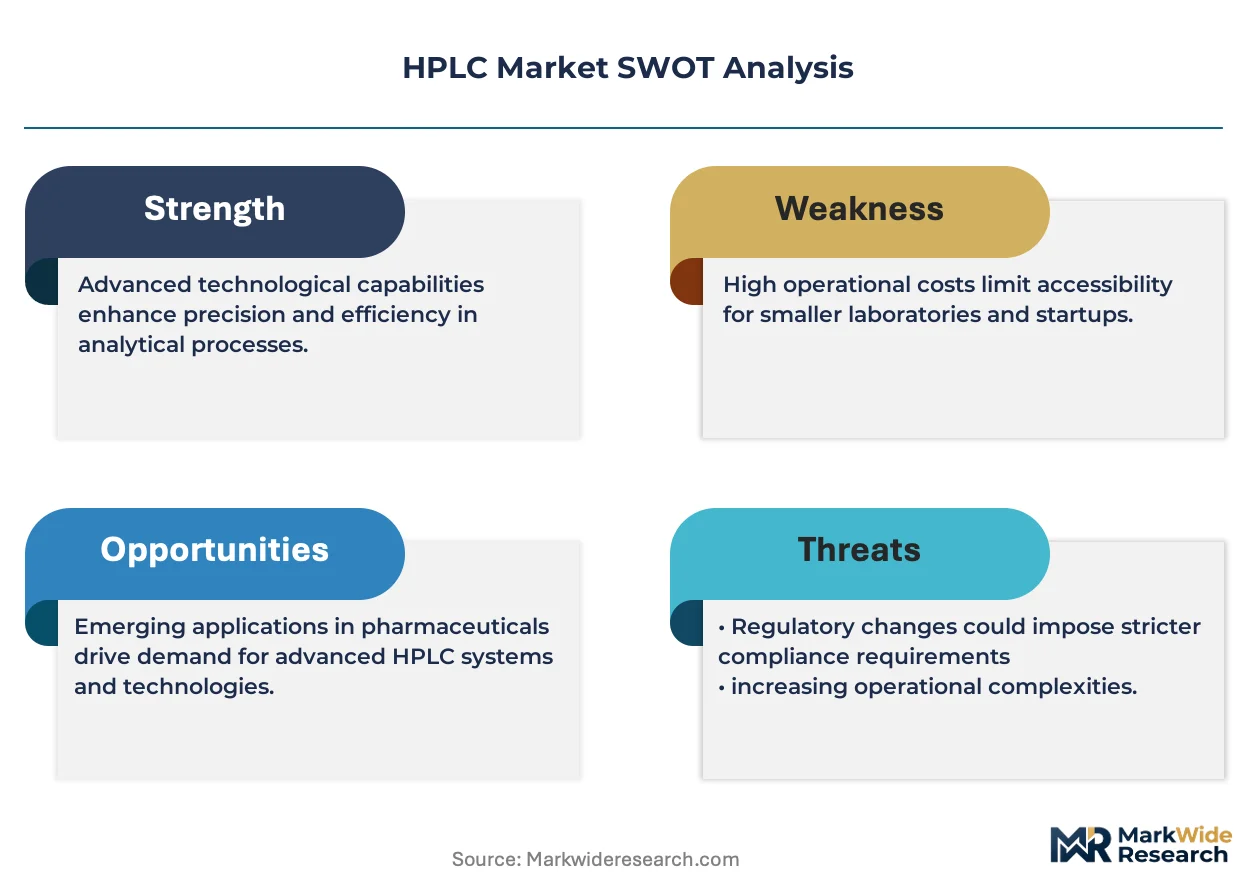
The HPLC market faces structural pressure from the shortage of trained chromatography specialists, which forces laboratories to choose between premium automated systems requiring minimal operator intervention and entry-level platforms with simplified workflows. This bifurcation is compressing mid-tier instrument demand.
Growth Catalysts
- FDA Method Validation Guidelines:The FDA's updated analytical method validation requirements tighten instrument qualification protocols, compelling pharmaceutical laboratories to upgrade aging systems and expand HPLC deployment for drug purity verification.
- Mass Spectrometry Detection Convergence:Hyphenated LC-MS systems are displacing single-detector configurations in complex biologics analysis, creating replacement demand across biopharma manufacturing clusters in Massachusetts and North Carolina.
- EPA Compliance Cycles:EPA methods 525.3 and 608.3 mandate HPLC with fluorescence or UV detection for drinking water and wastewater monitoring, driving scheduled instrument replacement in environmental testing laboratories.
Market Restraints
- Helium Supply Volatility:Gas chromatography helium shortages intermittently redirect demand toward HPLC, but residual helium dependency in certain detection modules creates input cost instability for instrument manufacturers.
- Silica Column Price Compression:Stationary phase raw material supply concentrates in China and Germany, exposing consumables producers to geographic concentration risk and margin pressure.
- UV-VIS Sensitivity Ceiling:Single-detector UV-VIS configurations face technical displacement by mass spectrometry in trace-level applications, constraining premium pricing power in routine quality control segments.
Strategic Opportunities
- Cell and Gene Therapy Analytical Demand:Emerging biologics manufacturing in South Korea and Singapore creates underpenetrated demand for ultra-high-pressure LC systems capable of resolving complex protein aggregates.
- Continuous Manufacturing Integration:Real-time release testing requirements in pharmaceutical production open white space for process analytical technology-enabled HPLC with embedded detection modules.
- ISO 17025 Accreditation Expansion:Testing laboratory certification mandates in India and Brazil tighten calibration and documentation protocols, generating service and compliance software attach-rate opportunities.
Industry Challenges
- Chromatography Specialist Scarcity:Universities produce insufficient analytical chemists trained in method development and troubleshooting, forcing vendors to absorb training costs or cede mid-market share to simplified platforms.
- Legacy System Integration Friction:Pharmaceutical quality control networks running 15-20 year-old chromatography data systems face complex validation requirements when connecting modern instruments to existing electronic batch records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HPLC Market |
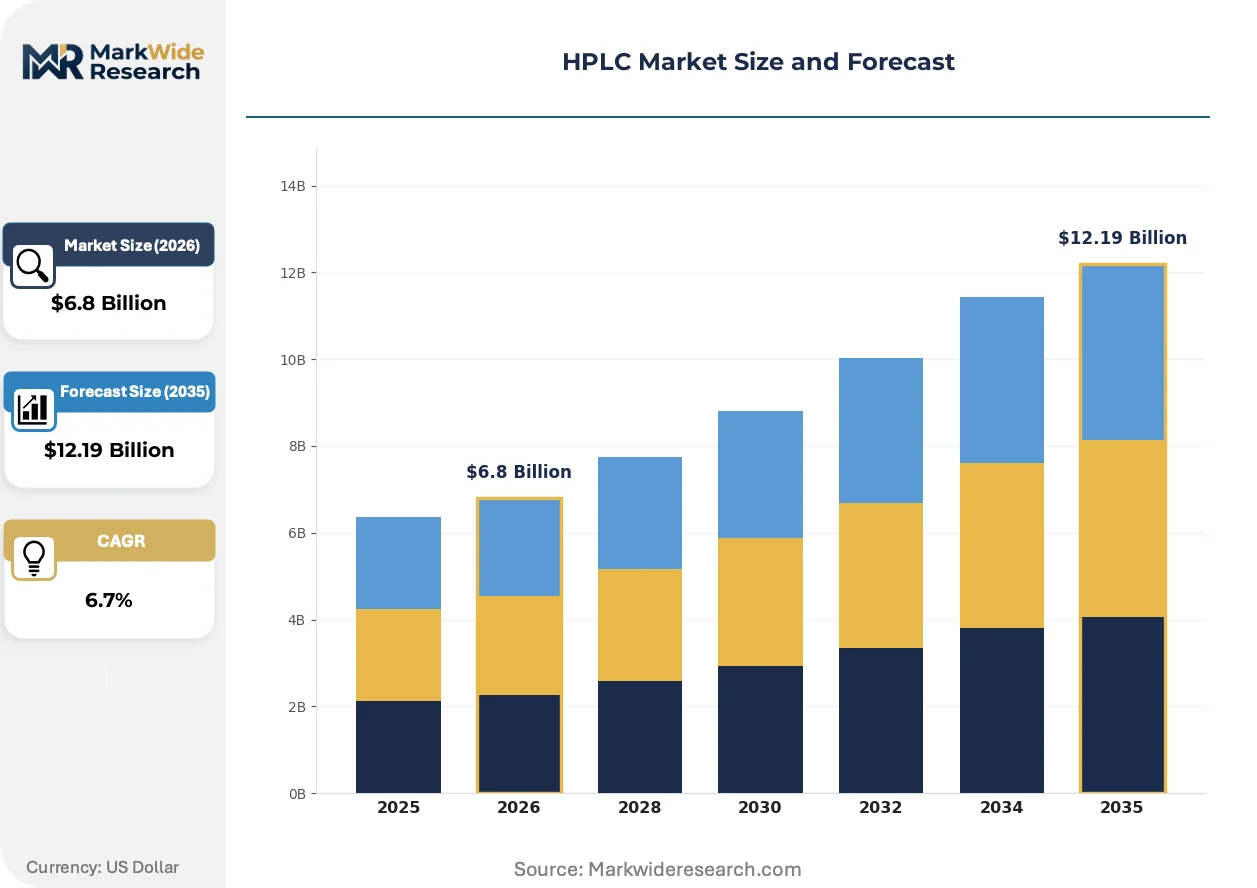
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Columns, Pumps, Detectors, Autosamplers End User: Pharmaceuticals, Biotechnology, Environmental Testing, Academia Application: Drug Testing, Quality Control, Research & Development, Food Safety Technology: UV-VIS, Fluorescence, Mass Spectrometry, Refractive Index |
| Companies Covered | Shimadzu Corporation, Merck KGaA, Waters Corporation, Hitachi High-Tech Corporation, Danaher Corporation, Agilent Technologies Inc., PerkinElmer Inc., JASCO Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HPLC Market Strategic Shifts
Instrumentation architecture is fragmenting as vendors respond to diverging operator skill levels and throughput requirements. Three distinct technology trajectories now define competitive positioning.
Ultra-high-pressure liquid chromatography is fragmenting the traditional HPLC installed base by enabling sub-2-micron particle columns to deliver resolution previously requiring longer run times. Biopharma laboratories in the United States and Germany are adopting UHPLC for stability-indicating methods at twice the pace of generic pharmaceutical facilities. This performance tier compression is squeezing conventional 5,000 psi systems into commodity routine testing roles.
REACH restrictions on hazardous solvents are reshaping mobile phase selection across European pharmaceutical and environmental testing laboratories. The ECHA regulatory framework now pressures method developers to substitute acetonitrile with less toxic alternatives in validated protocols. German and Swiss contract research organizations are responding by rebuilding chromatography libraries around aqueous buffer systems, extending method redevelopment timelines by 6-18 months.
Service contract unbundling is altering how pharmaceutical procurement teams evaluate total cost of ownership. Large molecule manufacturers in North Carolina and Massachusetts now separate preventive maintenance from software validation services, sourcing each through competitive bid rather than single-vendor bundles. This purchasing pattern fragmentation is compressing service margins for instrument manufacturers while expanding third-party field engineer networks.
HPLC Market Segmentation
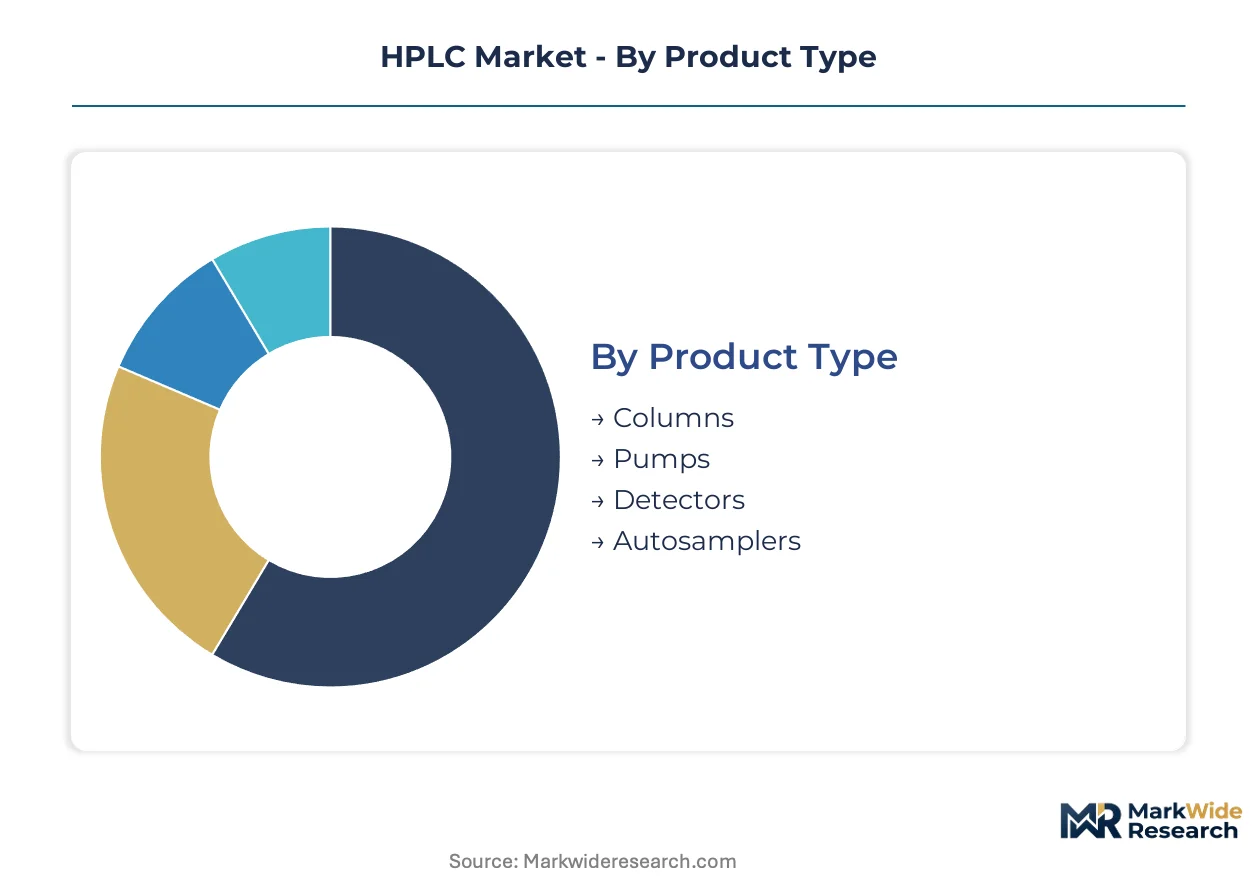
HPLC instrumentation segments face divergent substitution pressures from competing analytical platforms, with some categories defending against mass spectrometry displacement while others absorb redirected gas chromatography demand. Understanding these cross-technology dynamics shapes procurement strategy and vendor positioning across laboratory networks.
Product Type:
Columns encounter the most acute substitution threat from capillary electrophoresis and supercritical fluid chromatography in biopharma peptide analysis, while pumps and autosamplers defend installed base positions through workflow integration lock-in.
- Columns:Silica-based and polymeric stationary phases require regular replacement, generating recurring revenue streams. Demand concentrates in pharmaceutical quality control laboratories in Massachusetts and North Carolina, where FDA method validation requirements accelerate replacement cycles for validated protocols.
- Pumps:High-pressure solvent delivery systems achieving resolution above 5,000 psi constitute the core capital investment in HPLC platforms. Biopharma manufacturing clusters in Germany and Switzerland are upgrading to ultra-high-pressure variants capable of sub-2-micron particle operation.
- Detectors:Modular detection architectures allow laboratories to reconfigure systems without full instrument replacement. Environmental testing facilities facing EPA compliance cycles prioritize fluorescence and UV configurations for water pollutant monitoring.
- Autosamplers:Automated sample injection systems reduce operator intervention requirements, addressing chromatography specialist scarcity. Entry-level pharmaceutical laboratories in India and Brazil favor simplified workflows with minimal method development demands.
Columns anchor the volume base while mass spectrometry detection modules gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive biopharma deployments from budget-constrained academic installations, with environmental testing laboratories occupying a mid-tier position sensitive to regulatory compliance timing.
- Pharmaceuticals:Drug manufacturers deploy HPLC as the analytical backbone for release testing and stability studies. FDA Current Good Manufacturing Practice mandates in the United States compel validated method deployment across manufacturing sites in Puerto Rico and New Jersey.
- Biotechnology:Complex biologics analysis demands hyphenated LC-MS configurations for protein aggregate resolution. Cell and gene therapy manufacturers in South Korea and Singapore are expanding analytical capacity for emerging therapeutic modalities.
- Environmental Testing:Compliance-driven laboratories execute EPA methods 525.3 and 608.3 for drinking water and wastewater monitoring. Scheduled replacement cycles in municipal testing facilities create predictable procurement windows.
- Academia:University research laboratories prioritize modular systems supporting diverse method development. Funding constraints in European and North American institutions favor entry-level platforms with simplified operator interfaces.
Pharmaceutical laboratories command the premium tier while biotechnology applications expand most quickly.
Application:
Volume concentration in routine quality control segments contrasts with research and development applications where method flexibility and detection sensitivity determine platform selection.
- Drug Testing:Forensic and clinical laboratories employ HPLC for therapeutic drug monitoring and toxicology screening. State-level public health laboratories in the United States standardize on UV-VIS detection for cost-sensitive high-throughput protocols.
- Quality Control:Pharmaceutical release testing represents the highest-volume deployment segment with stringent documentation requirements. ISO 17025 accreditation mandates in India and Brazil tighten calibration protocols for contract testing organizations.
- Research & Development:Method development applications demand configurable systems supporting rapid column and solvent switching. Academic and biotech research clusters in Germany and Switzerland prioritize ultra-high-pressure capabilities for novel separation challenges.
- Food Safety:Contaminant screening for pesticides and veterinary residues employs fluorescence and UV detection modalities. Regulatory expansion in Brazilian and Indian food export certification drives laboratory instrumentation upgrades.
Quality control applications dominate current installed base while research and development segments climb the fastest.
Technology:
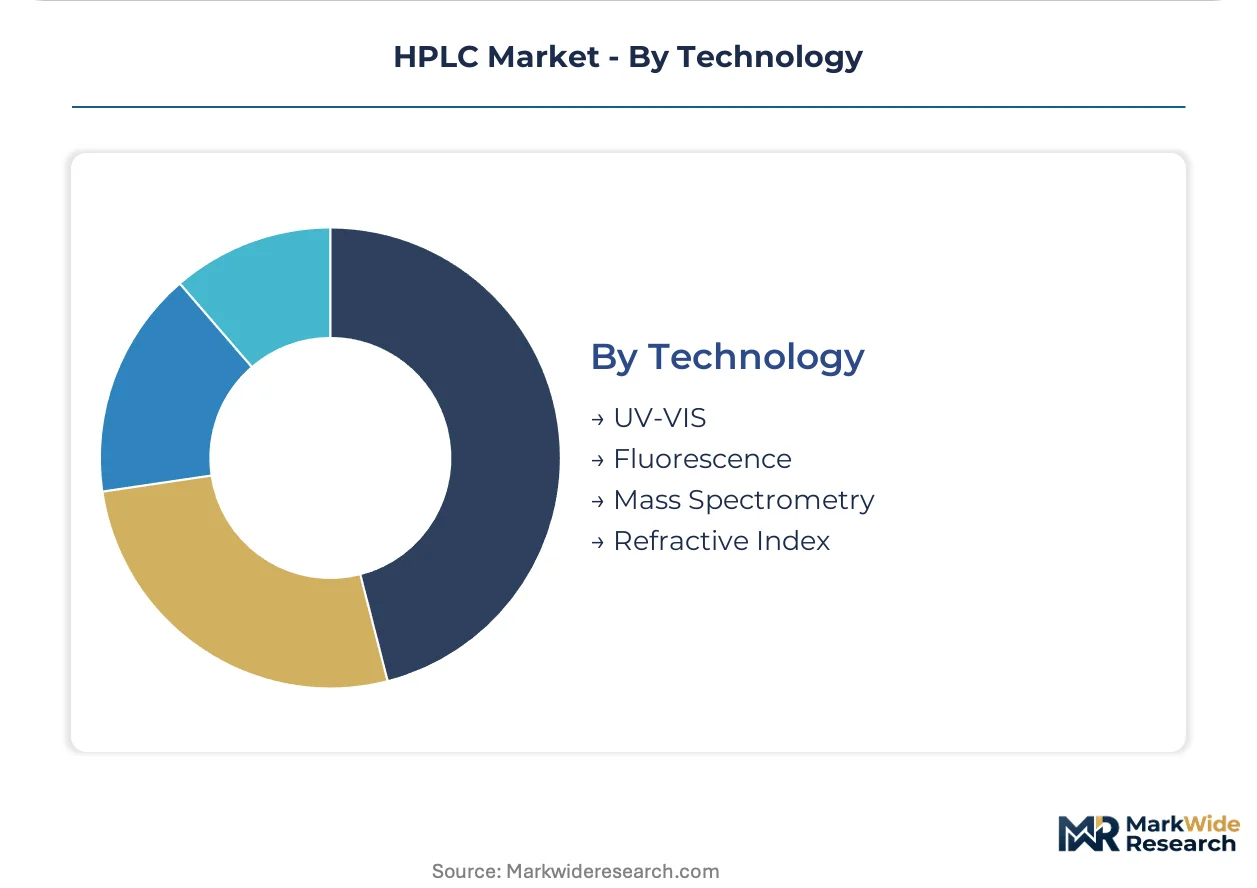
Detection technology maturity curves separate established UV-VIS configurations from mass spectrometry platforms experiencing rapid capability expansion and cost reduction.
- UV-VIS:Ultraviolet-visible absorbance detection retains cost leadership in routine applications where sensitivity requirements remain modest. Generic pharmaceutical facilities in India and Eastern Europe standardize on single-detector configurations for method transfer simplicity.
- Fluorescence:Selective detection of fluorescent compounds achieves lower detection limits than UV-VIS for specific analyte classes. Environmental testing laboratories executing EPA Method 525.3 deploy fluorescence for drinking water contaminant quantification.
- Mass Spectrometry:Hyphenated LC-MS systems deliver structural identification capabilities beyond retention time matching. Biopharma manufacturing in Massachusetts and North Carolina is displacing single-detector configurations for complex biologics characterization.
- Refractive Index:Universal detection without chromophore requirements serves carbohydrate and polymer analysis in food and chemical applications. Specialty contract research organizations in Switzerland maintain niche deployment for sugar alcohol quantification.
UV-VIS detection maintains volume leadership while mass spectrometry platforms capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and German biopharma clusters where ultra-high-pressure system premiums exceed generic pharmaceutical baselines in India and Eastern Europe by substantial margins. This asymmetry reflects divergent regulatory stringency and manufacturing complexity requirements.
United States
FDA Current Good Manufacturing Practice mandates compel validated HPLC deployment across biopharma manufacturing sites in Massachusetts and North Carolina. The agency's updated analytical method validation guidelines tighten instrument qualification protocols, accelerating replacement cycles. Cell and gene therapy manufacturers in the Research Triangle Park expand analytical capacity for emerging therapeutic modalities.
Germany
EMA quality guidelines and REACH restrictions on hazardous solvents reshape mobile phase selection across pharmaceutical and environmental testing laboratories. ECHA regulatory pressure forces method developers to substitute acetonitrile with aqueous buffer alternatives. Contract research organizations in Munich and Frankfurt rebuild chromatography libraries, extending method redevelopment timelines significantly.
Switzerland
Swissmedic enforcement of ISO 17025 accreditation standards tightens calibration and documentation protocols for testing laboratories. The country's precision manufacturing heritage supports premium positioning for ultra-high-pressure systems capable of sub-2-micron particle operation. Basel-based biopharma facilities adopt stability-indicating methods at elevated rates compared to generic pharmaceutical counterparts.
India
CDSCO manufacturing compliance requirements and expanding ISO 17025 accreditation mandates tighten instrument procurement specifications for contract testing organizations. BIS standards for laboratory equipment quality create certification barriers for imported systems. Pharmaceutical quality control laboratories in Maharashtra and Gujarat favor entry-level platforms with simplified operator interfaces to address chromatography specialist scarcity.
South Korea
MFDS biologics approval pathways and cell therapy manufacturing investments generate underpenetrated demand for ultra-high-pressure LC systems. The country's national pharmaceutical regulator accelerates review timelines for complex protein aggregate characterization methods. Biotech manufacturing clusters in Songdo and Osong expand analytical infrastructure for emerging therapeutic modalities.
HPLC Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision engineering specialists commanding premium positioning while scale-oriented manufacturers defend mid-market share through simplified platform economics. The vendor base organizes around three strategic archetypes: integrated conglomerates with captive column chemistry supply, pure-play instrument specialists with software-centric recurring revenue models, and diversified analytical platform providers with broad detection technology portfolios. Competitive moves concentrate on strategic partnerships for mass spectrometry detection convergence and geographic expansion into underpenetrated biopharma manufacturing clusters.
Among Japan-based precision instrumentation specialists, Shimadzu Corporation and Hitachi High-Tech Corporation occupy positions emphasizing ultra-high-pressure system performance and chromatography data system integration. JASCO Corporation represents the mid-market specialist archetype with focused portfolio depth. Waters Corporation and Agilent Technologies Inc. anchor the integrated analytical platform tier, with Danaher Corporation exemplifying conglomerate-scale vertical control across column chemistry and detection modules.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Merck KGaA |
| Waters Corporation |
| Hitachi High-Tech Corporation |
| Danaher Corporation |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| JASCO Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
Acetonitrile substitution with aqueous buffer systems under REACH restrictions simultaneously redistributes stationary phase manufacturing toward German and Swiss contract research organizations while compressing method redevelopment margins across European pharmaceutical laboratories.
Pricing Analysis
The customization-premium spread separates ultra-high-pressure systems configured for sub-2-micron particle operation from standard 5,000 psi platforms. Pricing stratifies across premium, standard, and economy tiers based on detection module complexity and software validation bundling. Cost compression in the economy tier intensifies because entry-level pharmaceutical laboratories in India and Brazil prioritize simplified operator interfaces over performance specifications. Generic pharmaceutical facilities in Eastern Europe exhibit the highest price sensitivity, while biopharma manufacturing clusters in Massachusetts and North Carolina absorb premium positioning for compliance-ready configurations.
Supply Chain Analysis
Germany and China anchor silica-based stationary phase production, with polymeric alternatives concentrating in Swiss specialty chemical facilities. High-purity solvent supply draws from regional petrochemical complexes in the United States and Middle East, while detection module electronics source from Japanese precision component manufacturers. Single-source vulnerability concentrates in helium-dependent detection configurations, exposing instrument manufacturers to gas supply interruptions. Distribution runs through authorized service networks with embedded field engineer capacity rather than direct equipment sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against mass spectrometry convergence displacing single-detector configurations in complex biologics analysis, a substitution threat that rewards integrated platform providers with captive detection technology.
For Market Incumbents: Fortify service contract attach rates by unbundling preventive maintenance from software validation offerings, responding to procurement team demands for competitive bidding in North Carolina and Massachusetts biopharma clusters. Deepen backward integration into column chemistry manufacturing to offset silica raw material price compression from Chinese and German supply concentration. For New Entrants and Emerging Players: Differentiate on ultra-high-pressure system affordability for cell and gene therapy manufacturers in South Korea and Singapore, where MFDS regulatory acceleration creates underpenetrated demand for protein aggregate resolution capabilities. Target ISO 17025 accreditation expansion in Indian contract testing organizations through simplified workflow platforms addressing chromatography specialist scarcity. For Investors and Strategic Acquirers: The market sits at a technology convergence phase that favors detection module specialists with mass spectrometry integration capabilities over pure-play instrument manufacturers. Long-term viability hinges on recurring revenue from consumables and compliance software rather than capital equipment cycles. Watch LC-MS hyphenation adoption rates in biopharma quality control as the inflection indicator for platform displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Detection Convergence | Hyphenated LC-MS configurations displace UV-VIS in Massachusetts biopharma stability testing protocols. |
| Continuous Manufacturing Integration | Real-time release testing requirements in North Carolina facilities open process analytical technology deployment. |
| Service Contract Unbundling | Large molecule manufacturers separate preventive maintenance from validation services through competitive sourcing. |
| REACH Compliance Method Redevelopment | German CROs rebuild chromatography libraries around aqueous buffers, extending timelines significantly. |
| ISO 17025 Accreditation Software | Indian and Brazilian testing laboratory certification mandates generate compliance documentation attach-rate opportunities. |
Study Parameters
Operator-level perspectives from pharmaceutical quality control managers, chromatography data system administrators, regulatory affairs specialists, and contract research organization laboratory directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FDA method validation guidelines, EPA compliance documentation, ISO 17025 accreditation standards, and SEC filings from publicly traded instrument manufacturers. Bottom-up segmentation modeling triangulated against top-down market sizing from trade customs data and industry association reports.
Sensitivity analysis tested forecast outputs across alternative scenarios for mass spectrometry adoption velocity and helium supply stability. The analytical framework segmented volume and value projections by product type, end user, application, and detection technology across the analysis window. CAGRs derived from instrument replacement cycle analysis, regulatory compliance timeline modeling, and biopharma manufacturing capacity expansion in named geographic clusters. Forecast inputs incorporated EPA method update schedules, ECHA solvent restriction implementation phases, and CDSCO manufacturing compliance enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained biopharma capital expenditure levels or accelerated LC-MS cost reduction curves would require recalibration. Forecasts reflect documented assumptions regarding chromatography specialist training pipeline recovery and REACH regulatory enforcement consistency. Recalibration cycles align with material shifts in FDA analytical method validation updates and MFDS biologics approval pathway modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Rheology Controller Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Viscometer Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Material Tester Market
Testing Equipment
Fibrin Degradation Product (Fndp) Assays Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Oxidation Stability Analyzer Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Total Hydrocarbon Analyzers Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market