
 Membrane Osmometer Market | 2026-2036
Membrane Osmometer Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Osmometer Market Insights
Buyer concentration among pharmaceutical quality control departments is recalibrating procurement priorities toward automated osmometry platforms. Advanced Instruments leverages its installed base in North American clinical labs to sustain recurring consumable revenue. Gonotec GmbH anchors European demand through precision engineering for research laboratories. ELITechGroup competes across Southern European diagnostics networks with localized service capabilities.
A membrane osmometer measures osmotic pressure across a semipermeable membrane to determine molecular weight or solution concentration, typically operating with cellulose acetate or regenerated cellulose membranes at controlled temperatures for colloid and polymer analysis. Static osmometers dominate installed capacity in legacy pharmaceutical facilities where throughput demands remain moderate, while dynamic osmometers capture fastest expansion in high-throughput bioprocessing quality control. Pressure measurement technology leads segment margins due to sensor miniaturization and digital calibration protocols that reduce operator intervention.
FDA osmolality guidelines for parenteral drug products shape instrument validation requirements in United States facilities, while EMA's quality guidelines for biological medicines drive comparable compliance investments across European manufacturing sites. ISO 9001 and ISO 13485 certification frameworks filter market access for suppliers serving regulated diagnostics and pharmaceutical end users. Stakeholders must weigh automation integration timelines against evolving pharmacopeial standards for osmolality determination methods.
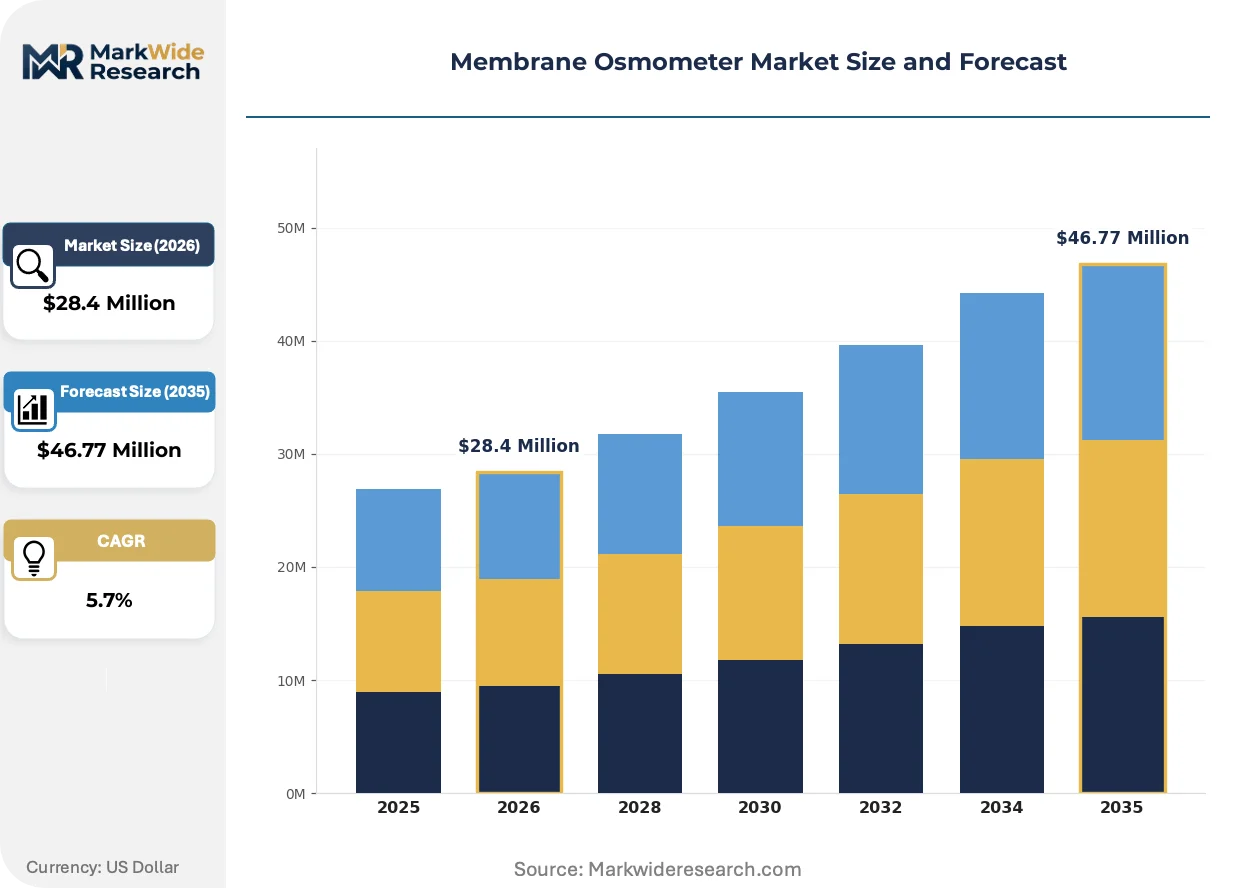
Market Dynamics
Pharmaceutical quality control departments are consolidating procurement around automated membrane osmometry platforms that compress validation cycles and reduce operator-to-operator variability in biologics manufacturing.
Growth Catalysts
- Biologics pipeline expansion:Contract development and manufacturing organizations are scaling membrane osmometer deployment to support monoclonal antibody and cell therapy production, with FDA osmolality guidance for parenteral products tightening batch release requirements.
- Cellulose acetate membrane refinements:Advances in membrane pore uniformity and chemical stability are extending measurement reproducibility across extended polymer molecular weight ranges, reducing recalibration frequency in high-throughput environments.
- United States clinical diagnostics density:Dense hospital laboratory networks and reference lab chains sustain replacement demand for legacy static osmometers while absorbing first dynamic osmometer installations in bioprocessing quality control.
Market Restraints
- Regenerated cellulose membrane supply concentration:European specialty chemical suppliers dominate semipermeable membrane substrate production, exposing instrument manufacturers to input cost volatility and single-source qualification risks.
- Sensor miniaturization cost barriers:Piezoelectric pressure transducer fabrication requires capital-intensive cleanroom infrastructure, elevating entry thresholds for regional instrument assemblers.
- ISO 13485 certification timeline friction:In vitro diagnostic device classification in regulated markets extends product registration cycles, delaying revenue recognition for new platform introductions.
Strategic Opportunities
- Indian biopharmaceutical manufacturing scale-up:CDSCO quality guidelines for biological medicines are driving osmometer procurement among domestic vaccine and biosimilar producers expanding GMP-compliant capacity.
- Digital calibration protocol convergence:Integration of cloud-connected sensor diagnostics with laboratory information management systems is unifying instrument fleets under predictive maintenance contracts.
- Cell and gene therapy application white space:Viral vector concentration monitoring and lipid nanoparticle characterization represent emerging use cases beyond traditional polymer analysis.
Industry Challenges
- Metrology technician specialization gaps:Colloid and polymer osmometry requires expertise in thermodynamic activity coefficients and membrane fouling diagnostics that outpaces vocational training program refresh rates.
- Legacy static osmometer integration complexity:Pharmaceutical facilities with decades-old installed bases face workflow disruption when bridging manual protocols to automated dynamic platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Osmometer Market |
| Market Size in 2026 | $28.4 Million |
| Market Size in 2035 | $46.77 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Osmometers, Dynamic Osmometers, Vapor Pressure Osmometers, Freezing Point Osmometers Technology: Electrical Resistance, Pressure Measurement, Optical Density, Capillary Method End User: Pharmaceuticals, Food & Beverage, Research Laboratories, Clinical Diagnostics Application: Quality Control, Research & Development, Product Testing, Educational Purposes |
| Companies Covered | Advanced Instruments, Precision Systems Inc., Gonotec GmbH, ELITechGroup, ARKRAY Inc., Loser Messtechnik, Wescor Inc., Knauer Wissenschaftliche Geräte GmbH, Nova Biomedical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Osmometer Market Trends and Innovations
Membrane osmometry instrumentation is pivoting from discrete analytical tools toward integrated bioprocess monitoring nodes, with sensor architecture and data infrastructure co-evolving to support real-time release testing paradigms.
Miniaturized piezoelectric pressure sensors are unifying osmotic pressure detection with temperature-compensated digital signal processing in single-chip modules. Bioprocessing quality control departments at mammalian cell culture facilities are adopting these consolidated sensor packages to reduce calibration drift. This unification is compressing the competitive advantage of standalone instrument manufacturers that rely on discrete component sourcing.
EMA quality guidelines for biological medicines are mandating enhanced characterization of polydisperse macromolecular species in drug substance specifications. European manufacturing sites are investing in dynamic osmometer platforms that satisfy pharmacopeial osmolality determination methods while supporting molecular weight distribution analytics. The pressure measurement technology segment is responding with modular instrument architectures that segregate regulatory-compliant workflows from research-grade method development.
Service contract unbundling is fragmenting traditional capital equipment procurement into instrument, consumable, and validation service line items. Reference laboratories in the United States are negotiating separate agreements for membrane replacement schedules and IQ/OQ/PQ documentation packages. This disaggregation is most pronounced in clinical diagnostics networks where procurement committees prioritize operational expenditure visibility over bundled capital outlays.
Membrane Osmometer Market Segmentation
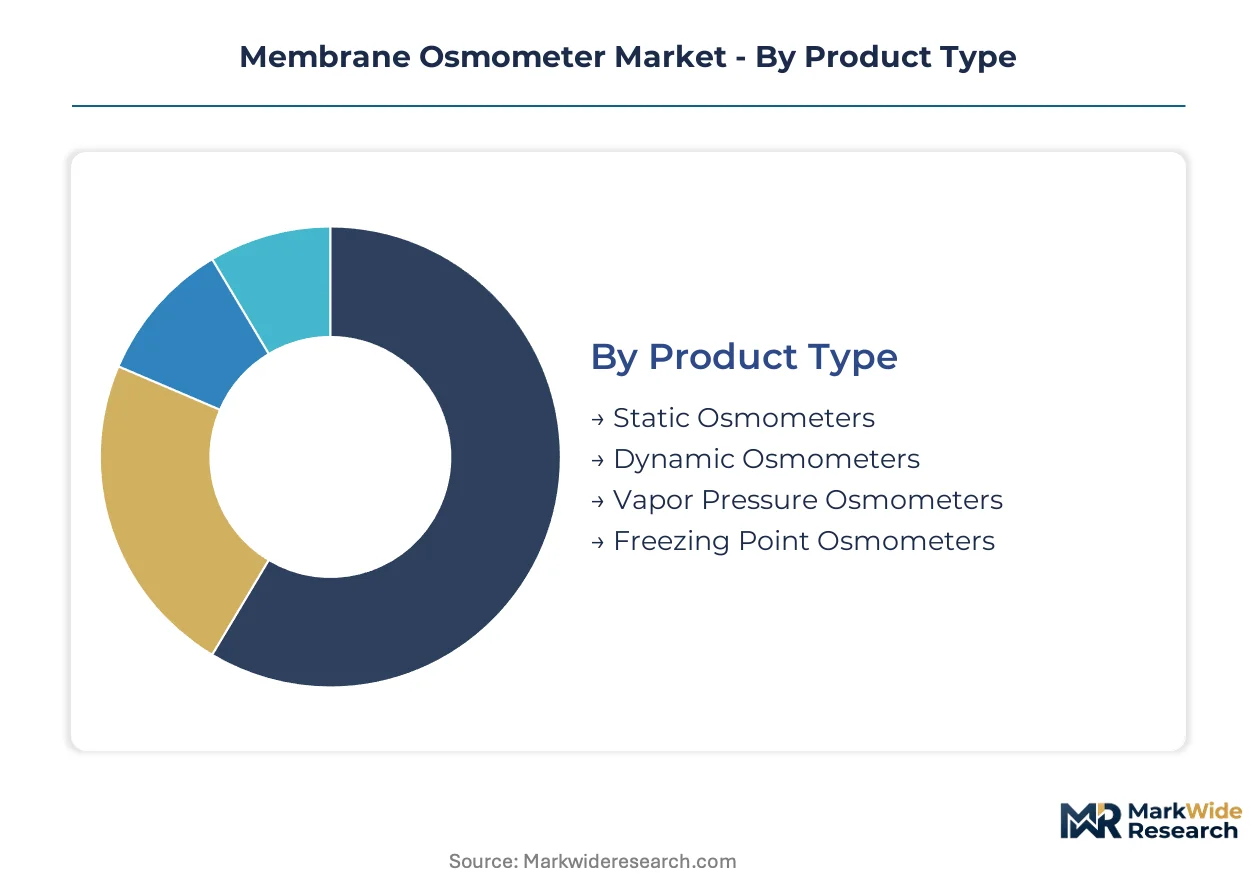
Membrane osmometer segmentation reveals distinct procurement patterns across automation tiers and regulatory compliance thresholds. Pharmaceutical quality control departments prioritize platforms that compress batch release timelines while satisfying pharmacopeial validation requirements.
Product Type:
Customization intensity varies sharply across this category, from manually operated legacy units to fully automated bioprocess monitoring nodes.
- Static Osmometers:These instruments rely on equilibrium-based pressure measurement across semipermeable membranes without active flow systems. Pharmaceutical facilities in the United States with moderate throughput demands retain these units for routine polymer molecular weight determination, though calibration drift limits deployment in continuous manufacturing environments.
- Dynamic Osmometers:Active flow configurations accelerate measurement cycles through forced convection across membrane surfaces. Bioprocessing quality control departments at mammalian cell culture facilities are absorbing these platforms fastest, driven by FDA osmolality guidance for parenteral drug products that tightens batch release documentation requirements.
- Vapor Pressure Osmometers:These units determine osmolality through vapor pressure depression rather than membrane-based pressure differential.
- Freezing Point Osmometers:Instruments measuring colligative properties via cryoscopic depression for clinical diagnostics applications.
Leading the category by volume: Static Osmometers. Growing fastest: Dynamic Osmometers.
Technology:
Cost tier stratification separates premium sensor architectures from commodity detection methods in this category.
- Pressure Measurement:Piezoelectric transducer miniaturization enables temperature-compensated digital signal processing in single-chip modules. Bioprocessing facilities are consolidating procurement around these consolidated sensor packages to reduce calibration drift and operator intervention.
- Electrical Resistance:Conductivity-based detection methods measure ionic concentration changes across membrane interfaces. Food and beverage quality control laboratories leverage these cost-effective platforms for routine osmolality screening in beverage formulation.
- Optical Density:Photometric detection systems track refractive index shifts in solution analysis.
- Capillary Method:Traditional displacement-based measurement approaches persist in educational settings.
Dominating margin capture: Pressure Measurement. Expanding most quickly in biopharma: Pressure Measurement.
End User:
Application maturity drives divergent procurement specifications across customer types in this category.
- Pharmaceuticals:Quality control departments at monoclonal antibody and cell therapy manufacturers deploy membrane osmometers for molecular weight verification and osmolality compliance. FDA guidance on injectable formulation testing mandates instrument validation investments that elevate platform specifications.
- Research Laboratories:Academic and institutional facilities prioritize modular architectures supporting method development across polymer and colloid systems. European research centers anchor demand for precision-engineered static configurations with extended membrane compatibility.
- Food & Beverage:Process control laboratories utilize osmometry for concentration monitoring in dairy and beverage production.
- Clinical Diagnostics:Hospital and reference laboratories deploy osmometers for serum and urine osmolality testing.
Commanding highest average selling prices: Pharmaceuticals. Penetrating fastest among CDMOs: Pharmaceuticals.
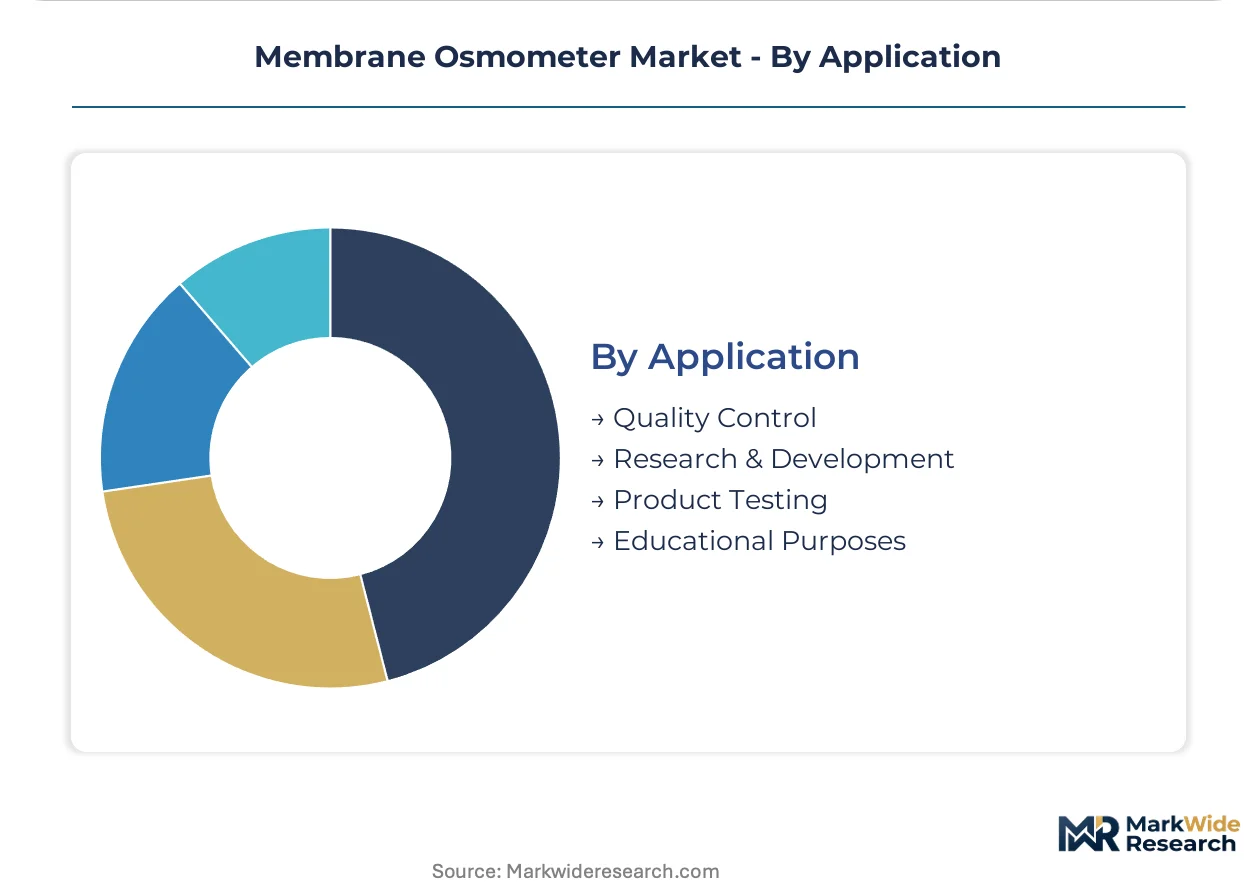
Application:
Volume concentration versus value capture creates distinct competitive dynamics across use cases in this category.
- Quality Control:Batch release testing for biologics and parenteral formulations demands GMP-compliant documentation and IQ/OQ/PQ validation packages. Contract manufacturing organizations are scaling osmometer fleets to support monoclonal antibody production under tightening regulatory scrutiny.
- Research & Development:Method development for novel therapeutic modalities requires flexible platform configurations supporting polymer characterization and formulation screening. Cell and gene therapy developers are pioneering viral vector concentration monitoring applications beyond traditional osmometry scope.
- Product Testing:Routine verification of raw material specifications and finished product stability.
- Educational Purposes:Training instrumentation for academic instruction in physical chemistry and thermodynamics.
Generating largest installed base: Quality Control. Gaining share fastest: Research & Development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regenerated cellulose membrane substrate production concentrates among European specialty chemical suppliers, creating input cost volatility that shapes geographic procurement patterns for instrument manufacturers worldwide.
United States
Biopharmaceutical R&D spending density and hospital laboratory network scale sustain replacement demand for legacy static osmometers while absorbing first dynamic osmometer installations. FDA osmolality guidance for parenteral drug products tightens batch release documentation requirements. The Greater Boston and San Francisco Bay Area biotech clusters anchor demand for high-throughput bioprocessing quality control platforms.
Germany
Precision engineering capabilities and research laboratory infrastructure anchor European demand for static osmometer configurations with extended membrane compatibility. EMA quality guidelines for biological medicines mandate enhanced characterization of polydisperse macromolecular species. The Baden-Württemberg and Bavaria industrial regions concentrate pharmaceutical manufacturing investments driving instrument procurement.
India
Domestic vaccine and biosimilar producers expanding GMP-compliant capacity are scaling osmometer procurement under CDSCO quality guidelines for biological medicines. The country's national pharmaceutical regulator tightens quality control requirements for injectable formulations. Maharashtra and Gujarat pharmaceutical manufacturing corridors concentrate contract development and manufacturing organization facility expansion.
Japan
Monoclonal antibody and cell therapy production facilities deploy membrane osmometers for molecular weight verification and osmolality compliance under PMDA regulatory frameworks. METI industrial policy supports bioprocessing infrastructure modernization. The Kanto and Kansai metropolitan regions concentrate pharmaceutical quality control laboratory investments.
United Kingdom
Academic and institutional research facilities prioritize modular osmometer architectures supporting method development across polymer and colloid systems. MHRA alignment with EMA quality guidelines shapes instrument validation requirements. The Oxford-Cambridge-London golden triangle anchors demand for precision-engineered research-grade configurations.
Membrane Osmometer Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue service contract unbundling and predictive maintenance integration. The vendor base stratifies across instrument manufacturers with captive membrane supply relationships and modular platform specialists. Three archetypes dominate: precision-engineering houses with European research laboratory anchors, clinical diagnostics incumbents leveraging North American installed bases, and diversified life science conglomerates with bundled validation service capabilities. Competitive moves concentrate on geographic expansion into Indian biopharmaceutical manufacturing corridors and technology licensing for cloud-connected sensor diagnostics.
Among precision-engineering specialists with German corporate structures, Gonotec GmbH and Knauer Wissenschaftliche Geräte GmbH exemplify the research laboratory anchor archetype. Advanced Instruments represents the North American clinical diagnostics incumbent position. ELITechGroup occupies a diversified European life science platform position with Southern European diagnostics network penetration. ARKRAY Inc. exemplifies the Asia-Pacific clinical laboratory focus archetype.
| Leading Market Players |
|---|
| Advanced Instruments |
| Precision Systems Inc. |
| Gonotec GmbH |
| ELITechGroup |
| ARKRAY Inc. |
| Loser Messtechnik |
| Wescor Inc. |
| Knauer Wissenschaftliche Geräte GmbH |
| Nova Biomedical |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical quality control departments at monoclonal antibody manufacturers negotiate instrument procurement through multi-year service contracts that bundle validation documentation with consumable replenishment schedules. This buyer concentration enables premium pricing for FDA-compliant dynamic osmometer platforms while compressing margins on legacy static configurations.
Pricing Analysis
Volume concentration in static osmometers sustains economy-tier pricing for educational and routine polymer screening applications, while pressure measurement technology platforms command premium positioning through piezoelectric sensor miniaturization and digital calibration protocols. Price differentiation separates ISO 13485-certified bioprocessing instruments from research-grade configurations lacking GMP documentation packages. Pricing pressure stems from CDSCO-mandated quality upgrades at Indian vaccine producers seeking entry-level dynamic platforms. Contract development and manufacturing organizations exhibit highest price sensitivity due to capital expenditure constraints, whereas reference laboratories in the United States prioritize operational expenditure visibility over upfront instrument costs.
Supply Chain Analysis
Domestic-content mandates under India's Production Linked Incentive scheme for medical devices are reshaping sourcing patterns for instrument assemblers seeking tariff advantages in that market. Regenerated cellulose membrane substrate production concentrates in Germany, France, and Austria, exposing manufacturers to input cost volatility when European specialty chemical suppliers adjust capacity. Piezoelectric pressure transducer fabrication draws from cleanroom infrastructure in Japan, South Korea, and the United States. Single-source qualification risks for cellulose acetate membrane formulations create vulnerability to supply disruption. Distribution runs through authorized distributor networks with localized validation service capabilities rather than direct instrument sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around automated platform specialists as ISO 13485 certification timelines and sensor miniaturization capital requirements force regional assemblers toward exit or acquisition.
For Market Incumbents: Extend predictive maintenance contract penetration among North American clinical diagnostics networks to lock in recurring revenue streams against emerging cloud-connected sensor diagnostics entrants. Deepen captive membrane supply relationships with European specialty chemical suppliers to defend margin position against input cost volatility. Prioritize backward integration into piezoelectric transducer fabrication where cleanroom infrastructure permits. For New Entrants and Emerging Players: Cloud-connected sensor diagnostics with laboratory information management system integration offers the most penetrable wedge for technology-first challengers seeking foothold. Target Indian biopharmaceutical manufacturing corridors where CDSCO quality guidelines are tightening but GMP-compliant instrument supply remains constrained. Pursue white-label partnerships with domestic assemblers to circumvent lengthy product registration cycles. For Investors and Strategic Acquirers: The window for entry favors precision-engineering houses with European research laboratory anchors and established EMA compliance track records. Long-term viability rests on consolidation plays that combine modular platform architectures with validation service capabilities. Monitor CDSCO enforcement intensity at Indian vaccine producers as inflection indicator for emerging market demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Miniaturization Investment | Piezoelectric single-chip modules reduce calibration drift at mammalian cell culture facilities. |
| Predictive Maintenance Contract Expansion | Cloud-connected diagnostics unify instrument fleets under recurring revenue arrangements with reference laboratories. |
| Indian Manufacturing Corridor Entry | CDSCO quality guidelines for biological medicines drive osmometer procurement among domestic vaccine producers. |
| Captive Membrane Supply Integration | European specialty chemical supplier relationships mitigate regenerated cellulose substrate cost volatility. |
| Cell Therapy Application Development | Viral vector concentration monitoring extends osmometry utility beyond traditional polymer analysis scope. |
Research Methodology
Document review covered FDA guidance documents, EMA quality guidelines, ISO 13485 certification records, and pharmacopeial osmolality determination methods, complemented by interviews with bioprocessing quality control directors, regulatory affairs specialists at monoclonal antibody manufacturers, metrology technicians, and laboratory information management system integration specialists. Secondary validation drew from CDSCO circulars, PMDA regulatory frameworks, SEC filings of listed life science instrument companies, and trade data for semipermeable membrane substrate imports. Bottom-up instrument shipment estimates triangulated against top-down biopharmaceutical R&D spending allocations.
Installed base projections across static and dynamic osmometer configurations, pressure measurement and electrical resistance technology tiers, and pharmaceutical quality control versus research laboratory end-use segments were generated through the analytical framework over the projection horizon. CAGRs were derived from regression analysis against biologics pipeline expansion rates and regulatory compliance investment cycles. Forecast inputs incorporated FDA osmolality guidance enforcement intensity and EMA quality guideline revision timelines.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting piezoelectric transducer trade flows, breakthrough displacement of membrane-based osmometry by mass spectrometry methods, and pandemic-scale disruptions to biopharmaceutical manufacturing operations. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and membrane substrate supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Lubricant Testing Machine Market
Testing Equipment
Liquid Chromatography Market
Testing Equipment
Process Analytical Technology Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Material Tester Market
Testing Equipment
Digital Shore Durometer Market
Testing Equipment
Hydrocarbon Tester Market
Testing Equipment
Paper Tester Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Flammability Tester Market
Testing Equipment
Next-Generation Titrators Market
Testing Equipment
Water Testing Equipment Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Brittleness Tester Market
Testing Equipment
Nitrogen Tester Market