
 In-Line UV-Vis Spectroscopy Market | 2026-2036
In-Line UV-Vis Spectroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
In-Line UV-Vis Spectroscopy Market Intelligence
Silicon photodiode arrays are decoupling in-line UV-Vis systems from legacy scanning monochromator architectures, cutting optical path complexity and maintenance cycles by half. Endress+Hauser Management AG leverages its process automation installed base to bundle spectroscopic probes with flow control systems. Agilent Technologies, Inc. anchors its position through chromatography-to-spectroscopy workflow integration. Thermo Fisher Scientific Inc. dominates the biopharmaceutical segment with GMP-validated optical train configurations.
In-line UV-Vis spectroscopy deploys fiber-coupled spectrometers operating across 190–1100 nm wavelengths to measure absorbance, transmittance, or reflectance without extracting samples from flowing process streams. The technique enables real-time concentration monitoring, endpoint detection, and impurity tracking in pressurized or hazardous environments where offline sampling introduces contamination risk or safety exposure. Automated product-type configurations command the strongest margin pools by embedding self-calibration routines and digital twin connectivity that reduce operator intervention. Process monitoring applications within the end-user dimension are outpacing quality control in growth velocity as chemical manufacturers retrofit continuous flow reactors with PAT-compliant analytical loops. Fiber optic technology leads in deployment volume due to its immunity to electromagnetic interference and compatibility with explosion-proof housings.
FDA process analytical technology guidance and EU MDR device classification rules jointly shape validation documentation burdens and equipment qualification protocols for manufacturers serving regulated industries. EPA effluent monitoring mandates and REACH substance registration requirements further expand the addressable base for environmental and chemical sector installations. Stakeholders must weigh optical durability specifications against total cost of ownership when specifying probes for high-salinity or high-temperature process conditions.
Market Dynamics
Fiber-coupled silicon photodiode arrays are collapsing optical path complexity in in-line UV-Vis systems, halving maintenance cycles while FDA and EU MDR validation protocols simultaneously tighten equipment qualification burdens for continuous manufacturing deployments.
Growth Catalysts
- Process Analytical Technology Mandates:FDA guidance on real-time release testing compels pharmaceutical manufacturers to embed spectroscopic probes directly into bioreactor control loops, eliminating offline sampling contamination risks.
- Continuous Flow Chemistry Expansion:Chemical manufacturers in Germany and the United States are retrofitting pressurized reactors with PAT-compliant analytical loops for endpoint detection and impurity tracking.
- Explosion-Proof Fiber Optics:Fiber optic probe immunity to electromagnetic interference enables deployment in hazardous environments where electrical spectrometers face ignition hazards.
Market Restraints
- High-Purity Sapphire Window Costs:Optical durability specifications for high-salinity or high-temperature process streams require synthetic sapphire probe interfaces, inflating per-probe material costs substantially.
- Validation Documentation Burden:EU MDR device classification rules impose extensive equipment qualification protocols that extend sales cycles and require specialized regulatory affairs personnel.
- Legacy Monochromator Obsolescence Risk:Installed bases of scanning monochromator architectures face stranded asset exposure as silicon photodiode arrays decouple performance from mechanical optical benches.
Strategic Opportunities
- Environmental Effluent Monitoring:EPA discharge mandates and REACH substance registration requirements are expanding the addressable base for chemical and wastewater sector installations requiring real-time contaminant detection.
- Digital Twin Integration:Automated product-type configurations embedding self-calibration routines and digital twin connectivity command premium positioning by reducing operator intervention requirements.
- Biopharmaceutical GMP Validation:GMP-validated optical train configurations for bioprocess monitoring represent underpenetrated white space in contract manufacturing organizations serving biosimilar production.
Industry Challenges
- Cross-Disciplinary Talent Scarcity:Integration of spectroscopic hardware with process control systems demands professionals conversant in optical engineering, chemical process dynamics, and GMP compliance simultaneously.
- Legacy System Integration Complexity:Retrofitting fiber-coupled spectrometers into existing distributed control systems requires custom communication protocol bridges that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Line UV-Vis Spectroscopy Market |
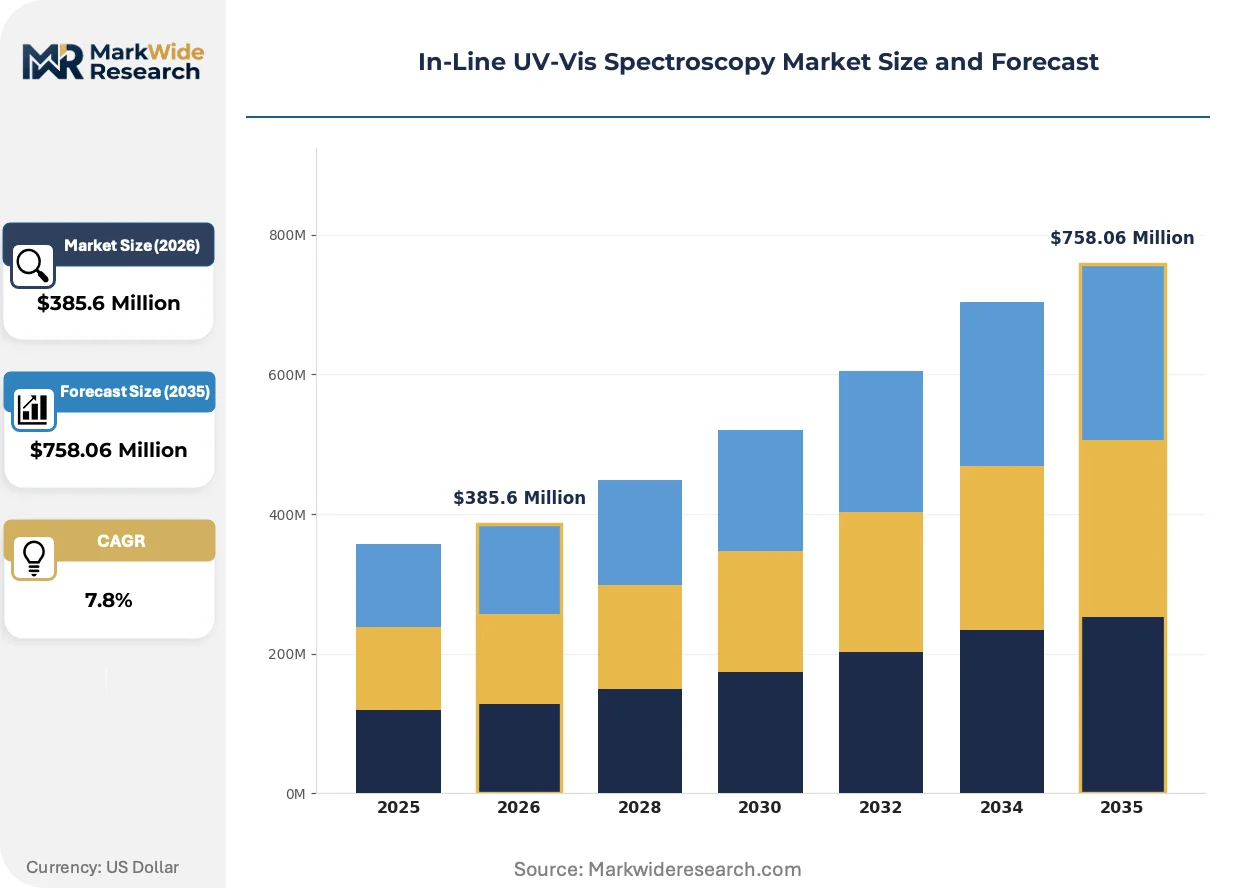
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $758.06 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-top, Portable, Handheld, Automated End User: Chemical Industry, Pharmaceutical Labs, Food & Beverage, Environmental Monitoring Technology: Fiber Optic, Tunable Filter, Array Detector, Spectrometer Application: Quality Control, Process Monitoring, Research & Development, Educational Purposes |
| Companies Covered | X-Rite, Endress+Hauser Management AG, Agilent Technologies, Inc., ColVisTec AG Inc., Kemtrak AB, Thermo Fisher Scientific Inc., AMETEK, Inc., Guided Wave, Inc., Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Line UV-Vis Spectroscopy Market Strategic Shifts & Innovations
Real-time bioprocess monitoring is forcing architectural transitions across hardware, regulatory compliance frameworks, and procurement models. Three distinct vectors are compressing traditional competitive positions.
Silicon photodiode array technology is rewriting the performance economics of in-line UV-Vis spectroscopy. These solid-state detectors capture full spectral data without mechanical scanning, enabling sub-second measurement cycles in flowing process streams. Biopharmaceutical manufacturers in Bavaria and the Boston-Cambridge corridor are deploying these systems for real-time titer monitoring and harvest optimization. The technology is rewriting supplier competitive dynamics by collapsing the barrier between entry-level and high-performance instrument tiers.
EU MDR medical device classification rules and FDA process analytical technology guidance are jointly elevating validation documentation requirements. Equipment qualification protocols now demand extensive optical train traceability and software lifecycle documentation. Biopharmaceutical end-use segments bear the heaviest compliance burden, with manufacturers responding by pre-qualifying probe configurations and embedding self-diagnostic routines that automate requalification after maintenance events.
Service unbundling is fragmenting traditional equipment procurement patterns. End-users increasingly separate hardware acquisition from validation support, calibration services, and digital twin implementation, sourcing each element through specialized vendors. This disintermediation is most pronounced in the United States, where contract manufacturing organizations prioritize flexible procurement structures that align analytical capital expenditures with specific program timelines rather than enterprise-wide standardization.
In-Line UV-Vis Spectroscopy Market Segmentation
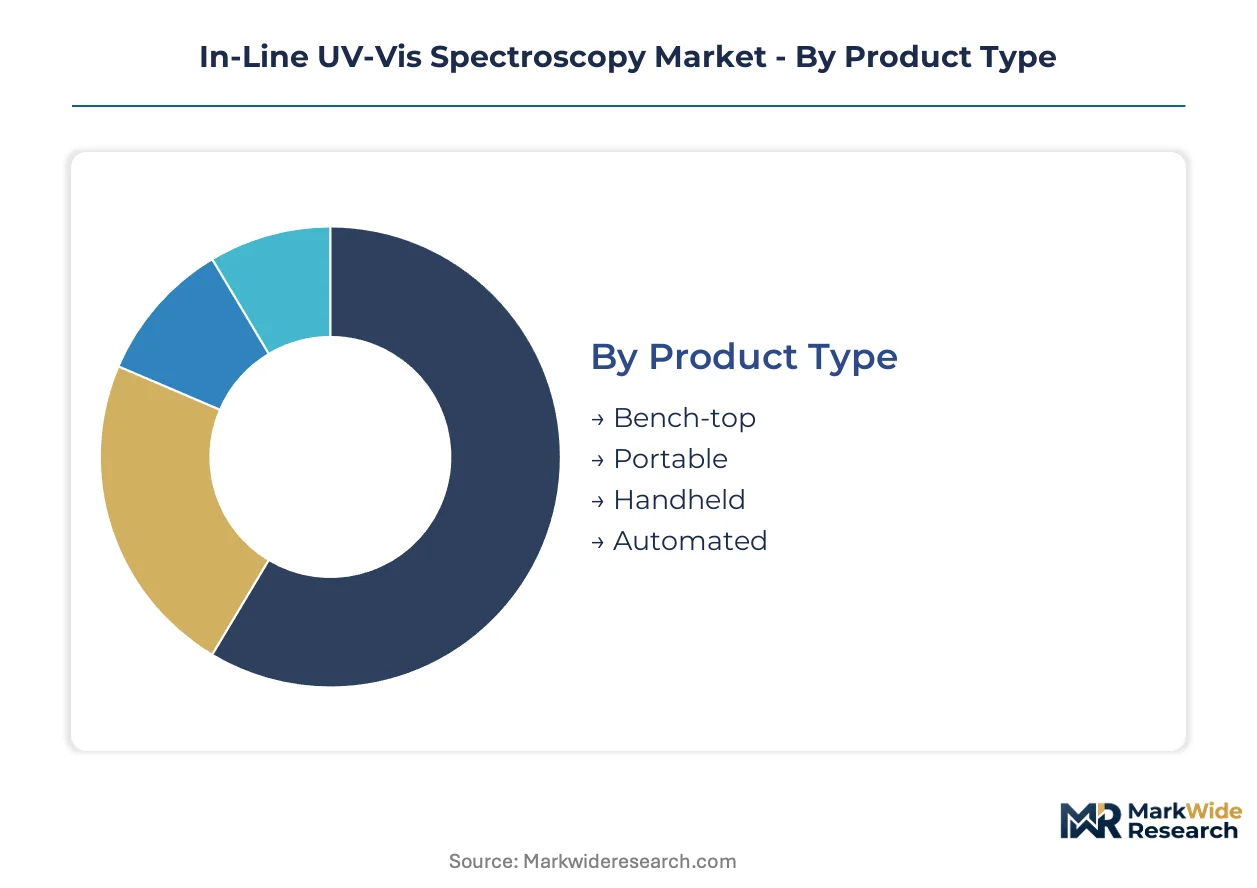
Segmentation in in-line UV-Vis spectroscopy reveals how hardware specifications, deployment environments, and regulatory pressures fragment purchasing behavior. Technology choices determine maintenance burdens and validation pathways, while end-user verticals impose distinct optical durability and connectivity requirements.
Product Type:
Optical architecture and enclosure specifications define four hardware tiers with divergent total cost of ownership profiles.
- Automated:Self-calibration routines and digital twin connectivity reduce operator intervention in continuous manufacturing environments. Pharmaceutical labs in Germany and the United States are expanding procurement of these configurations for real-time bioprocess monitoring under FDA process analytical technology guidance.
- Bench-top:Stationary units with fixed optical benches serve centralized quality control laboratories requiring high spectral resolution. Demand concentrates in Bavaria's pharmaceutical cluster where legacy infrastructure favors localized analytical stations over distributed probe networks.
- Portable:Battery-powered units with fiber-coupled probes enable mobile troubleshooting across multi-reactor facilities.
- Handheld:Compact single-wavelength devices address spot-check requirements in hazardous area classifications.
Mature deployment sits with Bench-top. Newer deployment is concentrated in Automated.
End User:
Regulatory stringency and contamination risk tolerance create four distinct customer archetypes with non-overlapping procurement specifications.
- Pharmaceutical Labs:GMP-validated optical train configurations dominate capital expenditure, driven by EU MDR device classification rules and FDA process analytical technology initiatives. The Boston-Cambridge biotech corridor represents dense demand for fiber-optic probes integrated into bioreactor control loops.
- Chemical Industry:Pressurized reactor retrofitting for continuous flow chemistry demands explosion-proof housings and sapphire window interfaces. German chemical manufacturers are prioritizing PAT-compliant analytical loops for endpoint detection and impurity tracking.
- Environmental Monitoring:EPA effluent monitoring mandates and REACH substance registration requirements expand installations for real-time contaminant detection.
- Food & Beverage:Hygienic design specifications and CIP compatibility constrain probe selection for inline concentration monitoring.
Procurement maturity is highest in Chemical Industry. Steepest expansion trajectory is occurring in Pharmaceutical Labs.
Technology:
Detector physics and optical coupling mechanisms determine measurement speed, electromagnetic immunity, and maintenance interval economics.
- Fiber Optic:Immunity to electromagnetic interference enables deployment in hazardous environments where electrical spectrometers face ignition hazards. Fiber-coupled silicon photodiode arrays are collapsing optical path complexity and halving maintenance cycles in Bavaria's pharmaceutical cluster and the Boston-Cambridge corridor.
- Array Detector:Solid-state capture of full spectral data without mechanical scanning enables sub-second measurement cycles in flowing process streams. Biopharmaceutical manufacturers are deploying these systems for real-time titer monitoring and harvest optimization.
- Tunable Filter:Acousto-optic or liquid crystal wavelength selection trades spectral range for optical simplicity in dedicated process streams.
- Spectrometer:Conventional scanning monochromator architectures face stranded asset exposure as silicon photodiode arrays decouple performance from mechanical optical benches.
Installed base concentration remains with Spectrometer. Technology transition is accelerating toward Array Detector.
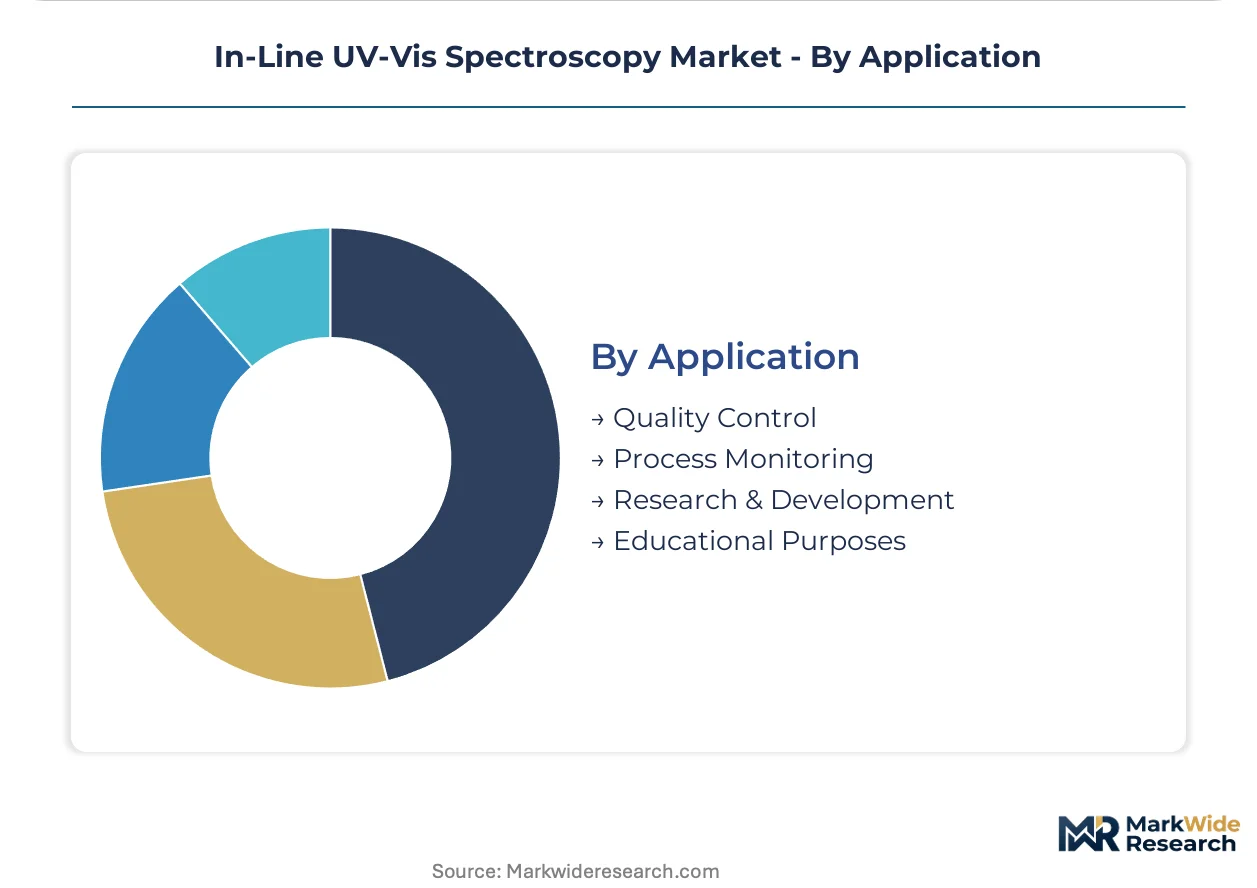
Application:
Use case specificity dictates probe durability specifications, software validation requirements, and integration depth with distributed control systems.
- Process Monitoring:Real-time concentration monitoring and endpoint detection in pressurized or hazardous environments where offline sampling introduces contamination risk or safety exposure. Chemical manufacturers in Germany and the United States are retrofitting continuous flow reactors with PAT-compliant analytical loops.
- Quality Control:Offline or at-line verification of product specifications against pharmacopeial standards requires traceable calibration chains.
- Research & Development:Method development flexibility and multi-wavelength capability prioritize spectral range over environmental hardening.
- Educational Purposes:Cost-optimized configurations sacrifice measurement speed and optical durability for capital accessibility.
Quality Control represents the established revenue base. Gaining share fastest is Process Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's pharmaceutical cluster and the Boston-Cambridge biotech corridor anchor concentration through specialized tax incentives and research zone designations that favor continuous manufacturing infrastructure.
United States
FDA process analytical technology guidance compels pharmaceutical manufacturers to embed spectroscopic probes into bioreactor control loops. The EPA effluent monitoring mandates expand installations for real-time contaminant detection in chemical manufacturing. The Boston-Cambridge biotech corridor represents dense demand for fiber-optic probes integrated into continuous flow reactor retrofits.
Germany
Chemical manufacturers prioritize PAT-compliant analytical loops for endpoint detection in pressurized reactor environments. The EU MDR device classification rules impose extensive equipment qualification protocols on pharmaceutical equipment suppliers. Bavaria's pharmaceutical cluster is expanding adoption of silicon photodiode arrays for real-time bioprocess monitoring.
China
Domestic pharmaceutical contract manufacturing organizations are retrofitting facilities with in-line analytical systems to meet export market GMP requirements. The national pharmaceutical regulator tightens validation documentation for continuous manufacturing equipment serving international markets. The Yangtze River Delta concentration of chemical manufacturers is deploying explosion-proof fiber optic probes in hazardous production environments.
Japan
PMDA quality-by-design initiatives accelerate integration of real-time release testing into biopharmaceutical production workflows. METI industrial technology programs subsidize advanced process analytical equipment adoption in domestic chemical manufacturing. The Kansai region's specialty chemical producers are implementing fiber-coupled spectrometers for impurity tracking in continuous flow systems.
Switzerland
Swissmedic GMP inspection protocols emphasize optical train traceability for spectroscopic equipment used in drug substance manufacturing. The country's pharmaceutical export orientation demands equipment configurations compatible with both FDA and EMA qualification standards. Basel's pharmaceutical manufacturing concentration is driving procurement of automated product-type configurations with embedded self-calibration routines.
In-Line UV-Vis Spectroscopy Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with process automation conglomerates bundling spectroscopic hardware alongside flow control systems while pure-play analytical instrument vendors defend position through chromatography-to-spectroscopy workflow integration. The vendor base organizes into three archetypes: diversified automation platforms, dedicated optical measurement specialists, and chromatography-centric analytical workflow providers. Competitive dynamics center on M&A activity targeting fiber-optic probe technology assets and strategic partnerships between spectrometer manufacturers and distributed control system vendors.
Among diversified automation platforms, Endress+Hauser Management AG leverages its process automation installed base to bundle spectroscopic probes with flow control systems. Agilent Technologies, Inc. anchors its position through chromatography-to-spectroscopy workflow integration. Thermo Fisher Scientific Inc. occupies a dominant position in the biopharmaceutical segment with GMP-validated optical train configurations. These three represent distinct competitive vectors: automation bundling, analytical workflow continuity, and regulated industry pre-qualification.
| Leading Market Players |
|---|
| X-Rite |
| Endress+Hauser Management AG |
| Agilent Technologies, Inc. |
| ColVisTec AG Inc. |
| Kemtrak AB |
| Thermo Fisher Scientific Inc. |
| AMETEK, Inc. |
| Guided Wave, Inc. |
| Shimadzu Corporation |
| Others |
Cost & Logistics Intelligence
Fiber-coupled silicon photodiode array adoption is collapsing optical path complexity while simultaneously concentrating procurement power among pharmaceutical and chemical manufacturers capable of absorbing qualification costs. This technology transition compresses margins for legacy scanning monochromator suppliers while elevating pricing power for probe manufacturers with GMP-validated configurations.
Pricing Analysis
Volume concentrates in mid-tier automated configurations while margins pool in premium GMP-validated optical trains with embedded digital twin connectivity. Pricing stratifies across FDA-validated, CE-marked, and non-certified equipment tiers, with certification grade commanding substantial premiums. Cost compression in standard fiber-optic probes is intensifying because Chinese manufacturers are expanding production capacity for silicon photodiode arrays. Contract manufacturing organizations exhibit highest price sensitivity due to program-timeline procurement constraints, while biopharmaceutical innovators show lowest sensitivity given regulatory compliance imperatives.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EU MDR compliance protocols compel manufacturers to qualify multiple suppliers for synthetic sapphire windows and fiber-optic cable assemblies. Production concentrates in Germany, the United States, and Japan for precision optical components, while China dominates silicon photodiode array fabrication. Supply chains draw from high-purity synthetic sapphire, specialty optical fibers, and hermetic sealing materials. Single-source vulnerability sits with synthetic sapphire window suppliers qualified for GMP environments. Distribution runs through process automation distributors and analytical instrument specialists serving regulated industries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with pre-qualified GMP configurations, as EU MDR validation documentation burdens force smaller players into niche non-regulated segments or acquisition targets.
For Market Incumbents: Deploy chromatography-to-spectroscopy workflow integration as the primary defensive lever. Backward integration into fiber-optic probe manufacturing secures supply continuity against sapphire window shortages. Incumbents must simultaneously expand validation support services to capture service-unbundling procurement patterns emerging among United States contract manufacturing organizations. For New Entrants and Emerging Players: The gap between premium GMP-validated systems and economy bench-top units creates entry space for mid-tier automated configurations with modular validation packages. Environmental monitoring applications in Germany and the United States represent the most penetrable vertical given lighter qualification requirements than pharmaceutical segments. A direct-to-end-user digital sales model bypasses entrenched distributor relationships in the process automation channel. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by process automation conglomerates seeking spectroscopic probe technology assets. Long-term viability favors vendors with installed bases in continuous manufacturing retrofits rather than quality control laboratory replacements. The signal to watch is FDA draft guidance on real-time release testing implementation timelines, which would accelerate pharmaceutical capital expenditure cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Fiber-Optic Probe Specialist | Process automation platforms secure PAT-compliant hardware for bioreactor integration. |
| GMP Validation Pre-Qualification Program | Equipment vendors compress pharmaceutical sales cycles under EU MDR documentation rules. |
| Digital Twin Platform Integration | Automated configurations command premium positioning through self-calibration connectivity. |
| Environmental Monitoring Channel Expansion | EPA effluent mandates expand addressable base beyond regulated pharmaceutical segments. |
| Explosion-Proof Housing Certification Investment | Chemical manufacturers in Germany prioritize hazardous-area deployment compatibility. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with bioprocess engineers, GMP compliance officers, analytical instrument procurement managers, and continuous manufacturing specialists. Primary fieldwork validated silicon photodiode array adoption rates and qualification timeline estimates. FDA 483 observations, EMA inspection reports, and SEC equipment supplier disclosures supplemented demand-side calibration. Bottom-up probe shipment estimates triangulated against top-down pharmaceutical capital expenditure patterns.
Data-stream reconciliation across technology deployment surveys, end-user procurement databases, and vendor revenue disclosures shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture tier, end-user regulatory stringency, detector technology type, and application use case. CAGRs derived from fitted growth curves against validated installation bases. Industry-specific inputs encompassed PAT guidance implementation timelines and continuous flow reactor retrofit pipelines.
Inputs from FDA guidance documents and EU MDR technical documentation were available through the study window; gaps in real-time release testing adoption rates at specific biopharmaceutical facilities introduce uncertainty bands around pharmaceutical segment projections. Deviation in synthetic sapphire supply availability or qualification timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Pellistor Bead Chemical Sensor Market
Testing Equipment
Laboratory Filtration Equipment and Supplies Market
Testing Equipment
Electrical Testing Equipment Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Laboratory Centrifuge and Accessories Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
Micro Carbon Residue Tester Market
Testing Equipment
Laboratory Accessories Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Global Residue Testing Market
Testing Equipment
Materials Testing Equipment Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
China Material Testing Market