
 Grease Analyzer Market | 2026-2036
Grease Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Grease Analyzer Market Foresight
Aftermarket service revenue is reshaping competitive economics in the grease analyzer space. Thermo Fisher Scientific leverages its global service infrastructure to capture recurring calibration and maintenance contracts. AMETEK Inc anchors its position through specialized training programs and certified support networks. Spectro Scientific competes by embedding remote diagnostics into its portable analyzer fleet, reducing customer downtime.
A grease analyzer measures lubricant viscosity, contamination levels, and chemical degradation to predict machinery failure and optimize oil change intervals. Benchtop analyzers dominate laboratory settings with precision reaching 0.1% repeatability in kinematic viscosity measurement, while portable units serve field technicians requiring rapid particulate count and moisture detection at mining and marine sites. Online analyzers represent the fastest-expanding segment as continuous monitoring replaces periodic sampling in critical turbine and gearbox applications. The oil and gas end-user category sustains premium pricing due to hazardous-area certification requirements and explosion-proof design standards.
The U.S. EPA enforces used oil management standards that mandate contamination testing before recycling or disposal, directly expanding analyzer deployment at automotive workshops and industrial facilities. ISO 4406 cleanliness codes and ASTM D445 viscosity protocols shape product specifications and create compliance-driven replacement cycles. ASTM International and the International Electrotechnical Commission jointly influence calibration traceability requirements that determine vendor qualification for defense and aerospace procurement. Stakeholders must weigh the capital efficiency of portable units against the data continuity of online installations as plant digitalization budgets tighten.
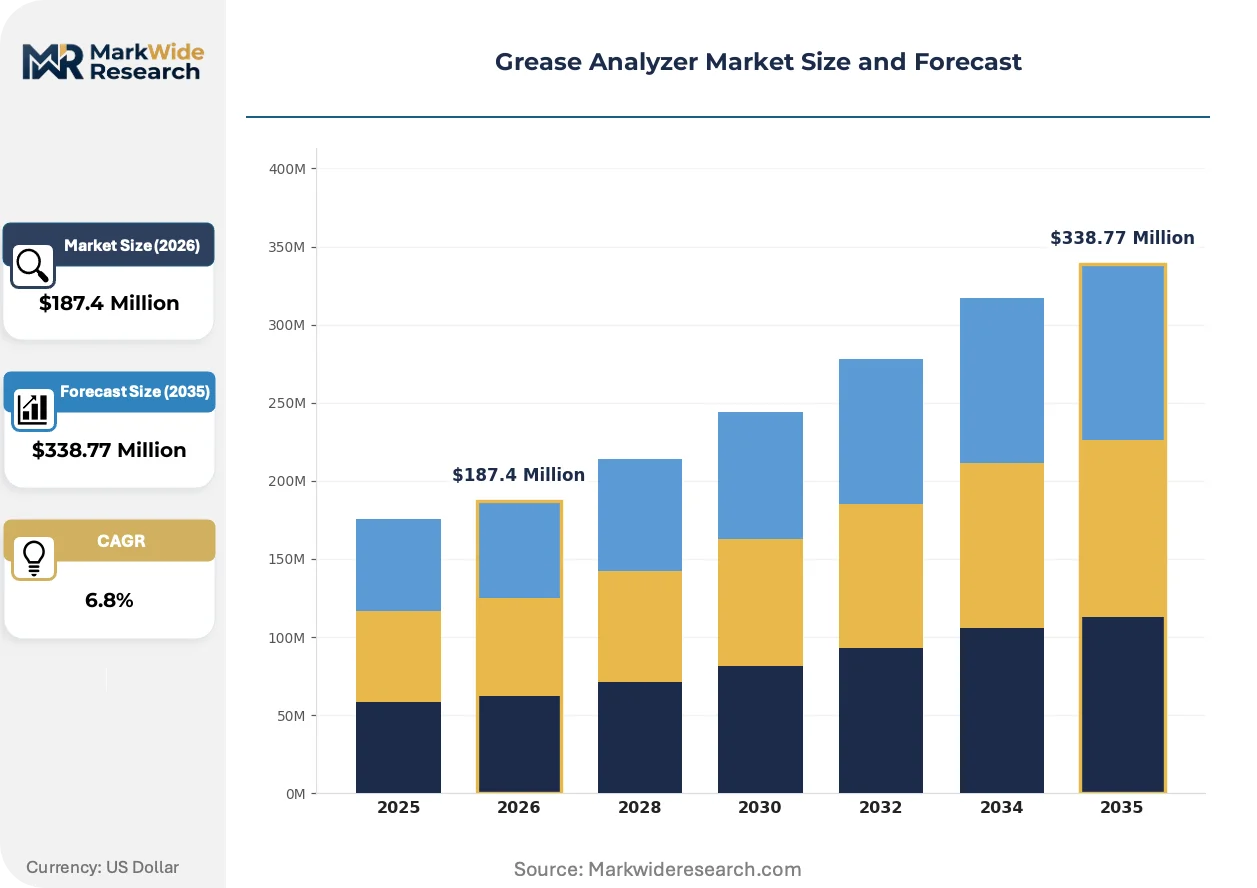
Market Dynamics
Predictive maintenance programs at German automotive plants and Japanese precision manufacturing facilities are accelerating analyzer deployment, while tightening EPA waste oil rules and ISO cleanliness standards force equipment upgrades across North American service workshops.
Growth Catalysts
- EPA Used Oil Management Standards:Mandatory contamination testing before recycling or disposal expands analyzer installation at US automotive workshops and industrial facilities, creating compliance-driven replacement cycles.
- Online Condition Monitoring:Continuous monitoring systems replace periodic sampling in critical turbine and gearbox applications, driving fastest-segment expansion for real-time viscosity and particulate tracking.
- German Automotive Hub Concentration:Manufacturing plants across Stuttgart and Wolfsburg expand predictive maintenance programs, anchoring European demand for high-precision benchtop analyzers.
Market Restraints
- Sensor Input Cost Volatility:Precision optical sensors and MEMS components face supply concentration risk from Asian semiconductor foundries, squeezing margins on portable analyzer production.
- Hazardous-Area Certification Barriers:Explosion-proof design standards for oil and gas deployment create 18-24 month approval timelines, delaying revenue recognition for new product introductions.
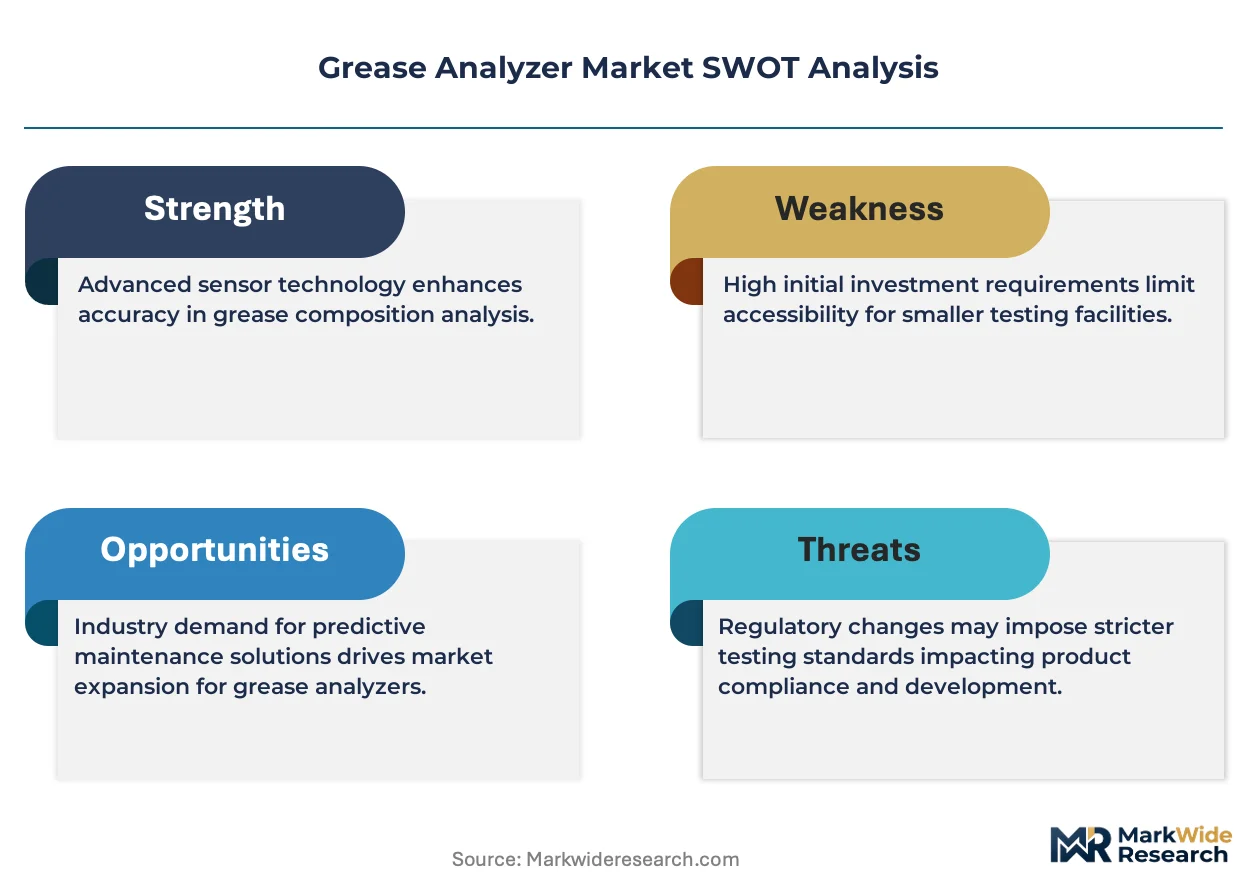
- Laboratory-Grade Substitution:Third-party oil analysis services at centralized laboratories compete for plant budgets, particularly at mid-size facilities without dedicated reliability teams.
Strategic Opportunities
- Indian Manufacturing Corridors:Underpenetrated predictive maintenance adoption at Pune and Chennai automotive clusters creates first-mover advantage for portable analyzer vendors establishing service networks.
- Remote Diagnostics Convergence:Integration of IoT connectivity with portable analyzer fleets enables subscription-based monitoring services, shifting revenue from hardware to recurring software contracts.
- EU Green Deal Alignment:Circular economy mandates for lubricant lifecycle tracking create new application demand for chemical degradation measurement beyond traditional wear metal analysis.
Industry Challenges
- Calibration Technician Scarcity:Specialized training requirements for ASTM D445 viscosity protocol compliance outpace available certification programs, extending deployment timelines at customer sites.
- Legacy System Integration Friction:Online analyzers face protocol incompatibility with existing SCADA infrastructure at aging power generation facilities, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grease Analyzer Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzer, Benchtop Analyzer, Online Analyzer, Laboratory Analyzer End User: Manufacturing Plants, Automotive Workshops, Research Institutes, Oil & Gas Industry Technology: Spectroscopy, Chromatography, Viscometry, Thermal Analysis Application: Quality Control, R&D, Field Testing, Routine Maintenance |
| Companies Covered | Thermo Fisher Scientific, AMETEK Inc, PerkinElmer, Agilent Technologies, HORIBA Scientific, Spectro Scientific, Cannon Instrument Company, Dexsil Corporation, Filtroil, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grease Analyzer Market Shifts & Advancements
Digitalization of maintenance workflows and convergence of field-portable with laboratory-grade precision are redefining equipment specifications, while regulatory fragmentation across jurisdictions forces modular certification strategies.
Multi-parameter MEMS sensors combining viscosity, moisture, and particulate detection in single cartridges are rendering obsolete single-function benchtop instruments that require separate sample preparation. Mining operators in Western Australia and marine technicians in the North Sea adopt these integrated units for rapid field diagnostics. The consolidation is compressing vendor R&D budgets toward unified platforms rather than specialized product lines.
REACH chemical registration requirements in Europe now mandate lubricant composition disclosure for imported equipment, forcing analyzer manufacturers to expand chemical degradation detection capabilities beyond standard wear metal suites. Industrial facilities in the Rhine-Ruhr manufacturing belt face the tightest compliance deadlines. Vendors respond by embedding infrared spectroscopy modules previously reserved for laboratory systems into mid-tier portable units.
Service unbundling now separates hardware procurement from calibration and maintenance contracts, with end-users in the US Gulf Coast petrochemical corridor negotiating multi-year service agreements independent of initial capital expenditure. Distributors lose margin to specialized service providers with certified technician networks. This pattern appears most pronounced at Texas and Louisiana refineries where turnaround schedules demand guaranteed analyzer uptime.
Grease Analyzer Market Segmentation
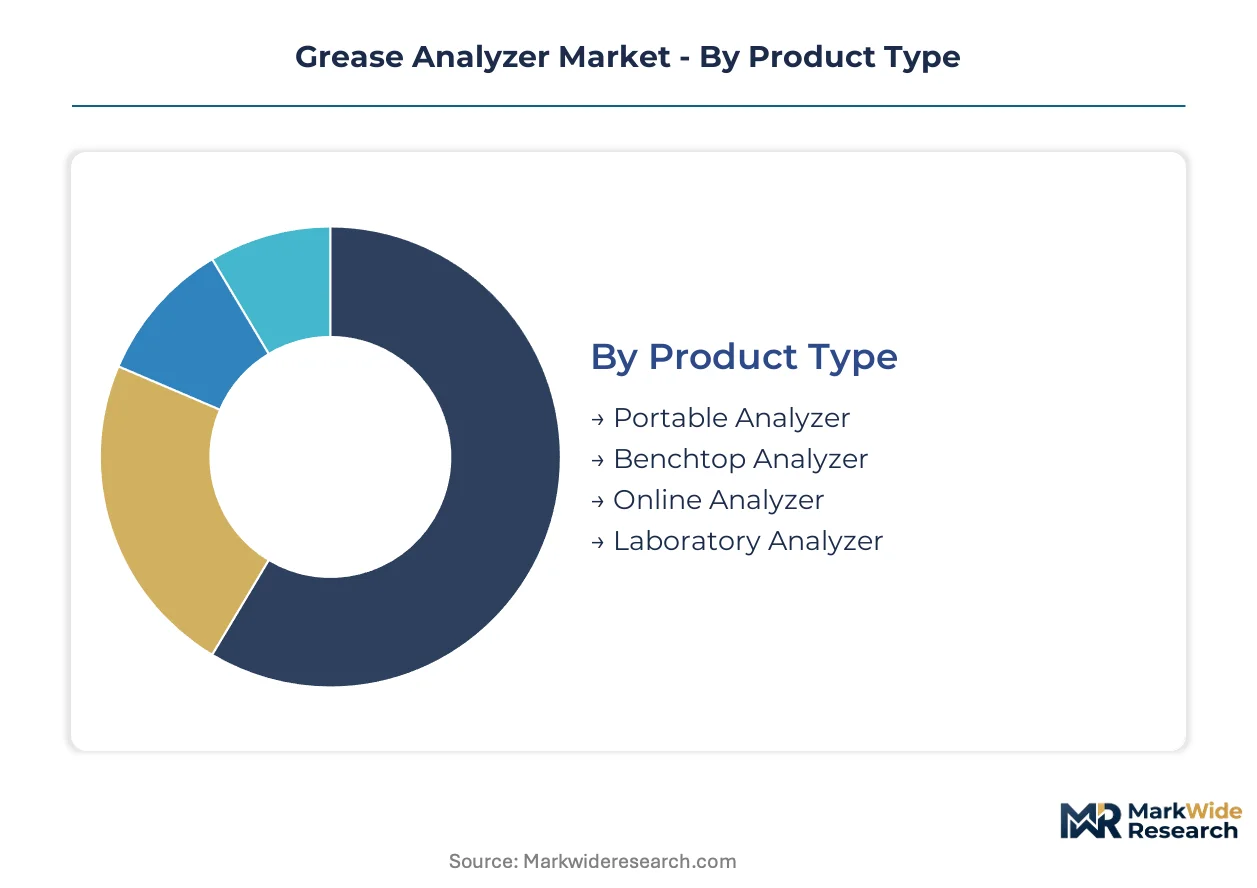
Product differentiation in grease analyzers determines service contract structures and customer lifetime value. Vendors calibrate pricing tiers and support packages around technical complexity, deployment environment, and analytical precision requirements.
Product Type:
After-sales-service intensity varies sharply across product categories, with online analyzers demanding continuous calibration support while portable units rely on episodic field service.
- Portable Analyzer:Compact battery-powered units integrate MEMS sensors for viscosity, moisture, and particulate detection in single cartridges. Mining operators in Western Australia and marine technicians in the North Sea adopt these for rapid field diagnostics where laboratory access is impractical.
- Online Analyzer:Continuous monitoring systems embed directly into turbine and gearbox lubrication loops, transmitting real-time data to plant SCADA infrastructure. These units command premium service contracts due to uptime guarantees required at Texas and Louisiana refineries.
- Benchtop Analyzer:Laboratory-grade precision instruments achieve 0.1% repeatability in kinematic viscosity measurement per ASTM D445 protocols.
- Laboratory Analyzer:Multi-parameter systems combine infrared spectroscopy with chromatographic separation for comprehensive lubricant characterization.
Benchtop analyzers hold the largest share; momentum sits with online analyzers.
End User:
Customer procurement authority shapes vendor engagement models, with centralized reliability teams at manufacturing plants negotiating enterprise frameworks versus transactional purchases at independent automotive workshops.
- Oil & Gas Industry:Downstream refineries and upstream production facilities require explosion-proof designs certified for hazardous-area deployment. The 18-24 month approval timelines for these certifications create sticky vendor relationships and multi-year service agreements.
- Manufacturing Plants:German automotive hubs in Stuttgart and Wolfsburg anchor European demand, expanding predictive maintenance programs that mandate high-precision analytical instrumentation.
- Automotive Workshops:EPA used oil management standards mandate contamination testing before recycling, driving compliance-driven replacement cycles across US service networks.
- Research Institutes:Academic and government laboratories prioritize calibration traceability to ASTM International and IEC standards for defense and aerospace procurement qualification.
Oil and gas sustains premium pricing; manufacturing plants show the steepest expansion trajectory.
Technology:
Technical maturity determines competitive density, with established viscometry methods facing commoditization pressure while spectroscopy platforms command differentiation through chemical degradation detection capabilities.
- Spectroscopy:Infrared and atomic emission modules detect wear metals, oxidation byproducts, and additive depletion. REACH chemical registration requirements in Europe now mandate lubricant composition disclosure, forcing expansion of these capabilities into mid-tier portable units.
- Viscometry:Kinematic and dynamic viscosity measurement remains the foundational analytical parameter, with ASTM D445 protocol compliance determining vendor qualification.
- Chromatography:Gas and liquid chromatographic separation enables detailed additive package analysis and base oil characterization.
- Thermal Analysis:Differential scanning calorimetry assesses oxidation stability and thermal degradation thresholds.
Viscometry holds the largest share; spectroscopy gains share fastest.
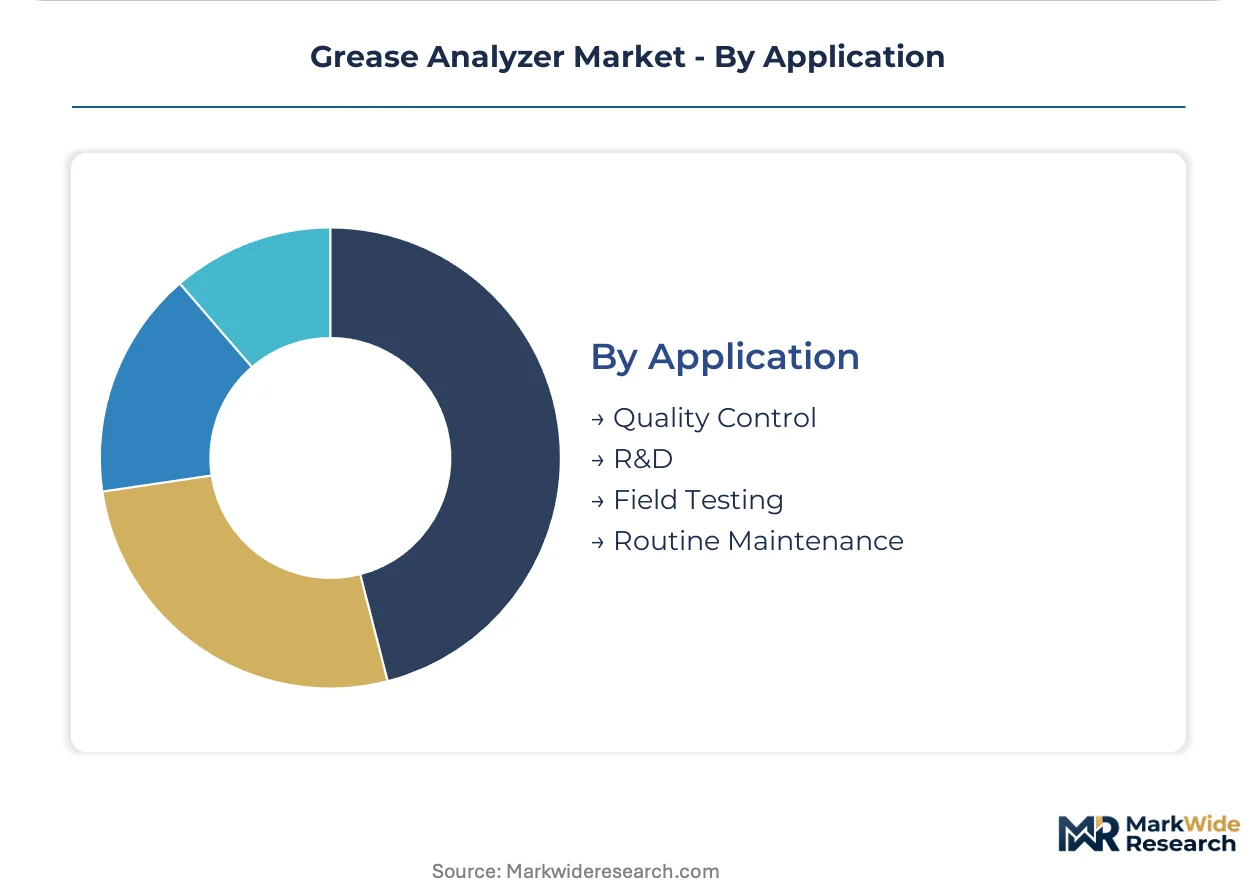
Application:
Workflow integration requirements separate laboratory-centric applications from field-deployable use cases, with quality control demanding documentation rigor and field testing prioritizing speed.
- Quality Control:Incoming lubricant verification and batch release testing require ISO 17025-compliant documentation chains. Industrial facilities in the Rhine-Ruhr manufacturing belt face the tightest REACH compliance deadlines for chemical composition verification.
- Routine Maintenance:Scheduled oil analysis programs at Japanese precision manufacturing corridors optimize change intervals and predict machinery failure before catastrophic damage.
- Field Testing:Rapid diagnostics at remote mining and marine sites prioritize portability over comprehensive analytical suites.
- R&D:Formulation development and additive screening demand method development flexibility and custom protocol capabilities.
Quality control holds the largest share; routine maintenance shows the strongest momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Japanese precision manufacturing corridors demonstrate the lowest price elasticity, absorbing premium benchtop analyzers for predictive maintenance programs, while US automotive workshops face acute cost pressure from EPA compliance mandates without dedicated reliability budgets to match.
United States
Downstream refineries along the Texas and Louisiana Gulf Coast sustain premium analyzer procurement through multi-year service agreements tied to turnaround schedules. EPA used oil management standards mandate contamination testing before recycling, forcing equipment upgrades at independent automotive service networks. Houston petrochemical complexes anchor hazardous-area certified analyzer deployment.
Germany
Automotive manufacturing plants in Stuttgart and Wolfsburg expand predictive maintenance programs, generating concentrated demand for high-precision analytical instrumentation. EU Green Deal circular economy mandates for lubricant lifecycle tracking create new application requirements for chemical degradation measurement. The Rhine-Ruhr manufacturing belt faces REACH compliance deadlines that expand spectroscopy module adoption.
Japan
Precision manufacturing corridors demonstrate lowest price sensitivity globally, purchasing laboratory-grade systems with 0.1% repeatability specifications. METI industrial efficiency programs subsidize condition monitoring infrastructure at machinery-intensive facilities. Nagoya automotive clusters and Osaka industrial zones anchor online analyzer installation for continuous turbine monitoring.
China
State-owned refinery operators in Shandong and Liaoning provinces drive hazardous-area certified analyzer procurement despite extended certification timelines. MIIT equipment reliability standards tighten analytical requirements at steel and cement plants. Yangtze River Delta manufacturing hubs experiment with portable analyzer fleets for distributed maintenance teams.
India
Pune and Chennai automotive clusters present first-mover opportunities as predictive maintenance adoption remains underpenetrated relative to production scale. BIS lubricant quality standards create compliance-driven replacement cycles at commercial vehicle service networks. Gujarat petrochemical complexes import explosion-proof analyzers through specialized distributors.
Grease Analyzer Market Competitive Landscape
Capability concentration sits with laboratory-grade specialists; scale advantage sits with diversified instrumentation conglomerates. The vendor base organizes around three archetypes: diversified analytical platforms with global service infrastructure, specialized lubricant analysis firms with certified technician networks, and component suppliers integrating MEMS sensors into unified cartridges. Competitive moves center on service contract unbundling and remote diagnostics integration.
Within the diversified instrumentation tier, Thermo Fisher Scientific and AMETEK Inc occupy positions defined by global calibration infrastructure and specialized training program scale. Spectro Scientific exemplifies the portable-specialist archetype, embedding connectivity features that enable subscription-based monitoring services. These three companies collectively represent the competitive tension between hardware-centric and recurring-revenue business models reshaping vendor economics.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| AMETEK Inc |
| PerkinElmer |
| Agilent Technologies |
| HORIBA Scientific |
| Spectro Scientific |
| Cannon Instrument Company |
| Dexsil Corporation |
| Filtroil |
| Others |
Supply & Pricing Matrix
Stuttgart's automotive manufacturing corridor concentrates high-precision benchtop analyzer production capacity, with OEM procurement leverage compressing margins on standard-grade portable units while sustaining premium pricing for laboratory-grade systems with embedded spectroscopy modules.
Pricing Analysis
After-sales service revenue drives lifetime value in grease analyzer procurement, with multi-year calibration contracts and certified technician support generating recurring income streams that exceed initial hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates explosion-proof hazardous-area certified systems for Texas refineries from basic portable units for automotive workshops. Price differentiation hinges on ASTM D445 calibration traceability and ISO 17025 documentation rigor. Cost compression in mid-tier portable segments intensifies because MEMS sensor supply concentration from Asian semiconductor foundries squeezes component sourcing budgets. Automotive workshops exhibit highest price sensitivity due to EPA compliance mandates without dedicated reliability capital allocations, while Japanese precision manufacturing corridors demonstrate lowest elasticity.
Supply Chain Analysis
Supplier-financing facilities with extended 90-120 day payment terms have become standard for distributors serving US Gulf Coast petrochemical complexes, easing working capital pressure on hazardous-area certified inventory. Precision optical sensors and MEMS viscosity detection components draw from Taiwan, Japan, and South Korea, with chromatography columns and infrared spectroscopy modules sourced from Germany and the United States. Single-source vulnerability concentrates in MEMS cartridge production for portable analyzer fleets. Distribution runs through specialized analytical instrumentation distributors with certified technician networks, bypassing general industrial supply channels for high-complexity installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as service unbundling separates hardware procurement from calibration contracts, creating niche positions for specialized service providers with certified ASTM D445 technician networks.
For Market Incumbents: Insulate recurring revenue streams by embedding remote diagnostics capabilities into portable analyzer fleets, converting transactional hardware sales into subscription-based monitoring services. Acquire certified technician networks in underpenetrated Indian manufacturing corridors before competitors establish service density. Vertical integration into MEMS sensor cartridge production reduces exposure to Asian foundry supply concentration. For New Entrants and Emerging Players: Build out portable analyzer service networks in Pune and Chennai automotive clusters where predictive maintenance adoption lags production scale. Target research institutes and academic laboratories with calibration-traceable benchtop systems for defense and aerospace procurement qualification. Pursue direct-to-plant sales models bypassing traditional distributor markups at mid-size manufacturing facilities without dedicated reliability teams. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among portable-specialist vendors with IoT-enabled diagnostics platforms, positioning these archetypes for premium valuation multiples relative to hardware-centric competitors. Long-term viability over the analysis window favors vendors with backward integration into MEMS sensor production and established hazardous-area certification pipelines. Monitor EPA enforcement intensity at independent automotive workshops as inflection indicator for compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Diagnostics Platform Development | Shifts revenue from hardware sales to recurring software subscriptions at Texas refineries. |
| Certified Technician Network Expansion | Captures service unbundling opportunities in Indian automotive manufacturing corridors. |
| MEMS Sensor Cartridge Integration | Consolidates multi-parameter detection into unified platforms for Western Australian mining operators. |
| Hazardous-Area Certification Pipeline Investment | Accelerates 18-24 month approval timelines for oil and gas deployment. |
| Spectroscopy Module Miniaturization | Embeds REACH-compliant chemical degradation detection into mid-tier portable units. |
Research Methodology
The analysis maps portable, online, benchtop, and laboratory analyzer sub-sectors, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads at industrial facilities across Germany, Japan, the United States, China, and India. Primary interviews with reliability engineers and calibration technicians combined with secondary validation from ASTM International standards documentation, EPA regulatory filings, SEC 10-K disclosures from diversified instrumentation conglomerates, and customs trade data for precision optical sensor imports. Bottom-up unit deployment estimates triangulated against top-down end-use industry spending patterns.
Assumptions held fixed include EPA enforcement intensity at current levels, ISO 4406 cleanliness code adoption trajectories, and MEMS sensor supply availability from established Asian foundries; variables tested include REACH chemical registration expansion scope and MIIT equipment reliability standard tightening timelines. Segmentation dimensions modeled encompass product type, end-use industry, analytical technology, and application workflow. CAGRs derived from regression analysis of historical deployment patterns against predictive maintenance program expansion rates and regulatory compliance deadline schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified instrumentation conglomerates into subscription-based service models would shift outcomes beyond projected ranges. Macroeconomic contraction in automotive manufacturing, regulatory rollback of used oil management standards, or breakthrough advances in laboratory-grade sensor miniaturization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Leather Testing Machine Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
2D Chromatography Market
Testing Equipment
Material Testing Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Odor Emission Measurement and Dynamic Olfactometry Test Equipment Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Analytical Gel Permeation Chromatography Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Durability Testing Systems Market
Testing Equipment
Gold Purity Tester Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market