
 Global Rheometer and Viscometer Market | 2026-2036
Global Rheometer and Viscometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rheometer and Viscometer Market Foresight
The gap between research-grade oscillatory rheometers and entry-level rotational viscometers is repositioning how vendors allocate engineering resources and service networks. Anton Paar GmbH leverages its Austrian manufacturing base to dominate high-precision rotational systems for polymer labs. Thermo Fisher Scientific sustains broad geographic coverage through its analytical instruments distribution network. Brookfield Engineering Laboratories specializes in benchtop viscometers that anchor quality control workflows across food and paint sectors.
Rheometers and viscometers measure fluid deformation and flow resistance under controlled shear conditions, typically operating across viscosity ranges from 0.1 mPa·s to 10⁹ Pa·s depending on instrument geometry. These instruments enable formulation validation, process control, and material certification in industries where flow behavior determines product performance. Rotational rheometers command premium pricing in academic and polymer research settings where dynamic mechanical analysis capabilities justify capital investment. Capillary viscometers retain strong positions in petroleum testing laboratories governed by ASTM and ISO standardized methods. Vibrational viscometers are gaining traction in inline process monitoring applications where real-time viscosity feedback reduces batch variation.
FDA process analytical technology initiatives and EU MDR conformity requirements are elevating documentation standards for rheological data in pharmaceutical manufacturing. China's NMPA alignment with ICH Q8-Q12 guidelines is creating parallel demand for validated instrumentation in domestic generic drug development. Japan's PMDA emphasizes shear-rate-dependent viscosity profiling for biologic formulations. Stakeholders must weigh capital deployment between modular platforms that span multiple test methods and dedicated instruments optimized for single-application throughput.
Market Dynamics
Modular rheometer architectures are compressing capital cycles as pharmaceutical and polymer labs demand single-platform flexibility across oscillatory, rotational, and capillary test methods. This reconfigurability is forcing vendors to rebalance hardware margins against recurring revenue from application-specific modules and validation services.
Growth Catalysts
- FDA Process Analytical Technology:Updated guidance mandates real-time viscosity monitoring for continuous manufacturing lines, pulling pharmaceutical firms toward validated inline instrumentation.
- Polymer R&D clustering in Shanghai:Petrochemical research centers concentrated around China's industrial corridor are generating concentrated demand for high-shear rheometers.
- EU MDR conformity framework:Medical device manufacturers must document rheological batch consistency, expanding quality control instrumentation budgets across European manufacturing sites.
Market Restraints
- Precious metal sensor costs:Platinum-cobalt torque transducers and tungsten carbide measuring geometries face price volatility from concentrated South African and Russian supply.
- Academic budget fragmentation:Public university capital equipment allocations in Germany and Japan have flattened, stretching replacement cycles for research-grade systems beyond seven years.
- Capillary viscometer lock-in:ASTM D445 and ISO 3104 standardized petroleum testing methods create technical friction against adopting newer rotational or vibrational alternatives.
Strategic Opportunities
- India's generic pharmaceutical expansion:CDSCO alignment with ICH Q8-Q12 guidelines is creating first-time demand for validated rheological instrumentation among domestic formulation developers.
- Biologic shear-thinning characterization:Monoclonal antibody and mRNA vaccine developers require viscosity profiling across temperature ramps, opening specialized module opportunities.
- Cloud-connected calibration networks:Remote diagnostic and automated compliance reporting capabilities are enabling service-contract unbundling and subscription revenue models.
Industry Challenges
- Rheologist talent scarcity:Industrial formulation science programs in the United States and United Kingdom are graduating fewer specialists trained in nonlinear viscoelastic analysis.
- 21 CFR Part 11 validation timelines:Pharmaceutical customers require six-to-nine-month qualification protocols for electronic records compliance, compressing vendor delivery-to-revenue recognition windows.
- Legacy LIMS integration friction:Laboratory information management systems from the 2010s lack native APIs for modern rheometer data streams, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rheometer and Viscometer Market |
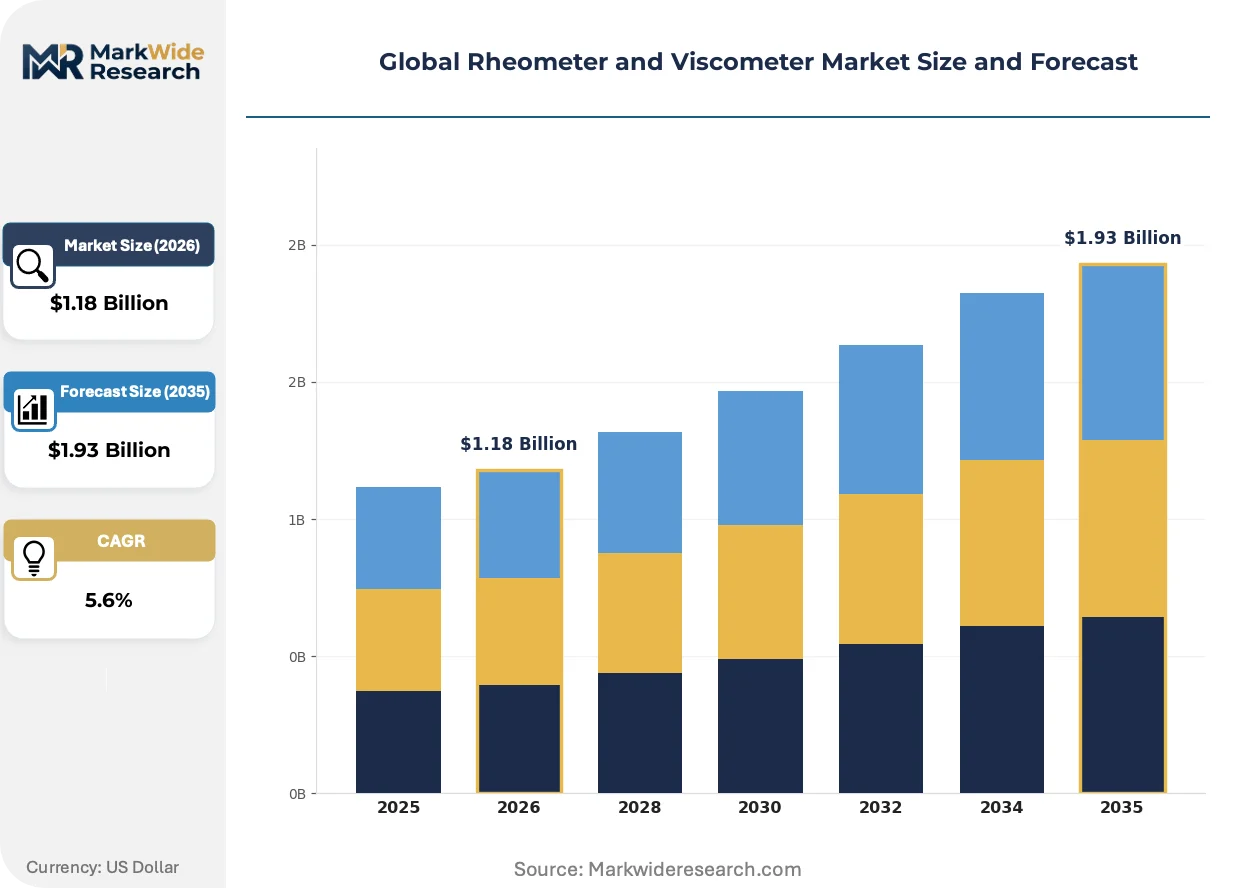
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.93 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotational Rheometers, Capillary Viscometers, Vibrational Viscometers, Falling Ball Viscometers, Oscillatory Rheometers Technology: Shear Rate Control, Dynamic Mechanical Analysis, Torque Measurement, Pressure Drop Analysis, Frequency Sweep Techniques Application: Polymer Characterization, Food Texture Analysis, Paint Formulation, Petroleum Testing, Cosmetic Consistency Measurement End User: Academic Research, Chemical Manufacturers, Quality Control Labs, Food Processing Firms, Material Testing Agencies |
| Companies Covered | Anton Paar GmbH, Thermo Fisher Scientific, Brookfield Engineering Laboratories, TA Instruments, Malvern Panalytical, Spectris PLC, Shimadzu Corporation, Emerson Electric, Cannon Instrument Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rheometer and Viscometer Market Shifts & Advancements
Instrument intelligence and connectivity layers are redefining competitive differentiation as buyers prioritize automated compliance and predictive maintenance over raw measurement precision. Vendors are racing to embed machine learning for anomaly detection and self-diagnostic calibration routines.
Microfluidic rheometry is converging with lab-on-chip fabrication techniques to enable picoliter-scale viscosity measurement for biopharmaceutical formulation screening. Early adopters in Cambridge and Boston biotech clusters are deploying these systems for high-throughput excipient characterization. The technology is converging with existing rotational platforms, pressuring mid-range instrument vendors to defend positioning through service bundling rather than hardware performance alone.
Japan's PMDA has tightened shear-rate-dependent viscosity documentation requirements for biologic drug submissions, effective across all new molecular entity filings. This regulatory compression is elevating demand for instruments capable of continuous shear ramp protocols with temperature control. Domestic Japanese manufacturers and their distributors are responding with localized validation support and Japanese-language compliance software modules.
Buying committees in multinational chemical firms are consolidating vendor relationships to reduce qualification overhead, favoring suppliers with multi-site service networks and interchangeable instrument fleets. Direct sales teams are displacing regional distributors for accounts above defined capital thresholds, most visibly across BASF and Dow formulation laboratories in Ludwigshafen and Midland. This concentration is compressing margins for smaller instrument makers lacking geographic coverage depth.
Global Rheometer and Viscometer Market Segmentation
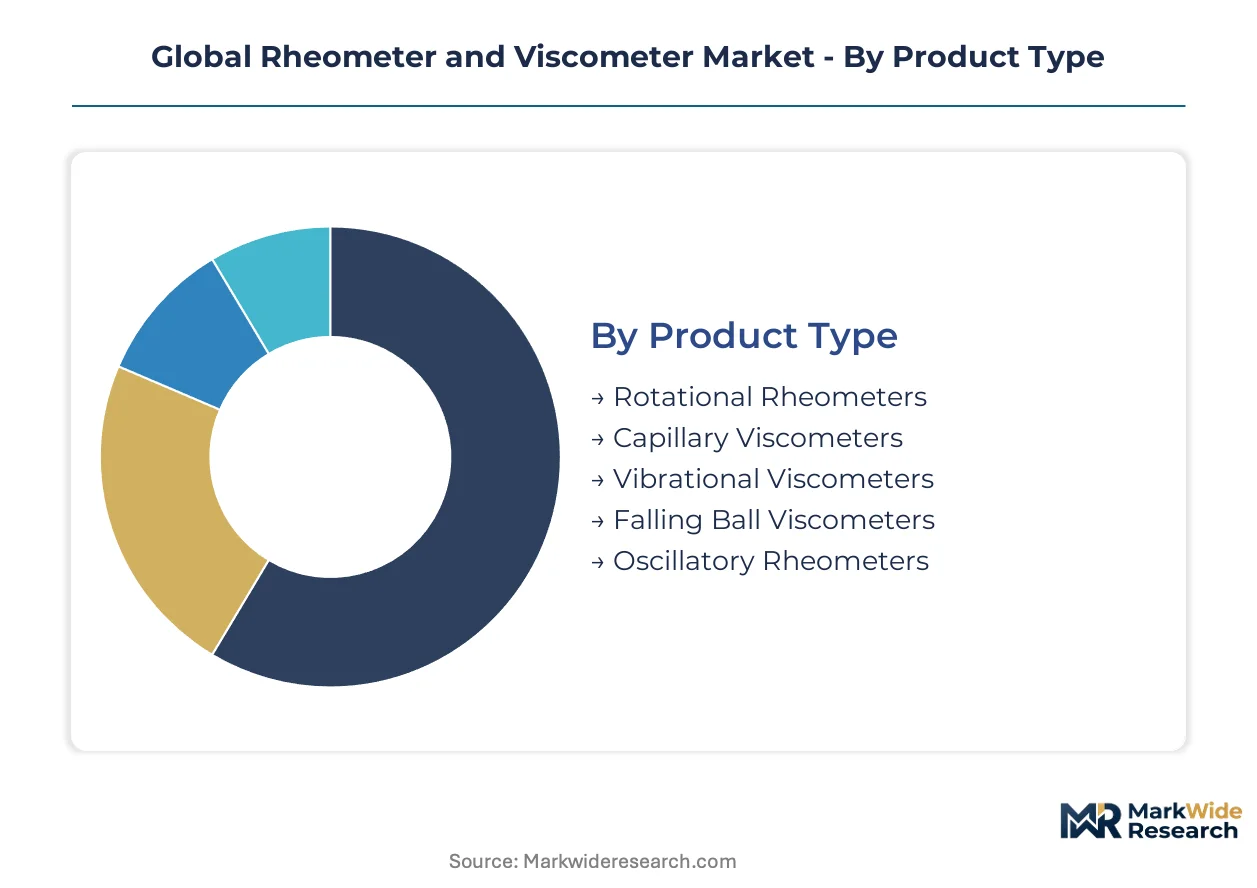
Segmentation in the rheometer and viscometer market reveals distinct capital deployment patterns across product architectures, measurement principles, and end-use workflows. Buyers prioritize instrument flexibility against dedicated throughput depending on regulatory burden and sample volume.
Product Type:
Capital intensity varies sharply across instrument architectures, with research-grade systems demanding five-to-tenfold upfront investment versus benchtop quality control units.
- Rotational Rheometers:These systems apply controlled shear stress or strain to fluids between concentric cylinders or cone-plate geometries, enabling viscosity profiling across broad shear-rate ranges. Pharmaceutical manufacturers in Germany and the United States concentrate demand here for formulation validation under FDA process analytical technology mandates. Premium pricing reflects precision torque transducers and temperature control modules.
- Oscillatory Rheometers:Dynamic mechanical analysis capabilities distinguish these instruments, measuring viscoelastic moduli through small-amplitude oscillatory deformation. Polymer R&D centers around Shanghai cluster procurement for high-shear characterization of petrochemical feedstocks and advanced materials development.
- Capillary Viscometers:Gravity-driven or pressure-driven flow through calibrated capillaries serves ASTM D445 and ISO 3104 standardized petroleum testing. These instruments retain installed base dominance in refinery laboratories despite limited reconfigurability.
- Vibrational Viscometers:Resonant frequency damping principles enable real-time inline monitoring without sample extraction. Food processing firms in Japan deploy these for continuous sauce and dairy viscosity feedback.
- Falling Ball Viscometers:Simple transparent tubes and calibrated spheres deliver entry-level viscosity measurement for educational settings and basic quality screening. Minimal capital requirements sustain niche positioning.
Rotational rheometers absorb the bulk of installed capacity; vibrational viscometers are expanding most quickly through process analytical technology adoption.
Technology:
Measurement methodology determines instrument complexity, with multi-technique platforms commanding premium positioning against single-parameter dedicated systems.
- Shear Rate Control:Precision motor systems maintain defined deformation rates independent of sample viscosity, forming the foundational architecture for rotational rheometry. Quality control labs across chemical manufacturers rely on this stability for batch release documentation.
- Dynamic Mechanical Analysis:Simultaneous storage and loss modulus measurement captures viscoelastic fingerprinting for polymer viscoelastic characterization. Academic research institutions in the United Kingdom prioritize these capabilities for nonlinear material behavior studies.
- Torque Measurement:High-resolution transducer sensitivity defines low-viscosity detection limits and high-viscosity range extension. Platinum-cobalt sensor supply concentration in South Africa creates procurement risk for instrument vendors.
- Pressure Drop Analysis:Differential pressure sensing across defined geometries enables capillary and slit rheometry for high-shear rate petroleum testing. Refinery laboratories maintain standardized protocols around this approach.
- Frequency Sweep Techniques:Time-temperature superposition and master curve generation support polymer viscoelastic modeling. Material testing agencies deploy these for long-term performance prediction.
Shear rate control dominates current installed base; dynamic mechanical analysis is gaining share fastest through polymer research clustering.
Application:
Regulatory documentation requirements fragment demand intensity, with pharmaceutical and medical device applications imposing validation burdens absent in commodity industrial testing.
- Polymer Characterization:Molecular weight distribution inference through zero-shear viscosity and viscoelastic fingerprinting supports petrochemical product development. Shanghai-based R&D centers generate concentrated procurement for high-throughput screening.
- Petroleum Testing:Kinematic viscosity at 40°C and 100°C remains mandatory for lubricant classification and fuel specification compliance. ASTM and ISO standardized methods lock in capillary instrument dominance despite rotational alternatives.
- Paint Formulation:Shear-thinning profile optimization balances application viscosity with sag resistance. Quality control labs at coatings manufacturers in Germany validate batch consistency against specification windows.
- Food Texture Analysis:Mouthfeel engineering through viscosity and yield stress measurement supports product reformulation. FDA and EU regulatory alignment drives documentation standardization.
- Cosmetic Consistency Measurement:Spreadability and stability testing for emulsions and suspensions requires low-torque sensitivity. Formulation developers prioritize portable benchtop units for rapid screening.
Polymer characterization commands the deepest instrument investment per site; food texture analysis is climbing the fastest through clean-label formulation complexity.
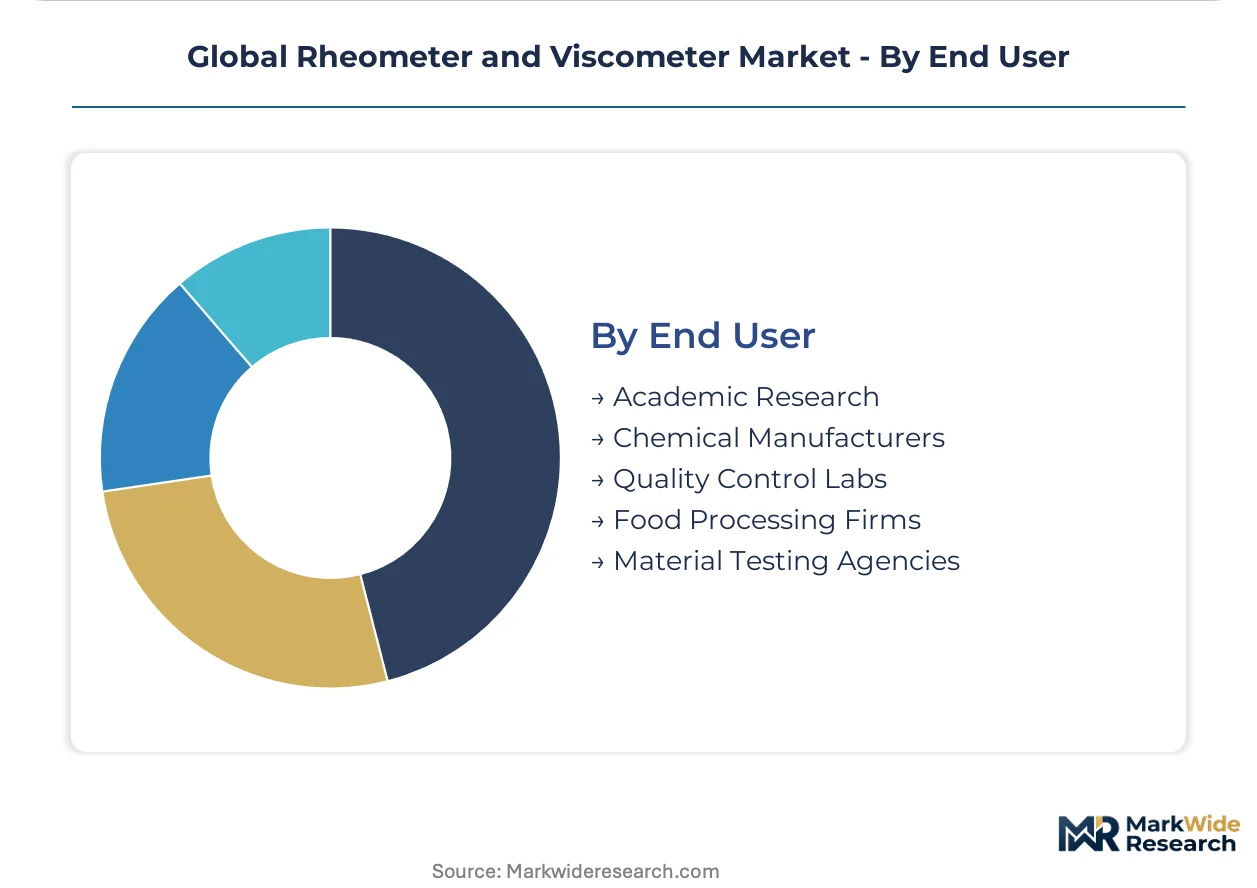
End User:
Procurement authority and qualification timelines diverge across organizational types, with pharmaceutical quality control labs imposing extended validation protocols against academic capital equipment cycles.
- Quality Control Labs:High-sample-throughput environments prioritize reliability and regulatory compliance documentation over measurement sophistication. EU MDR framework expansion is elevating instrumentation budgets across medical device manufacturing sites.
- Academic Research:Grant-funded capital acquisition favors modular platforms spanning multiple test methods. Public university budget flattening in Germany and Japan has stretched replacement cycles beyond seven years.
- Chemical Manufacturers:Formulation science groups require viscosity profiling across temperature and shear ramps for product development. BASF and Dow consolidation of vendor relationships favors suppliers with multi-site service networks.
- Food Processing Firms:Inline process monitoring adoption reduces laboratory sample testing burden. Japanese manufacturers lead deployment of vibrational sensors for continuous sauce and dairy production.
- Material Testing Agencies:Third-party certification laboratories require traceable calibration chains and interlaboratory comparison participation. ISO 17025 accreditation demands drive instrument selection criteria.
Quality control labs represent the largest installed base segment; chemical manufacturers are expanding procurement most steeply through modular platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's industrial corridor anchors concentrated demand for rheological instrumentation, with polymer and petrochemical R&D centers clustering around China's largest chemical manufacturing zone. Germany's Ludwigshafen and Leverkusen chemical complexes sustain parallel procurement intensity for quality control systems. The United States maintains fragmented demand across pharmaceutical hubs in Massachusetts and New Jersey alongside petroleum testing centers in Texas.
United States
Pharmaceutical manufacturers in Massachusetts and New Jersey are expanding quality control budgets for viscosity testing of biologic formulations. The FDA's updated process analytical technology guidelines mandate real-time monitoring for continuous manufacturing lines, pulling firms toward validated inline instrumentation. Houston-area petroleum testing laboratories maintain capillary viscometer dominance under ASTM D445 standardized methods.
Germany
BASF's Ludwigshafen headquarters and Bayer's Leverkusen complex anchor formulation science demand for modular rheometer platforms. The EU MDR conformity framework requires medical device manufacturers to document rheological batch consistency, elevating instrumentation budgets across manufacturing sites. Academic capital equipment allocations have flattened, stretching replacement cycles for research-grade systems beyond seven years.
China
Petrochemical research centers concentrated around Shanghai's industrial corridor generate procurement for high-shear rheometers and oscillatory systems. The NMPA alignment with ICH Q8-Q12 guidelines creates parallel demand for validated instrumentation in domestic generic drug development. State-backed polymer institutes in Beijing and Sichuan are deploying high-throughput screening systems for advanced materials characterization.
Japan
The PMDA has tightened shear-rate-dependent viscosity documentation requirements for biologic drug submissions across all new molecular entity filings. Domestic manufacturers are responding with localized validation support and Japanese-language compliance software modules. Food processing firms deploy vibrational viscometers for continuous sauce and dairy production viscosity feedback.
India
CDSCO alignment with ICH Q8-Q12 guidelines is creating first-time demand for validated rheological instrumentation among domestic formulation developers in Hyderabad and Mumbai. Generic pharmaceutical expansion drives quality control lab instrumentation procurement. Contract research organizations in Bangalore are adopting modular platforms to serve multinational client validation requirements.
Global Rheometer and Viscometer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across instrumentation precision tiers and validation service depth. The vendor base stratifies between Austrian and German precision engineering specialists, diversified analytical instrument conglomerates with broad geographic coverage, and dedicated viscometer fabricators serving quality control workflows. Three strategic archetypes dominate: precision rotational system specialists, modular platform providers spanning multiple test methods, and benchtop viscometer specialists optimized for throughput. Competitive moves concentrate on M&A for geographic coverage expansion and strategic partnerships for cloud-connected calibration networks.
Within the precision engineering tier, Anton Paar GmbH and TA Instruments exemplify capital-intensive positioning anchored by European manufacturing heritage and torque transducer expertise. Thermo Fisher Scientific occupies a position among diversified analytical instrument conglomerates leveraging distribution network breadth. Brookfield Engineering Laboratories represents the dedicated quality control specialist archetype, with Emerson Electric sitting within industrial automation integration. These named entities serve as anchors for industry-level commentary rather than specific competitive positioning claims.
| Leading Market Players |
|---|
| Anton Paar GmbH |
| Thermo Fisher Scientific |
| Brookfield Engineering Laboratories |
| TA Instruments |
| Malvern Panalytical |
| Spectris PLC |
| Shimadzu Corporation |
| Emerson Electric |
| Cannon Instrument Company |
| Others |
Supply & Pricing Matrix
Pharmaceutical quality control labs in Germany and the United States anchor demand for validated rheological instrumentation, locking in value-based pricing models tied to compliance documentation and uptime guarantees rather than hardware specifications alone. This buyer concentration elevates service-contract bundling and validation support as primary price anchors, compressing transactional hardware margins while expanding recurring revenue pools.
Pricing Analysis
Outcome-linked pricing for pharmaceutical manufacturing uptime anchors premium tiers, with FDA 21 CFR Part 11 validation packages and EU MDR conformity documentation commanding substantial premiums over base instrument costs. Price differentiation separates research-grade oscillatory systems with dynamic mechanical analysis capabilities from entry-level rotational viscometers optimized for batch release throughput. Cost compression in the benchtop quality control tier intensifies as Asian manufacturers expand distribution, eroding margins for established players. Academic research institutions exhibit highest price sensitivity due to grant-funded capital cycles, while continuous manufacturing operators in biologics show lowest sensitivity given regulatory non-compliance costs.
Supply Chain Analysis
Direct-to-pharmaceutical channels handle validated instrument demand, with regional distribution partners serving quality control labs below capital thresholds. Manufacturing concentrates in Austria, Germany, and Japan for precision torque transducers and temperature control modules. Platinum-cobalt sensor supply draws from South African and Russian sources, creating single-source vulnerability for high-resolution transducer production. Distribution runs through authorized service networks requiring localized calibration certification, with spare parts logistics anchored in regional hubs to minimize instrument downtime.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA process analytical technology mandates and EU MDR documentation requirements erect substantial barrier-to-entry moats for instrumentation vendors lacking validated service infrastructures.
For Market Incumbents: To counter modular platform encroachment from diversified analytical instrument conglomerates, deepen captive supply of platinum-cobalt torque transducers through backward integration into sensor fabrication. Expand multi-site validation service networks across Shanghai's polymer corridor and India's generic pharmaceutical hubs to capture CDSCO-aligned ICH Q8-Q12 demand. For New Entrants and Emerging Players: Microfluidic rheometry convergence with lab-on-chip fabrication offers a technology-first wedge into Cambridge and Boston biotech clusters for picoliter-scale viscosity screening. Target India's domestic formulation developers in Hyderabad and Mumbai with cloud-connected calibration networks and subscription revenue models that bypass upfront capital barriers. Partner with contract research organizations in Bangalore to serve multinational client validation requirements without direct regulatory qualification overhead. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision rotational system specialists with established FDA master files and EU notified body relationships in Germany and Austria. Long-term viability hinges on service-contract attach rates and recurring validation revenue rather than hardware shipment volumes. Monitor PMDA shear-rate-dependent documentation enforcement as inflection signal for biologic-focused instrumentation demand in Japan.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Networks | Remote diagnostic capabilities enable subscription revenue unbundling from hardware sales for pharmaceutical clients. |
| Modular Platform Expansion | Single-instrument flexibility across oscillatory, rotational, and capillary methods compresses customer capital cycles. |
| Backward Integration into Sensor Supply | In-house production of platinum-cobalt torque transducers mitigates South African and Russian supply concentration risk. |
| Localized Validation Support | Japanese-language compliance software modules address PMDA's tightened biologic submission requirements. |
| Microfluidic Rheometry Development | Picoliter-scale measurement capabilities target high-throughput excipient screening in Boston and Cambridge biotech clusters. |
Research Methodology
Trade publications, regulatory filing databases, and instrument manufacturer technical documentation formed the secondary backbone, cross-referenced against primary interviews with rheology laboratory directors, pharmaceutical quality control managers, polymer R&D leads, and analytical instrument procurement officers. Bottom-up triangulation across installed base estimates and top-down validation through capital expenditure disclosures ensured segmentation integrity. Primary fieldwork captured qualification timeline data and service contract pricing structures unavailable in public disclosures.
Historical instrument shipment patterns and replacement cycle analysis informed projection modeling across the forecast period, with CAGRs derived from regression against pharmaceutical capital expenditure trends and polymer research clustering intensity. Segmentation dimensions spanned product architecture, measurement principle, end-use workflow, and regional regulatory framework. Industry-specific inputs incorporated FDA process analytical technology adoption curves and EU MDR implementation timelines.
Several conditions sit outside the modeled scope, including sudden platinum-group metal price shocks, trade restriction impacts on sensor supply chains, and accelerated academic budget cuts beyond observed flattening. Forecasts reflect documented assumptions around regulatory enforcement continuity and pharmaceutical continuous manufacturing adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Viscometer Market
Testing Equipment
Global Dynamic Mechanical Analyzers Market
Testing Equipment
Global Adsorption Equipment Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Particle Size Analysis Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
HPLC Market
Testing Equipment
In Vitro Toxicity Testing Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
FTIR Fuel Analyzer Market