
 Lubricant Testing Machine Market | 2026-2036
Lubricant Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Lubricant Testing Machine Market Foresight
Automotive OEMs is reorganizing lubricant testing procurement, shifting volume from third-party labs toward captive validation centers at transmission and axle plants. AMETEK Spectro Scientific leverages its embedded oil analyzer architecture to dominate fleet and factory-floor deployments. Koehler Instrument Company anchors North American reference-method compliance through ASTM-calibrated benchtop systems. Anton Paar GmbH differentiates via high-precision rotational viscometry for research-grade formulation work.
Lubricant testing machines measure rheological, tribological, and chemical properties of oils and greases under controlled temperature, load, and shear conditions, typically operating from minus forty to one hundred fifty degrees Celsius with repeatability below one percent. These instruments verify that formulated lubricants meet OEM drain-interval specifications, prevent catastrophic bearing failure, and qualify fluids for electrified powertrains where dielectric properties matter. Automated systems now lead capital expenditure as labor costs and throughput requirements rise, while digital systems with cloud-connected diagnostics represent the fastest-expanding technology tier. Manual systems retain share in emerging-market small-batch labs where capital constraints persist. Among end users, the automotive industry commands the largest installed base, though the aerospace sector generates premium margins due to MIL-PRF specification stringency and low-volume, high-mix testing protocols.
ASTM International and ISO viscosity classification standards shape instrument design and calibration protocols in the United States and European Union, while China's GB standards and NMPA-equivalent metrology rules govern domestic certification requirements. The EPA's used-oil management regulations and REACH substance restrictions indirectly stimulate condition-monitoring test demand by extending fluid service intervals. Stakeholders must weigh capital deployment toward hybrid automated-manual platforms against full digital integration, as customer technical specifications fragment across EV thermal-fluid, hydrogen compressor, and conventional internal-combustion applications.
Market Dynamics
Automotive OEMs are consolidating lubricant validation operations into captive transmission and axle plant laboratories, compressing third-party testing volumes while elevating throughput requirements for automated viscometer and wear testing systems serving electrified powertrain fluid qualification programs.
Growth Catalysts
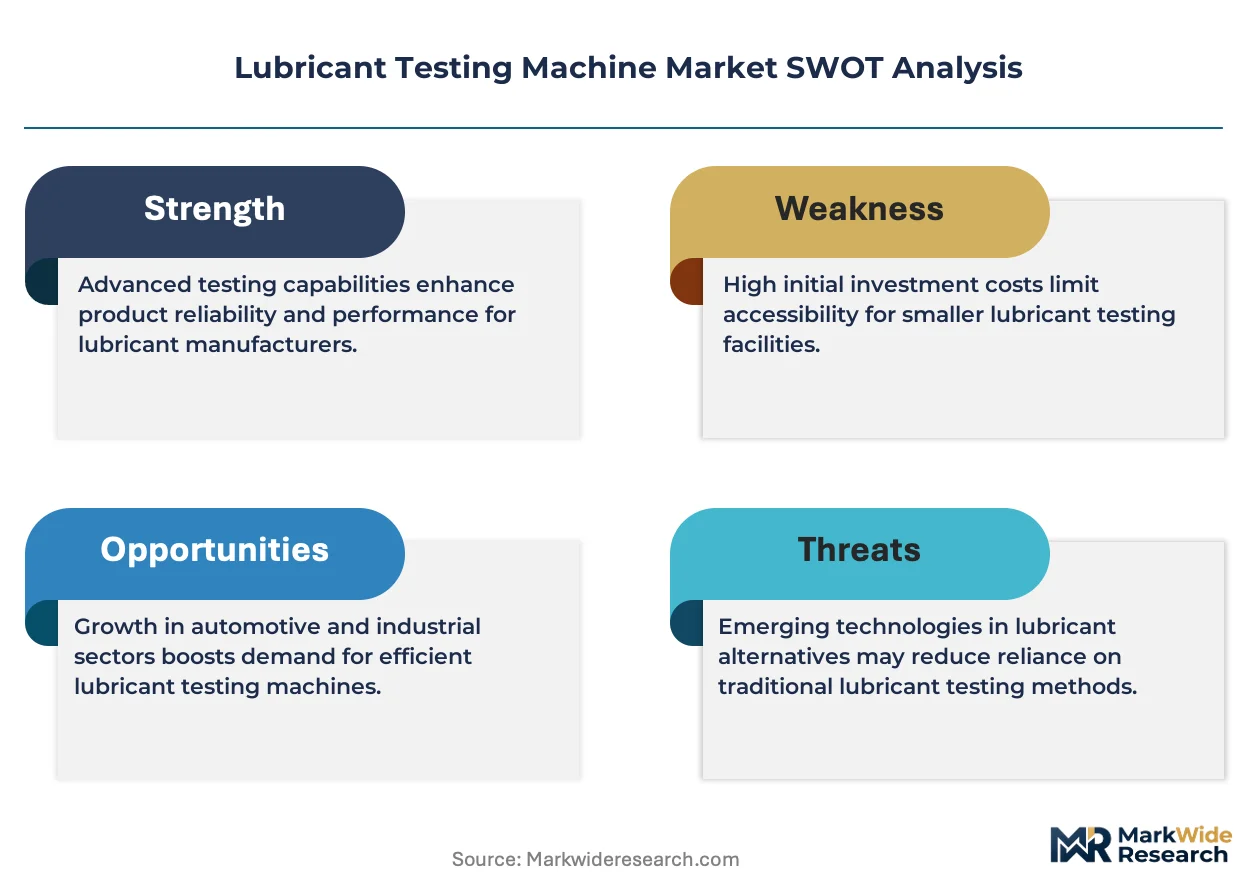
- ASTM D445 and ISO 3104 viscosity standard tightening:North American and European regulators are mandating stricter repeatability thresholds for kinematic viscosity measurement, forcing test lab upgrades and replacement cycles for aging manual capillary systems.
- Electric vehicle thermal fluid qualification:Dielectric property verification for battery coolant and e-axle lubricants requires new test protocols combining rheological and electrical characterization in single automated platforms.
- China's NMPA-equivalent metrology rules:Domestic certification requirements for lubricant testing equipment are accelerating localization demand among multinational instrument suppliers establishing in-country calibration facilities.
Market Restraints
- Precision sensor input cost volatility:Platinum resistance temperature detectors and torque transducers face supply concentration from German and Japanese component specialists, creating margin pressure for system integrators.
- Technical limitation in miniaturization:Portable field-deployable viscometers cannot yet match laboratory-grade repeatability below one percent, constraining adoption in remote mining and marine applications.
- REACH substance restrictions:ECHA chemical hazard classifications are complicating reference oil formulations used for instrument calibration, extending qualification timelines for new test methods.
Strategic Opportunities
- India's PLI scheme for automotive component manufacturing:Domestic transmission and axle production incentives are creating demand for localized lubricant validation infrastructure at tier-one supplier facilities.
- Cloud-connected predictive maintenance convergence:Integration of edge analytics with tribology test data enables real-time fleet oil condition monitoring, opening recurring revenue streams beyond capital equipment sales.
- Hydrogen compressor lubricant testing:Emerging hydrogen infrastructure requires novel fluid formulations resistant to gas solubility and chemical degradation, demanding specialized high-pressure rheometry capabilities.
Industry Challenges
- Tribology and electrochemistry cross-training gaps:EV thermal fluid testing demands personnel proficient in both mechanical wear analysis and dielectric characterization, a combination scarce in traditional lubricant laboratories.
- ASTM method revision synchronization:Proposed updates to D2272 oxidation stability and D4172 four-ball wear protocols create certification uncertainty for equipment already in validation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubricant Testing Machine Market |
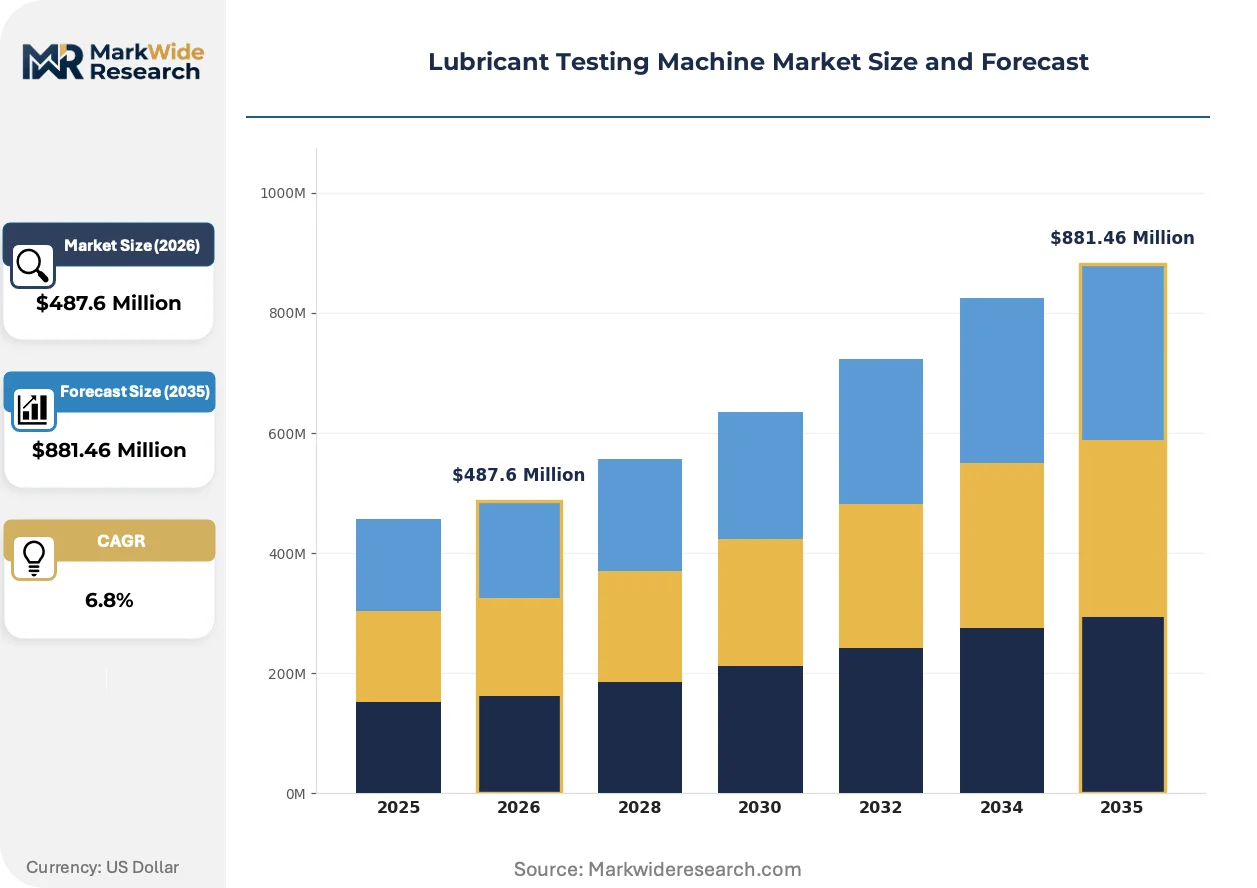
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscometer, Wear Tester, Load Tester, Friction Tester Technology: Automated Systems, Manual Systems, Hybrid Systems, Digital Systems End User: Automotive Industry, Aerospace Sector, Industrial Manufacturing, Oil & Gas Sector Service Type: Calibration Services, Testing Services, Maintenance Services, Consulting Services |
| Companies Covered | Thermo Fisher Scientific Inc., AMETEK Spectro Scientific, Anton Paar GmbH, Koehler Instrument Company, Beckman Coulter, CANNON Instrument Company, Parker Hannifin, Intertek Group Plc, Cole-Parmer Instrument Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubricant Testing Machine Market Shifts & Advancements
Digitalization is penetrating lubricant testing workflows through cloud-native instrument architectures and AI-assisted pattern recognition in wear debris analysis, compressing test cycle times while elevating data interoperability requirements across OEM supply chains.
Automated sample handling robotics is bifurcating the installed base between high-throughput automotive OEM validation centers and lower-volume formulation laboratories. Tier-one transmission plants in Germany and the United States are deploying fully automated viscometer banks processing five hundred samples daily. This technology compression is marginalizing semi-automated platforms that require manual sample transfer, forcing mid-tier equipment suppliers toward either premium full-automation or economy manual positioning.
REACH substance restrictions and the EPA's used-oil management regulations are extending fluid service intervals across commercial fleets and industrial machinery. Extended drain specifications demand more sensitive condition-monitoring test methods detecting incipient lubricant degradation before performance threshold breach. Commercial vehicle operators in the European Union are responding by embedding online particle counters and moisture sensors in hydraulic and engine oil circuits.
Buyer consolidation among automotive OEMs is compressing vendor qualification lists and unbundling after-sales service contracts from capital equipment purchases. Transmission engineering groups at major OEMs now negotiate separate multi-year service agreements with specialized calibration providers rather than accepting bundled manufacturer maintenance. This pattern is most visible in the United States and Germany where centralized procurement functions have absorbed previously decentralized plant-level instrument purchasing authority.
Lubricant Testing Machine Market Segmentation
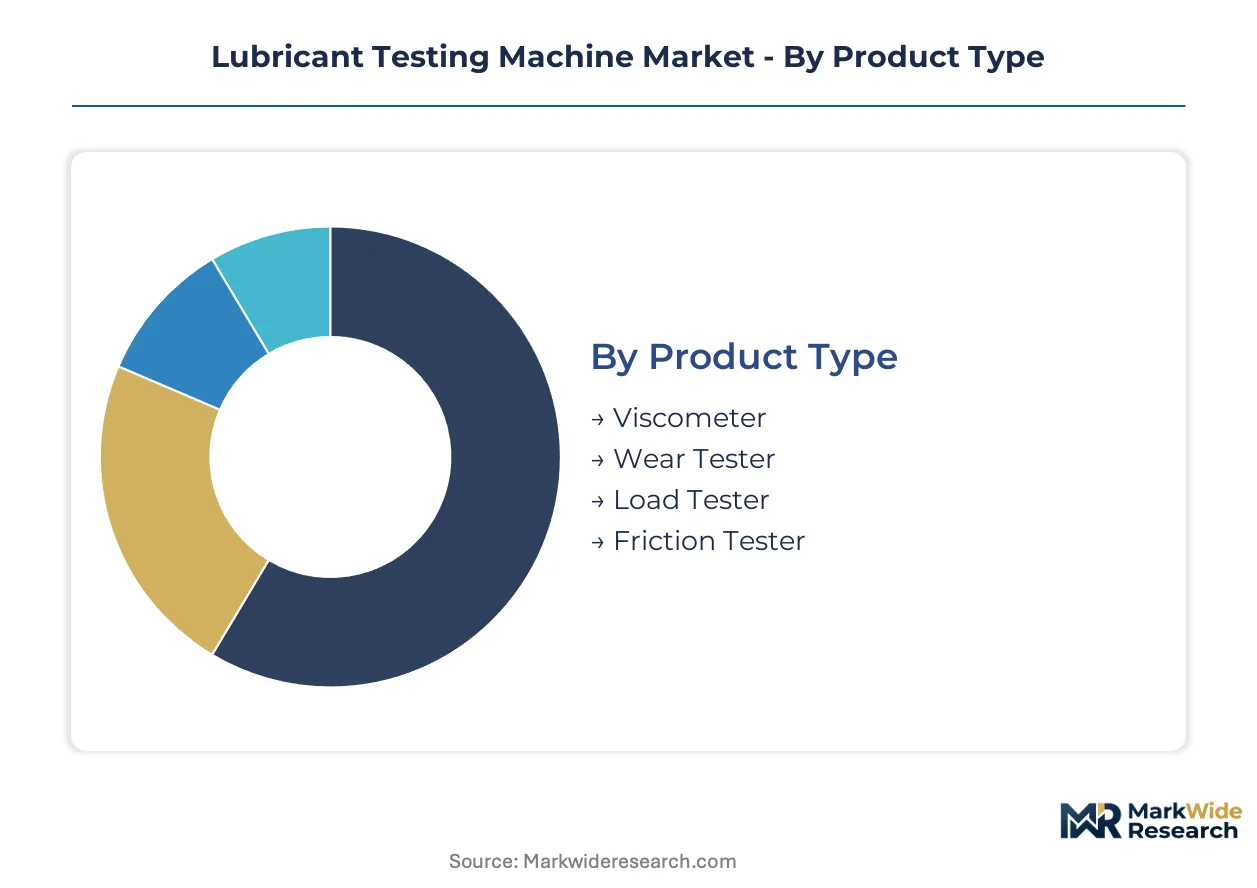
Lubricant testing machine segmentation reveals how equipment specifications fragment across electrified powertrain validation, legacy combustion applications, and emerging hydrogen infrastructure. Procurement patterns diverge sharply between high-throughput automotive OEM captive labs and lower-volume aerospace qualification facilities.
Product Type:
Wear testers face acute substitution pressure from integrated tribology-electrochemistry platforms demanded by EV thermal fluid programs, while standalone viscometers retain defensible positions in reference-method compliance workflows.
- Viscometer:Kinematic and rotational variants dominate ASTM D445 and ISO 3104 compliance workflows. Demand concentrates at automotive transmission plants in Germany and the United States where automated capillary banks process high sample volumes under tightening repeatability thresholds.
- Wear Tester:Four-ball and pin-on-disk configurations measure friction and anti-wear additive performance. Aerospace sector procurement in France and the United Kingdom drives premium specifications under MIL-PRF stringency, though EV fluid qualification is compressing standalone system relevance.
- Load Tester:Extreme pressure and fatigue testing for gear oil formulations.
- Friction Tester:Boundary lubrication characterization for fuel economy certification.
Viscometers anchor the volume base while wear testers gain share at the steepest rate through EV powertrain fluid qualification expansion.
Technology:
Cost tier stratification separates capital-intensive automated installations from constraint-driven manual system persistence in emerging markets.
- Automated Systems:Robotic sample handling and unattended operation define high-throughput validation centers. Tier-one transmission facilities in the United States deploy banks exceeding five hundred daily samples, displacing semi-automated platforms that require manual transfer intervention.
- Digital Systems:Cloud-native architectures with edge analytics enable predictive maintenance convergence. Fleet operators in Japan and South Korea embed these for real-time oil condition monitoring, creating recurring revenue beyond equipment sale.
- Manual Systems:Benchtop reference-method units persist where capital constraints limit automation.
- Hybrid Systems:Intermediate positioning faces margin compression from both full-automation and economy alternatives.
Automated systems command the installed value base while digital systems are expanding most quickly through service revenue attachment.
End User:
Application-driven specification divergence separates automotive volume procurement from aerospace premium-margin requirements.
- Automotive Industry:Transmission and axle plant captive laboratories constitute the largest installed base. OEM consolidation in Germany, the United States, and China is compressing vendor lists while elevating throughput demands for electrified powertrain fluid validation.
- Aerospace Sector:Low-volume, high-mix testing protocols under MIL-PRF specifications generate premium margins. Maintenance facilities in France and the United Kingdom sustain specialized tribology equipment for jet engine oil qualification.
- Industrial Manufacturing:Hydraulic and compressor lubricant monitoring across process industries.
- Oil & Gas Sector:Drilling fluid and pipeline lubricant characterization for upstream and midstream operations.
Automotive industry deployment anchors the volume base while aerospace sector applications command the steepest premium expansion trajectory.
Service Type:
Customer type evolution is unbundling after-sales contracts from capital equipment purchases, reshaping service revenue capture.
- Calibration Services:ASTM and ISO traceable verification maintains measurement integrity. Centralized procurement functions in Germany and the United States now negotiate multi-year agreements with specialized providers rather than accepting manufacturer-bundled maintenance.
- Testing Services:Third-party validation faces volume compression as OEMs consolidate captive capabilities.
- Maintenance Services:Predictive service models leverage cloud-connected diagnostics.
- Consulting Services:Method development support for novel EV and hydrogen fluid protocols.
Calibration services retain the recurring revenue base while testing services face structural displacement from captive laboratory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's lubricant testing machine distribution network, connecting ASTM-calibrated equipment manufacturers to Central European automotive plants. This maritime infrastructure underwrites the region's dominance in high-throughput validation system deployment.
United States
Automotive OEM captive laboratories in Detroit and Ohio process over five hundred daily samples through automated viscometer banks. EPA used-oil management regulations extend fluid service intervals, forcing upgrades to sensitive condition-monitoring equipment. Tier-one transmission plants in Michigan and Indiana now deploy cloud-connected diagnostic systems for real-time fleet monitoring.
Germany
REACH substance restrictions complicate reference oil formulations for instrument calibration, extending qualification timelines at Stuttgart-area tribology centers. ECHA chemical hazard classifications drive demand for alternative test method development. Bavarian precision engineering clusters supply platinum resistance temperature detectors to domestic system integrators facing margin pressure.
China
NMPA-equivalent metrology rules accelerate localization demand among multinational suppliers establishing in-country calibration facilities. GB standards governing domestic certification reshape instrument design protocols. Yangtze River Delta automotive plants in Shanghai and Jiangsu province consolidate lubricant validation operations from third-party labs to captive centers.
Japan
METI industrial standards align with ISO 3104 viscosity protocols, supporting export-oriented equipment manufacturers in Nagoya and Osaka. JIS certification requirements maintain measurement integrity for domestic automotive OEMs. Chubu region tribology specialists develop dielectric characterization methods for battery coolant qualification in electrified powertrains.
India
PLI scheme incentives for automotive component manufacturing create demand for localized validation infrastructure at tier-one supplier facilities. BIS standards adoption accelerates among domestic laboratories seeking international accreditation. Tamil Nadu and Maharashtra transmission plants deploy hybrid automated-manual platforms under capital constraints.
Lubricant Testing Machine Market Competitive Landscape
Listed leaders compete with private specialists across precision instrumentation and embedded diagnostics. The vendor base concentrates around three tiers: multinational conglomerates with diversified analytical portfolios, mid-cap specialists focused on reference-method compliance, and regional fabricators serving emerging-market price sensitivity. Strategic archetypes include ASTM-calibrated system architects, cloud-native predictive maintenance platforms, and economy benchtop suppliers. Competitive moves center on unbundling after-sales service contracts from capital equipment and backward integration into sensor component supply.
Within the precision instrumentation tier, Anton Paar GmbH and AMETEK Spectro Scientific exemplify divergent positioning strategies. The Austrian GmbH anchors research-grade formulation work through high-precision rotational viscometry. The US-listed conglomerate occupies a position in fleet and factory-floor deployments via embedded oil analyzer architecture. Koehler Instrument Company represents the reference-method compliance archetype among North American private specialists.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| AMETEK Spectro Scientific |
| Anton Paar GmbH |
| Koehler Instrument Company |
| Beckman Coulter |
| CANNON Instrument Company |
| Parker Hannifin |
| Intertek Group Plc |
| Cole-Parmer Instrument Company |
| Others |
Supply & Pricing Matrix
ASTM D445 and ISO 3104 certification tiers gate both supplier qualification and price differentiation simultaneously, forcing equipment manufacturers to maintain parallel production lines for reference-grade and economy segments while buyers segment procurement across captive validation centers and third-party service providers.
Pricing Analysis
Volume-discount tiering separates enterprise automotive OEM contracts from small-batch formulation laboratory purchases. Pricing stratifies across premium ASTM-calibrated systems, standard ISO-compliant platforms, and economy benchtop units for emerging markets. Cost compression in the economy tier intensifies because platinum resistance temperature detector supply concentrates in German and Japanese component specialists. Fleet operators and commercial vehicle service centers exhibit the highest price sensitivity, while aerospace MIL-PRF qualification facilities accept substantial premiums for low-volume, high-mix testing protocols.
Supply Chain Analysis
Rhine River logistics corridors through Rotterdam and Antwerp underwrite just-in-time delivery of precision sensor components to Stuttgart-area system integrators. Manufacturing draws from German precision engineering clusters for torque transducers, Japanese specialty ceramics for capillary viscometer tubes, and Austrian rotational viscometry expertise. Single-source vulnerability concentrates in platinum resistance temperature detector supply from two German component houses. Distribution runs through direct OEM procurement channels in Germany and the United States, with specialized calibration providers disaggregating from manufacturer-bundled service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle thermal fluid qualification programs are accelerating instrument replacement cycles, creating an early-cycle expansion story as OEMs consolidate captive validation capabilities and compress third-party testing volumes.
For Market Incumbents: Shield installed base positions by embedding cloud-native predictive maintenance architectures that lock in recurring calibration revenue streams. Backward integration into platinum resistance temperature detector supply hedges margin pressure from German and Japanese component concentration. Prioritize ASTM method revision synchronization to capture certification uncertainty among mid-tier competitors. For New Entrants and Emerging Players: Differentiate on dielectric-electrochemistry hybrid platforms for battery coolant qualification, a white-space segment where traditional tribology specialists lack cross-training depth. Target India's PLI scheme beneficiary transmission plants in Tamil Nadu and Maharashtra, where capital constraints favor hybrid automated-manual platforms over full-automation incumbents. Pursue joint development agreements with hydrogen compressor OEMs for high-pressure rheometry capabilities ahead of infrastructure scale-up. For Investors and Strategic Acquirers: REACH substance restriction implementation reshapes the acquisition landscape by extending reference oil reformulation timelines and elevating alternative test method development capabilities. Five-to-ten year viability favors targets with embedded oil analyzer architectures serving fleet condition-monitoring convergence. Watch for ASTM D2272 and D4172 protocol revision finalization as inflection signal for equipment replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Edge analytics attachment creates recurring revenue beyond capital equipment sales at automotive OEM captive labs. |
| Backward Integration into Sensor Supply | In-house production of platinum resistance temperature detectors mitigates margin pressure from German-Japanese component concentration. |
| Joint Venture for Hydrogen Fluid Testing | Specialized high-pressure rheometry capabilities position suppliers ahead of hydrogen infrastructure scaling in Germany and Japan. |
| Geographic Expansion to India PLI Beneficiaries | Hybrid automated-manual platforms address capital constraints at Tamil Nadu and Maharashtra transmission plants. |
| Calibration Service Unbundling | Multi-year agreements with specialized providers capture procurement centralization trends in Detroit and Stuttgart. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with tribology laboratory directors, automotive OEM transmission plant engineers, aftermarket service procurement managers, and precision instrumentation R&D heads; and secondary validation through ASTM method revision documentation, ISO 3104 calibration records, EPA used-oil management regulatory filings, and customs data on platinum resistance temperature detector trade flows. Bottom-up equipment shipment tallies and top-down automotive production capacity modeling were triangulated against OEM captive laboratory expansion announcements.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, technology tier, end-user industry, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical replacement cycle data and electrified powertrain penetration assumptions. Forecast inputs incorporated EV thermal fluid test protocol development timelines and hydrogen infrastructure deployment scenarios.
Material uncertainties — ASTM method revision finalization dates, REACH substance restriction enforcement intensity, and platinum group metal price volatility — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EV powertrain fluid qualification standards and hydrogen compressor lubricant specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
China Material Testing Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Chemical Detection Equipment Market
Testing Equipment
Benchtop Density Meter for Solids Market
Testing Equipment
Test Point Hoses Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Chemisorption Analyzer Market
Testing Equipment
Elemental Analysis Market
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Total Reflection X Ray Fluorescence (TXRF) Spectrometer Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Material Tester Market