
 Paint Tester Market | 2026-2036
Paint Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Tester Market Outlook
Specialized distribution through calibration-certified dealers is rewriting how paint testers reach end users in regulated industries. Elcometer leverages its UK-based manufacturing footprint to sustain direct service relationships with marine coating inspectors across Europe. DeFelsko Corporation anchors its North American position through integrated probe production and domestic calibration laboratories. BYK-Gardner differentiates by controlling color measurement reference standards that downstream competitors must license.
A paint tester is an instrument that quantifies coating properties such as dry film thickness, adhesion strength, gloss, color consistency, and corrosion resistance, typically operating within measurement tolerances of ±1 micron for thickness gauges and ΔE ≤ 0.4 for colorimeters. These devices enable manufacturers to verify that applied coatings meet specified performance criteria before products enter service or final assembly. Dry film thickness gauges occupy the largest installed base due to universal mandate across automotive and shipbuilding inspection protocols, while color measurement instruments command premium pricing from brand-sensitive consumer goods sectors. Electromechanical adhesion testers face substitution pressure from ultrasonic alternatives in thin-film electronics applications where substrate damage must be eliminated.
EPA Method 24 governs VOC content verification in US industrial coatings, compelling manufacturers to validate thinner film applications with higher-precision thickness gauges. REACH restrictions on hexavalent chromium pretreatments in Europe force adoption of alternative coating systems that demand modified corrosion testing protocols under ECHA guidance. China's GB standards for automotive refinish coatings, enforced by SAMR, require documented film thickness traceability. Stakeholders must monitor how evolving dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape instrument specification requirements for coating verification across export supply chains.
Market Dynamics
Calibration-certified distribution networks are consolidating channel power as REACH and EPA Method 24 compliance requirements force end users toward verified instrument sourcing with documented traceability chains.
Growth Catalysts
- Automotive coating protocols:German and Chinese automakers mandate dry film thickness verification at multiple assembly stages, expanding gauge deployment across stamping plants and refinish networks.
- REACH hexavalent chromium restrictions:ECHA-driven substitution of chrome pretreatments requires modified corrosion testing equipment capable of validating alternative coating systems.
- Ultrasonic adhesion testing:Thin-film electronics manufacturers in South Korea and Taiwan adopt non-destructive bond verification for flexible display substrates.
Market Restraints
- Reference standard concentration:Color measurement traceability depends on a handful of German and US national metrology institutes controlling spectral calibration artifacts.
- Probe supply bottlenecks:Electromechanical adhesion tester production concentrates among Japanese precision component suppliers vulnerable to input volatility.
- Ultrasonic substitution ceiling:Thick-film marine and infrastructure coatings exceed ultrasonic penetration limits, preserving mechanical gauge dependence.
Strategic Opportunities
- India automotive refinish expansion:BIS implementation of film thickness documentation requirements for OEM-certified body shops creates first-mover calibration service demand.
- Cloud-connected gauge ecosystems:Real-time thickness data streaming to coating application robots enables closed-loop process control in high-volume automotive lines.
- EU Green Deal embodied carbon tracking:Coating verification instruments gain specification as Scope 3 emissions accounting requires validated film thickness for mass-balance calculations.
Industry Challenges
- Metrology technician scarcity:ISO 17025 calibration competency requirements outpace vocational training output in Eastern European industrial regions.
- Multi-protocol instrument integration:Automotive inspectors face workflow friction combining thickness, gloss, and color data across incompatible manufacturer software platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Tester Market |
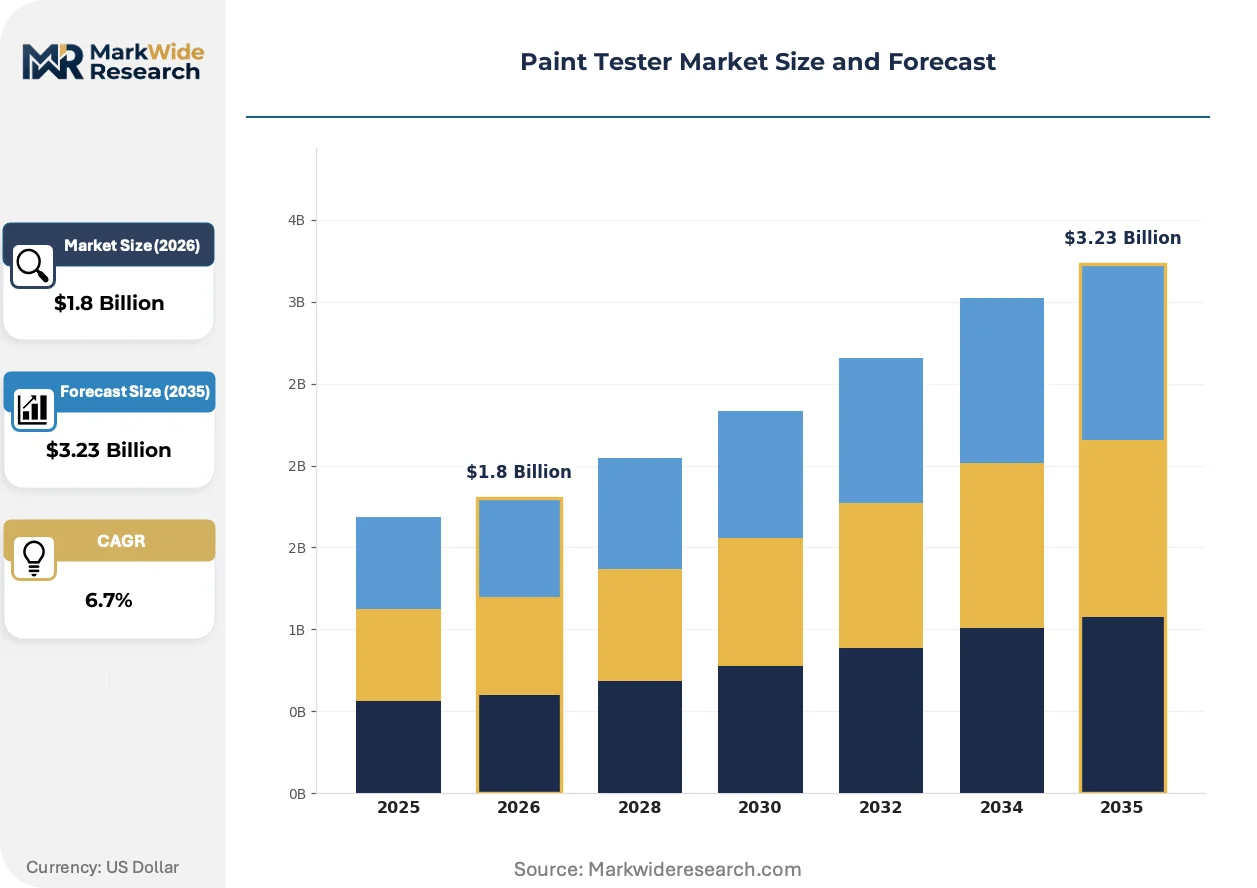
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesion Testers, Dry Film Thickness Gauges, Corrosion Testers, Color Measurement Instruments End User: Automotive Manufacturers, Aerospace Industries, Construction Firms, Paint Suppliers Technology: Infrared, Ultrasonic, Optical, Electromechanical Application: Surface Preparation, Quality Control, Product Development, Research & Development |
| Companies Covered | Elcometer, DeFelsko Corporation, BYK-Gardner, TQC Sheen, Fischer Technology, ElektroPhysik, Erichsen GmbH & Co. KG, Konica Minolta Sensing, Taber Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Tester Market Strategic Shifts
Non-contact measurement modalities and connected instrument architectures are compressing inspection cycle times while elevating data utility for process automation.
Terahertz spectroscopy for multi-layer coating analysis is rendering obsolete destructive cross-section microscopy in aerospace composite qualification. Boeing and Airbus suppliers in France and Germany deploy portable terahertz units for in-situ verification of thermal barrier and anti-icing stacks. The technology eliminates substrate sectioning, cutting qualification time from days to minutes while preserving component integrity.
EPA Method 24 VOC verification protocols are tightening film thickness tolerance windows for compliant coating applications. US industrial finishers must validate thinner films without sacrificing coverage uniformity, driving gauge specification toward ±0.5 micron precision classes. Automotive refinish chains in Michigan and Ohio upgrade inspection stations to meet documented traceability requirements for environmental audit defense.
Certification-driven procurement now dominates regulated industries as SAMR enforcement of GB standards in China and EPA audit activity in North America elevate documented calibration history above unit price in vendor selection. Tier-1 automotive suppliers in Shanghai and Detroit specify instruments with embedded calibration certificate storage and automated due-date alerting. This preference shift compresses sales cycles for factory-authorized distributors while marginalizing gray-market instrument channels.
Paint Tester Market Segmentation
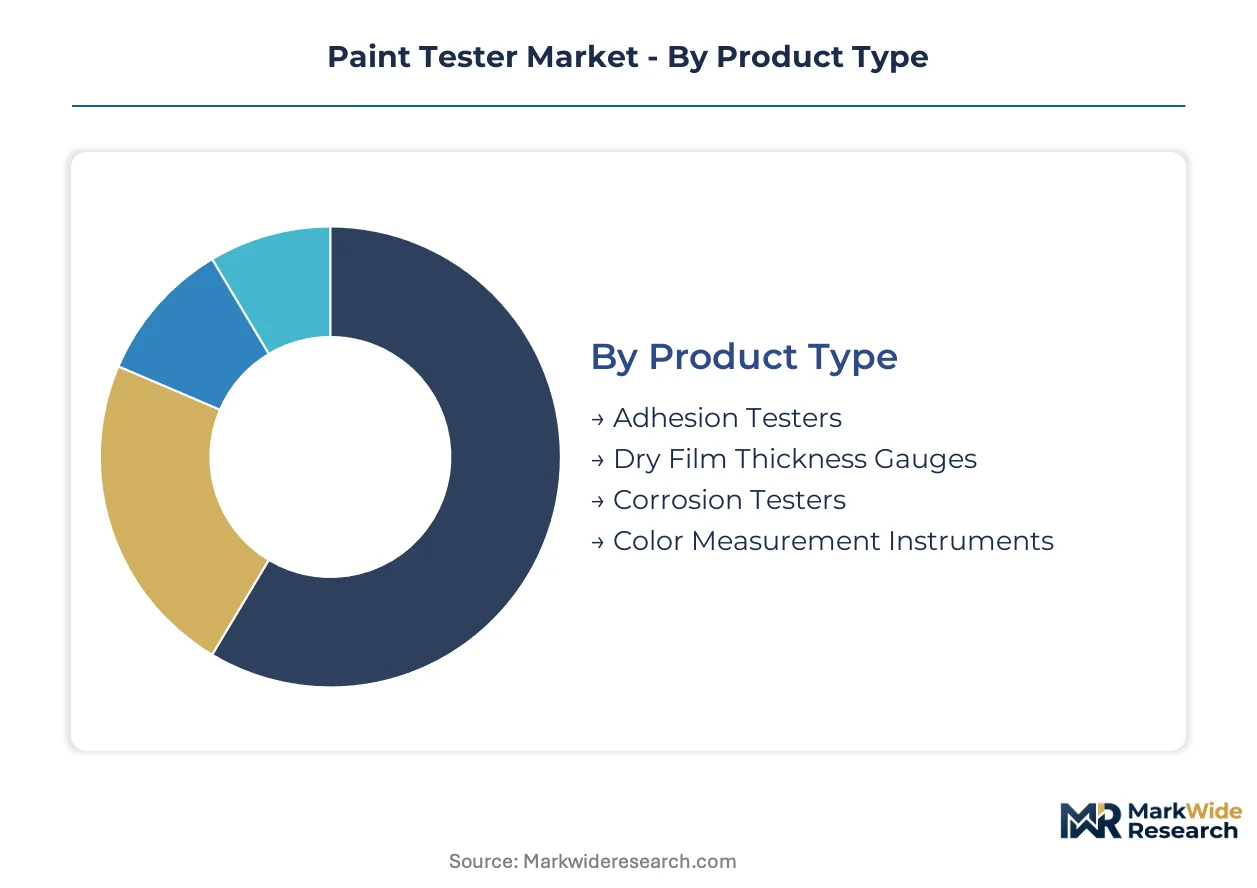
Segmentation in paint testing equipment reveals how calibration complexity and service intensity vary sharply across instrument categories. Procurement patterns diverge between high-frequency automotive production lines and sporadic construction site inspections, reshaping vendor engagement models.
Product Type:
After-sales service intensity distinguishes instrument categories, with calibration frequency and probe replacement cycles determining lifetime revenue capture for distributors.
- Dry Film Thickness Gauges:Electromagnetic and eddy-current sensors measure coating depth on ferrous and non-ferrous substrates with ±1 micron repeatability. German automotive stamping plants and Chinese refinish networks deploy thousands of units under mandatory inspection protocols, generating recurring calibration revenue streams.
- Adhesion Testers:Electromechanical pull-off devices and ultrasonic bond verification systems quantify coating-substrate integrity. South Korean flexible display manufacturers drive ultrasonic adoption to eliminate substrate damage during thin-film electronics qualification.
- Corrosion Testers:Salt spray cabinets and electrochemical impedance spectroscopy units accelerate coating degradation assessment. ECHA restrictions on hexavalent chromium pretreatments force European coaters to validate alternative systems with modified test protocols.
- Color Measurement Instruments:Spectrophotometers and colorimeters enforce ΔE ≤ 0.4 tolerance for brand-sensitive consumer goods packaging. Premium pricing reflects captive reference standard licensing from German and US national metrology institutes.
Dry film thickness gauges hold the largest share; momentum sits with adhesion testers as ultrasonic technology penetrates electronics manufacturing.
End User:
Cost tier stratification separates capital-intensive automated inspection from portable field verification, with aerospace and automotive commanding specification premiums over construction.
- Automotive Manufacturers:Stamping plants, assembly lines, and refinish networks mandate multi-stage thickness verification under OEM quality systems. German and Chinese automakers specify cloud-connected gauges for real-time data streaming to coating robots.
- Aerospace Industries:Boeing and Airbus suppliers deploy terahertz spectroscopy for non-destructive multi-layer stack analysis on thermal barrier coatings. French and German composite manufacturers cut qualification cycles from days to minutes.
- Construction Firms:Infrastructure and marine contractors rely on mechanical gauges for thick-film inspection where ultrasonic penetration fails. Field durability requirements prioritize ruggedized housings over laboratory precision.
- Paint Suppliers:Formulation laboratories use comprehensive instrument suites for product development and customer technical support. Certification documentation for EPA Method 24 and REACH compliance drives specification investment.
Automotive manufacturers dominate procurement volume; aerospace industries exhibit the steepest expansion trajectory as terahertz adoption accelerates.
Technology:
Application environment dictates modality selection, with substrate material and coating thickness defining ultrasonic, optical, or electromechanical suitability.
- Ultrasonic:Non-destructive bond and thickness measurement for thin-film electronics and delicate substrates. Taiwanese display panel producers eliminate mechanical probe damage during flexible OLED qualification.
- Electromechanical:Pull-off adhesion testing remains standard for thick-film marine and infrastructure coatings. Japanese precision component suppliers concentrate probe production, creating supply vulnerability.
- Optical:Spectrophotometric color measurement and gloss assessment for surface appearance verification. Reference standard traceability concentrates among German and US national metrology institutes.
- Infrared:Thermal imaging for coating uniformity and cure monitoring in industrial finishing operations. Integration with automated process control systems expands in high-volume automotive lines.
Electromechanical technology retains the largest installed base; ultrasonic modalities are gaining share fastest in electronics manufacturing applications.
Application:
Customer type segmentation separates production-line volume purchasers from laboratory specification buyers, with divergent software integration and data management requirements.
- Quality Control:In-process and final inspection for coating thickness, adhesion, and appearance verification. EPA Method 24 enforcement in Michigan and Ohio drives documented traceability upgrades at automotive refinish chains.
- Surface Preparation:Pre-coating substrate assessment and cleanliness verification per ISO 8501 standards. Marine coating inspectors in European shipyards specify calibration-certified instruments for specification compliance.
- Product Development:Formulation screening and performance benchmarking for new coating system introduction. REACH-driven substitution of chrome pretreatments accelerates alternative system validation cycles.
- Research & Development:Advanced materials characterization and novel measurement methodology investigation. Terahertz spectroscopy development for aerospace composite qualification originates in French and German research institutes.
Quality control commands the dominant revenue share; research and development exhibits the most rapid technology adoption curve as terahertz and connected instrument architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany's automotive testing corridor while Chinese industrial coating hubs compete on calibration service density. This asymmetry shapes instrument procurement patterns across export supply chains.
Germany
Automotive OEMs in Stuttgart and Munich mandate dry film thickness verification at multiple stamping plant stages. ECHA REACH restrictions on hexavalent chromium pretreatments force coaters in Bavaria to validate alternative systems with modified corrosion protocols. The Baden-Württemberg automotive testing corridor generates concentrated demand for calibration-certified instruments with documented traceability chains.
China
Industrial coating hubs in Shanghai and Shenzhen drive volume procurement for refinish network expansion. SAMR enforcement of GB standards for automotive coatings requires documented film thickness traceability across OEM-certified body shops. Yangtze River Delta manufacturing clusters specify cloud-connected gauges for real-time data streaming to coating application robots.
United States
Automotive refinish chains in Michigan and Ohio upgrade inspection stations for EPA Method 24 VOC compliance defense. EPA audit activity elevates documented calibration history above unit price in vendor selection criteria. Detroit-area Tier-1 suppliers specify instruments with embedded calibration certificate storage and automated due-date alerting.
South Korea
Flexible display manufacturers in Gyeonggi Province adopt ultrasonic adhesion testing to eliminate substrate damage during thin-film electronics qualification. METI-aligned quality protocols drive specification of non-destructive bond verification systems for OLED panel production. Seoul Capital Area electronics clusters represent the fastest-growing demand center for ultrasonic modalities.
India
BIS implementation of film thickness documentation requirements for OEM-certified body shops creates first-mover calibration service demand. Maharashtra and Tamil Nadu automotive manufacturing zones drive procurement of electromagnetic and eddy-current sensors for ferrous substrate inspection. Pune and Chennai industrial corridors exhibit accelerating gauge deployment under emerging quality system mandates.
Paint Tester Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in probe production and reference standard licensing. The vendor base organizes around calibration-certified distribution networks rather than manufacturing scale alone. Two strategic archetypes dominate: UK and German manufacturers leveraging direct service relationships with marine and automotive inspectors, and North American producers anchoring positions through integrated probe production and domestic calibration laboratories. Competitive moves concentrate on geographic expansion of authorized distributor networks and technology licensing agreements for spectral reference standards.
Within the European calibration-service tier, Elcometer and ElektroPhysik exemplify platform integrators sustaining direct relationships with marine coating inspectors across European shipyards. DeFelsko Corporation anchors the North American component-specialist position through integrated probe production and domestic calibration laboratory infrastructure. BYK-Gardner occupies a distinctive reference-standard tier, controlling color measurement artifacts that downstream competitors must license for traceability compliance.
| Leading Market Players |
|---|
| Elcometer |
| DeFelsko Corporation |
| BYK-Gardner |
| TQC Sheen |
| Fischer Technology |
| ElektroPhysik |
| Erichsen GmbH & Co. KG |
| Konica Minolta Sensing |
| Taber Industries |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors shape cost dynamics for German and UK instrument manufacturers, compressing margins on calibration-certified units while amplifying price premiums for ISO 17025-traceable configurations. Supply concentration in Japanese probe production and German reference standard licensing feeds downstream differentiation between commodity gauges and specification-grade systems.
Pricing Analysis
The customization-premium spread separates configured-to-order terahertz spectroscopy units from standard electromagnetic thickness gauges. Tiered pricing stratifies across certification-grade, standard, and economy levels, with ISO 17025 traceability commanding substantial premiums over factory-calibrated alternatives. Cost compression in the economy tier intensifies as Chinese manufacturers scale eddy-current sensor production. Automotive OEM procurement teams exhibit the least price sensitivity due to audit defense requirements, while independent refinish shops face acute margin pressure.
Supply Chain Analysis
Upstream feedstock dependencies center on precision ferrite cores from Japan, spectral calibration artifacts from Germany and the United States, and rare-earth magnets from China. Component sourcing concentrates in Japan, Germany, and China, with probe assembly anchored in Japanese precision manufacturing clusters. Single-source vulnerability in ultrasonic transducer ceramics threatens supply continuity for non-destructive testing modalities. Distribution runs through factory-authorized calibration laboratories rather than traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where regulatory entrenchment protects incumbent positions. ISO 17025 certification requirements create switching costs that lock end users into established service relationships.
For Market Incumbents: Entrench calibration service density in automotive corridors before ultrasonic substitution accelerates. Deepen backward integration into probe production to offset Japanese supply vulnerability. Expand cloud-connected gauge ecosystems to capture real-time data streaming revenue from coating robot integrations.
For New Entrants and Emerging Players: India's Maharashtra and Tamil Nadu automotive zones offer underpenetrated calibration service demand as BIS documentation requirements take effect. Target first-mover positioning in ultrasonic adhesion testing for flexible display manufacturers. Pursue licensing partnerships with German metrology institutes for spectral reference standard access.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial instrumentation parents where paint testing represents non-core revenue. Long-term viability hinges on regulatory compliance automation rather than hardware commoditization. Watch for EPA audit activity intensity as the inflection signal for calibration service valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Network Expansion | ISO 17025 accreditation in Shanghai and Detroit secures automotive OEM specification lock-in. |
| Terahertz Spectroscopy Platform Launch | Boeing and Airbus supplier qualification in France and Germany accelerates aerospace penetration. |
| Cloud-Connected Gauge Ecosystem | Real-time thickness data streaming to coating robots enables closed-loop process control. |
| Reference Standard Licensing Agreement | Access to German metrology institute artifacts secures color measurement traceability compliance. |
| Ultrasonic Transducer Joint Venture | Taiwanese display panel partnerships reduce substrate damage risk in flexible OLED qualification. |
Study Parameters
A spread of perspectives from calibration laboratory directors, automotive quality engineers, marine coating inspectors, and metrology equipment procurement managers converged on the working assumptions. Primary field engagement combined with secondary validation against customs trade data, SEC instrument manufacturer filings, and national metrology institute certification records. Bottom-up gauge shipment estimates and top-down coating industry spend analysis were triangulated to constrain variance.
Demand-supply-balance modeling across the projection horizon incorporated product type segmentation by measurement modality, end-user industry verticals, technology platform maturity, and application workflow integration. CAGRs were derived from instrument replacement cycle analysis and regulatory mandate implementation timelines. Specific inputs included EPA Method 24 enforcement trajectory and ECHA hexavalent chromium restriction phase-out schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese sensor manufacturers or terahertz platform specialists would shift outcomes. Cross-checking against automotive OEM capital expenditure disclosures and shipyard newbuild order books is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
FTIR Fuel Analyzer Market
Testing Equipment
Water Testing Equipment Market
Testing Equipment
Rubber Testing Equipment Market
Testing Equipment
Liquid Chromatography Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
Abrasion Tester Market
Testing Equipment
Electrical Testing Equipment Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
China Material Testing Market
Testing Equipment
Glass Testing Equipment Market
Testing Equipment
Sample Preparation Market
Testing Equipment
Hydrometer Market
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
Global Liquid Chromatography Systems Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
Global Chromatography Instrumentation Market