
 Hydrometer Market | 2026-2036
Hydrometer Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrometer Market Foresight
Aftermarket calibration service revenue is tilting from instrument sales toward recurring certification contracts across laboratory networks. Anton Paar GmbH leverages its Austrian manufacturing base to dominate high-precision density measurement segments. Mettler Toledo International Inc. sustains broad channel control through direct service teams in North American and European research hubs. Thermo Fisher Scientific Inc. anchors its position via extensive distribution partnerships with university and government laboratory systems.
A hydrometer measures liquid density relative to water through buoyancy displacement, typically employing glass or metal construction with graduated stems reading specific gravity from 0.700 to 2.000. Digital variants incorporate temperature compensation circuits and microprocessor-controlled displays to eliminate meniscus reading errors in quality-critical environments. Glass hydrometers retain cost advantages in educational and routine industrial settings where precision demands remain moderate. Digital hydrometers command premium positioning in pharmaceutical and food safety laboratories requiring traceable documentation. The calibration type dimension reveals factory-calibrated instruments capturing recurring revenue streams through manufacturer-certified recertification programs.
FDA current good manufacturing practice guidelines and EPA water quality monitoring protocols shape instrument accuracy requirements and documentation standards for U.S. deployment. ISO 9001 quality management systems and ISO/IEC 17025 testing laboratory accreditation drive metrological traceability demands across European and Asian commercial laboratories. Stakeholders must weigh capital allocation between expanding digital product portfolios and defending aftermarket service attach rates as procurement patterns shift toward total cost of ownership frameworks.
Market Dynamics
The hydrometer market pivots on a fundamental tension between legacy glass instrumentation and digital density measurement systems, as laboratories recalibrate capital budgets toward connected, traceable devices that satisfy tightening ISO/IEC 17025 documentation requirements.
Growth Catalysts
- ISO/IEC 17025 Accreditation Mandates:Testing laboratories across Germany and France face mandatory recertification cycles that accelerate replacement of analog instruments with calibrated digital alternatives.
- Food Safety Protocols:The FDA's current good manufacturing practice guidelines enforce density verification at multiple production stages, expanding instrument deployment in dairy and beverage processing facilities.
- Buoyancy Sensor Miniaturization:Advances in MEMS-based displacement detection enable handheld digital units that match laboratory precision at substantially reduced footprint and sample volume.
Market Restraints
- Precision Glass Supply Concentration:Borosilicate glass manufacturing clusters in Saxony and Thuringia create geographic single-source vulnerability for conventional hydrometer producers.
- Platinum Resistance Thermometer Costs:Digital units require temperature-compensating sensors whose palladium and platinum content exposes margins to precious metal price volatility.
- Mercury Ban Transition Friction:The EU Mercury Regulation (EU) 2017/852 forces abandonment of reference thermometers, complicating calibration chain traceability for legacy instrument users.
Strategic Opportunities
- India Laboratory Modernization:BIS laboratory recognition programs and CDSCO pharmaceutical testing expansion create first-mover advantage for digital density equipment vendors establishing local service infrastructure.
- Blockchain Documentation Integration:Convergence of IoT-enabled hydrometers with distributed ledger systems enables immutable calibration records that command premium positioning in pharmaceutical audit environments.
- Water Quality Monitoring Mandates:EPA National Pollutant Discharge Elimination System permits increasingly require continuous density monitoring, opening municipal utility procurement channels.
Industry Challenges
- Metrology Technician Scarcity:Specialized competence in buoyancy-based calibration and uncertainty budget calculation remains concentrated among aging practitioner pools in Stuttgart and Berlin precision clusters.
- ISO 17025 Certification Timelines:Accreditation body backlogs extend laboratory recertification from six to fourteen months, delaying instrument upgrade decisions and compressing vendor sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrometer Market |
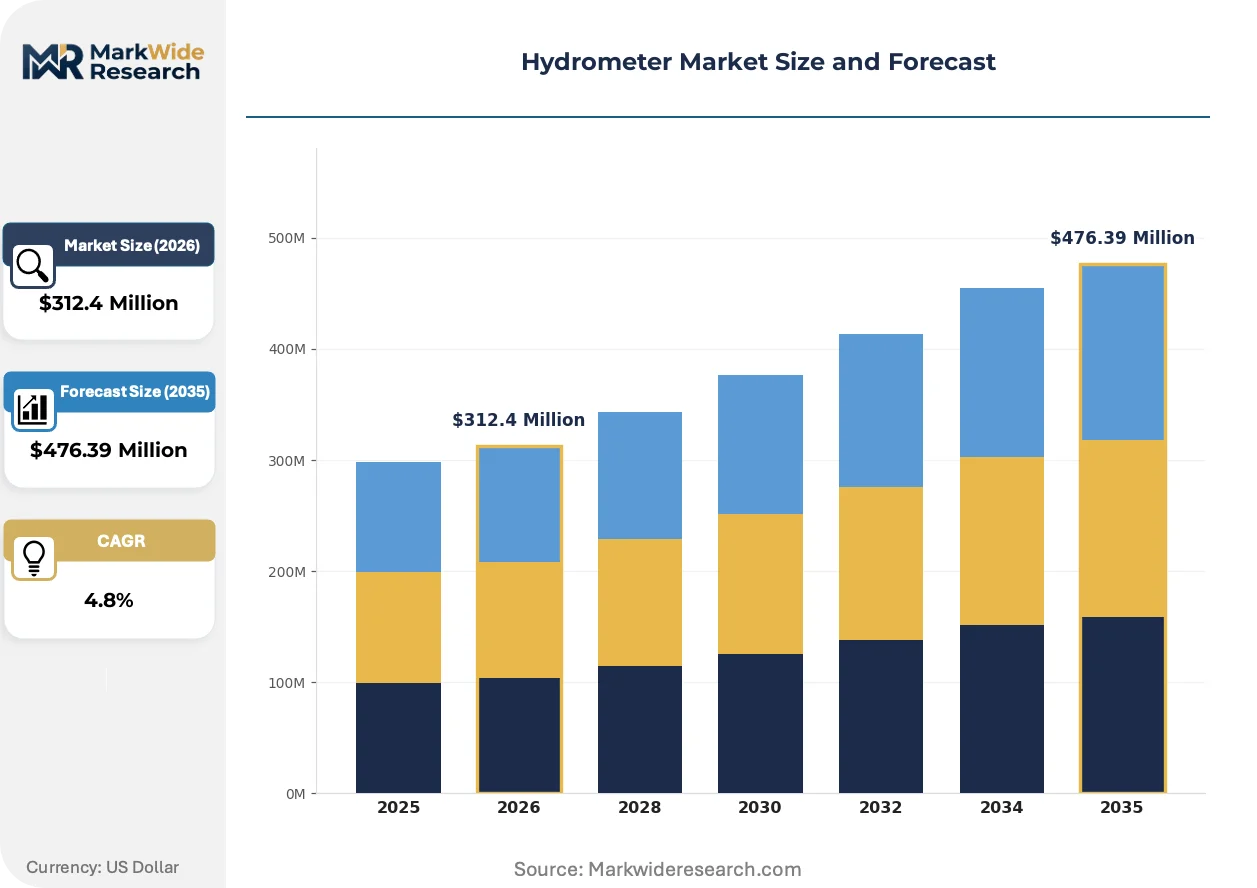
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Hydrometers, Glass Hydrometers, Optical Hydrometers, Portable Hydrometers End User: Laboratories, Food & Beverage Industry, Chemical Industry, Educational Institutions Calibration Type: Factory Calibrated, Field Calibrated, Manual Calibrated, Automated Calibrated Features: Temperature Compensation, High Accuracy, User-Friendly Interface, Bluetooth Connectivity |
| Companies Covered | Mettler Toledo International Inc., Thermo Fisher Scientific Inc., Anton Paar GmbH, Avantor, Inc., Cole-Parmer, Inc., Hach Company, Inc., Hanna Instruments, Inc., Atago Co., Ltd., Koehler Instrument Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrometer Market Shifts & Advancements
Digital transformation is penetrating density measurement instrumentation through three reinforcing vectors: sensor architecture evolution, regulatory documentation digitization, and procurement model restructuring toward outcome-based service frameworks.
MEMS-based oscillating U-tube technology is digitizing liquid density determination by replacing visual meniscus reading with frequency-based mass detection. Pharmaceutical quality control laboratories in Basel and Boston are adopting these units at replacement rates exceeding conventional hydrometer retirement schedules. This shift is compressing the addressable market for glass instrumentation to educational and routine industrial applications where precision demands remain moderate.
The EU In Vitro Diagnostic Medical Devices Regulation (IVDR) imposes Unique Device Identification and post-market surveillance obligations on analytical instruments used in clinical diagnostics. Manufacturers serving European hospital laboratories must reconfigure product architectures to embed serialization and connectivity features. High-precision digital hydrometer lines are absorbing these compliance costs fastest, widening their performance and documentation gap against uncertified imports.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships in North American academic and government laboratory systems. These entities now negotiate enterprise-level calibration service contracts spanning multiple instrument categories, bundling density measurement within broader metrology managed service agreements. The restructuring is most visible across National Institutes of Health-funded research centers, where capital budgets have migrated to operational expenditure frameworks.
Hydrometer Market Segmentation
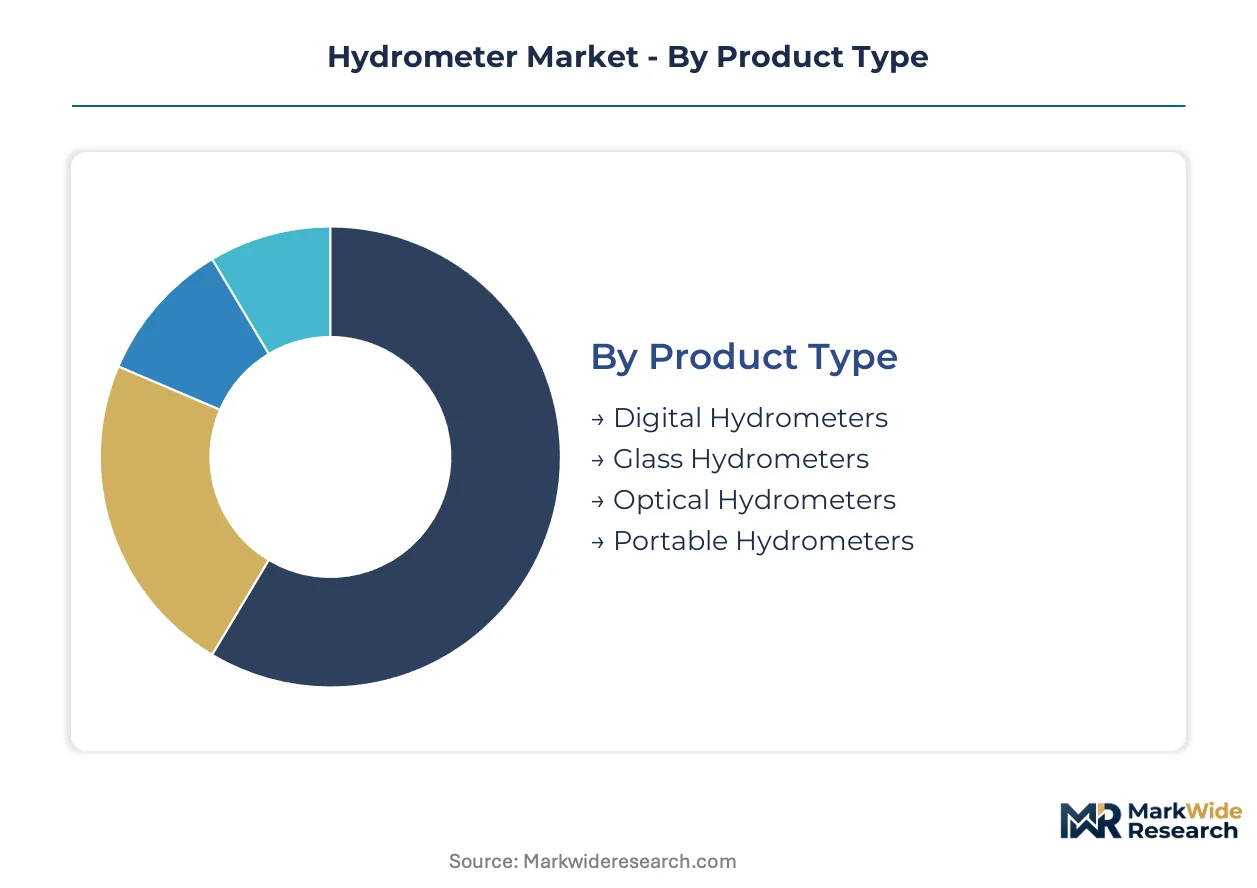
Hydrometer segmentation reveals distinct procurement patterns across precision tiers and operational environments. Laboratories prioritize traceable digital instrumentation, while educational and routine industrial settings sustain demand for cost-effective glass alternatives.
Product Type:
Precision requirements span from educational demonstrations to pharmaceutical quality control, with each product architecture serving defined accuracy and documentation needs.
- Digital Hydrometers:Microprocessor-controlled units with temperature compensation circuits eliminate meniscus reading errors. Pharmaceutical laboratories in Basel and Boston deploy these for FDA-compliant documentation chains. MEMS-based oscillating U-tube variants now match laboratory precision at reduced sample volumes.
- Glass Hydrometers:Borosilicate construction with graduated stems reading specific gravity from 0.700 to 2.000 retains cost advantages. Educational institutions and routine dairy processing facilities in Germany favor these where moderate precision suffices.
- Optical Hydrometers:Refractometry-based density determination serves beverage alcohol content verification.
- Portable Hydrometers:Handheld digital units enable field water quality monitoring under EPA protocols.
The dominant share belongs to Glass Hydrometers, while Digital Hydrometers is closing the gap fastest.
End User:
Budget authority and compliance exposure shape purchasing behavior across institutional categories.
- Laboratories:ISO/IEC 17025-accredited facilities require traceable calibration chains and automated documentation. Stuttgart and Berlin precision clusters concentrate metrology technician competence here.
- Food & Beverage Industry:Dairy and beverage processors face FDA current good manufacturing practice density verification mandates at multiple production stages.
- Chemical Industry:Process control applications demand corrosion-resistant materials and hazardous area certifications.
- Educational Institutions:Physics and chemistry curricula sustain demand for basic glass instrumentation.
Laboratories command premium pricing acceptance, though Food & Beverage Industry procurement volumes are climbing fastest.
Calibration Type:
Service attach rates and recurring revenue potential hinge on calibration methodology selection.
- Factory Calibrated:Manufacturer-certified instruments anchor recurring recertification revenue streams. Anton Paar GmbH leverages its Austrian base to dominate this segment through direct service teams.
- Field Calibrated:On-site adjustment capabilities reduce instrument downtime for continuous process applications.
- Manual Calibrated:Technician-dependent adjustment persists in legacy installations and budget-constrained settings.
- Automated Calibrated:Self-diagnosing units with internal reference standards serve unmanned monitoring stations.
Factory Calibrated instruments capture the largest service contract value, while Automated Calibrated systems are expanding most quickly in utility applications.
Features:
Connectivity and compensation capabilities differentiate premium positioning from commodity alternatives.
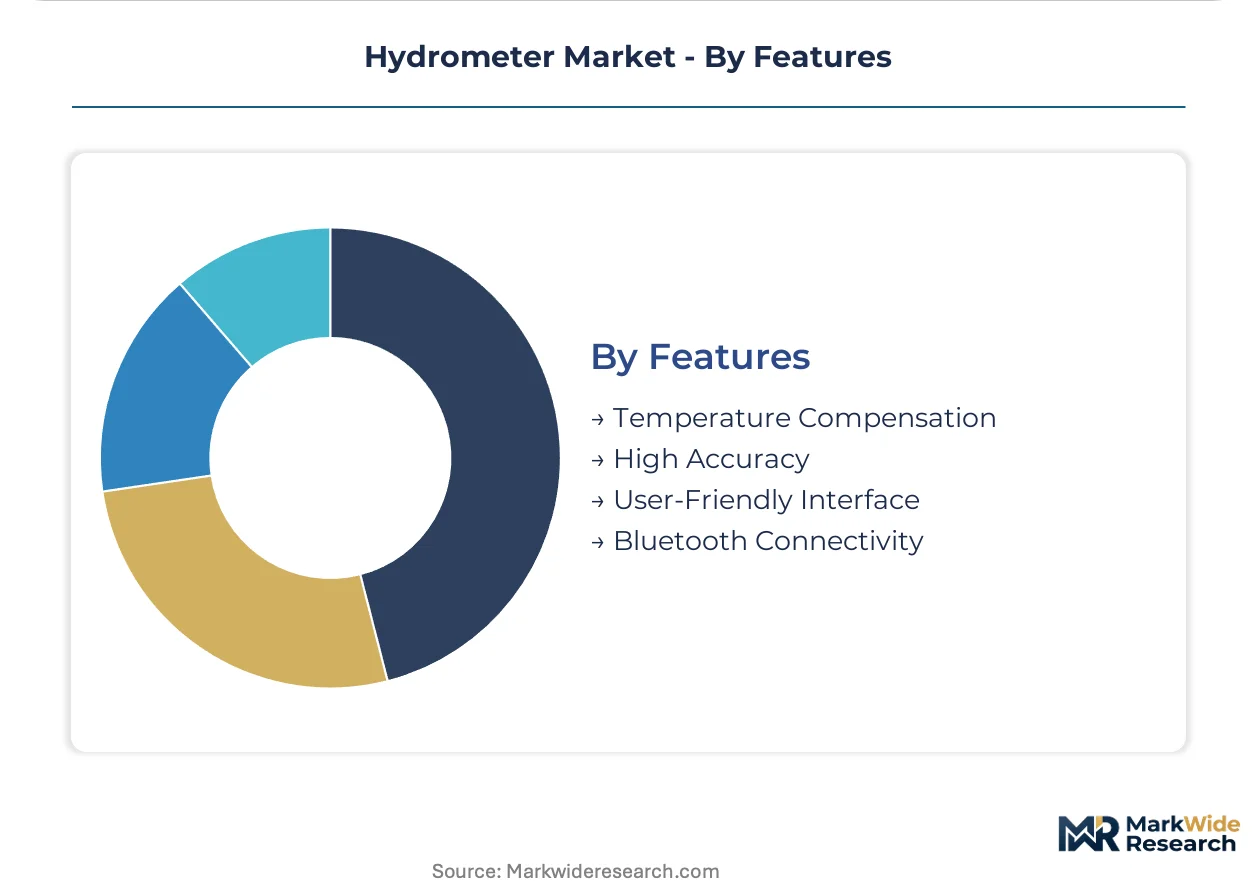
- Temperature Compensation:Platinum resistance thermometer integration corrects density readings across variable thermal conditions. Precious metal content exposes margins to palladium price volatility.
- High Accuracy:Expanded uncertainty budgets below 0.0001 g/cm³ serve pharmaceutical reference standard applications.
- User-Friendly Interface:Touchscreen displays and guided workflows reduce operator training burdens in high-turnover environments.
- Bluetooth Connectivity:Wireless data transmission enables IoT integration and blockchain-anchored calibration records for audit trails.
Temperature Compensation remains the most specified feature, though Bluetooth Connectivity is gaining specification fastest among pharmaceutical procurement teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys hydrometers predominantly within ISO/IEC 17025-accredited pharmaceutical laboratories, whereas India concentrates procurement in food safety and environmental monitoring stations where cost sensitivity shapes instrument selection.
Germany
Pharmaceutical quality control laboratories in Stuttgart and Berlin drive demand for digital density measurement systems with automated documentation. The national accreditation body enforces strict ISO/IEC 17025 recertification cycles that accelerate analog instrument replacement. Precision instrumentation clusters in Baden-Württemberg concentrate metrology technician competence and manufacturer service infrastructure.
United States
FDA current good manufacturing practice guidelines mandate density verification across dairy and beverage processing facilities, expanding instrument deployment. EPA water quality monitoring protocols under the National Pollutant Discharge Elimination System create municipal utility procurement channels. Research hubs in Greater Boston and the San Francisco Bay Area sustain premium pricing acceptance for connected, traceable devices.
India
BIS laboratory recognition programs and CDSCO pharmaceutical testing expansion drive modernization of analytical infrastructure. FSSAI food safety regulations enforce density verification at multiple production stages in dairy processing. Industrial corridors in Maharashtra and Gujarat attract first-mover digital density equipment vendors establishing local calibration service networks.
Japan
METI industrial standards and PMDA pharmaceutical manufacturing guidelines shape instrument accuracy requirements in Osaka and Nagoya pharmaceutical clusters. JIS-certified calibration chains command premium positioning in quality-critical environments. Precision manufacturing heritage in the Chubu region sustains demand for high-reliability measurement instrumentation.
Switzerland
Swissmedic pharmaceutical manufacturing oversight and dual-track apprenticeship systems preserve specialized metrology competence in Basel chemical laboratories. ISO 9001 quality management systems drive traceable documentation requirements across contract manufacturing organizations. The country's precision instrument tradition anchors regional demand for factory-calibrated digital alternatives.
Hydrometer Market Competitive Landscape
Capability concentration sits with Austrian and Swiss precision instrumentation specialists; scale advantage sits with North American diversified laboratory conglomerates. The vendor base organizes around three strategic archetypes: precision-focused European specialists, diversified life science conglomerates with broad channel control, and regional fabrication houses serving cost-sensitive procurement. Competitive positioning hinges on M&A activity consolidating calibration service networks and geographic expansion into Indian and Southeast Asian laboratory modernization programs.
Within the precision-specialist tier, Anton Paar GmbH exemplifies European manufacturing heritage and direct service team deployment. Among diversified life science conglomerates, Mettler Toledo International Inc. and Thermo Fisher Scientific Inc. occupy positions defined by extensive distribution partnerships and enterprise-level calibration contract negotiation. These three entities represent distinct competitive vectors: manufacturing-base proximity to German precision clusters, North American research hub channel density, and university-government laboratory system penetration respectively.
| Leading Market Players |
|---|
| Mettler Toledo International Inc. |
| Thermo Fisher Scientific Inc. |
| Anton Paar GmbH |
| Avantor, Inc. |
| Cole-Parmer, Inc. |
| Hach Company, Inc. |
| Hanna Instruments, Inc. |
| Atago Co., Ltd. |
| Koehler Instrument Company, Inc. |
| Others |
Supply & Pricing Matrix
Borosilicate glass manufacturing clusters in Saxony and Thuringia concentrate upstream capacity for conventional hydrometer production, translating geographic single-source vulnerability into asymmetric pricing power for precision glass suppliers serving Stuttgart and Berlin laboratory networks. This feedstock concentration enables tiered margin extraction across instrument grades, while MEMS sensor miniaturization introduces alternative cost structures that compress pricing premiums for legacy buoyancy-based devices.
Pricing Analysis
Long-term calibration service contracts anchor revenue stability for factory-certified instrument vendors, while spot procurement persists in educational and routine industrial segments where precision demands remain moderate. Price differentiation rests on ISO/IEC 17025 certification tier and after-sales service bundling, with pharmaceutical laboratories in Basel and Boston accepting substantial premiums for traceable documentation chains. Cost compression in glass hydrometer tiers is intensifying because MEMS-based digital alternatives match laboratory precision at reduced sample volumes. Educational institutions exhibit highest price sensitivity, whereas ISO-accredited facilities prioritize total cost of ownership frameworks over unit acquisition cost.
Supply Chain Analysis
Borosilicate glass feedstock draws from Germany, China, and the Czech Republic, with specialty boron sourcing concentrated in Turkey and the United States. Platinum and palladium for temperature-compensating sensors rest on South African and Russian supply chains, exposing margins to precious metal price volatility. Single-source vulnerability in Saxony-Thuringia precision glass clusters creates tariff-immune but logistics-constrained supply risk. Distribution runs through direct manufacturer service teams in European research hubs and consolidated group purchasing organizations across North American academic systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrometer procurement is shifting toward connected-device platforms that integrate calibration documentation with laboratory information management systems, creating interoperability premiums for vendors embedding IoT architectures and blockchain-anchored audit trails.
For Market Incumbents: Harden aftermarket service attach rates by embedding predictive calibration alerts within digital hydrometer firmware, countering displacement from MEMS-based oscillating U-tube substitutes. Deepen backward integration into platinum resistance thermometer supply through long-term offtake agreements with South African refiners, insulating margins from palladium price volatility. For New Entrants and Emerging Players: Establish a beachhead in Indian pharmaceutical testing expansion driven by CDSCO regulatory modernization, where local calibration infrastructure gaps create first-mover advantage for digital density equipment vendors. Target Maharashtra and Gujarat industrial corridors with field-calibrated portable units serving FSSAI dairy verification mandates, leveraging lower certification overhead against entrenched European specialists. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue platform play because ISO/IEC 17025 recertification cycles generate captive demand for manufacturer-certified service contracts spanning instrument lifecycles. Target acquisition archetype: precision instrumentation specialists with dense installed bases in German pharmaceutical clusters and undermonetized calibration attach rates. Monitor BIS laboratory recognition program expansion timelines as inflection signal for Indian market entry valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Documentation Integration | Immutable calibration records command premium positioning in FDA pharmaceutical audit environments. |
| MEMS Sensor Architecture Migration | Oscillating U-tube miniaturization matches laboratory precision while eliminating meniscus reading errors. |
| Indian Calibration Infrastructure Buildout | Local service networks capture CDSCO-driven laboratory modernization in Maharashtra and Gujarat corridors. |
| Platinum Supply Chain Hedging | Long-term precious metal offtakes insulate digital hydrometer margins from South African supply volatility. |
| Group Purchasing Organization Consolidation | Enterprise-level metrology contracts bundle density measurement within NIH-funded research center procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ISO/IEC 17025 accreditation body records, FDA 483 inspection observations, and EPA National Pollutant Discharge Elimination System permit databases. Interviews with laboratory quality managers, metrology technicians in Stuttgart precision clusters, pharmaceutical procurement directors, and aftermarket calibration service heads informed demand-side validation. Trade data from German Federal Statistical Office and Indian Directorate General of Commercial Intelligence supplemented bottom-up instrument shipment triangulation with top-down market sizing.
Forecast inputs span product type evolution from glass to MEMS-based digital architectures, calibration methodology migration from manual to automated systems, and end-user expansion across pharmaceutical quality control and environmental monitoring applications. Segmentation dimensions include precision tier, connectivity features, and regional regulatory cluster intensity. CAGRs were derived through logistic diffusion modeling of analog-to-digital replacement cycles, cross-referenced against ISO 17025 recertification backlog timelines and precious metal price scenario bands.
Stress conditions across platinum supply disruption, EU Mercury Regulation enforcement acceleration, and Indian BIS recognition program delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MEMS cost curves and laboratory accreditation timelines. Cross-checking against Anton Paar and Mettler Toledo public disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Laboratory Ware Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Global Distillate Oil Testing Service Market
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Global Silica Analyzer Market
Testing Equipment
China Material Testing Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Wood Moisture Tester Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Lactose Assay Kit Market