
 Salt Spray Chamber Market | 2026-2036
Salt Spray Chamber Market Size, Share, and Industry Trends Forecast 2026-2036
Salt Spray Chamber Market Analytics
Direct sales from manufacturers to end-users is tilting toward certified distributor networks with regional service capabilities. Weiss Technik anchors European supply through its localized technical support infrastructure. ATLAS (AMETEK) leverages its broad materials testing portfolio to cross-sell corrosion chambers into existing accounts. Q-LAB competes on test consumables bundling, creating recurring revenue attachment to chamber hardware placements.
A salt spray chamber is an enclosed climatic test apparatus that generates a controlled saline fog environment, typically maintaining 35°C chamber temperature and 5% sodium chloride concentration to accelerate corrosion on coated or bare metal specimens. The equipment replicates years of atmospheric exposure in compressed test cycles, enabling manufacturers to validate protective coating durability before product release. Standard chambers dominate current installed base volumes due to their compatibility with universally referenced ASTM B117 protocols, while custom chambers capture disproportionate margin pools from aerospace and defense contractors requiring non-standard specimen geometries. Automated testing features represent the fastest-growing capability segment as quality control labs pursue unattended multi-cycle operation and digital data logging for audit trails.
ASTM International, ISO, and FDA shape product standards and market access through test method harmonization and medical device coating validation requirements. ASTM B117 and ISO 9227 compliance serves as a de facto market entry threshold, with deviations risking disqualification from automotive and aerospace supplier qualification programs. Stakeholders must monitor evolving revisions to salt fog test standards and assess whether existing chamber fleets accommodate modified spray nozzle specifications or updated calibration intervals.
Market Dynamics
Automotive OEMs are tightening corrosion validation protocols, forcing Tier-1 and Tier-2 suppliers to upgrade aging chamber fleets and expand testing capacity ahead of new product qualification cycles.
Growth Catalysts
- ASTM B117 Protocol Harmonization:North American automotive suppliers face mandatory compliance refresh cycles, driving replacement demand for legacy chambers that cannot meet revised calibration intervals.
- Medical Device Coatings:FDA validation requirements for implantable device corrosion resistance are expanding chamber procurement across orthopedic and cardiovascular instrument manufacturers.
- German Automotive Clusters:Dense supplier networks around Stuttgart and Wolfsburg anchor concentrated equipment deployment, with TÜV-certified labs requiring redundant chamber capacity.
Market Restraints
- Stainless Steel Input Volatility:Chamber fabrication depends on 316L and 304-grade steel, with price swings compressing margins for European fabricators.
- Single-Source Nozzle Suppliers:Precision spray nozzle manufacturing concentrates among German and Japanese specialty metalworkers, creating supply vulnerability.
- Test Duration Compression Limits:ASTM B117's 24-hour minimum exposure cannot be shortened without protocol deviation, capping lab throughput regardless of automation.
Strategic Opportunities
- Indian PLI-Linked Manufacturing:India's production-linked incentive scheme for automotive and electronics components is seeding new testing infrastructure demand among export-oriented suppliers.
- Multi-Environment Cycling:Converged chambers combining salt spray with UV and thermal cycling capture aerospace contractor budgets seeking consolidated footprint.
- Remote Monitoring Subscriptions:Cloud-connected chamber telemetry creates recurring revenue streams for equipment vendors serving distributed quality networks.
Industry Challenges
- Metallurgical Technician Scarcity:Interpretation of corrosion rating scales requires trained personnel, with qualified candidates concentrated near legacy automotive hubs.
- ISO 9227 Certification Backlogs:Third-party chamber calibration queues extend 8-12 weeks in peak automotive validation seasons, delaying production releases.
- Legacy Data Migration:Paper-based test logs from pre-digital chambers block audit trail integration with modern LIMS platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salt Spray Chamber Market |
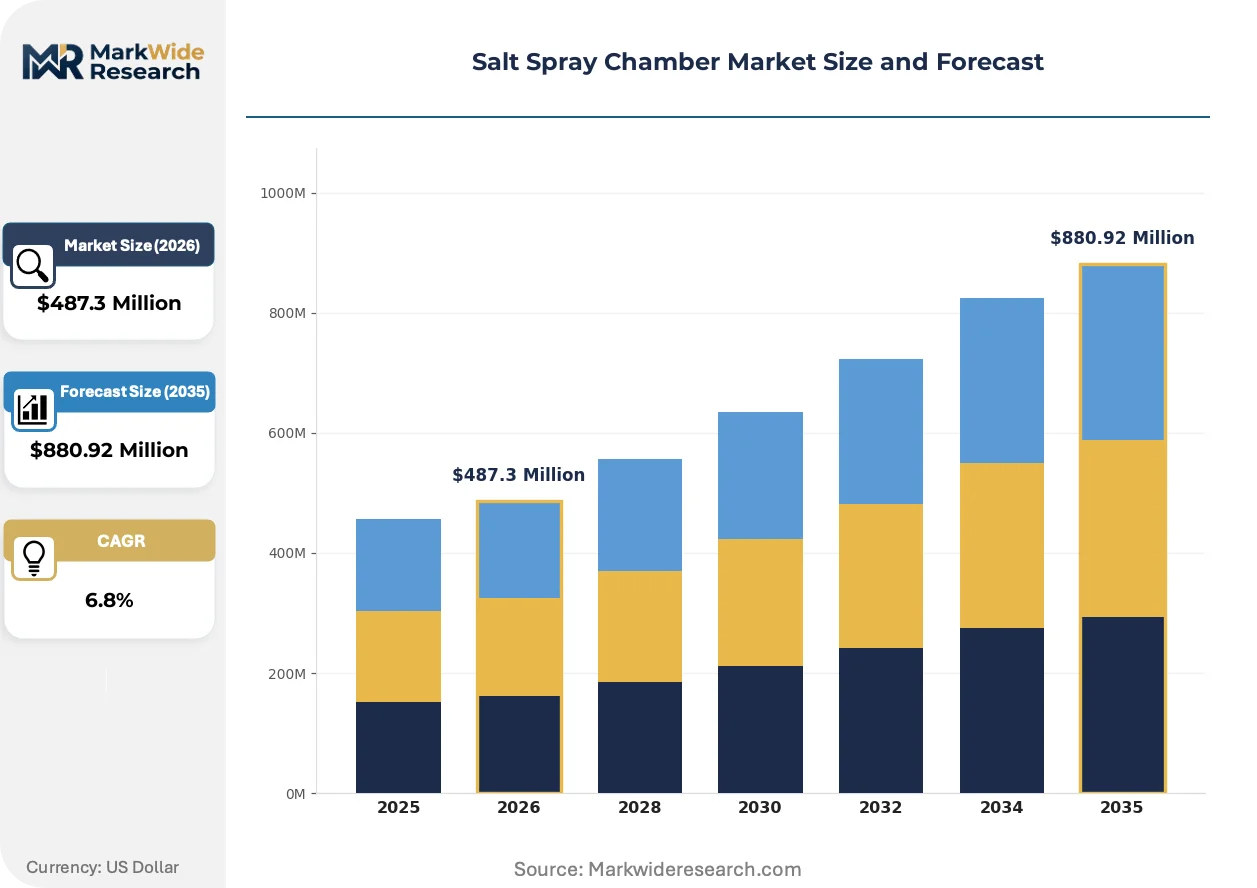
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Chambers, Custom Chambers, Laboratory Chambers, Portable Chambers Application: Automotive Parts, Aerospace Components, Coatings Testing, Electronics Testing End User: Manufacturers, Research Institutions, Quality Control Labs, Defense Contractors Features: Temperature Control, Humidity Control, Automated Testing, User-Friendly Interface |
| Companies Covered | Weiss Technik, ATLAS (AMETEK), Q-LAB, Suga Test Instruments, Hastest Solutions, Cincinnati Sub-Zero, Thermotron, Angelantoni, Uby Industrial, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salt Spray Chamber Market Evolving Landscape
Equipment vendors are embedding sensor networks and predictive maintenance algorithms into chamber architectures, compressing the gap between raw testing hardware and integrated quality systems.
IoT-enabled salt spray chambers are digitizing test workflows through continuous pH monitoring, automated salt solution replenishment, and real-time fog density adjustment. Tier-1 automotive suppliers in Germany and Japan are deploying these systems fastest, prioritizing unattended overnight operation. The technology is digitizing compliance documentation, eliminating manual log entries and accelerating audit preparation.
REACH substance restrictions on hexavalent chromium coatings are redirecting R&D budgets toward alternative corrosion protection chemistries requiring modified test protocols. European surface treatment suppliers must validate new coating systems against historical performance baselines. Aerospace primes in France and Italy are most affected, expanding chamber capacity to parallel-test legacy and next-generation formulations.
Contract testing laboratories are unbundling equipment ownership from test execution, offering per-specimen pricing that shifts capital burden from manufacturers to service providers. Small and mid-sized automotive suppliers in Mexico and Eastern Europe are adopting this model fastest, accessing TÜV-grade capacity without chamber procurement. The shift concentrates equipment investment among multi-site lab networks with regional coverage density.
Salt Spray Chamber Market Segmentation
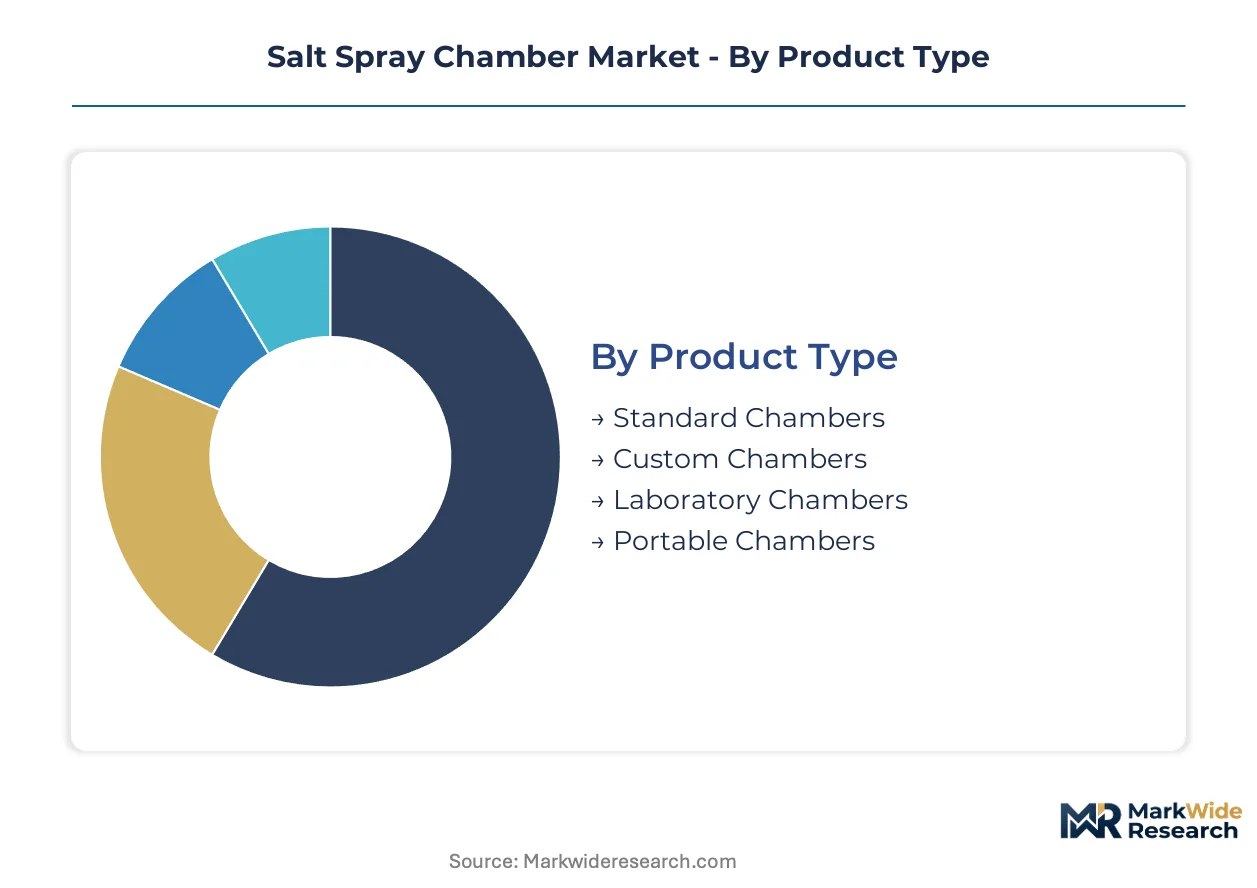
Salt spray chamber procurement patterns diverge sharply between standardized automotive validation workflows and specialized aerospace defense programs. Equipment specifications, automation levels, and service integration requirements vary significantly across these deployment contexts.
Product Type:
Mature standard configurations dominate installed base volumes while emerging custom architectures capture premium margin pools from non-standard specimen requirements.
- Standard Chambers:Fixed-dimension enclosures engineered to ASTM B117 and ISO 9227 specifications with 35°C temperature uniformity and 5% NaCl concentration control. Automotive OEMs in Germany and Japan deploy these most densely for coating qualification cycles, constrained by protocol rigidity that prevents test duration compression.
- Custom Chambers:Purpose-built architectures accommodating oversized aerospace wing sections, irregular defense component geometries, or multi-specimen rack configurations. French and Italian aerospace primes drive procurement as REACH restrictions on hexavalent chromium force parallel validation of alternative coating chemistries.
- Laboratory Chambers:Compact footprint units designed for R&D environments with modular salt solution reservoirs and rapid calibration protocols.
- Portable Chambers:Field-deployable systems with integrated power and water supply for on-site coating validation at manufacturing facilities.
Standard chambers retain volume leadership; custom chambers hold the steepest expansion curve.
Application:
Cost tier stratification separates high-volume production validation from specialized development testing across end-use industries.
- Automotive Parts:Exhaust systems, fasteners, and body panel coatings undergo accelerated corrosion cycles to meet OEM warranty specifications. Tier-1 suppliers around Stuttgart and Wolfsburg anchor concentrated demand as TÜV certification requirements mandate redundant testing capacity.
- Aerospace Components:Airframe structures and landing gear assemblies require extended exposure protocols with precise fog density control. US and European defense contractors specify these systems for MIL-STD compliance, with procurement concentrated among primes in France, Italy, and the United States.
- Coatings Testing:Surface treatment laboratories validate protective layer adhesion and degradation rates across substrate materials.
- Electronics Testing:Printed circuit boards and connector housings undergo salt fog exposure to assess solder joint integrity and housing seal performance.
Automotive parts testing commands the largest procurement budget; aerospace components show the most rapid capacity expansion.
End User:
Customer type determines ownership models, with capital-intensive manufacturers contrasting against service-based contract laboratory arrangements.
- Manufacturers:In-house quality departments at automotive and electronics producers operate chamber fleets for production release validation. Mexican and Eastern European suppliers increasingly access TÜV-grade capacity through contract testing rather than equipment procurement.
- Research Institutions:University materials science departments and government laboratories pursue fundamental corrosion mechanism studies with grant-funded equipment acquisitions.
- Quality Control Labs:Independent testing facilities serving multiple clients with per-specimen pricing models.
- Defense Contractors:Classified program requirements drive custom chamber specifications with enhanced data security and audit trail capabilities.
Manufacturers maintain the deepest installed base; quality control labs are climbing the fastest as contract testing models proliferate.
Features:
Technology maturity separates baseline environmental control from digitally integrated automation capabilities.
- Temperature Control:Precision heating systems maintaining 35°C chamber temperature within ±1°C tolerance per ASTM B117 requirements.
- Humidity Control:Saturator tower regulation of fog generation density for consistent salt deposition rates.
- Automated Testing:Unattended multi-cycle operation with digital data logging, pH monitoring, and automatic salt solution replenishment. Tier-1 automotive suppliers in Germany and Japan deploy these systems fastest for overnight operation and accelerated audit preparation.
- User-Friendly Interface:Touchscreen programming and remote telemetry access reducing technician training requirements.
Temperature control remains universal; automated testing features are gaining share fastest as labor scarcity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European chamber logistics, handling precision instrumentation imports for German automotive testing clusters while Rotterdam's container throughput supports Benelux distribution networks.
United States
FDA corrosion validation requirements for cardiovascular implants drive chamber procurement among Boston and Minneapolis medical device manufacturers. NHTSA safety standards mandate coating durability testing for underbody components. Detroit's Tier-1 supplier corridor maintains dense chamber deployment for OEM qualification cycles.
Germany
TÜV certification requirements force redundant testing capacity among Stuttgart and Wolfsburg automotive clusters. REACH restrictions on hexavalent chromium redirect R&D budgets toward alternative coating validation. Bavarian surface treatment labs anchor concentrated equipment investment for supplier qualification programs.
China
GB standards harmonization with ISO 9227 accelerates chamber fleet modernization among Yangtze River Delta exporters. MIIT automotive quality mandates tighten corrosion test protocols for domestic EV manufacturers. Shanghai's testing service providers expand capacity to capture electronics export certification demand.
Japan
METI industrial standards enforcement drives chamber replacement among Nagoya automotive suppliers facing revised calibration intervals. JIS protocol adoption by Southeast Asian export markets expands qualification testing volume. Osaka's coating technology institutes invest in multi-environment cycling systems for next-generation validation.
India
PLI scheme incentives for automotive and electronics components seed testing infrastructure among Tamil Nadu and Gujarat export suppliers. BIS certification requirements for imported machinery raise entry barriers for uncertified equipment. Pune's supplier clusters deploy chambers to meet European OEM qualification standards.
Salt Spray Chamber Market Competitive Landscape
On the supply side, the industry is consolidating around technical service capabilities rather than manufacturing scale alone. Regional fabricators compete against multinational testing equipment portfolios through localized calibration support. Two archetypes dominate: precision chamber specialists with captive nozzle supply relationships, and diversified materials testing houses cross-selling corrosion systems into installed accounts. Competitive moves concentrate on distributor network certification and remote monitoring subscription attach rates.
Among European-based fabricators, Weiss Technik anchors technical service infrastructure across German automotive clusters. ATLAS occupies a position within diversified testing equipment portfolios, leveraging cross-selling relationships into materials science accounts. Q-LAB exemplifies the consumables-bundling archetype, attaching recurring revenue streams to chamber hardware placements through test supply contracts.
| Leading Market Players |
|---|
| Weiss Technik |
| ATLAS (AMETEK) |
| Q-LAB |
| Suga Test Instruments |
| Hastest Solutions |
| Cincinnati Sub-Zero |
| Thermotron |
| Angelantoni |
| Uby Industrial |
| Others |
Value Network & Pricing Analysis
Single-source nozzle dependency in German and Japanese specialty metalworking determines both the steep premium spread for ASTM-certified chambers and the regional clustering of fabrication capacity around Stuttgart and Nagoya supplier networks.
Pricing Analysis
Volume-discount tiering separates TÜV-certified installations from standard laboratory configurations, with certification grade and after-sales service bundling as the primary price differentiation levers. Three-tier pricing structure across premium, standard, and economy levels reflects automation depth and calibration support intensity. Cost compression in economy-tier standard chambers is intensifying because Indian and Chinese fabricators are scaling export capacity. Tier-1 automotive suppliers in Germany exhibit the lowest price sensitivity due to warranty liability exposure, while Mexican contract testing labs negotiate aggressively on per-specimen service rates.
Supply Chain Analysis
Tariff exposure between European Union and Chinese stainless steel suppliers dominates input cost volatility for chamber fabricators. Manufacturing concentrates in Germany, Japan, and China, with 316L and 304-grade steel, precision spray nozzles, and saturated tower assemblies as critical component dependencies. Single-source vulnerability in nozzle supply creates procurement risk during automotive validation peak seasons. Distribution runs through certified technical service networks rather than direct manufacturer relationships, with regional calibration capability as the gating factor for channel authorization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as FDA corrosion validation requirements for implantable medical devices extend chamber procurement beyond traditional automotive demand centers.
For Market Incumbents: Pre-empt margin erosion in standard chamber segments by deepening captive nozzle supply relationships and embedding predictive maintenance subscriptions into hardware contracts. Capacity addition in Tamil Nadu and Gujarat captures PLI-linked Indian automotive supplier demand before local fabrication scales. Certification investment in BIS compliance creates entry barriers against uncertified Chinese competitors. For New Entrants and Emerging Players: Pursue contract testing laboratory networks in Mexico and Eastern Europe as the most penetrable customer archetype, where per-specimen pricing models shift capital burden from manufacturers to service providers. Remote monitoring software attach offers a SaaS-based go-to-market angle with lower capital intensity than chamber fabrication. For Investors and Strategic Acquirers: Precision chamber specialists with established TÜV-certified service infrastructure represent the optimal acquisition archetype for exposure to automotive validation cycle durability. Long-term viability hinges on diversification beyond automotive into medical device and aerospace coating validation. Watch REACH regulatory expansion into additional coating chemistries as the inflection signal for parallel testing capacity demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nozzle Manufacturing | Captive supply of precision spray components insulates margin from German-Japanese supplier bottlenecks. |
| Remote Monitoring Subscription Launch | Cloud-connected telemetry creates recurring revenue attachment to chamber hardware placements in distributed quality networks. |
| TÜV Certification Investment | Third-party calibration authorization unlocks premium pricing in Stuttgart and Wolfsburg automotive clusters. |
| Multi-Environment Cycling System Development | Converged salt spray-UV-thermal chambers capture aerospace contractor budgets seeking consolidated footprint. |
| Indian PLI-Linked Manufacturing Partnership | Local assembly presence qualifies for automotive component incentive schemes and reduces import duty exposure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ASTM International protocol documentation, ISO 9227 calibration records, and automotive OEM supplier qualification databases. Primary interviews incorporated quality control lab directors, Tier-1 automotive supplier procurement leads, TÜV certification auditors, and chamber fabrication plant managers. Secondary validation drew from SEC filings of diversified testing equipment portfolios, customs data on stainless steel trade flows, and FDA medical device coating validation guidance. Bottom-up chamber deployment counts triangulated against top-down automotive and aerospace R&D expenditure patterns.
Forecast inputs incorporate product type segmentation across standard, custom, laboratory, and portable configurations; application segmentation spanning automotive parts, aerospace components, coatings testing, and electronics; and end-user segmentation separating manufacturers, research institutions, quality control labs, and defense contractors. CAGRs were derived from elasticity modeling against automotive production cycles and medical device approval timelines. Industry-specific inputs include REACH regulatory expansion scenarios and PLI scheme uptake rates in Indian automotive supplier clusters.
Macroeconomic conditions sit as an overlay; deviation in stainless steel commodity indices, automotive OEM capital expenditure cycles, or FDA medical device review throughput would shift the trajectory. Forecasts reflect documented assumptions on protocol harmonization timing and calibration queue duration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Dynamic Vapor Sorption Analyzer Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Material Testing Market
Testing Equipment
Paper Tester Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Global Lab Automation in Analytical Chemistry Market
Testing Equipment
Global Circular Dichroism (CD) Spectrometers Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Americas Testing, Inspection and Certification (TIC) Market
Testing Equipment
Flash Point Apparatus Market
Testing Equipment
Laboratory Mixer Market
Testing Equipment
Chlorine Meter Market
Testing Equipment
Global Life Science and Chemical Instrumentation Market
Testing Equipment
Cyclic Corrosion Test Chamber Market