
 Chromatography Systems Market | 2026-2036
Chromatography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatography Systems Market Analysis
Multi-source instrument procurement is shifting toward consolidated vendor partnerships in large pharmaceutical labs. Agilent Technologies leverages its cross-platform software ecosystem to lock in recurring service revenue. Thermo Fisher Scientific anchors its position through captive consumables and applied market channels. Waters Corporation differentiates via mass spectrometry-chromatography integration for biopharma analytical workflows.
Chromatography systems separate, identify, and quantify chemical mixtures by passing mobile phases through stationary-phase columns, with resolution measured in theoretical plates and detection sensitivity reaching picogram levels for trace analysis. These instruments enable drug purity verification, environmental contaminant screening, and food safety testing across regulated industries. High-performance Liquid Chromatography dominates installed bases in pharmaceutical quality control labs where gradient elution methods handle complex biomolecule separations. Gas Chromatography retains strong positions in environmental and petrochemical testing due to superior volatile compound resolution. Academic Institutions represent a growing end-user segment as federal research funding expands analytical chemistry infrastructure.
FDA method validation guidelines and EMA ICH Q2(R1) standards dictate column reproducibility and detector calibration requirements that shape instrument replacement cycles. EPA protocols for drinking water and air toxics monitoring mandate specific chromatography configurations, creating compliance-driven demand in environmental agencies. REACH substance identification rules in Europe require analytical traceability that favors certified reference material compatibility. Stakeholders must monitor evolving pharmacopeial monographs and sustainability mandates affecting solvent consumption and waste disposal economics.
Market Dynamics
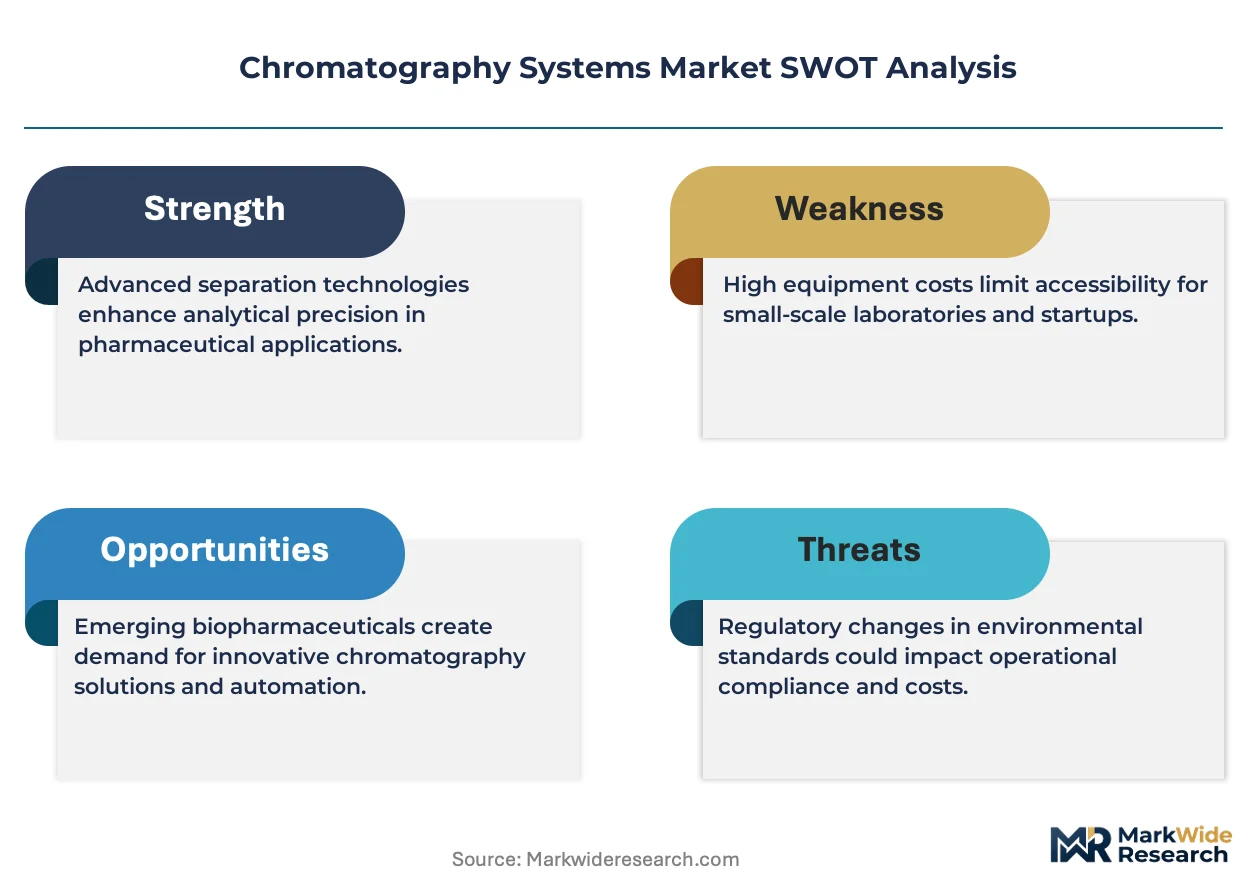
Biologics manufacturing scale-up is compressing instrument replacement cycles as pharmaceutical quality control labs face column reproducibility mandates from FDA and EMA. This regulatory pressure is forcing capital allocation toward integrated chromatography-mass spectrometry platforms that reduce method validation timelines.
Growth Catalysts
- FDA Method Validation Guidelines:Tightening detector calibration requirements accelerate instrument refresh rates in pharmaceutical quality control labs.
- Gradient Elution Methods:Complex biomolecule separations in biologics manufacturing expand High-performance Liquid Chromatography installed bases.
- Petrochemical Testing Clusters:Gas Chromatography demand concentrates in Houston and Rotterdam for volatile compound resolution in environmental monitoring.
Market Restraints
- Helium Supply Concentration:Gas Chromatography operations depend on concentrated helium sourcing from Qatar and the United States, creating input volatility.
- Column Manufacturing Bottlenecks:Silica particle supply concentrates among limited specialty chemical producers in Germany and Japan.
- EPA Protocol Rigidity:Prescriptive drinking water monitoring configurations limit instrument flexibility and extend replacement decision timelines.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore require analytical infrastructure buildouts for export compliance.
- Continuous Chromatography-Mass Spectrometry Integration:Real-time process analytical technology convergence enables in-line bioreactor monitoring for upstream bioprocessing.
- EU Green Deal Solvent Mandates:Sustainability requirements for acetonitrile waste reduction create demand for aqueous mobile phase system redesigns.
Industry Challenges
- Method Transfer Expertise Scarcity:Pharmaceutical labs face shortages of analytical chemists capable of cross-platform validation between HPLC and UHPLC systems.
- Legacy Data System Integration:21 CFR Part 11 compliance requirements complicate migration from standalone chromatography data stations to enterprise LIMS architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatography Systems Market |
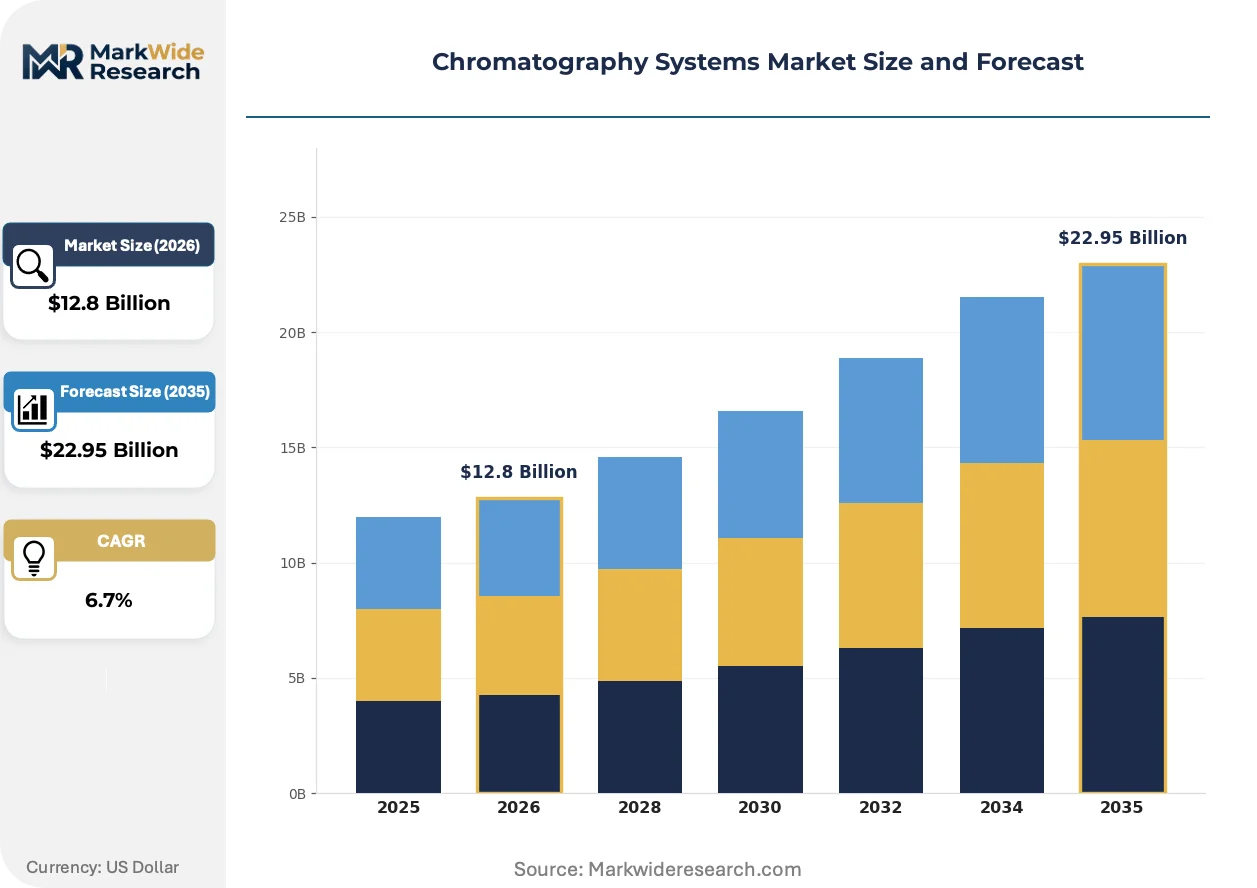
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-performance Liquid Chromatography, Gas Chromatography, Supercritical Fluid Chromatography, Thin-layer Chromatography End User: Pharmaceutical Companies, Academic Institutions, Environmental Agencies, Food & Beverage Companies Technology: Liquid Chromatography, Column Chromatography, FPLC, Affinity Chromatography Application: Drug Testing, Quality Control, Chemical Analysis, Research & Development |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Waters Corporation, Shimadzu Corporation, PerkinElmer, Bio-Rad Laboratories, Merck KGaA, GE Healthcare, JASCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatography Systems Market Emerging Trajectories
Chromatography instrumentation is pivoting toward modularity and software-defined workflows that compress method development timelines. Vendors are repositioning hardware as platforms for recurring consumables and service revenue rather than discrete capital sales.
Ultra-High Performance Liquid Chromatography is expanding into peptide mapping and charge variant analysis for monoclonal antibody characterization. Biopharma quality control labs in Boston and Basel are adopting sub-2-micron particle columns to reduce run times by half. This compression of analytical cycles is expanding into high-throughput screening applications previously served by older HPLC platforms.
EMA ICH Q14 guidelines for analytical procedure development are mandating enhanced method understanding and design space definition. Pharmaceutical sponsors must now demonstrate robustness across deliberate variation ranges before regulatory submission. This documentation burden is accelerating adoption of automated method scouting systems in Germany and Switzerland.
Consolidated vendor partnerships are displacing multi-source procurement in large pharmaceutical labs. Procurement teams in New Jersey and North Carolina are negotiating enterprise framework agreements that bundle instruments, columns, and qualification services. This concentration of supplier relationships is most visible among top-20 biopharma manufacturers seeking to reduce validation overhead.
Chromatography Systems Market Segmentation
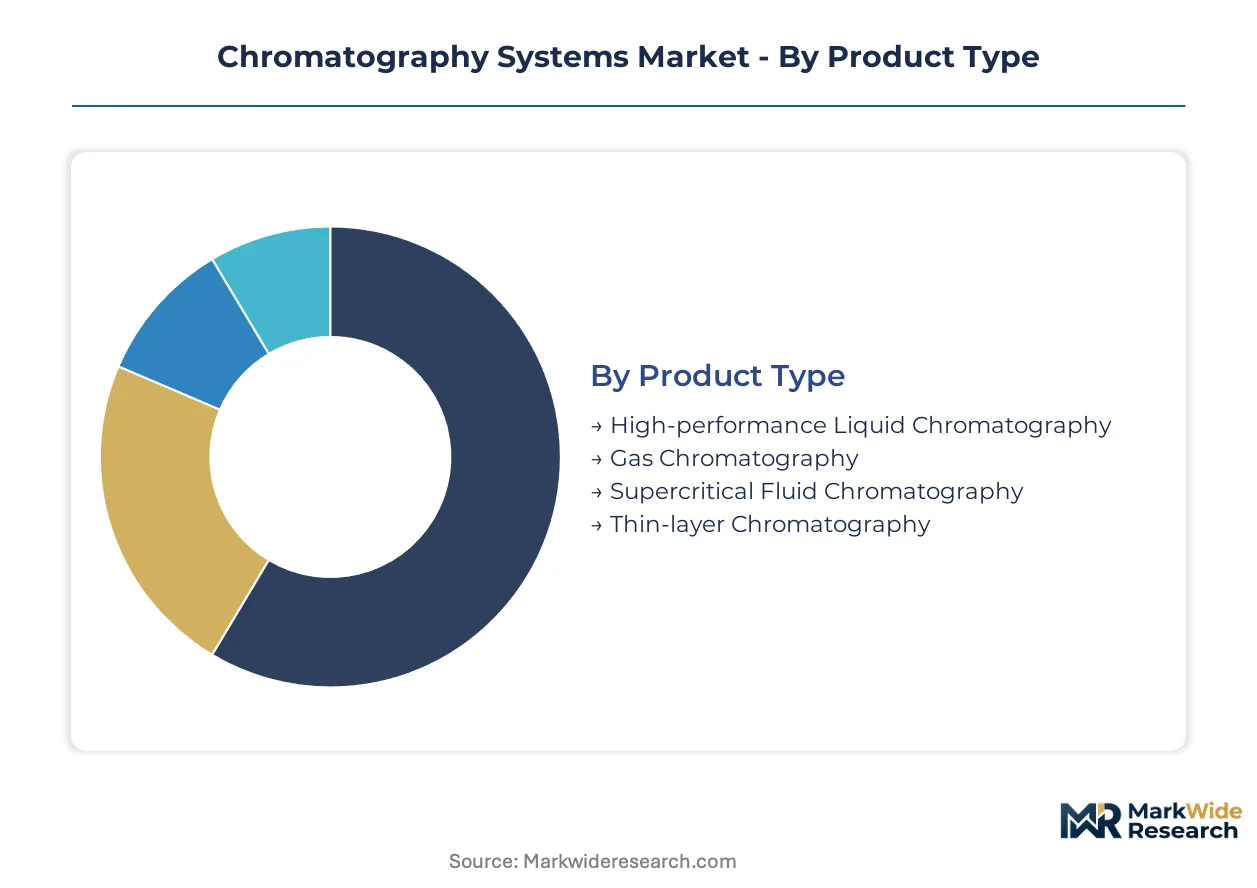
Chromatography system segmentation reveals distinct upgrade cycles across product architectures and end-use environments. Pharmaceutical quality control labs drive premium platform adoption while academic and environmental segments prioritize cost efficiency and modular flexibility.
Product Type:
Replacement cycles diverge sharply across chromatography architectures, with pressure tolerance specifications and particle size capabilities dictating obsolescence timelines.
- High-performance Liquid Chromatography:Systems operate at pressures up to 600 bar with 3-5 micron particle columns, dominating pharmaceutical quality control labs in Germany and the United States where FDA method validation mandates accelerate refresh rates.
- Gas Chromatography:Instruments achieve superior volatile compound resolution through thermal desorption and headspace sampling, concentrating demand in Houston and Rotterdam petrochemical testing clusters facing EPA air toxics monitoring protocols.
- Supercritical Fluid Chromatography:CO2-based mobile phase systems reduce organic solvent consumption for chiral separations.
- Thin-layer Chromatography:Low-cost planar format retains position in educational laboratories and rapid screening applications.
High-performance Liquid Chromatography sits at the top of the volume ranking, with Supercritical Fluid Chromatography climbing the fastest.
End User:
Capital allocation patterns separate regulated industries with compliance-driven procurement from research segments with grant-dependent purchasing cycles.
- Pharmaceutical Companies:Biologics manufacturers in Basel and Boston deploy integrated chromatography-mass spectrometry platforms for monoclonal antibody characterization, with EMA ICH Q14 guidelines forcing method robustness documentation investments.
- Academic Institutions:Federal research funding expansions in the United States and Germany support analytical chemistry infrastructure buildouts for graduate training programs.
- Environmental Agencies:EPA drinking water and air monitoring protocols mandate specific detector configurations, extending replacement decision timelines.
- Food & Beverage Companies:Contaminant screening requirements under FSSAI in India and FDA Food Safety Modernization Act drive routine testing infrastructure.
Pharmaceutical Companies command the largest installed base, while Academic Institutions are expanding most quickly.
Technology:
Platform architecture choices determine consumables lock-in and service revenue potential for vendors.
- Liquid Chromatography:Gradient elution systems with binary or quaternary pumps handle complex biomolecule separations, anchoring biopharma quality control workflows in Switzerland and Massachusetts.
- Column Chromatography:Preparative-scale systems with adjustable bed heights support protein purification in contract manufacturing organizations.
- FPLC:Fast protein liquid chromatography operates at low pressure with biocompatible flow paths for antibody purification.
- Affinity Chromatography:Ligand-specific separations exploit protein A, protein G, or custom resin chemistries for target molecule isolation.
Liquid Chromatography leads technology deployment, with Affinity Chromatography gaining share fastest in bioprocessing applications.
Application:
Workflow automation requirements separate high-throughput routine testing from method development environments.
- Drug Testing:Forensic and clinical toxicology labs require validated quantitative methods with chain-of-custody documentation, concentrating demand in certified reference material-compatible platforms.
- Quality Control:Release testing protocols in pharmaceutical manufacturing mandate system suitability checks and detector calibration traceability under FDA and EMA guidelines.
- Chemical Analysis:Petrochemical and specialty chemical producers utilize Gas Chromatography for purity verification and impurity profiling.
- Research & Development:Method scouting and analytical procedure development activities prioritize flexible gradient programming and multi-detector configurations.
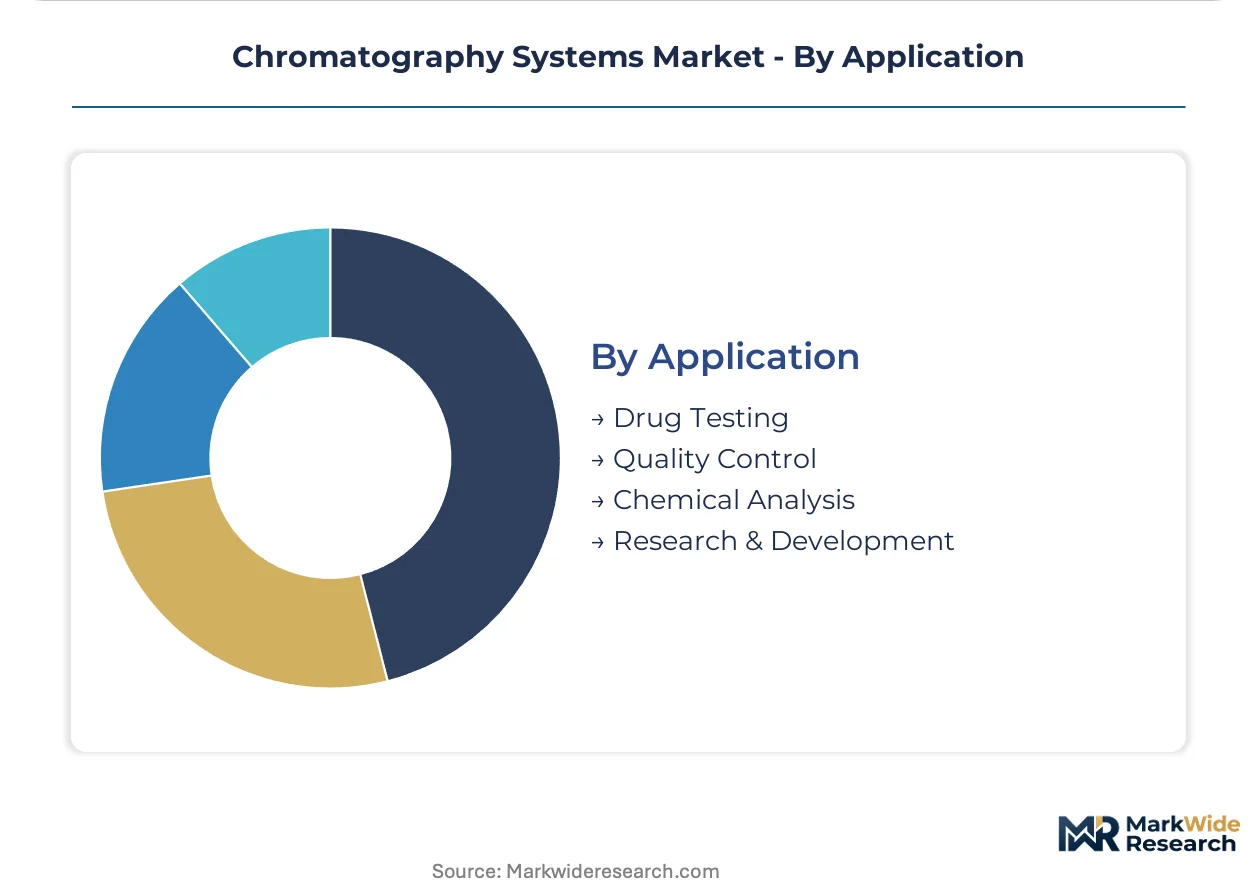
Quality Control dominates application spending, with Research & Development showing the steepest expansion trajectory as EMA ICH Q14 documentation burdens intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters anchor chromatography system demand through pharmaceutical quality control infrastructure and analytical chemistry instrumentation exports.
United States
FDA method validation guidelines and biologics manufacturing scale-up drive instrument replacement cycles in pharmaceutical quality control labs. The EPA mandates specific detector configurations for drinking water and air toxics monitoring protocols. Boston and North Carolina's Research Triangle host concentrated biopharma analytical operations deploying integrated chromatography-mass spectrometry platforms.
Germany
EMA ICH Q14 documentation requirements and REACH substance identification rules shape analytical procedure development investments. The EU Green Deal solvent mandates accelerate aqueous mobile phase system redesigns. Baden-Württemberg and Bavaria house specialty chemical producers supplying silica particle columns to global instrument manufacturers.
Switzerland
Swissmedic validation standards and monoclonal antibody characterization workflows concentrate demand for sub-2-micron particle column systems. Federal research funding expansions support graduate analytical chemistry training infrastructure. Basel's biopharma manufacturing corridor drives premium platform adoption for release testing protocols.
India
FSSAI contaminant screening requirements and CDSCO export compliance standards accelerate analytical infrastructure buildouts. The PLI scheme for pharmaceuticals incentivizes domestic manufacturing quality control capabilities. Hyderabad and Bangalore's contract development and manufacturing organizations require chromatography capacity for international market access.
Japan
PMDA analytical method validation guidelines and METI sustainability directives influence instrument procurement patterns. JIS standards certification requirements favor established vendor relationships in quality control environments. The Kansai region's specialty chemical sector maintains silica particle supply chain positions for chromatography column manufacturing.
Chromatography Systems Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular platform architectures and software-defined workflow niches. The vendor base stratifies across integrated system architects, consumables-dominant suppliers, and regional instrumentation specialists. Three archetypes dominate: full-platform providers with captive consumables ecosystems, mass spectrometry-chromatography integration specialists, and analytical software platform vendors. Consolidation pressures favor enterprise framework agreements bundling instruments, columns, and qualification services.
Among United States-based instrumentation conglomerates, Agilent Technologies and Thermo Fisher Scientific exemplify full-platform providers with recurring revenue architectures through service and consumables lock-in. Waters Corporation anchors the mass spectrometry-chromatography integration specialist tier. Japanese precision instrument manufacturers including Shimadzu Corporation occupy positions emphasizing detector sensitivity and column reproducibility specifications.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Waters Corporation |
| Shimadzu Corporation |
| PerkinElmer |
| Bio-Rad Laboratories |
| Merck KGaA |
| GE Healthcare |
| JASCO |
| Others |
Supply Flow & Price Mechanics
Sub-2-micron particle column manufacturing is consolidating in Germany and Japan while aqueous mobile phase redesigns under EU Green Deal mandates simultaneously raise R&D amortization costs and concentrate supplier qualification pools among certified vendors. Pharmaceutical quality control labs in Basel and Boston now face compressed procurement timelines as silica particle supply bottlenecks intersect with FDA detector calibration requirements.
Pricing Analysis
Input-cost pass-through from helium supply volatility in Qatar and the United States runs through Gas Chromatography system pricing, with column manufacturing bottlenecks in Germany and Japan amplifying pressure on consumables tiers. Three-tier pricing structure across premium, standard, and economy levels separates integrated chromatography-mass spectrometry platforms from modular HPLC systems and educational-grade instruments. Cost compression in standard-tier systems is intensifying because academic institutions prioritize grant-funded capital efficiency over service bundling. Environmental agencies exhibit highest price sensitivity due to EPA protocol rigidity extending replacement cycles, while biopharma manufacturers show lowest sensitivity where EMA ICH Q14 documentation burdens mandate platform consolidation.
Supply Chain Analysis
Dual-sourcing requirements from pharmaceutical quality control labs mandate multi-supplier qualification for silica particle columns across Germany, Japan, and emerging specialty chemical producers in the United States. Raw material dependencies center on high-purity silica substrates, helium for carrier gas applications, and biocompatible resins for protein A affinity chromatography. Single-source vulnerability concentrates in helium extraction from Qatar's North Field and the United States' Hugoton-Panhandle complex. Distribution runs through direct vendor partnerships with large pharmaceutical labs and regional distributors serving academic and environmental segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chromatography Systems Market functions as a regulatory compounder where EMA ICH Q14 method robustness documentation mandates perpetually refresh instrument installed bases across pharmaceutical quality control labs.
For Market Incumbents: Hedge helium supply exposure through captive partnerships with Qatar-based extraction operators and United States shale gas processors while accelerating aqueous mobile phase system development to preempt EU Green Deal solvent mandates. Consolidate vendor relationships with top-20 biopharma manufacturers through enterprise framework agreements bundling instruments, columns, and qualification services to defend against modular platform entrants. For New Entrants and Emerging Players: Software-defined workflow automation offers a technology-first wedge into method development environments where EMA ICH Q14 documentation burdens strain legacy data system integration. Target academic institutions in Germany and the United States where federal research funding expansions support analytical chemistry infrastructure buildouts with lower validation overhead than regulated pharmaceutical environments. Deploy cloud-native chromatography data systems as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional instrumentation specialists with captive column manufacturing capabilities in Germany and Japan. Long-term viability hinges on consumables recurring revenue capture rather than discrete capital sales. Acquisition target archetype: mid-tier vendors with silica particle supply chain positions and underexploited service revenue streams. Watch for inflection in India CDMO analytical infrastructure buildouts as the signal indicating sustained emerging market demand.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Chromatography-Mass Spectrometry Integration | Enables real-time bioreactor monitoring under FDA process analytical technology guidance. |
| Backward Integration into Silica Particle Manufacturing | Secures column reproducibility supply for EMA ICH Q2(R1) validation requirements. |
| Aqueous Mobile Phase System Redesign | Addresses EU Green Deal acetonitrile waste reduction mandates for pharmaceutical labs. |
| Enterprise Framework Agreement Expansion | Locks in recurring service revenue with top-20 biopharma manufacturers in Basel and Boston. |
| India CDMO Analytical Infrastructure Partnership | Captures export compliance-driven demand from Hyderabad and Bangalore manufacturing clusters. |
Methodological Framework
Multiple input streams — technical interviews with analytical chemistry directors at pharmaceutical quality control labs, procurement discussions with academic research officers, and regulatory affairs consultations with EMA and FDA compliance leads — were reconciled against secondary validation from FDA method validation guidelines, EMA ICH Q14 documentation requirements, EPA drinking water monitoring protocols, and SEC filings from publicly traded instrumentation conglomerates. Bottom-up installed base estimates from pharmaceutical, academic, and environmental end-use segments were triangulated against top-down market sizing from vendor revenue disclosures.
Cross-referencing historical instrument replacement cycle patterns with panel input from chromatography data system architects informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-user industry, application workflow, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating biologics manufacturing scale-up rates and federal research funding trajectories. Industry-specific forecast inputs encompassed helium supply concentration indices and silica particle manufacturing capacity utilization.
The model holds under stable regulatory validation timelines and sustained biologics pipeline investment; deviation in FDA or EMA method validation stringency, helium supply disruption from Qatar export restrictions, or abrupt EU Green Deal solvent mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
CHS (Carbon Hydrogen Sulfur) Analyzers Market
Testing Equipment
Global Lab Supplies Market
Testing Equipment
Automated Solid Phase Extraction Systems Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Ultrasonic Testing Market
Testing Equipment
Reagent Filling Systems Market
Testing Equipment
Material Testing Market
Testing Equipment
Global Liquid Chromatography Instruments Market
Testing Equipment
Melting Point Apparatus Market
Testing Equipment
Heavy Metal Testing Market
Testing Equipment
Supercritical Fluid Chromatography (SFC) System Market
Testing Equipment
Glass Testing Instruments Market
Testing Equipment
Supercritical Fluid Chromatography Market
Testing Equipment
Carbon Black Content Tester Market
Testing Equipment
Liquid Chromatography Market