
 Artificial Intelligence (AI) in Manufacturing Market | 2026-2036
Artificial Intelligence (AI) in Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Manufacturing Market Analysis
ISO/IEC 23053 for AI system trustworthiness is reorganizing vendor qualification protocols across industrial AI procurement. NVIDIA Corporation dominates GPU-accelerated inference for factory floor deployments. Intel Corporation leverages its OpenVINO toolkit to anchor edge AI pipelines in discrete manufacturing. Microsoft Corporation extends Azure Industrial IoT to compete for cloud-based AI operations in process industries.
Artificial Intelligence in Manufacturing denotes machine learning algorithms, computer vision systems, and natural language processing tools deployed to optimize production workflows, typically requiring sub-50ms inference latency for real-time quality inspection and predictive equipment diagnostics. The primary purpose centers on reducing unplanned downtime and defect rates through automated pattern recognition across sensor networks. Machine Learning captures the largest share of technology spending as manufacturers prioritize anomaly detection over generative applications. Predictive Maintenance leads application adoption because ROI materializes within single fiscal cycles through avoided catastrophic equipment failures. Edge Computing deployments are expanding fastest where latency constraints prohibit cloud round-trips for safety-critical robotic coordination.
The EU AI Act classifies manufacturing AI systems by risk tier, compelling conformity assessments for quality-control algorithms that influence product safety. The FDA's software-as-medical-device framework indirectly shapes diagnostic equipment manufacturing standards that propagate through supplier chains. OSHA's machine guarding standards are adapting to accommodate collaborative robots running AI-powered computer vision. Stakeholders must monitor how divergent regulatory timelines between Brussels and Washington create compliance fragmentation for multinational plant operators.
Market Dynamics
Edge inference latency requirements below 50 milliseconds are forcing manufacturers to deploy GPU clusters directly on factory floors rather than routing through cloud data centers. This architectural shift compresses capital deployment timelines and requalifies vendor relationships around real-time performance guarantees.
Growth Catalysts
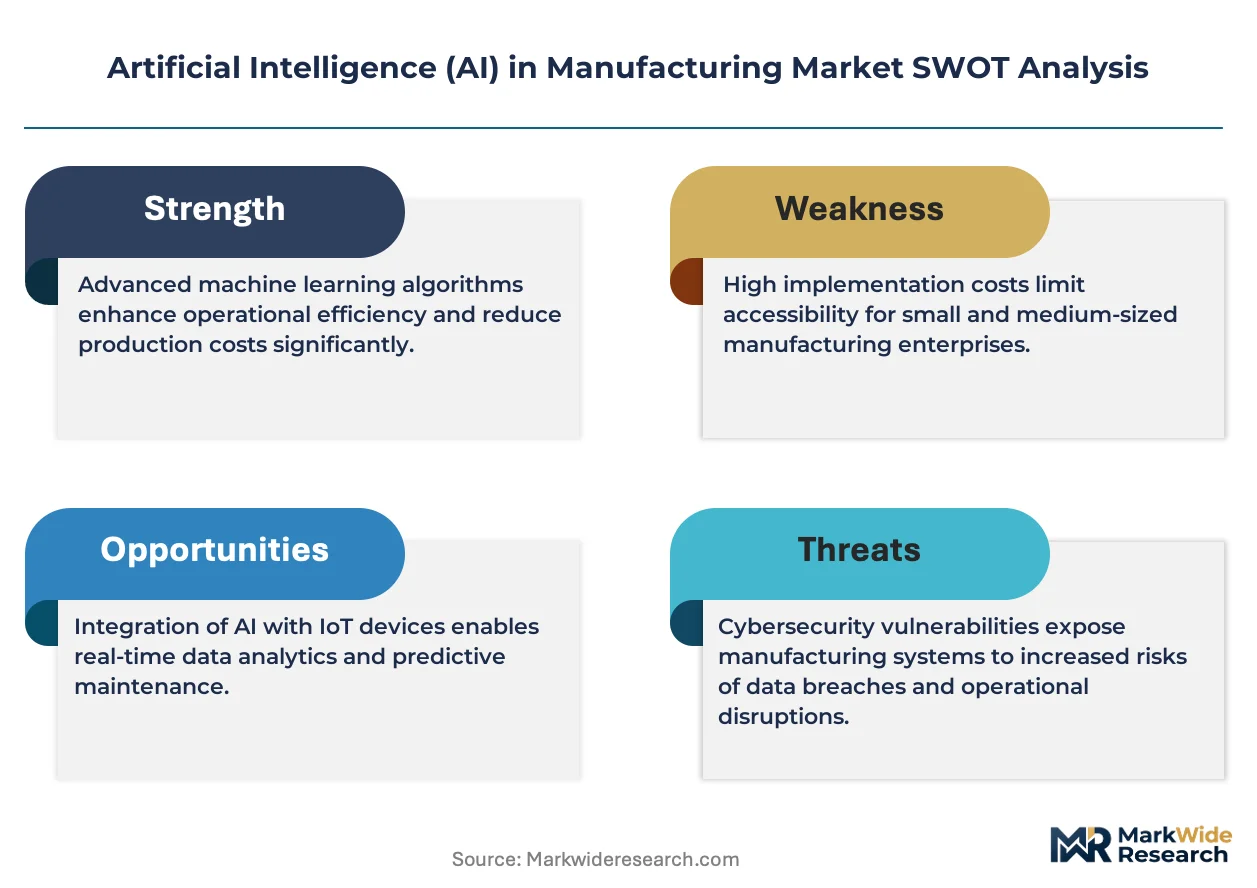
- Predictive Maintenance ROI:Automotive and semiconductor fabs recoup AI investments within single fiscal cycles through avoided catastrophic equipment failures. Anomaly detection algorithms now process vibration and thermal sensor streams continuously.
- EU AI Act Conformity Assessments:Quality-control algorithms influencing product safety face mandatory third-party evaluation. Manufacturers serving European markets must document risk management systems and training data governance.
- German Industrial Cluster Density:Siemens and Bosch anchor smart factory ecosystems in Baden-Württemberg and Bavaria. Supplier networks around these anchors accelerate technology diffusion through shared infrastructure and talent pools.
Market Restraints
- NVIDIA GPU Supply Concentration:Inference acceleration hardware for factory floor deployments depends on a single dominant supplier. Geopolitical export controls and foundry capacity constraints create procurement vulnerability.
- ISO/IEC 23053 Certification Costs:Trustworthiness framework compliance requires extensive documentation of AI system lifecycle processes. Small and mid-sized manufacturers face disproportionate audit burden relative to implementation scale.
- Legacy PLC Integration Friction:Decades-old programmable logic controllers lack native API architectures. Retrofit costs for sensor data extraction often exceed greenfield AI deployment budgets.
Strategic Opportunities
- India PLI Scheme Manufacturing Incentives:Production-linked incentive schemes for electronics and automotive sectors subsidize smart factory investments. Greenfield plants can embed AI-native architecture without legacy migration costs.
- FDA Software-as-Medical-Device Precedents:Diagnostic equipment manufacturing standards for AI-enabled devices propagate through supplier chains. Component vendors serving medical device OEMs gain transferable compliance credentials.
- Digital Twin Convergence with Physics Simulation:Real-time sensor feeds feeding into finite element models enable closed-loop process optimization. Chemical and materials processing industries show early adoption traction.
Industry Challenges
- Industrial Data Science Talent Scarcity:Manufacturers compete with technology firms for practitioners capable of bridging mechanical engineering and machine learning pipelines. Compensation premiums of 40-60% above traditional automation engineering roles strain HR budgets.
- OSHA Machine Guarding Standard Adaptation:Collaborative robots running computer vision require revised safety certification protocols. Regulatory lag creates deployment uncertainty for human-robot workcell implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Manufacturing Market |
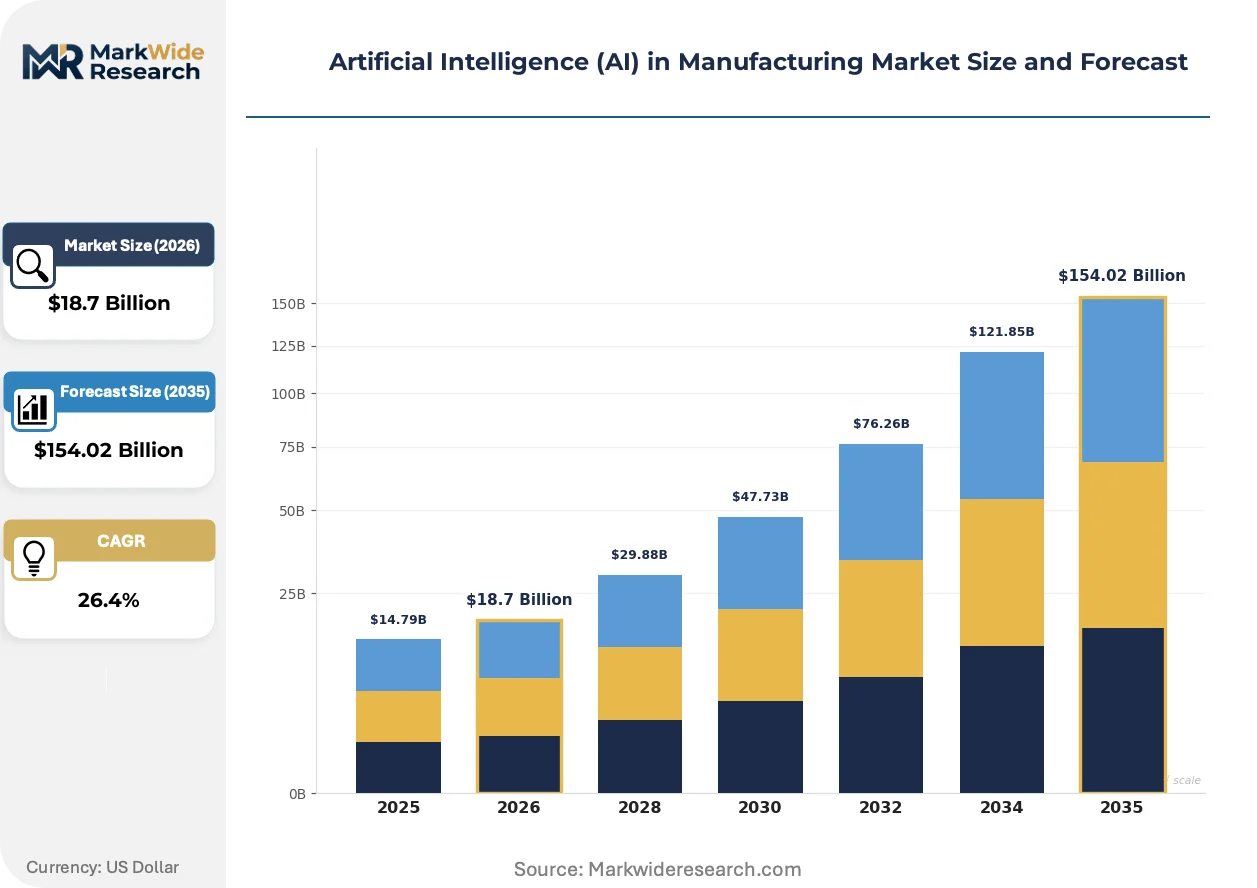
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $154.02 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Robotics, Computer Vision Application: Predictive Maintenance, Quality Control, Supply Chain Optimization, Process Automation End User: Automotive Manufacturers, Electronics, Consumer Goods, Aerospace Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Amazon.com Inc., SAP SE, Rockwell Automation Inc., Alphabet Inc., Microsoft Corporation, IBM, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Manufacturing Market Emerging Trajectories
Manufacturing AI is pivoting from cloud-centric model training to edge-native inference architectures. This reorientation redistributes computational investment across the production technology stack and redefines vendor competitive advantage around latency engineering.
Embedded vision processors are miniaturizing quality inspection systems from rack-mounted servers to camera-integrated modules. Automotive paint shops and electronics assembly lines deploy these units at each workstation rather than centralized stations. The technology is miniaturizing defect detection infrastructure and collapsing the physical footprint required for hundred-percent inspection coverage.
REACH chemical substance restrictions and RoHS hazardous material limits are cascading into AI hardware procurement specifications. Manufacturers must now document supply chain compliance for rare earth elements in GPU accelerators and sensor components. Medical device and automotive verticals face the strictest material traceability requirements, driving supplier qualification toward full bill-of-materials transparency.
Buyers now unbundle AI software licenses from automation hardware contracts, treating machine learning models as renewable subscription assets rather than capital equipment appendages. System integrators respond with outcome-based pricing tied to measured downtime reduction or yield improvement. This shift is most visible in Germany's automotive supplier tier, where OEMs demand performance guarantees rather than feature checklists.
Artificial Intelligence (AI) in Manufacturing Market Segmentation
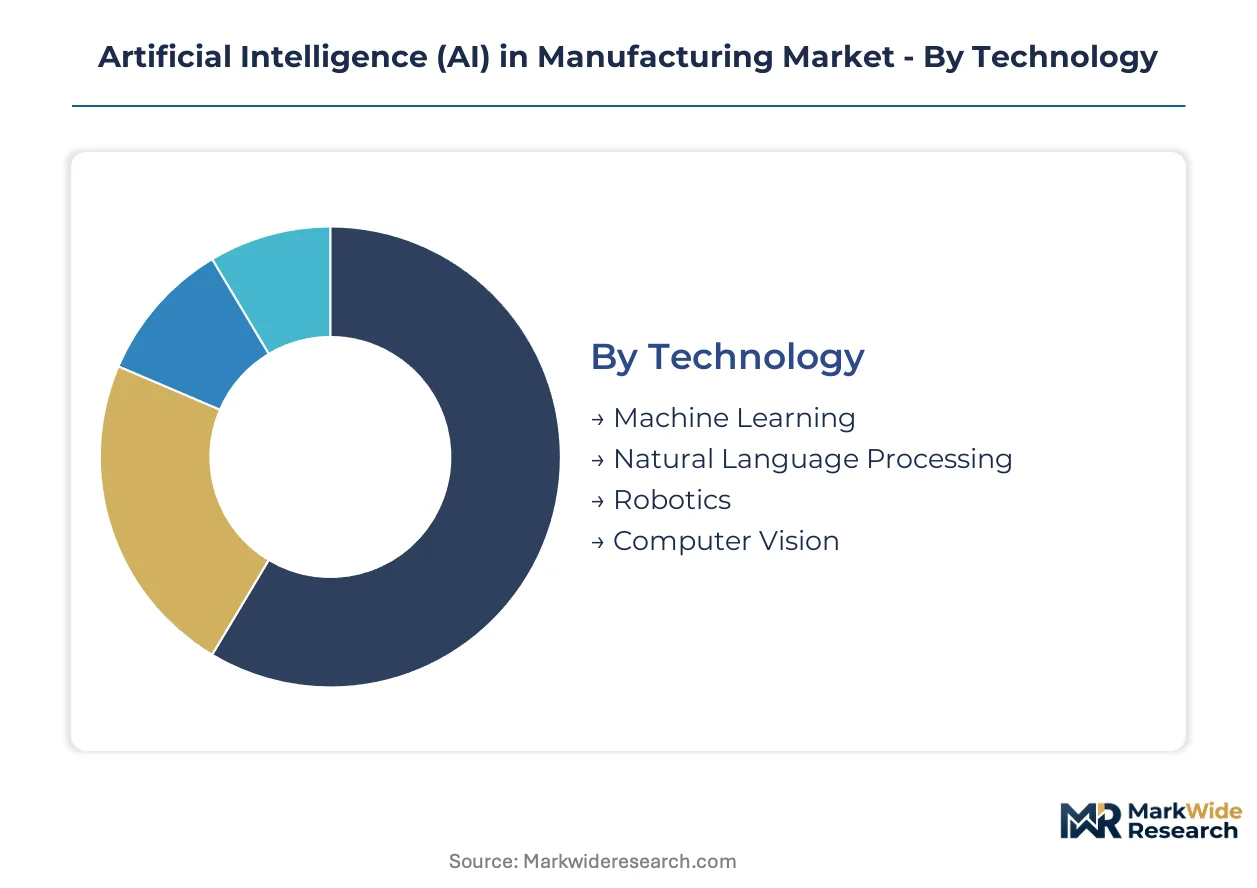
AI deployment patterns in manufacturing diverge sharply by latency tolerance, data sovereignty requirements, and legacy infrastructure maturity. Procurement channels for each segment reflect these technical constraints, with system integrators bundling hardware-software stacks differently across factory archetypes.
Technology:
Machine Learning and Computer Vision flow through automation OEM channel partnerships, while Natural Language Processing and Robotics typically route through specialized AI consultancies and cobot distributors respectively.
- Machine Learning:Supervised and unsupervised algorithms process vibration, thermal, and acoustic sensor streams for anomaly detection. Automotive manufacturers in Germany's supplier tier prioritize this technology for its single-fiscal-cycle ROI through avoided catastrophic equipment failures.
- Computer Vision:Convolutional neural networks and transformer architectures enable real-time defect inspection with sub-50ms inference requirements. Electronics assembly lines in Baden-Württemberg deploy embedded vision processors at each workstation rather than centralized stations.
- Natural Language Processing:Text and voice interfaces for maintenance documentation and operator guidance. Demand concentrates in aerospace MRO operations where multilingual technical manual parsing reduces mean time to repair.
- Robotics:AI-powered motion planning and grasp optimization for collaborative and autonomous systems. Consumer goods packaging lines integrate these capabilities through cobot distributor networks focused on human-robot workcell safety certification.
Machine Learning dominates installed base. Computer Vision is where expansion concentrates.
Application:
Cost tier differentiation separates premium predictive maintenance suites from standardized quality control modules, with process automation commanding mid-tier pricing and supply chain optimization anchoring the economy segment through SaaS subscriptions.
- Predictive Maintenance:Continuous monitoring algorithms forecast equipment degradation before functional failure. Semiconductor fabs in Bavaria recoup investments fastest through avoided unplanned downtime in lithography and deposition tools.
- Quality Control:Automated visual inspection systems detect surface defects, dimensional deviations, and assembly errors. Automotive paint shops deploy hundred-percent inspection coverage with miniaturized camera-integrated modules.
- Supply Chain Optimization:Demand forecasting and inventory positioning algorithms. Electronics manufacturers leverage cloud-based deployments for multi-site coordination without edge infrastructure capital.
- Process Automation:Closed-loop control systems adjusting parameters in real-time. Chemical processing industries show early traction where digital twins converge with physics simulation for materials optimization.
Predictive Maintenance commands premium pricing through outcome-based contracts. Quality Control is gaining share fastest as inspection coverage requirements tighten across medical device and automotive verticals.
End User:
Volume concentration in automotive creates procurement scale effects, while aerospace and consumer goods segments fragment across specialized system integrators with domain-specific compliance credentials.
- Automotive Manufacturers:Full-stack AI adoption spanning predictive maintenance, computer vision quality gates, and robotic welding coordination. OEMs in Germany demand performance guarantees rather than feature checklists from tier-one suppliers.
- Electronics:Miniaturized component inspection and cleanroom process control. Surface-mount technology lines require sub-50ms inference for real-time defect rejection without throughput degradation.
- Consumer Goods:Flexible packaging and palletizing applications with frequent changeover requirements. Cobot deployments emphasize rapid reprogramming through vision-guided teaching rather than fixed automation.
- Aerospace:Composite material inspection and predictive MRO scheduling. FAA and EASA certification requirements propagate through supplier chains, favoring vendors with transferable compliance documentation.
Automotive Manufacturers anchor procurement volume. Electronics is where deployment velocity is accelerating.
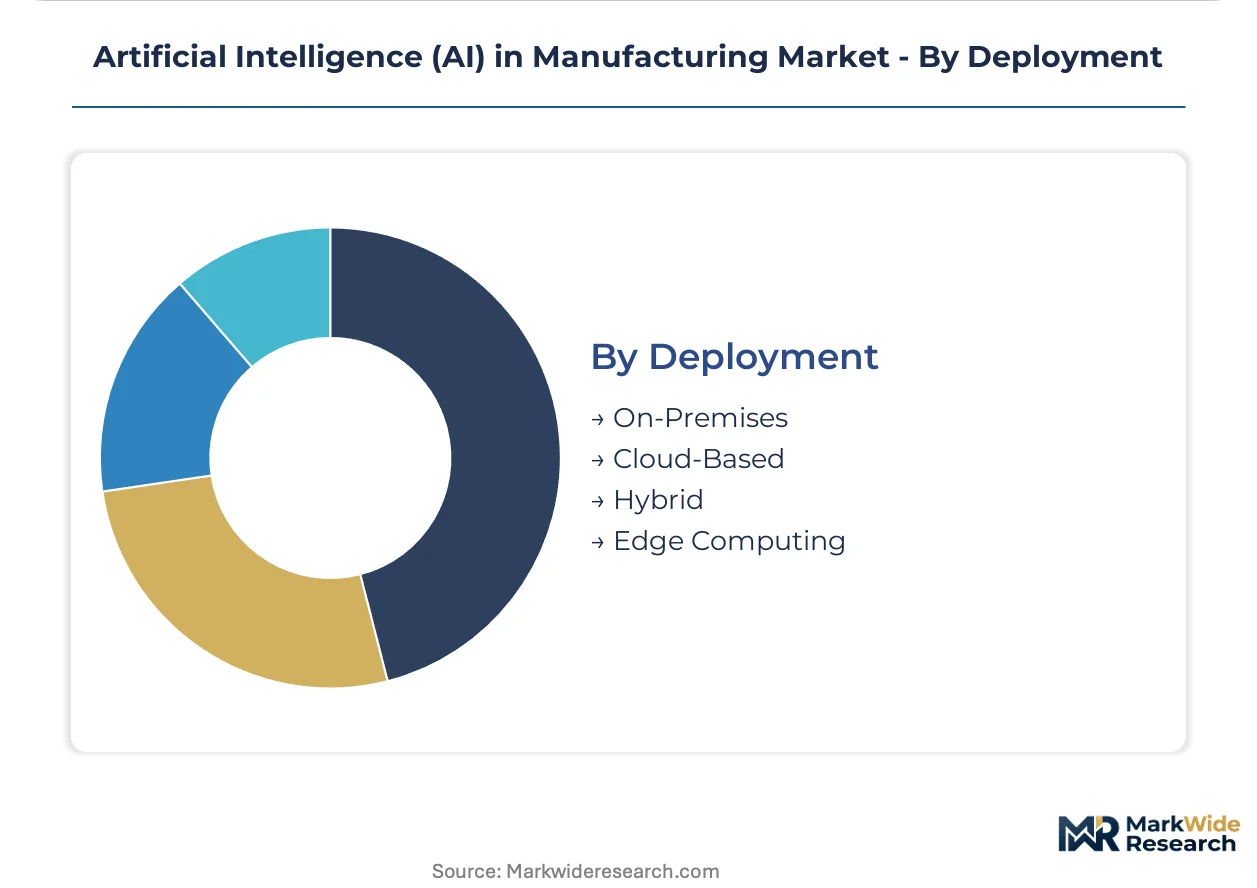
Deployment:
Maturity gradients separate established on-premises architectures from emerging edge-native designs, with hybrid configurations bridging legacy PLC environments and cloud-based model training pipelines.
- Edge Computing:GPU clusters deployed directly on factory floors for sub-50ms inference latency. Safety-critical robotic coordination in automotive welding cells prohibits cloud round-trips, forcing capital deployment timeline compression.
- On-Premises:Private data center infrastructure for model training and batch inference. Semiconductor and pharmaceutical manufacturers prioritize this mode for intellectual property protection and regulatory audit trail requirements.
- Cloud-Based:Centralized compute for non-time-sensitive workloads including supply chain optimization and historical trend analysis. Consumer goods manufacturers with distributed plant networks favor this for rapid scaling without infrastructure capital.
- Hybrid:Edge inference with cloud model retraining pipelines. This architecture accommodates legacy PLC integration friction while enabling continuous algorithm improvement from aggregated fleet data.
On-Premises retains largest installed base. Edge Computing is climbing the fastest as latency requirements harden across safety-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement offices and semiconductor fabrication operators concentrate AI manufacturing demand across four distinct national production ecosystems. Each geography deploys regulatory frameworks and industrial clustering mechanisms that reshape vendor qualification protocols and capital deployment timelines.
United States
FDA software-as-medical-device precedents cascade into diagnostic equipment manufacturing standards, compelling AI-enabled production line documentation. OSHA machine guarding standards adapt to accommodate collaborative robots running computer vision systems. Automotive assembly plants in Michigan and South Carolina anchor tier-one supplier networks demanding predictive maintenance performance guarantees.
Germany
EU AI Act conformity assessments mandate third-party evaluation for quality-control algorithms influencing product safety. ISO/IEC 23053 trustworthiness frameworks reorganize industrial AI procurement protocols. Siemens and Bosch anchor smart factory ecosystems in Baden-Württemberg and Bavaria, accelerating technology diffusion through shared infrastructure.
China
MIIT smart manufacturing initiatives subsidize edge computing deployments in Yangtze River Delta electronics clusters. Dual carbon goals drive AI-powered process optimization in steel and chemical processing. Shenzhen and Shanghai fabrication zones concentrate GPU-accelerated inference hardware procurement for sub-50ms latency requirements.
India
PLI scheme manufacturing incentives subsidize smart factory investments in electronics and automotive sectors. BIS standards for industrial automation equipment reshape vendor qualification requirements. Karnataka and Tamil Nadu greenfield plants embed AI-native architecture without legacy PLC migration costs.
Japan
METI Society 5.0 roadmaps prioritize predictive maintenance for aging industrial infrastructure. JIS standards for collaborative robot safety certification propagate through automotive supplier chains. Nagoya industrial corridor Toyota production facilities demand anomaly detection algorithms with single-fiscal-cycle ROI documentation.
Artificial Intelligence (AI) in Manufacturing Market Vendor Landscape
Player mix skews toward diversified technology conglomerates with cloud infrastructure assets and specialized automation OEMs with embedded AI portfolios. Market structure exhibits tiered consolidation around GPU hardware suppliers, hyperscale cloud operators, and industrial automation incumbents. Two strategic archetypes dominate: semiconductor vendors supplying inference acceleration hardware and system integrators bundling edge-to-cloud software stacks. Competitive moves center on strategic partnerships bridging IT-OT convergence and geographic expansion into German and Indian industrial clusters.
Within the semiconductor acceleration tier, NVIDIA Corporation and Intel Corporation exemplify divergent architectural approaches to factory floor inference deployment. NVIDIA dominates GPU-accelerated inference for sub-50ms quality inspection latency requirements. Intel leverages OpenVINO toolkit positioning for edge AI pipelines in discrete manufacturing environments. Microsoft Corporation occupies a position among hyperscale cloud operators extending industrial IoT platforms to compete for process industry AI operations, anchoring the software-centric competitive vector.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Amazon.com Inc. |
| SAP SE |
| Rockwell Automation Inc. |
| Alphabet Inc. |
| Microsoft Corporation |
| IBM |
| General Electric Company |
| Others |
Supply Flow & Price Mechanics
ISO/IEC 23053 trustworthiness certification gates both vendor qualification and price differentiation simultaneously, compelling manufacturers to absorb audit costs that stratify procurement tiers across industrial AI deployments.
Pricing Analysis
Cost-plus contracts with GPU hardware indexation dominate predictive maintenance suites, while outcome-based pricing tied to measured downtime reduction anchors quality control modules. Three-tier pricing structure across premium, standard, and economy levels separates Siemens-anchored ecosystems from mid-tier system integrators and SaaS-native entrants. Pricing pressure stems from NVIDIA GPU supply concentration forcing buyers toward long-term offtake commitments. Tier-one automotive OEMs in Germany exhibit lowest price sensitivity, demanding performance guarantees over feature checklists, while mid-sized discrete manufacturers face acute budget constraints.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for GPU inference accelerators, while Germany and the United States concentrate industrial automation hardware production. The supply chain draws from rare earth elements for sensor components, silicon wafers for embedded vision processors, and cobalt for battery-backed edge installations. Single-source vulnerability concentrates in NVIDIA's foundry relationships, exposing procurement timelines to geopolitical export controls. Distribution runs through automation OEM channel partnerships in Baden-Württemberg and system integrator networks in Michigan and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-tier classification creates a regulatory inflection that will compress deployment timelines for quality-control algorithms while elevating compliance costs as the primary competitive filter.
For Market Incumbents: Compound defensible positions through backward integration into GPU-accelerated hardware supply chains and captive development of ISO/IEC 23053 certification capabilities. Threats from SaaS-native entrants with outcome-based pricing models demand channel control reinforcement in German automotive supplier tiers. Priority levers include edge-native inference architecture R&D and long-term offtake agreements with foundry operators. For New Entrants and Emerging Players: Differentiate on latency engineering specialization for sub-50ms safety-critical applications, targeting electronics assembly lines in India's PLI-subsidized greenfield plants. The most penetrable white space sits in mid-sized discrete manufacturing where legacy PLC integration friction has stalled incumbent deployments. Go-to-market angles should emphasize subscription-based computer vision modules with rapid workstation-level deployment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge computing infrastructure as GPU cluster deployment timelines compress. Long-term viability favors vendors with demonstrated EU AI Act conformity assessment completion and transferable FDA software-as-medical-device credentials. Acquisition target archetypes include embedded vision processor specialists with automotive tier-one relationships. The signal to watch is OSHA machine guarding standard finalization timing for collaborative robot certification.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Inference Architecture Deployment | Sub-50ms latency requirements in automotive welding cells force capital reallocation toward factory-floor GPU clusters. |
| EU AI Act Conformity Assessment Completion | Third-party evaluation documentation becomes mandatory gating factor for quality-control algorithm procurement in European markets. |
| Outcome-Based Pricing Model Adoption | Performance guarantees tied to measured downtime reduction displace feature-checklist procurement in Germany's automotive supplier tier. |
| Backward Integration into GPU Supply | Long-term foundry offtake agreements mitigate NVIDIA supply concentration vulnerability for tier-one automation OEMs. |
| Digital Twin-Physics Simulation Convergence | Real-time sensor feeds into finite element models enable closed-loop optimization in chemical processing industries. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted, spanning plant engineers at automotive OEMs in Michigan and Bavaria, AI procurement leads at tier-one electronics manufacturers, system integrators specializing in cobot deployments, and edge infrastructure architects at semiconductor fabs. Secondary validation drew from SEC filings of automation conglomerates, EU AI Act implementation guidance documents, FDA software-as-medical-device precedents, and hyperscaler industrial IoT platform disclosures. Bottom-up deployment estimates triangulated against top-down technology spending projections across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including technology type, application purpose, end-user vertical, and deployment architecture, with regional regulatory cluster as an additional cross-cutting variable. CAGRs were derived from weighted average growth contributions across these segments, incorporating inputs from capital expenditure tracking in German industrial clusters and PLI scheme disbursement patterns in Indian electronics manufacturing.
The analysis sits within stated boundaries; outcomes outside sustained GPU hardware availability, stable EU-US regulatory alignment, and continued automotive OEM capital expenditure would require recalibration. Forecasts reflect documented assumptions regarding edge inference latency requirements and legacy PLC integration friction persistence. Recalibration cycles align with material shifts in OSHA machine guarding standard finalization and EU AI Act enforcement precedent establishment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
AI Dubbing Software Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
Egypt Artificial Intelligence Market
Artificial Intelligence (AI)
Industrial Artificial Intelligence [AI] Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Supermarket AI-Powered Checkout Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations Platform Market
Artificial Intelligence (AI)
AI in Food & Beverages Market
Artificial Intelligence (AI)
Artificial Intelligence Systems Spending Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Radiology Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Brain Computer Interface Market