
 Cognitive Services Platform Market | 2026-2036
Cognitive Services Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Cognitive Services Platform Market Analysis
Enterprise IT departments is collapsing as the dominant buyer archetype for cognitive services platforms, while line-of-business units in healthcare and finance gain procurement authority. Microsoft Corporation leverages its Azure AI stack to anchor enterprise deployments across hybrid cloud environments. Amazon Web Services competes through specialized speech recognition APIs that dominate contact-center automation. IBM Corporation differentiates via Watson Health integrations that sustain long-term contracts with hospital networks.
Cognitive services platforms deliver programmable APIs for vision, language, speech, and decision functions, typically accessed through REST endpoints with sub-100-millisecond latency requirements for real-time inference. These systems enable industrial automation, customer service orchestration, and clinical diagnostic support without requiring bespoke model development. Natural language processing leads deployment volumes among application segments, while image analysis captures premium pricing in quality-control manufacturing use cases. Cloud-based deployment is accelerating fastest as financial institutions prioritize elastic compute for fraud detection workloads, though on-premises installations retain share where data residency rules apply.
The EU AI Act imposes conformity assessments on high-risk cognitive applications including biometric identification and credit scoring, forcing vendors to restructure product roadmaps for European market access. In the United States, FDA guidance on software-as-a-medical-device shapes how healthcare providers deploy diagnostic algorithms, while NIST AI Risk Management Framework influences federal procurement standards. Stakeholders must monitor divergence between Brussels and Washington regulatory timelines to avoid stranded development investments.
Market Dynamics
Enterprise procurement authority is fragmenting across line-of-business units, collapsing the traditional IT department gatekeeper role and forcing vendors to rebuild sales motions around clinical, financial, and operational stakeholders rather than centralized technical buyers.
Growth Catalysts
- Federal AI procurement guidelines:United States government mandates for responsible AI acquisition are creating structured demand pipelines for certified cognitive services vendors serving defense and civilian agencies.
- Contact-center automation:Speech recognition APIs are displacing legacy interactive voice response systems as enterprises pursue real-time sentiment analysis and agent augmentation.
- Clinical documentation burden:Healthcare providers in the United States are deploying natural language processing tools to reduce physician administrative time and mitigate burnout-related staffing losses.
Market Restraints
- GPU supply concentration:Inference hardware dependency on Taiwan-based semiconductor fabrication creates vulnerability to geopolitical disruption and allocation rationing.
- EU AI Act conformity costs:High-risk system classification for biometric identification and credit scoring forces vendors to restructure product architectures for European market access.
- On-premises data residency requirements:Financial institutions in Germany and Switzerland maintain captive infrastructure for fraud detection workloads, limiting pure-cloud expansion.
Strategic Opportunities
- Edge inference deployment:Manufacturing quality-control applications in Japan and South Korea are driving demand for sub-50-millisecond vision processing outside centralized data centers.
- Software-as-a-medical-device pathways:FDA guidance on diagnostic algorithms creates regulatory clarity for hospital networks seeking clinical decision support integration.
- Multimodal API convergence:Unified endpoints combining vision, language, and speech functions are enabling industrial automation vendors to reduce integration complexity for smart factory deployments.
Industry Challenges
- MLops talent scarcity:Production deployment of cognitive services requires scarce specialists capable of managing model drift, versioning, and monitoring at enterprise scale.
- Legacy system interoperability:Hospital electronic health record systems and manufacturing execution systems demand custom middleware development for cognitive API integration.
- NIST AI Risk Management Framework alignment:Federal contractors face documentation and audit burdens to demonstrate conformity with emerging procurement standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cognitive Services Platform Market |
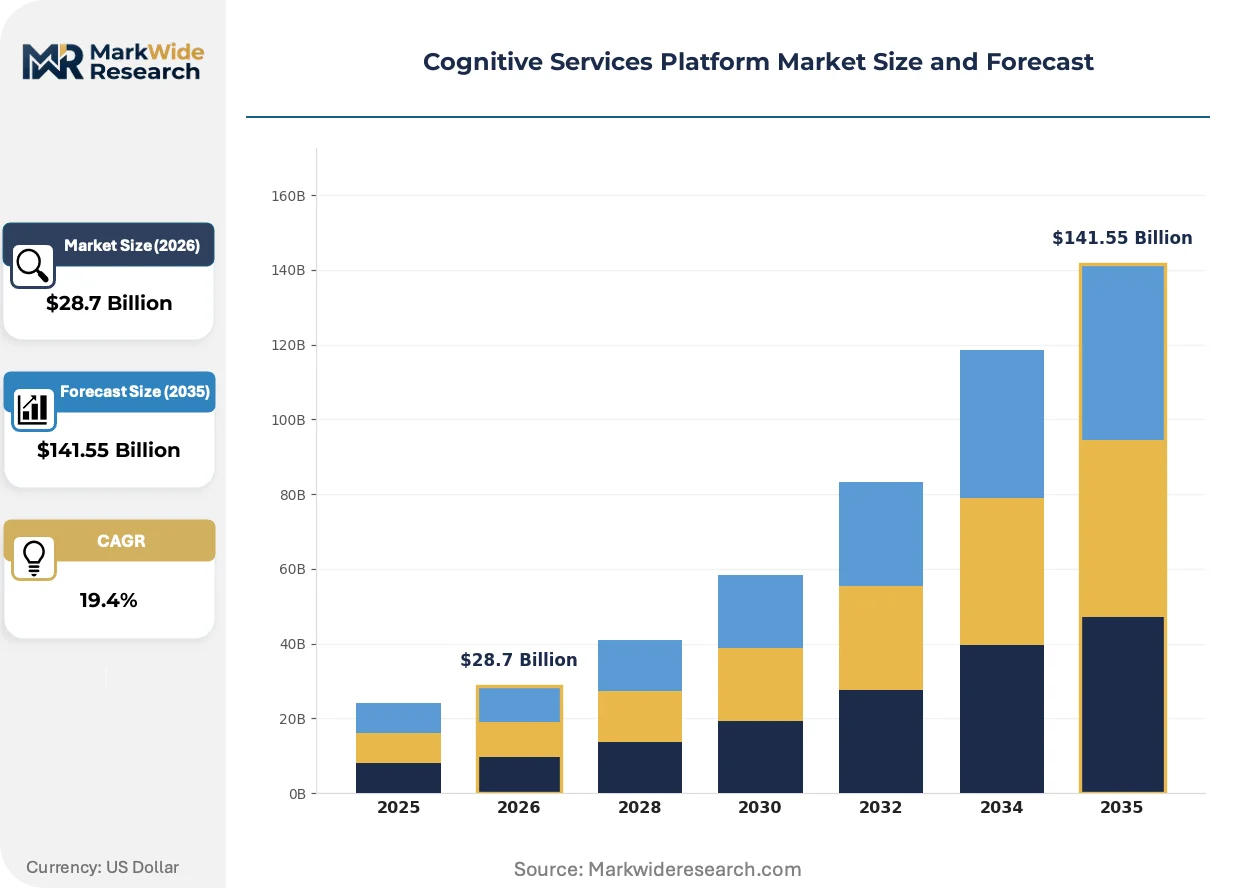
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $141.55 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Natural Language Processing, Speech Recognition, Image Analysis, Facial Recognition End User: Healthcare Providers, Retail Chains, Financial Institutions, Education Sector Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Multi-Tenant Technology: Machine Learning, Deep Learning, Neural Networks, AI Model Training |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Google LLC, IBM Corporation, Oracle Corporation, SAS Institute, SAP SE, Nuance Communications, Attivio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cognitive Services Platform Market Emerging Trajectories
Foundation model architectures are commoditizing core cognitive capabilities, forcing vendors to differentiate through vertical specialization, latency optimization, and regulatory pre-certification rather than raw performance benchmarks.
Small language models optimized for specific domains are fragmenting the inference landscape. Medical device manufacturers and industrial automation vendors are deploying these compressed architectures to achieve on-device processing without cloud dependency. This shift is fragmenting vendor concentration in natural language processing and enabling regional specialists to capture niche applications previously dominated by hyperscale providers.
The EU AI Act's risk-tier classification system is restructuring product development roadmaps. High-risk designations for biometric identification and credit scoring impose conformity assessment requirements that extend time-to-market by 12-18 months for affected applications. European healthcare providers are responding by prioritizing lower-risk clinical documentation tools over diagnostic algorithms until regulatory clarity solidifies.
Hospital procurement committees are consolidating vendor relationships around integrated platform stacks rather than best-of-breed point solutions. This consolidation favors suppliers offering unified vision, language, and speech APIs with pre-negotiated enterprise licensing. The pattern is most visible in United States health systems pursuing digital transformation initiatives under constrained capital budgets.
Cognitive Services Platform Market Segmentation
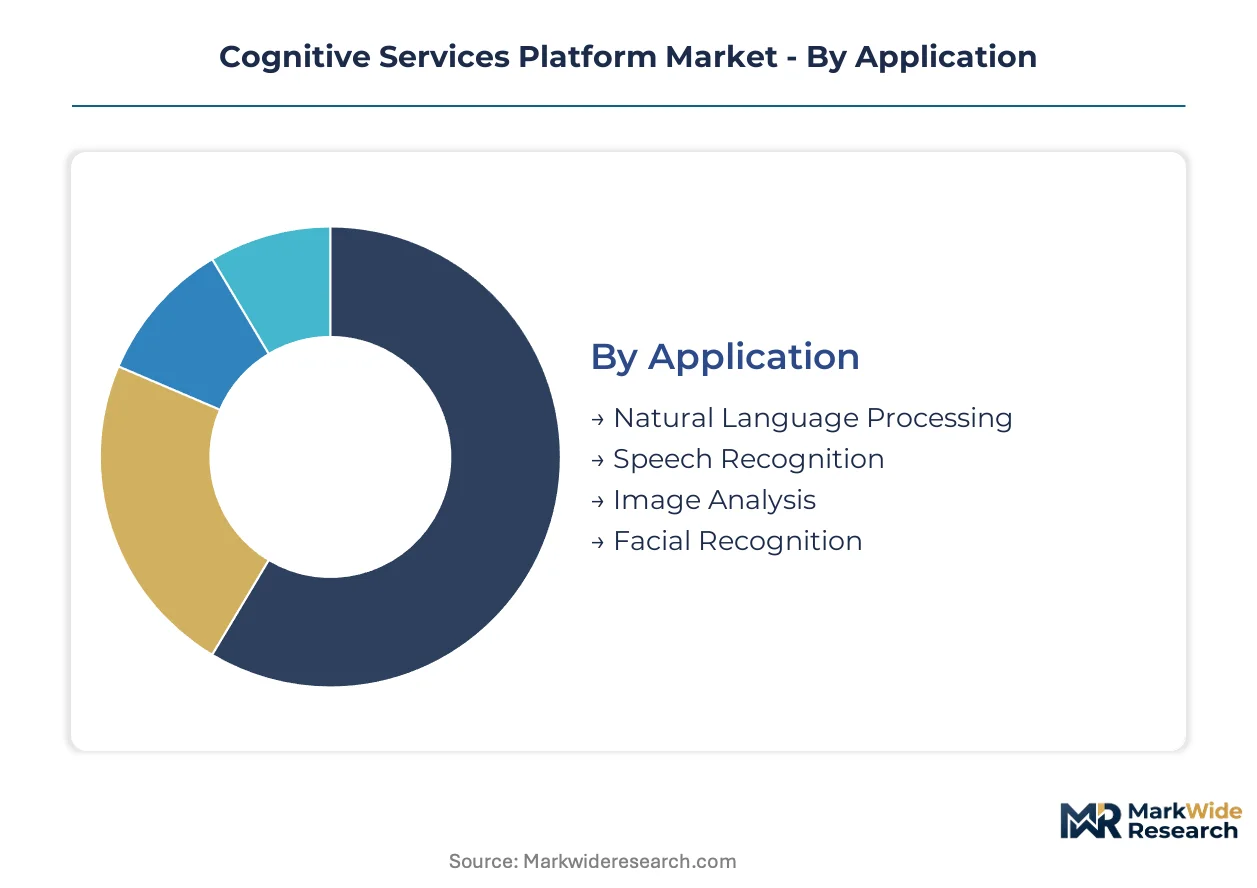
Cognitive services platforms fragment across four critical dimensions that determine procurement authority, compliance burden, and integration complexity. Application type dictates whether EU AI Act conformity assessments apply. Deployment mode shapes data residency obligations and latency performance. End-user vertical determines pricing tolerance and regulatory exposure. Technology foundation influences talent requirements and infrastructure investment.
Application:
EU AI Act risk-tier classification creates divergent compliance pathways across cognitive functions, with biometric and credit-scoring applications facing mandatory conformity assessments while clinical documentation tools navigate lighter oversight.
- Natural Language Processing:Programmable APIs for text generation, sentiment analysis, and document summarization. Healthcare providers in the United States deploy these tools to reduce physician administrative burden and mitigate staffing attrition. Demand concentrates where FDA software-as-a-medical-device guidance permits clinical documentation without full diagnostic classification.
- Speech Recognition:Real-time audio transcription and voice command processing with sub-100-millisecond latency requirements. Contact-center operators in the United States displace legacy interactive voice response systems for agent augmentation and sentiment analysis. The technology dominates enterprise automation budgets due to immediate ROI visibility.
- Image Analysis:Computer vision APIs for defect detection, medical imaging interpretation, and quality control. Manufacturing execution systems in Japan and South Korea demand sub-50-millisecond edge deployment for production line integration.
- Facial Recognition:Biometric identification systems subject to EU AI Act high-risk classification. European market access requires extended conformity assessments that stretch time-to-market by 12-18 months.
Established volume favors Natural Language Processing; emerging adoption favors Image Analysis.
End User:
Procurement authority fragmentation across line-of-business units collapses centralized IT gatekeeping, forcing vendors to rebuild sales motions around clinical, financial, and operational stakeholders with divergent compliance priorities.
- Healthcare Providers:Hospital networks and integrated delivery systems deploying diagnostic algorithms and clinical documentation tools. FDA guidance on software-as-a-medical-device shapes deployment architecture, while physician burnout drives administrative automation spending. Procurement committees consolidate around unified platform stacks rather than point solutions.
- Financial Institutions:Banks and insurers prioritizing elastic compute for fraud detection and credit scoring workloads. German and Swiss institutions maintain on-premises infrastructure for data residency compliance, constraining pure-cloud expansion. EU AI Act high-risk classification for credit scoring imposes conformity cost burdens.
- Retail Chains:Customer service orchestration and inventory vision systems. Demand clusters around contact-center automation and supply chain quality control with moderate regulatory exposure.
- Education Sector:Administrative automation and accessibility tools with lower compliance complexity. Procurement cycles extend due to constrained capital budgets and distributed decision authority.
Healthcare Providers capture premium pricing; Financial Institutions drive infrastructure hybridization.
Deployment:
Data residency rules and latency requirements fragment infrastructure strategy, with cloud acceleration in financial fraud detection coexisting alongside captive installations where sovereign compliance mandates apply.
- Cloud-Based:Elastic compute accessed through REST endpoints with centralized model management. Financial institutions in the United States prioritize this mode for fraud detection scalability. The architecture accelerates fastest where data sovereignty rules permit.
- On-Premises:Captive infrastructure for biometric data, classified workloads, and regulated industries. German financial institutions and Swiss healthcare providers maintain this deployment for residency compliance.
- Hybrid Solutions:Split architectures routing sensitive processing on-premises while leveraging cloud for model training. Hospital networks adopt this pattern to balance FDA audit requirements with compute elasticity.
- Multi-Tenant:Shared infrastructure with tenant isolation for cost-sensitive mid-market buyers. Education sector procurement favors this mode for administrative automation workloads.
Cloud-Based deployment climbs the fastest; On-Premises retains structural share.
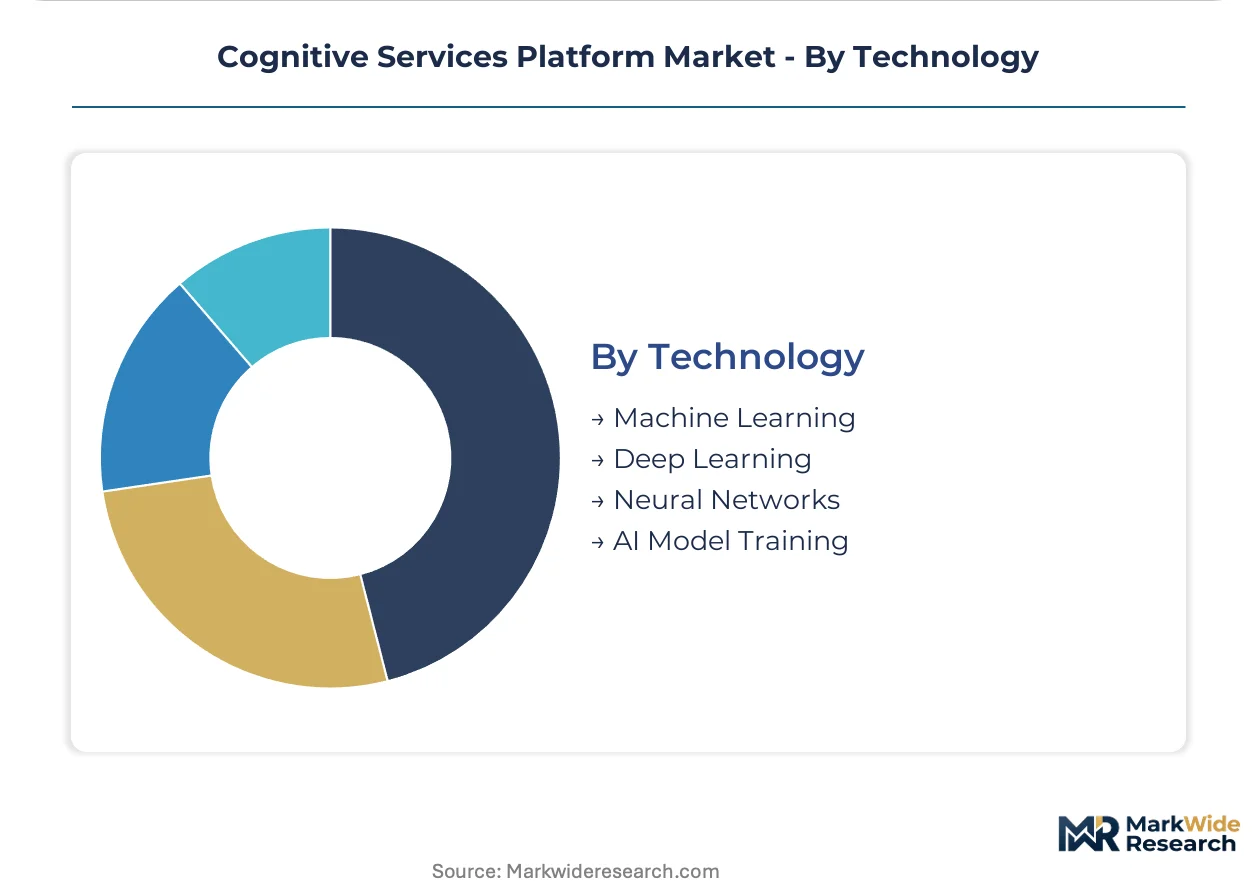
Technology:
Foundation model commoditization forces differentiation through vertical specialization and latency optimization rather than raw performance benchmarks, compressing margins for undifferentiated infrastructure.
- Machine Learning:Statistical pattern recognition and predictive modeling with established MLOps tooling. Mature deployment pipelines support enterprise scale, though talent scarcity constrains production management.
- Deep Learning:Multi-layer neural architectures for complex perception tasks. GPU supply concentration from Taiwan-based fabrication creates geopolitical vulnerability and allocation rationing.
- Neural Networks:Biologically-inspired computation for speech and vision processing. Small language model compression enables on-device deployment without cloud dependency.
- AI Model Training:Custom model development and fine-tuning services. Hospital networks and industrial automation vendors demand this capability for domain-specific diagnostic and quality-control applications.
Machine Learning holds established volume; AI Model Training shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transatlantic fiber cables and cloud region interconnects anchor demand concentration across the United States, Germany, Japan, United Kingdom, and South Korea. These infrastructure assets enable sub-100-millisecond API latency that industrial automation and clinical diagnostics require.
United States
Federal AI procurement guidelines and FDA software-as-a-medical-device pathways drive healthcare provider adoption. NIST AI Risk Management Framework shapes defense and civilian agency contracting standards. Hospital networks in the Boston-Cambridge cluster consolidate vendor relationships around unified platform stacks for digital transformation.
Germany
On-premises data residency requirements from financial institutions sustain captive infrastructure demand. EU AI Act conformity assessments impose 12-18 month delays for high-risk biometric and credit-scoring deployments. Industrial automation vendors in the Stuttgart region pursue edge inference for manufacturing quality-control applications.
Japan
Sub-50-millisecond latency requirements from automotive and electronics manufacturers accelerate edge deployment. METI standards for AI quality and safety shape enterprise procurement criteria. Manufacturing execution systems in the Nagoya-Toyota corridor integrate vision APIs for production line defect detection.
United Kingdom
NHS procurement frameworks for clinical documentation tools reduce physician administrative burden. MHRA guidance on software-as-a-medical-device creates regulatory clarity for diagnostic algorithm deployment. London-based fintech clusters drive elastic compute demand for fraud detection workloads.
South Korea
Smart factory initiatives from electronics conglomerates fragment inference across compressed small language models. MFDS medical device regulations shape healthcare AI deployment architecture. Seoul-Incheon industrial zones prioritize multimodal API convergence for automation integration complexity reduction.
Cognitive Services Platform Market Vendor Landscape
Listed hyperscale cloud providers compete with private enterprise software specialists across hybrid deployment architectures and vertical integration depth. Market structure concentrates around three-tier vendor stratification: full-stack platform operators, API-specialist pure-plays, and regional system integrators. Dominant archetypes include cloud-native infrastructure bundlers, healthcare-focused compliance specialists, and edge-optimized latency providers. Competitive moves center on M&A for vertical capability acquisition and strategic partnerships for regulatory pre-certification.
Within the full-stack platform tier, Microsoft Corporation and Amazon Web Services anchor enterprise deployment authority through cloud infrastructure integration, while IBM Corporation exemplifies the vertical-specialist archetype sustaining long-term contracts through healthcare system entrenchment. These three entities represent the dominant competitive anchors that shape procurement committee consolidation patterns across hospital networks and financial institutions.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Google LLC |
| IBM Corporation |
| Oracle Corporation |
| SAS Institute |
| SAP SE |
| Nuance Communications |
| Attivio |
| Others |
Supply Flow & Price Mechanics
Hyperscale cloud capacity utilization above eighty percent anchors price floors for cognitive API tiers, concentrating supply leverage among Taiwan-based GPU foundries and compressing margins for second-tier inference providers. This scale dynamic forces smaller vendors toward vertical specialization or edge-optimized latency offerings to escape commodity pricing traps.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise commitment levels, with annual contract value thresholds separating premium managed-service tiers from standard self-serve API access. Price differentiation hinges on latency guarantees and EU AI Act pre-certification status, with healthcare providers showing lowest sensitivity due to bundled compliance value. Pricing pressure stems from foundation model commoditization, while education sector buyers exhibit highest price elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate cloud infrastructure provisioning, though strategic stockpiling of NVIDIA H100 accelerators has emerged among tier-one providers. GPU fabrication concentrates in Taiwan, South Korea, and the United States, with advanced packaging dependencies drawing from Japan and Malaysia. Single-source vulnerability in TSMC's CoWoS capacity feeds supply chain risk. Distribution runs through hyperscaler marketplaces and direct enterprise licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cognitive services platforms sit in early-cycle expansion, with clinical documentation automation in United States hospital networks providing sustained adoption tailwinds through physician productivity mandates.
For Market Incumbents: Shield market position by deepening healthcare vertical integration through FDA pre-certified diagnostic pathways, while accelerating edge inference partnerships with Japanese automotive suppliers to offset cloud commoditization threats from open-source foundation models. For New Entrants and Emerging Players: Lead with specialized small language model deployments for German manufacturing quality control, where sub-50-millisecond latency requirements and data residency rules create defensible white space against hyperscale incumbents. For Investors and Strategic Acquirers: Healthcare compliance specialists with pre-negotiated hospital GPO contracts represent the highest-conviction acquisition archetype. Long-term viability across the analysis window rests on regulatory pre-certification moats. Watch FDA software-as-a-medical-device clearance velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Pre-Certification | Accelerates European market access for biometric and credit-scoring applications by 12-18 months. |
| Edge Inference Partnership | Captures Japanese automotive and electronics manufacturing demand outside centralized cloud infrastructure. |
| Hospital System GPO Consolidation | Locks in multi-year platform commitments under constrained United States health system capital budgets. |
| Small Language Model Acquisition | Enables on-device clinical documentation without cloud dependency for physician workflow integration. |
| Multi-Modal API Convergence | Reduces smart factory integration complexity for Seoul-Incheon industrial automation vendors. |
Methodological Framework
The analysis maps natural language processing, speech recognition, image analysis, and facial recognition sub-sectors, each validated through platform engineering leads, hospital procurement committees, financial services CTOs, and manufacturing automation directors. Primary interview findings triangulate against hyperscaler capex disclosures, FDA software-as-a-medical-device filings, EU AI Act implementation guidance, and hospital GPO contract databases. Bottom-up deployment volume estimates reconcile with top-down cloud infrastructure spending patterns.
Consistency checks validate outputs against external benchmarks including hyperscaler AI revenue segment disclosures and enterprise software spending surveys. The analytical framework models deployment mode, end-user vertical, application type, and regulatory risk tier across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves and infrastructure capacity expansion schedules, with inference hardware allocation constraints and EU conformity timeline assumptions as critical inputs.
Underlying assumptions cover cloud migration velocity, GPU supply normalization, and transatlantic regulatory convergence, with deviation risk concentrated in Taiwan semiconductor fabrication disruption and EU AI Act enforcement variance. Practitioners should keep alternative scenarios live as federal procurement guideline implementations and foundation model commoditization trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Reinforcement Learning Market
Artificial Intelligence (AI)
Global Augmented Intelligence Market
Artificial Intelligence (AI)
Chatbot Market
Artificial Intelligence (AI)
Intelligent Personal Assistant Market
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
Global Conversational Systems Market
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
AI Search Engine Market
Artificial Intelligence (AI)
Europe Artificial Intelligence Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Software Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Global Conversational AI Platform Software Market
Artificial Intelligence (AI)
Semantic Web Market