
 Global Artificial Intelligence SAAS Market | 2026-2036
Global Artificial Intelligence SAAS Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Intelligence SAAS Market Foresight
Modular unbundling of AI SAAS into discrete API-accessible microservices is hardening as the dominant packaging pattern. Microsoft Corporation leverages its Azure OpenAI integration to anchor enterprise workloads across hybrid cloud environments. Amazon Web Services sustains market presence through breadth in machine learning infrastructure and dedicated AI chip availability. Google Cloud differentiates via proprietary tensor processing hardware and deep integration with enterprise data analytics pipelines.
Artificial Intelligence SAAS denotes software-delivered machine learning, natural language processing, and computer vision capabilities accessed via subscription models over cloud infrastructure, typically requiring GPU-accelerated compute clusters and RESTful API endpoints for real-time inference. The primary commercial purpose is to democratize advanced AI capabilities without requiring clients to build or maintain underlying hardware, model training pipelines, or MLOps infrastructure. Public cloud deployment dominates current revenue volume due to lower barrier-to-entry and elastic scaling economics, while hybrid cloud configurations capture expanding margin pools from regulated industries requiring on-premise data residency. Machine learning platforms lead solution offering revenue, though computer vision applications in manufacturing quality control and autonomous systems represent the fastest-expanding segment within the solution portfolio.
The EU AI Act and GDPR impose mandatory risk classification, transparency documentation, and human oversight requirements on AI SAAS providers serving European enterprises, directly shaping product architecture and compliance tooling investment. In the United States, FDA guidance on AI-enabled medical devices and NIST AI Risk Management Framework influence development priorities for healthcare-facing solutions. Stakeholders must monitor evolving cross-border data localization mandates and emerging sector-specific AI liability standards that will determine market access conditions and competitive positioning in the next phase of commercial expansion.
Market Dynamics
Modular API-first architectures are compressing deployment timelines for enterprise AI workloads while fragmenting vendor lock-in patterns across the Global Artificial Intelligence SAAS Market. This structural unbundling is redistributing margin pools from integrated suites toward specialized inference microservices.
Growth Catalysts
- Federal AI Procurement Directives:United States government mandates for cloud-native machine learning infrastructure are accelerating vendor certification pipelines and expanding addressable public sector spend.
- Diagnostic Imaging Workflows:Healthcare providers in Germany, France, and the United Kingdom are deploying computer vision APIs for radiology triage, creating sustained demand for GDPR-compliant inference endpoints.
- GPU-Accelerated Compute Clusters:Elastic provisioning of NVIDIA and AMD hardware through hyperscaler marketplaces is eliminating capital barriers for mid-market model training.
Market Restraints
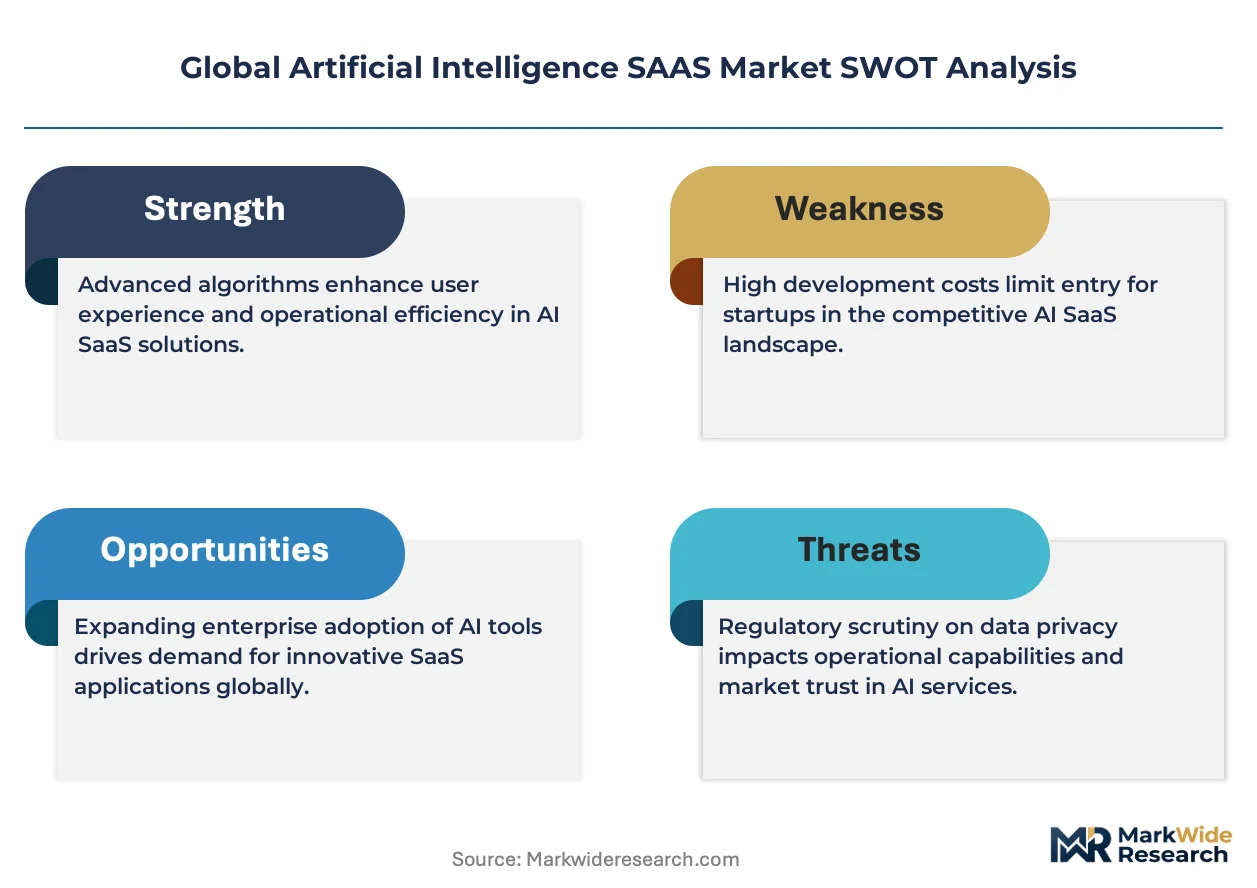
- EU AI Act Compliance Burden:Mandatory risk classification and transparency documentation for high-risk applications are extending sales cycles and inflating legal review costs for providers serving European enterprises.
- Hyperscaler Concentration:Compute capacity for training large language models concentrates among three United States-based cloud operators, creating single-source vulnerability for training-intensive workloads.
- Data Residency Requirements:Cross-border localization mandates in China, Russia, and Saudi Arabia are forcing redundant infrastructure deployment and fragmenting operational scale.
Strategic Opportunities
- Explainable AI Tooling:NIST AI Risk Management Framework alignment is creating premium pricing power for vendors offering auditable model lineage and bias detection dashboards.
- Manufacturing Quality Control:Computer vision microservices for defect detection in automotive and electronics assembly lines remain underpenetrated in Mexico, Vietnam, and Poland.
- Hybrid Cloud Configurations:On-premise inference clusters with cloud-based model updates are capturing margin pools from financial services and defense contractors requiring air-gapped deployment.
Industry Challenges
- MLOps Talent Scarcity:Pipeline engineering and model observability expertise commands premium compensation, compressing margins for service-heavy implementation contracts.
- Legacy System Integration:Mainframe and on-premise data warehouse connectivity requires custom middleware development, extending proof-of-concept timelines for Fortune 500 accounts.
- API Standardization Delays:Competing inference protocols from OpenAI, Anthropic, and open-source foundations are forcing vendors to maintain redundant endpoint architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Intelligence SAAS Market |
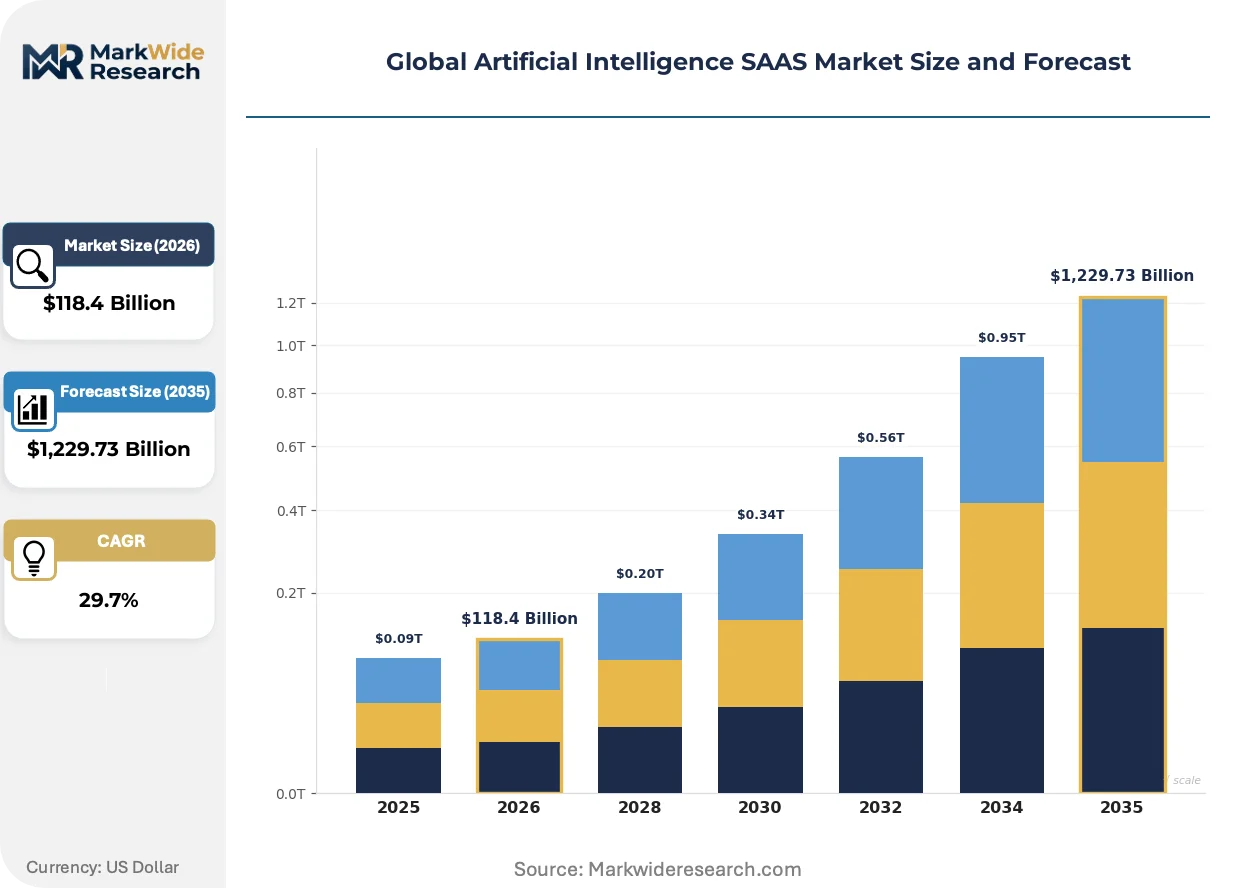
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $1,229.73 Billion |
| CAGR (2026 – 2036) | 29.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, Community Cloud Solution Offering: Machine Learning Platforms, Natural Language Processing, Computer Vision, Robotic Process Automation, Speech Recognition Use Case: Fraud Detection, Customer Insights, Predictive Maintenance, Demand Forecasting, Sentiment Analysis End User Industry: Financial Services, Telecommunications, Manufacturing, Government, Education |
| Companies Covered | Microsoft Corporation, Amazon Web Services, Google Cloud, IBM Corporation, Salesforce, Oracle Corporation, C3.ai, Adobe Inc., DataRobot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Intelligence SAAS Market Shifts & Advancements
Foundation model commoditization is compressing differentiation timelines while amplifying the strategic value of proprietary data pipelines and domain-specific fine-tuning capabilities across the Global Artificial Intelligence SAAS Market.
Small language models optimized for edge deployment are absorbing inference workloads previously routed to centralized cloud APIs. Manufacturing quality control teams in Japan and Germany are adopting these compressed architectures for sub-50 millisecond response requirements. This shift is absorbing margin from hyperscaler inference services while enabling on-device privacy compliance for sensitive visual data.
The EU AI Act's mandatory conformity assessments for high-risk systems are restructuring product development roadmaps for healthcare and financial services applications. Providers must now embed human oversight interfaces and model documentation pipelines before commercial release. French and Dutch regulators are enforcing these requirements most aggressively, compressing competitive timelines for compliance-ready platforms.
Consumption-based pricing for inference tokens is displacing fixed subscription contracts among enterprise procurement teams. Mid-market software vendors in India and Brazil are negotiating usage floors with burst elasticity rather than committed annual spend. This behavioral shift is most visible in generative text and image applications where workload volatility exceeds predictable baselines.
Global Artificial Intelligence SAAS Market Segmentation
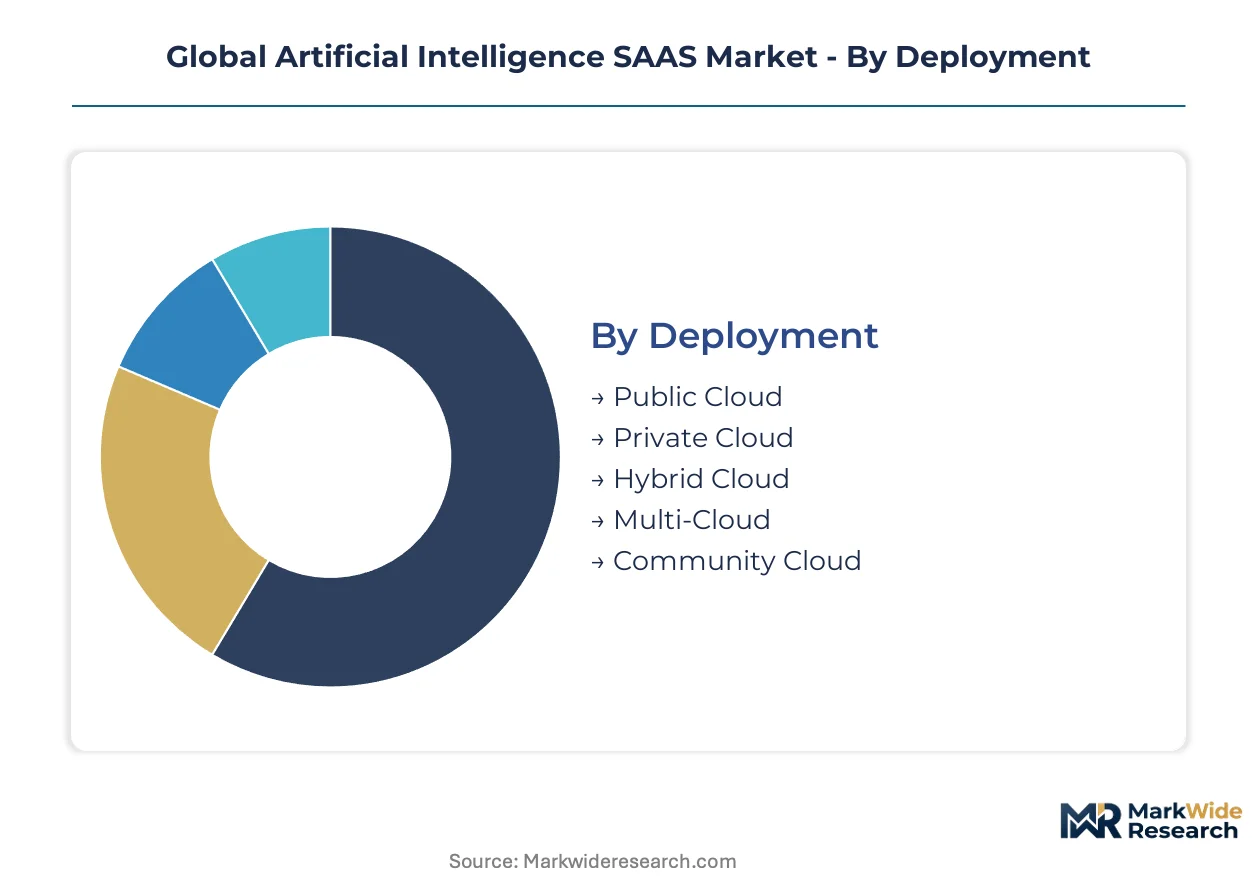
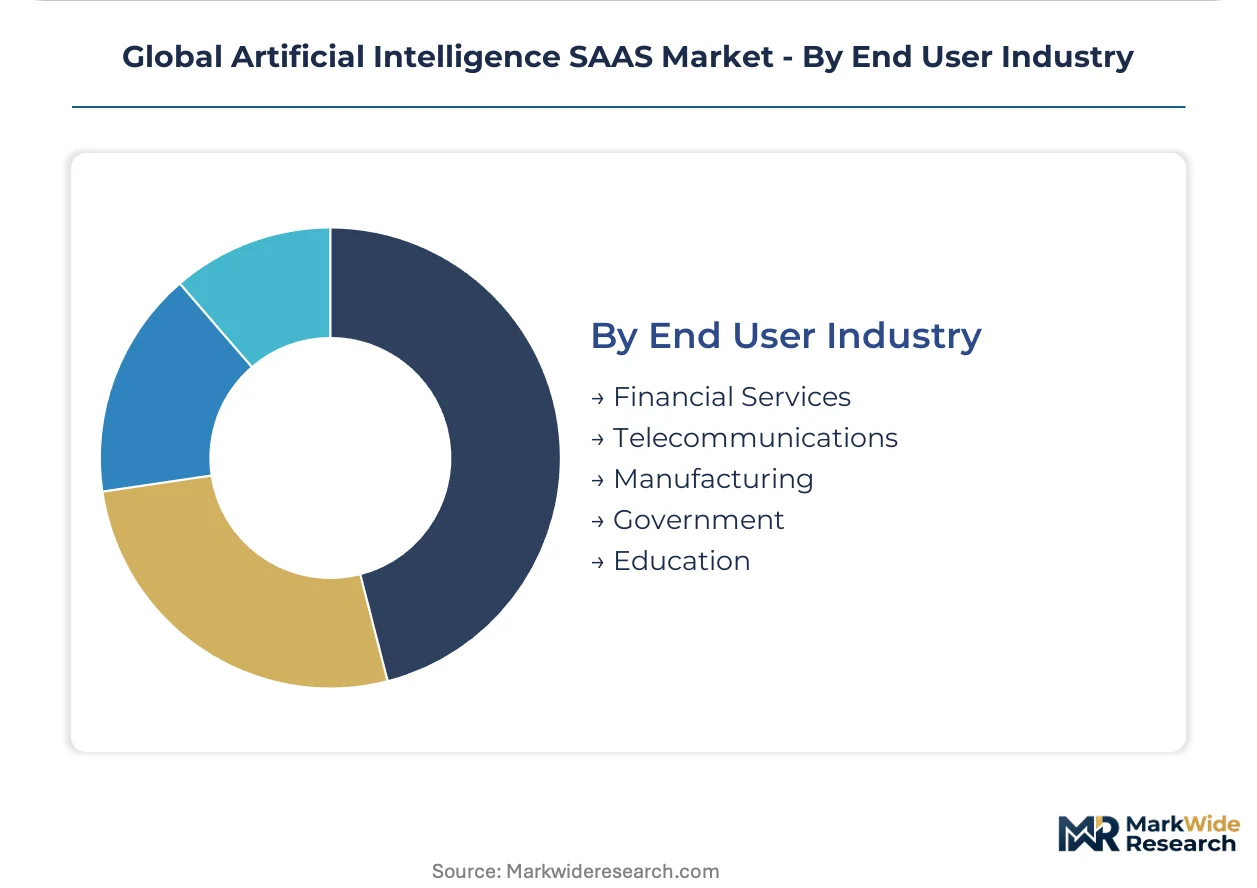
Segmentation reveals how AI SAAS procurement patterns diverge across infrastructure choices, solution types, and industry verticals. Deployment architecture and regulatory constraints reshape vendor selection criteria more sharply than in conventional enterprise software categories.
Deployment:
Upgrade cycles in enterprise infrastructure are compressing as GPU-accelerated compute becomes the bottleneck for AI workload performance, forcing faster refresh decisions than traditional cloud migrations.
- Public Cloud:Elastic provisioning through hyperscaler marketplaces eliminates capital expenditure barriers for model training and inference. Demand concentrates among mid-market software vendors in India and Brazil negotiating usage-based contracts with burst elasticity provisions.
- Hybrid Cloud:On-premise inference clusters with cloud-based model updates capture margin pools from financial services and defense contractors requiring air-gapped deployment for sensitive data residency. German automotive manufacturers and US federal contractors drive premium pricing for these configurations.
- Private Cloud:Dedicated infrastructure serving single-tenant requirements in regulated healthcare and banking sectors.
- Multi-Cloud:Distributed architectures mitigating vendor concentration risk for training-intensive large language model workloads.
- Community Cloud:Shared infrastructure among consortium members in European research collaborations and Canadian healthcare networks.
Public Cloud sits at the top of the volume ranking, with Hybrid Cloud climbing the fastest as regulated industries demand data sovereignty.
Solution Offering:
Cost tier differentiation separates premium model-training platforms from commoditized inference APIs, with middleware tooling capturing expanding margin pools.
- Machine Learning Platforms:End-to-end MLOps pipelines encompassing data preparation, model training, and deployment orchestration. Demand concentrates in United States federal procurement channels and German industrial automation clusters requiring NIST AI Risk Management Framework alignment.
- Computer Vision:Image classification, object detection, and video analysis APIs for manufacturing quality control and diagnostic imaging. Japanese automotive assembly lines and French radiology departments drive sub-50 millisecond latency requirements.
- Natural Language Processing:Text classification, entity extraction, and semantic search capabilities for customer service automation.
- Robotic Process Automation:Workflow automation combining computer vision with deterministic rule engines for document processing.
- Speech Recognition:Transcription and voice command interfaces for contact center modernization and accessibility tooling.
Machine Learning Platforms command the largest revenue share, while Computer Vision expands most quickly on manufacturing quality control penetration.
Use Case:
Application maturity varies sharply, with fraud detection commanding established budgets while sentiment analysis struggles to demonstrate measurable ROI in enterprise procurement cycles.
- Fraud Detection:Real-time transaction scoring and anomaly detection for payment networks and insurance underwriting. United States financial institutions and United Kingdom neobanks embed these capabilities as core infrastructure.
- Predictive Maintenance:Sensor data analysis forecasting equipment failure in industrial machinery. German chemical plants and Japanese steel manufacturers prioritize these deployments for operational continuity.
- Customer Insights:Behavioral clustering and lifetime value prediction for retail and telecommunications.
- Demand Forecasting:Supply chain optimization and inventory positioning for consumer goods distribution.
- Sentiment Analysis:Brand monitoring and customer feedback classification for marketing operations.
Fraud Detection maintains the deepest enterprise penetration, with Predictive Maintenance gaining share fastest on industrial IoT sensor deployment.
End User Industry:
Customer type segmentation exposes divergent procurement sophistication, with financial services demanding explainable AI tooling while education sectors prioritize cost minimization over performance optimization.
- Financial Services:Algorithmic trading, credit scoring, and regulatory reporting automation requiring auditable model lineage. United States banks and United Kingdom insurers mandate bias detection dashboards for EU AI Act compliance.
- Manufacturing:Quality control, predictive maintenance, and supply chain optimization across automotive and electronics assembly. Mexican and Vietnamese factories represent underpenetrated expansion targets for computer vision microservices.
- Telecommunications:Network optimization and customer churn prediction for mobile operators.
- Government:Federal AI procurement directives accelerating cloud-native machine learning infrastructure certification.
- Education:Administrative automation and personalized learning platforms with constrained procurement budgets.
Financial Services leads industry spending, with Manufacturing expanding most rapidly on quality control automation in emerging production clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Artificial intelligence SAAS originated in United States research laboratories and Silicon Valley cloud infrastructure, then diffused through European regulatory frameworks and Asian manufacturing clusters. Geographic concentration now reflects divergent compliance regimes and sector-specific adoption patterns.
United States
Federal procurement directives from the Department of Defense and civilian agencies are accelerating cloud-native machine learning infrastructure deployment. NIST AI Risk Management Framework requirements shape vendor certification pipelines for public sector contracts. Seattle and San Francisco Bay Area hyperscaler headquarters anchor enterprise workload migration, while Boston and Austin clusters specialize in healthcare and defense-facing AI tooling.
Germany
Automotive manufacturers in Stuttgart and Munich are deploying computer vision microservices for quality control automation with sub-50 millisecond latency requirements. EU AI Act mandatory conformity assessments extend sales cycles but create compliance-ready vendor premiums. Industrial automation clusters in Bavaria and Baden-Württemberg drive hybrid cloud configurations for air-gapped manufacturing data residency.
United Kingdom
Financial services firms in London mandate bias detection dashboards and auditable model lineage for algorithmic trading and credit scoring applications. UK regulators align with EU AI Act transparency requirements while maintaining distinct FCA guidance on AI-enabled financial products. Cambridge and Edinburgh research clusters supply specialized talent for natural language processing and fraud detection pipelines.
Japan
Manufacturing quality control teams in Toyota City and Osaka industrial corridors adopt small language models optimized for edge deployment. METI industrial policy promotes domestic AI infrastructure investment alongside international cloud partnerships. Tokyo enterprise procurement teams negotiate consumption-based inference token contracts with burst elasticity provisions for generative workloads.
India
Mid-market software vendors in Bangalore and Hyderabad negotiate usage-based AI SAAS contracts with hyperscaler marketplaces, eliminating capital barriers for model training. RBI guidelines on algorithmic decision-making in financial services create compliance demand for explainable AI tooling. Mumbai financial services and Pune manufacturing clusters represent expanding deployment targets for computer vision and predictive maintenance APIs.
Global Artificial Intelligence SAAS Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance-readiness and hybrid cloud integration depth. The vendor base concentrates among three hyperscalers with GPU-accelerated infrastructure, supplemented by specialized MLOps platforms and vertical-specific application providers. Strategic archetypes include full-stack cloud operators, modular API-first specialists, and domain-tuned application vendors. Competitive moves center on strategic partnerships for model access and geographic expansion through localized data residency configurations.
Within the hyperscaler tier, Microsoft Corporation anchors enterprise workloads through Azure OpenAI integration across hybrid environments. Amazon Web Services sustains market presence through breadth in machine learning infrastructure and dedicated AI chip availability. Google Cloud occupies a position differentiated by proprietary tensor processing hardware and deep integration with enterprise data analytics pipelines. These three exemplify the infrastructure-concentration pattern that shapes competitive dynamics for training-intensive workloads.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Amazon Web Services |
| Google Cloud |
| IBM Corporation |
| Salesforce |
| Oracle Corporation |
| C3.ai |
| Adobe Inc. |
| DataRobot |
| Others |
Supply & Pricing Matrix
MLOps pipeline engineering talent concentrates in Seattle, San Francisco Bay Area, and Bangalore clusters, and labor-cost differentials between these engineering hubs widen pricing-tier spreads across deployment models. Premium hybrid-cloud configurations absorb margin from mid-market public-cloud tiers as compliance-ready expertise commands compensation premiums.
Pricing Analysis
Consumption-based inference token pricing displaces fixed annual subscriptions as the dominant commercial structure. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-compliant EU AI Act certification tiers from uncertified commodity inference endpoints. Price differentiation rests on latency guarantees and human-oversight documentation depth. Cost compression in standard tiers intensifies because GPU hyperscaler marketplace competition erodes committed-spend negotiating leverage. Mid-market software vendors in India and Brazil exhibit highest price sensitivity, while United States federal contractors tolerate premium pricing for air-gapped deployment.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for NVIDIA H100 and AMD MI300 clusters through Microsoft Azure, Amazon Web Services, and Google Cloud marketplaces. Geographic supply concentration centers on Taiwan for TSMC chip fabrication, United States for NVIDIA and AMD chip design, and South Korea for HBM memory modules. Raw material dependencies include high-bandwidth memory stacks, advanced packaging substrates, and specialized cooling fluids. Single-source vulnerability runs through TSMC's monopoly on leading-edge GPU manufacturing. Distribution runs through hyperscaler-integrated hardware leasing with elastic burst provisions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU AI Act compliance costs inflate European procurement budgets while Indian and Brazilian mid-market buyers capture equivalent inference capabilities at usage-based discounts.
For Market Incumbents: Cement hybrid-cloud integration depth as the defensive moat against modular API-first specialists. Expand on-premise inference cluster certification pipelines for United States Department of Defense and German automotive manufacturers. Prioritize NIST AI Risk Management Framework alignment and auditable model lineage tooling as the compliance lever. Counter GPU hyperscaler concentration risk through multi-cloud training workload distribution. For New Entrants and Emerging Players: Begin with computer vision microservices for manufacturing quality control in Mexican and Vietnamese automotive assembly lines, the most penetrable white-space segment. Target sub-50 millisecond latency requirements with edge-optimized small language models as the technical wedge. Pursue channel partnerships with industrial automation distributors rather than direct enterprise sales to compress customer acquisition timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical-specific MLOps platforms with domain-tuned fine-tuning capabilities and proprietary data pipeline assets. Long-term viability across the analysis window favors vendors with hybrid-cloud deployment expertise and EU AI Act compliance tooling. Target acquisition archetype: computer vision specialists with manufacturing defect-detection IP and established Japanese or German automotive customer relationships. Monitor hyperscaler capex disclosures for GPU cluster expansion as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Unlocks premium pricing for healthcare and financial services deployments in France and Germany. |
| Hybrid Cloud Configuration Expansion | Captures margin pools from United States federal contractors requiring air-gapped data residency. |
| Edge-Optimized Model Compression | Enables sub-50 millisecond inference for Japanese automotive quality control workflows. |
| Multi-Cloud GPU Infrastructure Partnership | Mitigates single-source vulnerability from TSMC-NVIDIA supply concentration. |
| Manufacturing Quality Control API Launch | Penetrates underdeveloped Mexican and Vietnamese electronics assembly automation markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged CTOs at United States healthcare systems, platform engineers at Indian mid-market software vendors, IT procurement officers at German automotive manufacturers, and integration specialists at hyperscaler partner networks. Secondary validation drew from SEC 10-K hyperscaler capex disclosures, EU AI Act regulatory filings, NVIDIA and AMD supply chain disclosures, and healthcare procurement databases. Bottom-up deployment volume estimates triangulated against top-down cloud infrastructure spend analysis.
Segment-weighting across deployment architecture, solution offering, and end-user industry dimensions structured the analytical framework. Machine learning platforms, computer vision APIs, and natural language processing services each carried distinct growth coefficients based on GPU compute intensity and compliance documentation requirements. CAGRs derived from elastic demand modeling for inference token consumption and capital expenditure trajectory analysis for training cluster deployment. Industry-specific inputs included FDA guidance timelines for AI-enabled medical devices and METI industrial policy incentives for Japanese domestic AI infrastructure.
Several conditions sit outside the modeled scope, including sovereign AI mandates from regulators not yet published, foundation model commoditization velocity beyond current trajectories, and cross-border data localization enforcement intensity in China and Russia. Forecasts reflect documented assumptions about hyperscaler GPU supply expansion and EU AI Act implementation consistency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Semantic Web Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Stadium Market
Artificial Intelligence (AI)
Artificial Intelligence Platform Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
Global Cognitive Automation Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Security Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
AI Voice Cloning Market
Artificial Intelligence (AI)
Global Conversational Computing Platform Market
Artificial Intelligence (AI)
Global Cognitive Services Market
Artificial Intelligence (AI)
Global AI Training Dataset Market