
 Cloud Natural Language Processing (NLP) Market | 2026-2036
Cloud Natural Language Processing (NLP) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Natural Language Processing (NLP) Market Analysis
Hyperscaler data center buildouts in Northern Virginia are pivoting toward GPU-dense configurations optimized for large language model inference. Amazon Web Services leverages its custom Trainium and Inferentia silicon to reduce per-token inference costs for enterprise NLP workloads. Google Cloud Platform anchors its competitive position through deep integration between Vertex AI and its proprietary transformer architectures. Microsoft Azure dominates enterprise distribution channels by embedding NLP capabilities directly into Office 365 and Teams collaboration suites.
Cloud Natural Language Processing encompasses the delivery of computational linguistics capabilities—spanning tokenization, syntactic parsing, named entity recognition, and neural machine translation—as metered services over distributed cloud infrastructure, typically accessed via REST APIs or SDKs with latency targets under 200 milliseconds for real-time applications. The technology serves primarily to automate text-intensive business processes at scale without requiring clients to maintain specialized AI infrastructure or linguistic expertise. Public cloud deployment captures the dominant share of current revenue as organizations prioritize elastic scaling for unpredictable query volumes, though hybrid cloud configurations are gaining traction among financial services and healthcare entities constrained by data residency requirements. Speech recognition applications within the application segment are expanding fastest as voice interfaces penetrate customer service operations, while sentiment analysis remains the most mature use case with established pricing benchmarks and measurable ROI frameworks.
The EU AI Act and GDPR jointly shape product architecture decisions for any NLP service processing personal data or deploying high-risk automated systems in European jurisdictions, forcing providers to implement explainability layers and human oversight mechanisms. The US lacks comprehensive federal AI legislation, but sector-specific frameworks including HIPAA for healthcare data and SEC disclosure rules for algorithmic trading create compliance patchworks that vendors must navigate. Stakeholders should monitor emerging standardization efforts at ISO and IEC around AI risk management, as these will likely crystallize into procurement requirements before binding regulations take full effect.
Market Dynamics
GPU-dense hyperscaler data center configurations in Northern Virginia, Seattle, and San Francisco are compressing per-token inference costs and redistributing competitive advantage toward vertically integrated cloud providers with custom silicon programs.
Growth Catalysts
- EU AI Act transparency mandates:Healthcare providers across Germany and France are accelerating procurement of explainable clinical documentation tools to meet algorithmic accountability requirements for high-risk automated systems.
- Voice interface penetration:Customer service operations in US retail and financial services are replacing touch-tone IVR systems with real-time speech recognition APIs, driving query volume elasticity that favors cloud-native deployment.
- Seattle-San Francisco corridor R&D concentration:Enterprise AI research investment clusters around these metro areas, creating talent density and infrastructure spillovers that reduce time-to-market for new NLP capabilities.
Market Restraints
- GDPR-EU AI Act compliance stacking:Dual regulatory frameworks force providers to maintain parallel engineering tracks for explainability layers and human oversight mechanisms, inflating fixed development costs.
- GPU supply concentration:Advanced accelerator procurement depends on Taiwan Semiconductor Manufacturing capacity allocation, exposing inference cost structures to geopolitical supply disruptions.
- On-premise legacy substitution:Financial services institutions with existing on-site NLP deployments face switching costs from data gravity and internal model training investments.
Strategic Opportunities
- Hybrid cloud healthcare expansion:German and Dutch hospital networks constrained by patient data residency requirements represent underpenetrated demand for sovereign cloud NLP configurations.
- Real-time translation convergence:Neural machine translation paired with edge speech recognition is opening defense and diplomatic procurement channels previously served by specialized hardware vendors.
- India PLI scheme localization:Production-linked incentives for AI hardware assembly are attracting cloud providers to establish Mumbai and Bengaluru inference nodes for South Asian language coverage.
Industry Challenges
- Transformer architecture talent scarcity:Deep expertise in attention mechanism optimization and distributed training orchestration commands premium compensation, constraining mid-tier provider engineering velocity.
- ISO/IEC 42001 certification timelines:AI management system audits require 12-18 month implementation cycles, delaying enterprise procurement approvals for uncertified vendors.
- Legacy EHR integration friction:Healthcare NLP deployments face HL7 FHIR mapping complexity and proprietary data format translation costs that erode implementation margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Natural Language Processing (NLP) Market |
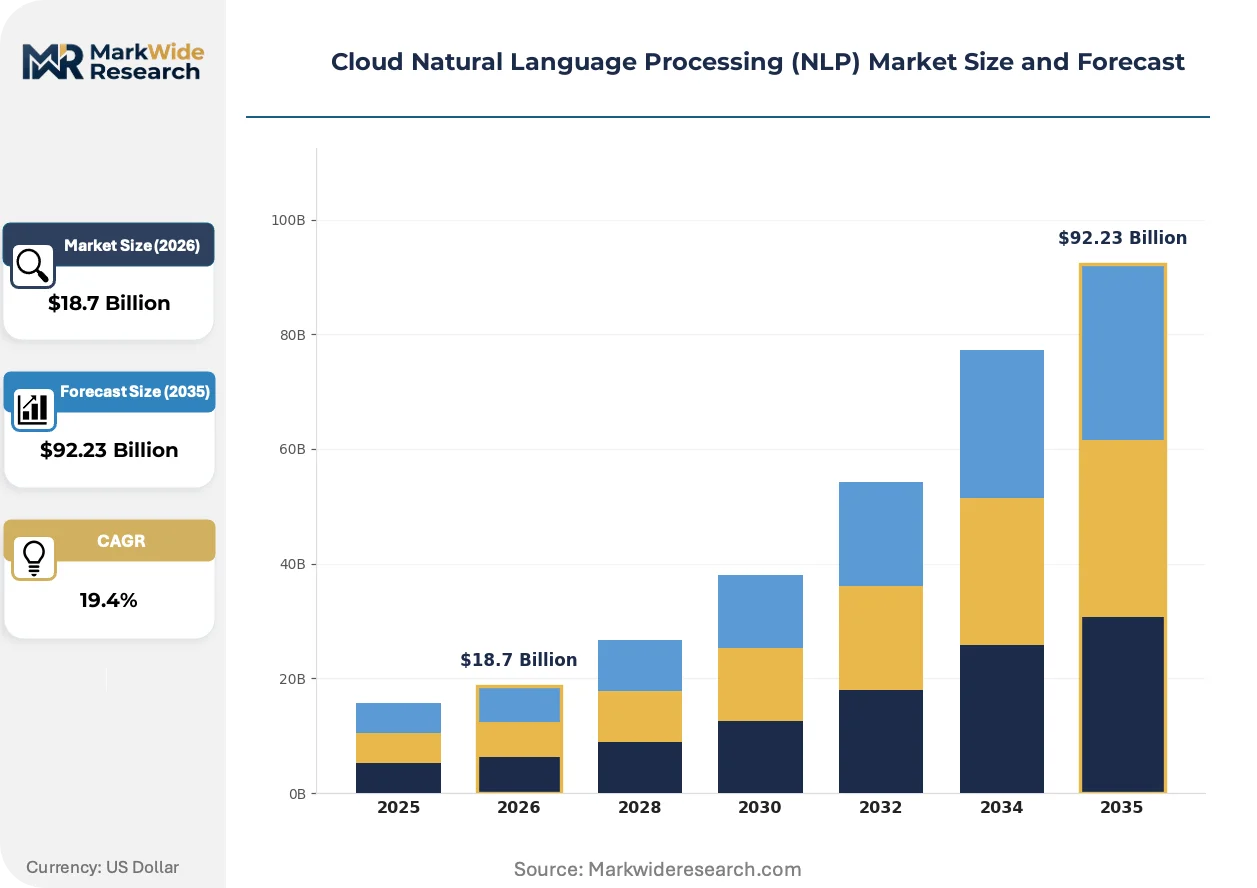
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Enterprises, Startups, Academic Institutions, Government Agencies Application: Sentiment Analysis, Text Classification, Chatbots, Speech Recognition Functionality: Content Moderation, Entity Recognition, Language Translation, Grammar Checking |
| Companies Covered | Amazon Web Services, Google Cloud Platform, Microsoft Azure, IBM Watson, Intel Corporation, Baidu, Salesforce, SAP SE, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Natural Language Processing (NLP) Market Emerging Trajectories
Foundation model inference optimization is compressing latency thresholds and enabling real-time applications previously reserved for rule-based systems, while regulatory pressure is forcing architectural investments in explainability.
Retrieval-augmented generation architectures are electrifying enterprise knowledge management by grounding large language model outputs in proprietary document corpora. Legal services and pharmaceutical regulatory affairs teams are adopting these systems to reduce hallucination rates in contract analysis and submission drafting. The technology is electrifying competitive positioning for providers offering hybrid search-generation pipelines with sub-second citation verification.
The EU AI Act's risk-based classification system is mandating conformity assessments for high-risk NLP applications including credit scoring and recruitment automation. Providers must now maintain technical documentation, human oversight protocols, and post-market monitoring systems that mirror medical device quality management requirements. Financial services institutions in France and Germany are prioritizing vendors with notified body pre-certification to de-risk procurement timelines.
Consumption-based API pricing with tiered rate limiting is displacing traditional enterprise software licensing in mid-market customer service deployments. Buyer finance teams prefer operational expenditure alignment with query volume rather than fixed annual commitments. This pattern is most visible among US-based SaaS companies with seasonal support ticket volatility, who are negotiating burst capacity clauses directly with hyperscaler marketplaces rather than through systems integrators.
Cloud Natural Language Processing (NLP) Market Segmentation
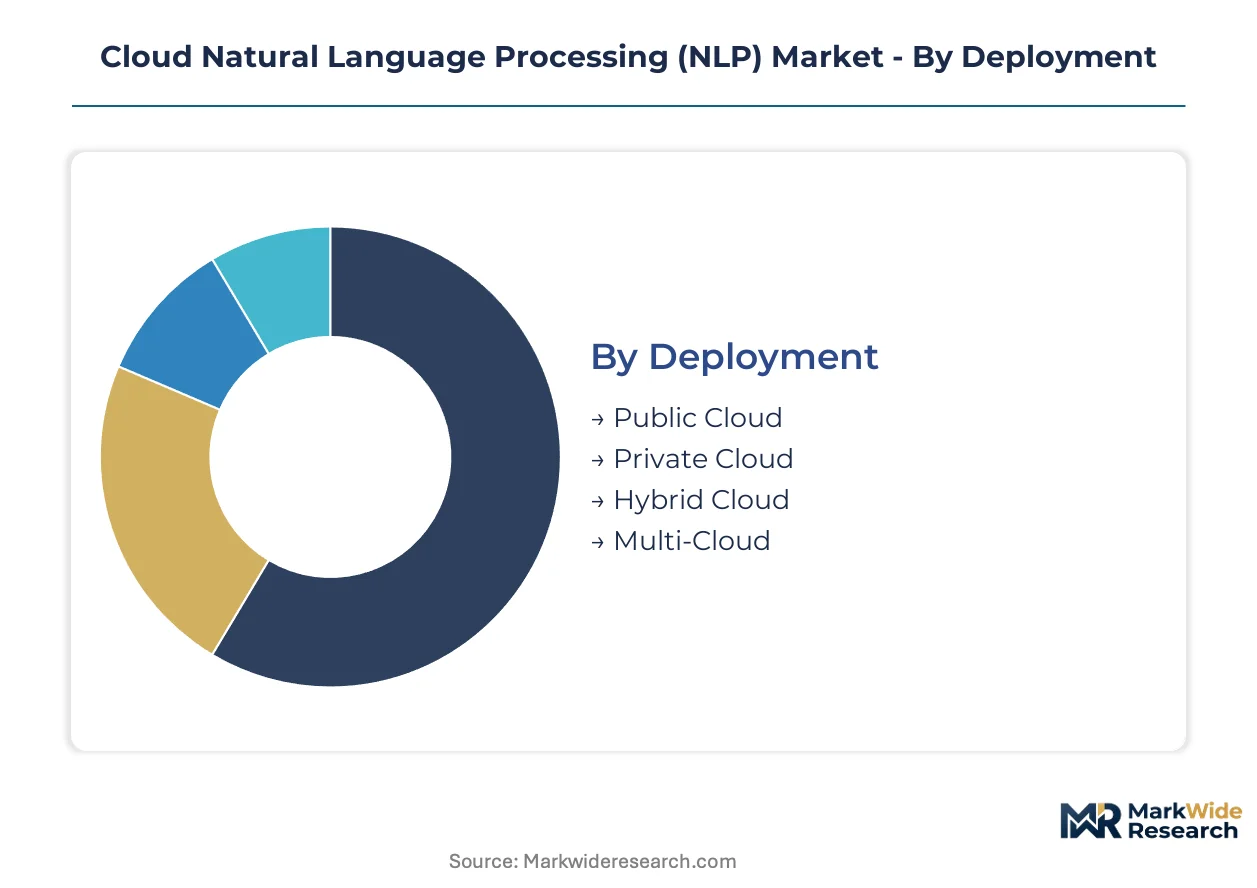
Cloud NLP segmentation reflects divergent buyer priorities across data sovereignty requirements, computational latency constraints, and regulatory exposure levels. Procurement patterns cluster around deployment architecture decisions that determine compliance posture and cost elasticity.
Deployment:
Elastic scaling requirements and data residency mandates drive architecture selection more than raw per-token pricing.
- Public Cloud:Metered API access over shared infrastructure delivers sub-200ms latency for real-time applications. US retail and financial services customer service operations prioritize burst capacity for seasonal query volatility.
- Hybrid Cloud:Split processing between on-premise sensitive data and cloud inference for non-regulated workloads. German and Dutch hospital networks constrained by patient data residency requirements represent concentrated demand for sovereign configurations.
- Private Cloud:Dedicated tenant environments serving defense and diplomatic procurement channels with air-gapped security requirements.
- Multi-Cloud:Redundancy architectures mitigating vendor lock-in for enterprise SaaS companies with 99.99% SLA obligations.
Public Cloud leads on scale; Hybrid Cloud leads on momentum.
End User:
Budget predictability and internal AI expertise availability separate procurement patterns across buyer types.
- Enterprises:Volume-committed contracts with negotiated rate limiting and custom model fine-tuning provisions. Fortune 500 legal and pharmaceutical regulatory affairs teams drive retrieval-augmented generation adoption for contract analysis.
- Government Agencies:FedRAMP and IL5 compliance requirements with mandatory human oversight protocols for high-risk automated systems.
- Startups:Consumption-based API pricing with tiered rate limiting preferred over fixed annual commitments.
- Academic Institutions:Research licensing with discounted inference quotas for non-commercial transformer architecture experimentation.
Enterprises dominate current revenue contribution; Government Agencies show steepest expansion trajectory as defense and diplomatic channels open.
Application:
Use case maturity determines pricing benchmark availability and measurable ROI framework establishment.
- Sentiment Analysis:Established pricing benchmarks with quantifiable customer experience metrics. Maturest use case with proven enterprise adoption curves.
- Speech Recognition:Real-time voice interfaces replacing touch-tone IVR systems in US retail and financial services contact centers. Expanding most quickly as edge deployment reduces latency.
- Chatbots:Conversational automation for tier-1 support deflection with escalating escalation protocols.
- Text Classification:Document routing and compliance screening with explainability layer requirements under EU AI Act.
Sentiment Analysis leads on scale; Speech Recognition leads on momentum.
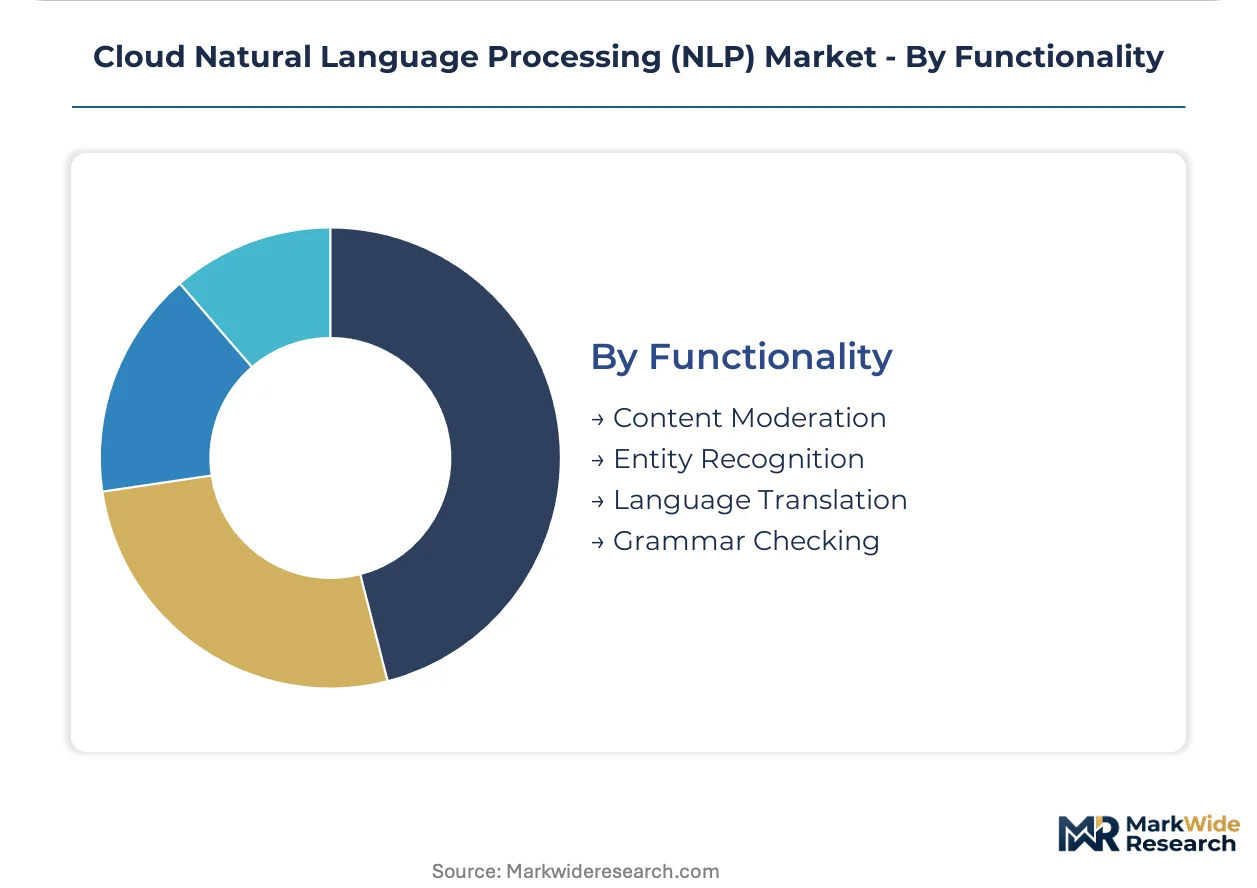
Functionality:
Regulatory risk classification under EU AI Act determines mandatory conformity assessment scope and human oversight investment.
- Content Moderation:Automated platform governance with transparency reporting obligations under Digital Services Act.
- Entity Recognition:Structured data extraction from unstructured clinical and financial documents with HL7 FHIR mapping complexity.
- Language Translation:Neural machine translation paired with edge speech recognition opening defense procurement channels previously served by specialized hardware vendors.
- Grammar Checking:Productivity augmentation embedded in collaboration suites with lowest regulatory exposure classification.
Entity Recognition leads on scale; Language Translation leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise infrastructure spending dwarfs German clinical AI procurement volumes, yet EU regulatory pressure is compressing deployment timelines in European healthcare systems.
United States
Enterprise cloud infrastructure spending clusters around Seattle, San Francisco, and Northern Virginia data center corridors. HIPAA compliance requirements shape healthcare NLP procurement specifications. Seattle-based hyperscalers leverage custom silicon programs to reduce per-token inference costs for customer service operations.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are accelerating explainable clinical documentation procurement. The EU AI Act mandates algorithmic transparency for high-risk automated systems. Munich-based medical AI vendors are integrating human oversight protocols into diagnostic NLP workflows.
France
Financial services institutions in Paris prioritize vendors with notified body pre-certification for credit scoring applications. GDPR and EU AI Act jointly force explainability layer investments. Île-de-France hosts concentrated demand for recruitment automation compliance tooling.
India
Production-linked incentives for AI hardware assembly are attracting inference node establishment in Mumbai and Bengaluru. The national AI strategy prioritizes South Asian language model development. Telangana and Karnataka state governments are negotiating sovereign cloud configurations with hyperscalers.
United Kingdom
London-based legal services firms drive retrieval-augmented generation adoption for contract analysis. The UK lacks comprehensive AI legislation but maintains sector-specific financial conduct authority guidance. Cambridge AI research clusters are spawning specialized NLP tooling vendors.
Cloud Natural Language Processing (NLP) Market Vendor Landscape
United States hyperscalers anchor the infrastructure tier; European enterprise software specialists hold workflow integration positions. Market structure concentrates around vertically integrated cloud providers with custom silicon programs and independent platform vendors with deep vertical expertise. Three archetypes dominate: hyperscaler infrastructure operators, enterprise application embedders, and vertical-specific AI platforms. Competitive intensity manifests through custom accelerator deployment and API marketplace expansion.
Among US-based hyperscalers, Amazon Web Services, Google Cloud Platform, and Microsoft Azure exemplify the infrastructure-integrated archetype. These entities occupy positions defined by data center density in Northern Virginia and Seattle corridors, custom Trainium, Inferentia, and proprietary silicon development, and direct embedding into Office 365 and Teams collaboration suites. Their competitive posture represents the convergence of elastic compute provisioning with downstream application distribution channels.
| Leading Market Players |
|---|
| Amazon Web Services |
| Google Cloud Platform |
| Microsoft Azure |
| IBM Watson |
| Intel Corporation |
| Baidu |
| Salesforce |
| SAP SE |
| Hewlett Packard Enterprise |
| Others |
Supply Flow & Price Mechanics
Hyperscaler balance-sheet capacity anchors supply discipline across cloud NLP infrastructure, with AWS, Google Cloud, and Microsoft Azure deploying sovereign wealth-backed capital to underwrite GPU-dense data center buildouts while metering API access through consumption-based pricing tiers that compress margin elasticity for mid-tier platform vendors.
Pricing Analysis
Capacity additions in Northern Virginia and Seattle are reshaping price floors for inference workloads as hyperscalers leverage custom Trainium and Inferentia silicon to undercut general-purpose GPU rental rates. Metered API pricing with tiered rate limiting dominates mid-market procurement, separating enterprise volume commitments from startup burst capacity. Pricing pressure stems from Taiwan Semiconductor Manufacturing capacity allocation constraints that inflate accelerator procurement costs. Financial services institutions exhibit lowest price sensitivity due to compliance-driven vendor stickiness, while SaaS startups with seasonal ticket volatility drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through AWS Marketplace, Azure Marketplace, and Google Cloud Partner Advantage, bypassing traditional systems integrators for API distribution. Supply concentrates in Taiwan for advanced GPU fabrication, the United States for hyperscaler data center operations, and India for production-linked incentive assembly of inference hardware. Raw material dependencies span high-bandwidth memory from South Korea, advanced packaging substrates from Japan, and rare earth elements for magnet assemblies. Single-source vulnerability around Taiwan Semiconductor Manufacturing exposes inference cost structures to geopolitical disruption. Distribution runs through cloud marketplace ecosystems with embedded billing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud NLP procurement arbitrage opportunities concentrate between German hospital networks facing EU AI Act compliance deadlines and US retail contact centers optimizing seasonal elasticity, with regulatory cost differentials exceeding infrastructure efficiency gaps across Atlantic deployment corridors.
For Market Incumbents: Lock in German and French healthcare procurement cycles ahead of EU AI Act conformity assessment deadlines by pre-certifying explainability layers with notified bodies. Defend margin position through backward integration into custom silicon programs that reduce per-token inference costs below general-purpose GPU rental benchmarks. Channel control via embedded Office 365 and Teams distribution insulates Microsoft Azure from standalone API vendor displacement. For New Entrants and Emerging Players: The premium-to-economy pricing gap in sovereign cloud configurations offers entry traction for mid-tier platform vendors with hybrid deployment expertise. Target German and Dutch hospital networks constrained by patient data residency requirements with air-gapped inference nodes and HL7 FHIR-native integration. Go-to-market leverage rests on ISO/IEC 42001 certification acceleration to compress enterprise procurement approval timelines. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical-specific AI platforms with deep healthcare or legal workflow integration rather than undifferentiated API infrastructure. Long-term viability across the analysis window favors acquisition targets with proprietary retrieval-augmented generation pipelines and established human-in-the-loop protocols for high-risk automated systems. Monitor EU AI Act notified body pre-certification velocity as inflection indicator for European healthcare procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Custom Silicon Program Expansion | AWS Trainium deployment reduces per-token costs below NVIDIA GPU rental benchmarks. |
| Retrieval-Augmented Generation Platform Launch | Vertex AI grounding services compress hallucination rates for legal contract analysis. |
| Notified Body Pre-Certification Partnership | TÜV SÜD conformity assessments accelerate German hospital procurement timelines. |
| Hybrid Cloud Sovereign Configuration | Munich data center nodes satisfy Bavarian patient data residency mandates. |
| ISO/IEC 42001 Certification Acceleration | Twelve-month audit compression enables mid-market enterprise sales velocity. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with CTOs at Fortune 500 enterprises, IT procurement officers at German hospital networks, platform engineers at hyperscaler marketplaces, and integration specialists at systems integrators with secondary validation against SEC hyperscaler capex disclosures, EU AI Act implementation guidance, and ISO/IEC 42001 certification timelines. Bottom-up deployment architecture modeling triangulated against top-down infrastructure spending estimates.
Segment-weighting approaches distributed value across deployment models, organization size tiers, vertical applications, and regional regulatory clusters throughout the projection horizon. Analytical frameworks modeled elastic scaling patterns, data residency constraint penetration, and voice interface adoption curves. CAGRs derived from inference query volume elasticity, per-token cost compression trajectories, and compliance-driven procurement acceleration in European healthcare systems.
The model assumes a particular technology adoption path; alternative pathways for edge speech recognition convergence would alter the outlook. Forecasts reflect assumptions around Taiwan Semiconductor Manufacturing capacity allocation, EU AI Act enforcement consistency, and hyperscaler custom silicon program execution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Task Manager App Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
Embedded Intelligence Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Global AI in Telecommunication Market
Artificial Intelligence (AI)
Global Mobile Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Governance Market
Artificial Intelligence (AI)
AI in Fashion Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Artificial Intelligence Oven Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market