
 AI in Construction Market | 2026-2036
AI in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Construction Market Analysis
The EU Green Deal is expanding compliance obligations for embodied carbon tracking across construction value chains, forcing contractors to adopt AI-powered design and procurement tools. Autodesk leverages generative design algorithms to optimize material selection against regulatory thresholds. Trimble Inc. anchors its position through integrated hardware-software platforms that connect field sensors to cloud-based analytics. Dassault Systèmes differentiates via digital twin capabilities that simulate building performance across full lifecycle emissions.
AI in construction encompasses machine learning algorithms, computer vision systems, and natural language processing tools deployed to automate design optimization, safety monitoring, and project scheduling across building and infrastructure workflows. These technologies process sensor data, aerial imagery, and historical project records to generate predictive insights that reduce cost overruns and site incidents. Machine Learning currently leads technology adoption by revenue, while Computer Vision is expanding fastest through drone-based site monitoring and autonomous equipment guidance. Building Information Modeling dominates product type revenue as the foundational data layer, though Safety Monitoring Systems are gaining share as insurers mandate real-time hazard detection.
The EU Green Deal, EPA construction emission guidelines, and OSHA workplace safety standards collectively shape product requirements and procurement criteria across major construction markets. Compliance with these frameworks determines platform eligibility for public infrastructure contracts and influences insurance underwriting terms. Stakeholders must evaluate which regulatory jurisdictions will tighten disclosure requirements first, as this sequence will dictate geographic rollout priorities for AI solution providers.
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are forcing contractors to reconfigure procurement systems around AI-powered material tracking and lifecycle analytics.
Growth Catalysts
- EU Green Deal compliance mandates:Embodied carbon disclosure rules now require builders to document emissions across supply chains, creating immediate demand for automated tracking platforms.
- Federal infrastructure spending in the United States:Public works allocations prioritize digitized project delivery, accelerating procurement of predictive scheduling and risk assessment systems.
- Computer vision for site safety:Drone-based hazard detection and autonomous equipment guidance reduce incident rates while satisfying insurer requirements for real-time monitoring.
Market Restraints
- Specialized talent scarcity:Shortage of engineers capable of integrating machine learning models with legacy Building Information Modeling workflows limits deployment velocity.
- Data interoperability gaps:Proprietary file formats across design, procurement, and field management platforms fragment analytics pipelines and inflate integration costs.
- High upfront platform costs:Cloud infrastructure, sensor hardware, and retraining expenses concentrate adoption among large commercial contractors with balance sheet capacity.
Strategic Opportunities
- Mid-tier contractor penetration in Germany:Mittelstand builders remain underserved by current AI scheduling tools, presenting white space for localized, lower-cost platforms.
- Digital twin convergence with generative design:Combined simulation and automated optimization capabilities enable real-time carbon threshold compliance during schematic phases.
- OSHA safety standard tightening:Anticipated expansion of real-time hazard detection mandates creates procurement pull for computer vision systems across US federal contracts.
Industry Challenges
- Legacy system integration complexity:ERP and project management platforms deployed over decades resist API connectivity, forcing costly middleware development.
- Model training data quality:Inconsistent historical project documentation and proprietary data silos degrade predictive accuracy for cost and schedule algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Construction Market |
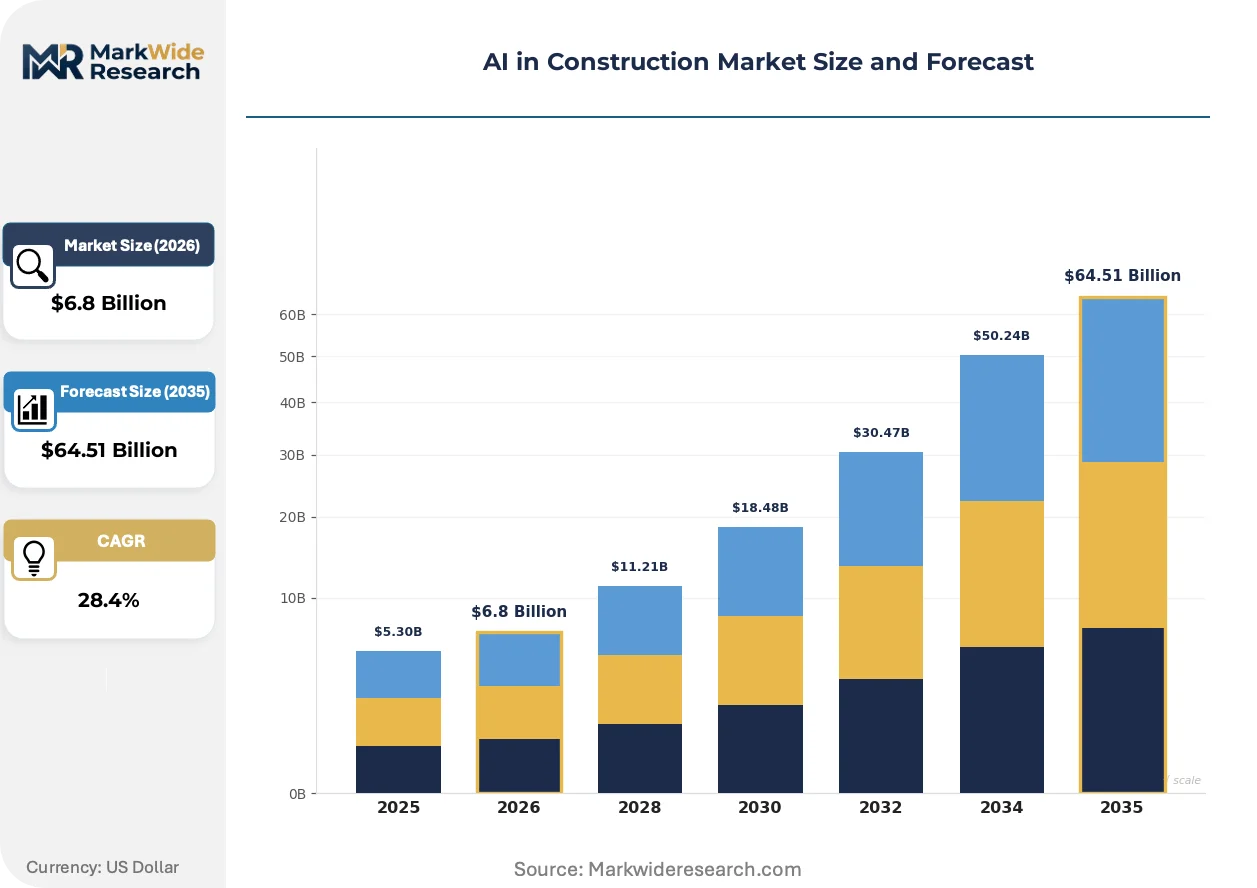
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Design Software, Project Management Tools, Safety Monitoring Systems, Building Information Modeling End User: Contractors, Architects, Engineers, Developers Technology: Machine Learning, Computer Vision, Natural Language Processing, Robotics Application: Site Analysis, Risk Assessment, Project Scheduling, Cost Estimation |
| Companies Covered | Autodesk, SAP SE, Bentley Systems, Trimble Inc., Oracle Corporation, ALICE Technologies Inc., Microsoft, International Business Machines Corporation, Dassault Systèmes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Construction Market Emerging Trajectories
Generative design algorithms, regulatory disclosure automation, and predictive safety analytics are compressing decision cycles across construction planning and delivery workflows.
Building Information Modeling is converging with generative design algorithms to automate material selection against carbon thresholds. Large commercial contractors in Germany and France are deploying these integrated platforms during schematic design phases. The convergence is compressing procurement timelines while ensuring EU Green Deal compliance before construction mobilization.
The EU Green Deal's embodied carbon disclosure framework now mandates granular emissions documentation across construction value chains. Builders must track material origins, transportation modes, and manufacturing processes through digital platforms. Heavy civil infrastructure projects in the Netherlands and Denmark face the steepest compliance curves, driving fastest adoption of automated supply chain analytics.
Buyer concentration among large commercial contractors is reshaping vendor go-to-market strategies. Tier-one builders now demand integrated hardware-software platforms rather than point solutions, consolidating procurement around full-stack providers. This pattern is most visible in the United States, where federal infrastructure contractors bundle sensor hardware, cloud analytics, and field applications into single-vendor agreements.
AI in Construction Market Segmentation
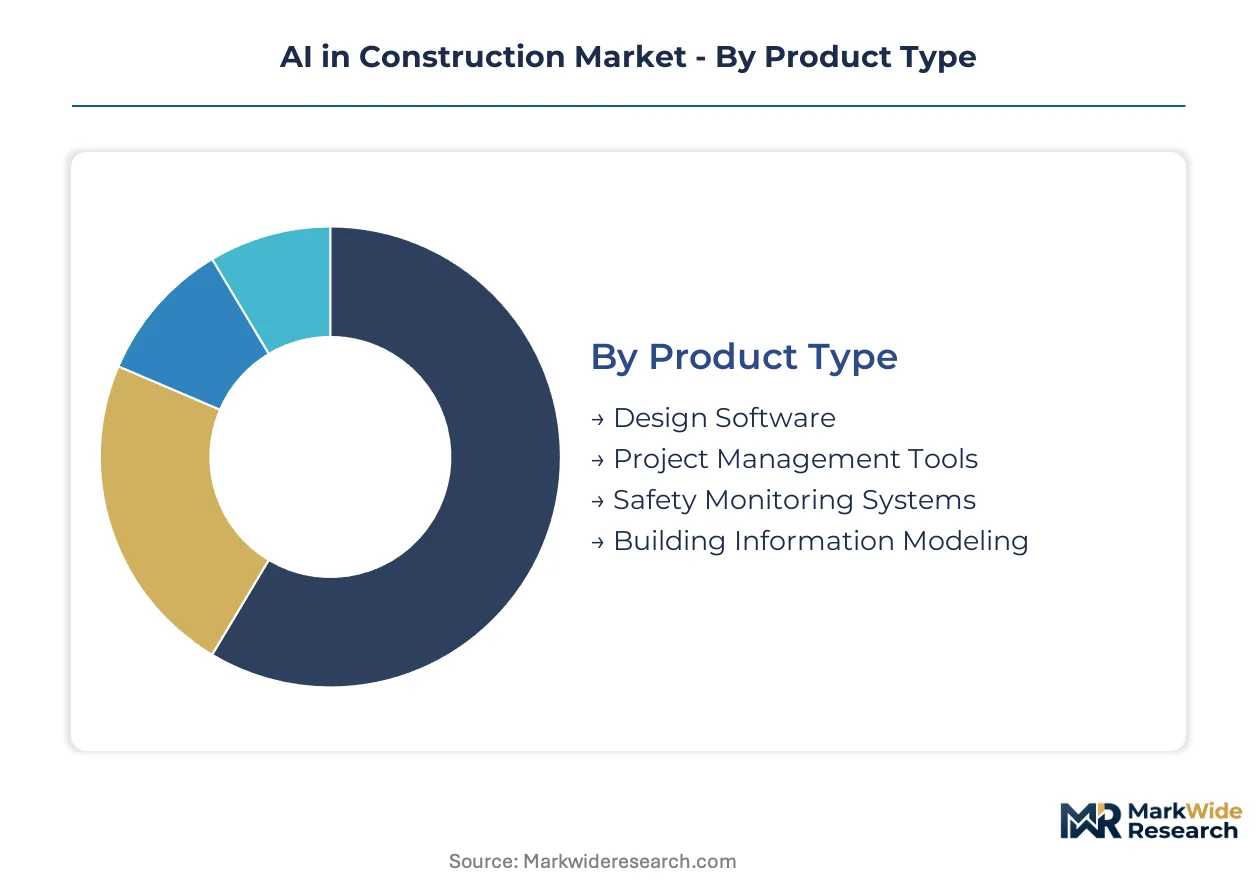
Segmentation in AI construction platforms reveals how procurement decisions cluster around technical capabilities, regulatory compliance requirements, and project scale. Buyers prioritize integrated toolchains over point solutions, reshaping vendor positioning across every category axis.
Technology:
Algorithms and sensing modalities differentiate platform architectures and determine integration complexity with legacy field systems.
- Machine Learning:Predictive models trained on historical project data forecast cost overruns and schedule slippage. Demand concentrates among large commercial contractors in the United States seeking to satisfy federal infrastructure contract requirements for digitized risk assessment.
- Computer Vision:Image recognition systems process drone footage and fixed-site cameras for hazard detection and progress monitoring. Heavy civil infrastructure projects in the Netherlands deploy these systems to meet insurer mandates for real-time safety documentation.
- Natural Language Processing:Document parsing tools extract specifications from RFPs and contract amendments. Mid-tier contractors in Germany adopt NLP modules to accelerate bid preparation without expanding technical staff.
- Robotics:Autonomous equipment guidance systems translate digital models into machine instructions. Japanese construction firms deploy robotics for precision earthmoving and rebar placement in seismic-sensitive structures.
Machine Learning leads on scale; Computer Vision leads on momentum.
Product Type:
Software categories map to distinct workflow phases, with buyers favoring platforms that span multiple phases through unified data layers.
- Building Information Modeling:Centralized digital repositories integrate geometric, temporal, and cost data across project lifecycles. BIM platforms anchor procurement in France where EU Green Deal disclosure rules require granular material tracking from schematic design through handover.
- Safety Monitoring Systems:Real-time hazard detection platforms combine sensor networks with alerting protocols. US federal contractors install these systems to satisfy OSHA documentation requirements and secure insurance premium reductions.
- Design Software:Generative algorithms automate schematic optimization against carbon thresholds. Architects in Denmark leverage these tools to preempt regulatory rejection during municipal permitting.
- Project Management Tools:Scheduling and resource allocation platforms synchronize subcontractor workflows. Developers in the United Arab Emirates deploy these systems to coordinate international labor pools across mega-project sites.
Building Information Modeling dominates current procurement volumes; Safety Monitoring Systems are climbing the fastest as liability frameworks tighten.
Application:
Use-case specialization determines whether platforms serve planning-phase decisions or field-execution control.
- Risk Assessment:Monte Carlo simulations and sensitivity analyses quantify contingency requirements. Contractors in Germany apply these tools to satisfy Mittelstand lender demands for documented downside protection.
- Project Scheduling:Critical path optimization algorithms compress delivery timelines. Infrastructure agencies in the United States mandate these capabilities for federal grant eligibility.
- Site Analysis:Topographic and subsurface data processing informs foundation design. Dutch engineering firms combine LiDAR with soil sensors to model flood resilience for delta-region developments.
- Cost Estimation:Parametric pricing models benchmark material and labor inputs against historical databases. Quantity surveyors in the United Kingdom deploy these systems to align tender submissions with post-Brexit supply chain volatility.
Project Scheduling captures the largest deployment base; Risk Assessment is gaining share fastest as bond insurers tighten underwriting standards.
End User:
Professional role determines interface complexity requirements and data ownership structures within project consortia.
- Contractors:Field-focused platforms prioritize mobile accessibility and offline functionality. Large commercial contractors in the United States drive category revenue through bundled hardware-software procurement.
- Architects:Design-phase tools emphasize generative capabilities and visualization fidelity. French practices adopt these platforms to automate EU Green Deal compliance documentation.
- Engineers:Structural and MEP specialists require simulation integration with calculation engines. German engineering consultancies demand API connectivity to proprietary analysis software.
- Developers:Investment-focused dashboards consolidate progress tracking against pro forma projections. UAE sovereign wealth fund projects mandate real-time reporting portals for stakeholder transparency.
Contractors represent the deepest installed base; Architects are expanding procurement most rapidly as regulatory design obligations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
AI engineering talent clusters in the United States, Germany, and China anchor regional platform development. Federal procurement mandates and EU Green Deal compliance obligations concentrate deployment in North America and Western Europe. Emerging demand in the UAE and Japan reflects infrastructure digitization programs and seismic safety imperatives.
United States
Large commercial contractors drive procurement of predictive scheduling and risk assessment platforms. Federal infrastructure spending through the Infrastructure Investment and Jobs Act mandates digitized project delivery for grant eligibility. Dallas-Fort Worth and Atlanta metro areas concentrate deployment of computer vision systems for federal highway contractors.
Germany
Mittelstand engineering consultancies adopt NLP-powered document parsing to accelerate bid preparation without expanding technical staff. The EU Green Deal's embodied carbon disclosure rules force builders to reconfigure procurement systems around automated material tracking. Munich and Stuttgart industrial clusters lead adoption of digital twin platforms for automotive factory construction.
France
Architectural practices deploy generative design algorithms to automate EU Green Deal compliance documentation during municipal permitting. The country's national building regulator enforces granular material origin tracking for public infrastructure contracts. Paris and Lyon metro areas concentrate BIM-integrated procurement for commercial high-rise developments.
Netherlands
Heavy civil infrastructure projects face steep compliance curves under EU Green Deal delta-region flood resilience standards. The country's national environmental agency mandates real-time carbon accounting across transportation and manufacturing supply chains. Rotterdam port-adjacent developments anchor fastest adoption of automated supply chain analytics platforms.
United Arab Emirates
Sovereign wealth fund mega-projects mandate real-time reporting portals for stakeholder transparency across international labor pools. The country's national construction regulator requires digitized progress tracking for contracts above specified value thresholds. Dubai and Abu Dhabi development corridors concentrate procurement of integrated project management tools.
AI in Construction Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the AI construction platform landscape. The market exhibits tiered consolidation, with full-stack providers capturing federal and mega-project contracts while point-solution vendors serve mid-tier builders. Two strategic archetypes dominate: integrated hardware-software platform builders and cloud-native algorithm specialists. Competitive dynamics center on strategic partnerships with sensor manufacturers and portfolio diversification into adjacent compliance automation modules.
Within the integrated platform tier, Autodesk and Trimble Inc. exemplify full-stack positioning through bundled hardware-software procurement models. SAP SE occupies a position bridging enterprise resource planning workflows with construction-specific analytics. Dassault Systèmes represents the digital twin specialization vector, anchoring lifecycle simulation capabilities for carbon threshold compliance. ALICE Technologies Inc. and Bentley Systems sit within the algorithm-native tier, offering predictive optimization without captive hardware ecosystems.
| Leading Market Players |
|---|
| Autodesk |
| SAP SE |
| Bentley Systems |
| Trimble Inc. |
| Oracle Corporation |
| ALICE Technologies Inc. |
| Microsoft |
| International Business Machines Corporation |
| Dassault Systèmes |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up construction software specialists anchor supply behavior through bundled platform procurement, while their balance sheet discipline enforces tiered SaaS pricing that concentrates margin capture among large commercial contractors with multi-year deployment horizons.
Pricing Analysis
Bundled hardware-software procurement commands premium positioning against unbundled point solutions. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, with premium tiers including dedicated implementation support and API connectivity. Cost compression in mid-market SaaS tiers is intensifying because cloud infrastructure providers are commoditizing compute resources. Small-to-mid-tier contractors exhibit highest price sensitivity, while federal infrastructure contractors prioritize compliance certification over cost.
Supply Chain Analysis
Dual-sourcing requirements from US federal contractors and EU Green Deal-mandated platform vendors force qualification of multiple sensor hardware and cloud infrastructure providers. Supply concentrates in the United States, Germany, and China for AI chipsets, LiDAR sensors, and edge computing modules. Platform providers draw from NVIDIA GPUs, Intel edge processors, and Sony image sensors as critical inputs. Single-source vulnerability in specialized AI accelerators creates procurement risk. Distribution runs through direct enterprise sales teams and systems integrators serving heavy civil infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with regulatory compliance mandates across the EU Green Deal and US federal infrastructure spending creating durable, non-discretionary demand for digitized project delivery platforms.
For Market Incumbents: Hedge against algorithm-native disruptors by deepening captive sensor hardware ecosystems and securing exclusive data partnerships with Tier 1 contractors. Acquire mid-tier European BIM specialists before EU Green Deal enforcement tightens. Vertical integration into LiDAR manufacturing reduces exposure to semiconductor allocation volatility.
For New Entrants and Emerging Players: Capture white space in Germany's Mittelstand contractor segment through localized, lower-cost NLP-powered document parsing tools. Target French architectural practices with generative design modules that automate municipal permitting workflows. Pursue channel partnerships with national construction associations rather than direct field sales.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier computer vision specialists with proven drone-based site monitoring deployments but limited platform breadth. Long-term viability hinges on regulatory compliance automation rather than pure operational efficiency. Monitor OSHA rulemaking dockets for real-time hazard detection mandate timing as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies BIM, generative design, and field sensors to satisfy EU Green Deal disclosure requirements. |
| Strategic Partnership | Aligns with federal infrastructure contractors to secure multi-year bundled procurement agreements. |
| Acquisition of Specialist Firm | Absorbs mid-tier NLP or computer vision teams to fill capability gaps in compliance automation. |
| Geographic Expansion | Establishes localized presence in Germany's Mittelstand belt for underserved contractor segments. |
| Product Launch | Introduces carbon threshold compliance modules timed to EU Green Deal enforcement deadlines. |
Methodological Framework
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined through structured interviews and secondary validation. Primary fieldwork engaged construction technology procurement officers, federal contract compliance managers, architectural practice principals, and heavy civil project directors. Secondary sources included EPA construction emission guidelines, EU Green Deal regulatory filings, OSHA safety standard databases, and federal infrastructure spending disclosures. Bottom-up project deployment tracking and top-down platform revenue analysis were triangulated against contractor survey responses.
Granularity-level modeling segmented by technology type, product category, application use case, and end-user professional role across national regulatory clusters. Deployment velocity, compliance mandate timing, and contractor digitization maturity informed CAGR derivation across the analysis window. Machine learning adoption curves and computer vision hardware shipment data served as industry-specific forecast anchors.
Regulatory enforcement delays, sensor component supply disruptions, and contractor balance sheet stress are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about mandate implementation schedules and technology integration timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence SAAS Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
AI Demand Forecasting Software Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Japan Edge AI Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Drug Discovery Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
Global Augmented Intelligence Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Voice Assistance Application Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Explainable AI Market
Artificial Intelligence (AI)
Voice Recognition Market