
 Artificial Intelligence in Logistics Market | 2026-2036
Artificial Intelligence in Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Logistics Market Insights
Enterprise-grade predictive accuracy is collapsing the gap between legacy supply chain software and autonomous logistics platforms. Amazon.com Inc. leverages its proprietary fulfillment algorithms to sustain same-day delivery density across North American metro corridors. Microsoft Corporation anchors enterprise adoption through Azure-based supply chain copilots integrated with SAP and Oracle ERP stacks. NVIDIA Corporation dominates AI training infrastructure for logistics, controlling the GPU supply that powers computer vision models in automated sortation facilities.
Artificial intelligence in logistics encompasses machine learning algorithms, predictive analytics engines, computer vision systems, and natural language processing tools that optimize freight routing, warehouse robotics, and demand forecasting across multimodal supply chains. These technologies process real-time telemetry from IoT sensors, GPS trackers, and ERP databases to reduce transit variance and inventory carrying costs. Machine learning and computer vision currently lead technology deployment, with the former powering demand forecasting engines and the latter enabling autonomous pallet recognition and damage detection. Route planning and warehouse automation represent the fastest-growing application areas, as labor scarcity and fuel volatility push carriers toward algorithmic dispatch and robotic put-away systems.
The EU AI Act, FDA guidelines for pharmaceutical cold-chain traceability, and China's MIIT algorithmic recommendation provisions collectively shape compliance costs and data governance requirements for cross-border logistics AI. The EU AI Act specifically imposes risk-classification obligations on automated warehouse systems that make safety-critical decisions without human intervention. Stakeholders must monitor how divergent regulatory timelines between Brussels, Beijing, and Washington affect the portability of trained models across jurisdictions.
Market Dynamics
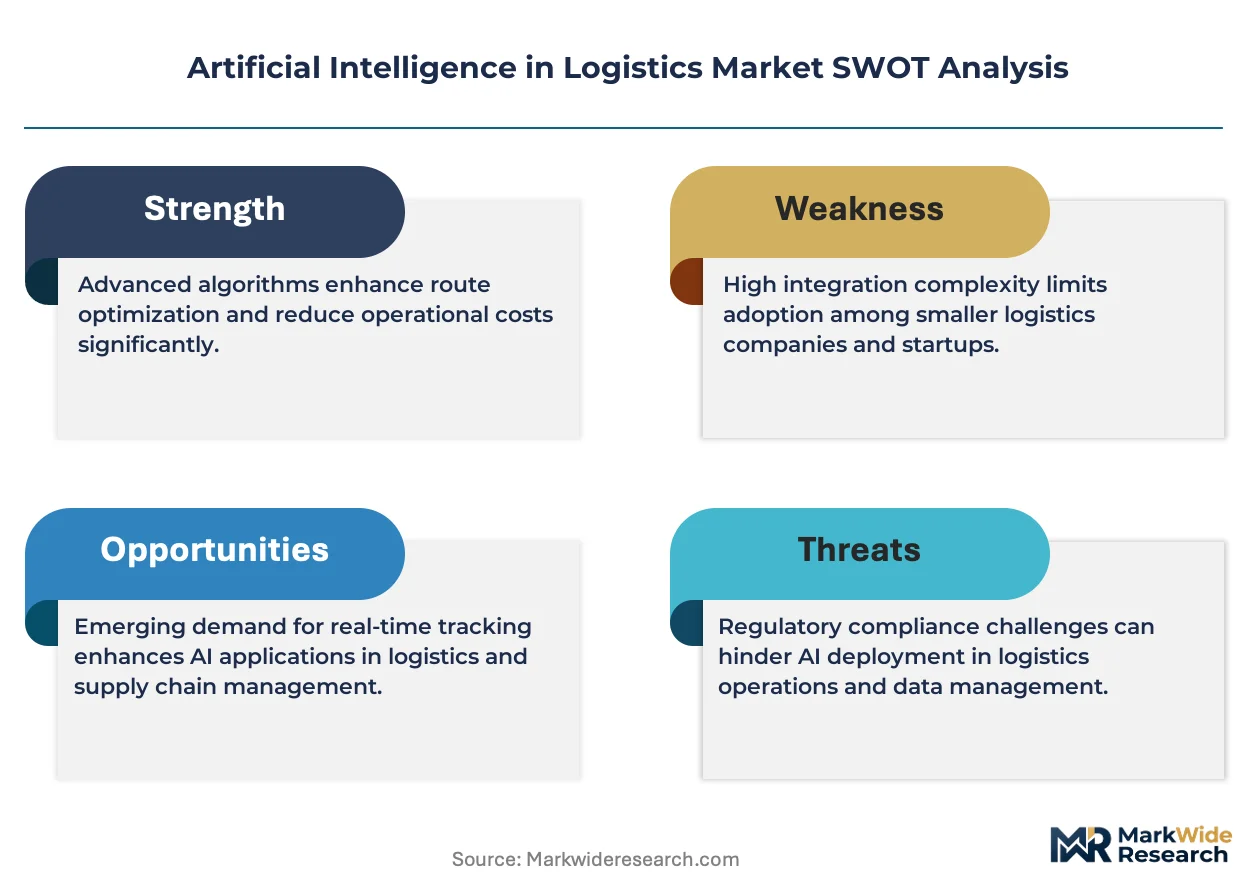
The EU AI Act's risk-classification framework for automated decision-making systems is compressing deployment timelines for warehouse robotics and freight optimization platforms across multimodal supply chains.
Growth Catalysts
- E-commerce fulfillment density:Same-day delivery promises from Amazon and FedEx are forcing 3PLs to deploy predictive routing engines and autonomous sortation systems.
- EU AI Act compliance mandates:Risk-tiered obligations for safety-critical warehouse automation are accelerating vendor investment in explainable AI and human-in-the-loop architectures.
- Computer vision maturation:Damage detection and pallet recognition models trained on NVIDIA infrastructure are reducing manual inspection headcount in high-throughput distribution centers.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in AI training hardware creates single-source dependency for logistics computer vision development.
- Cross-border model portability:Divergent algorithmic governance between Brussels, Beijing, and Washington fragments training data sets and compliance architectures.
- Pharmaceutical cold-chain traceability:FDA guidelines impose sensor density and telemetry retention costs that squeeze margins on temperature-controlled freight AI.
Strategic Opportunities
- India's logistics modernization:The PLI scheme for warehousing and cold-chain infrastructure is opening procurement channels for predictive demand forecasting platforms.
- Edge-AI convergence:On-device inference chips combined with 5G private networks are enabling millisecond-latency routing decisions without cloud dependency.
- Japan's labor scarcity:METI automation incentives are creating demand for autonomous forklift fleets and robotic put-away systems in aging distribution workforces.
Industry Challenges
- Mechatronics talent scarcity:The intersection of robotics hardware and machine learning software requires skill sets concentrated in automotive and semiconductor sectors.
- Legacy ERP integration:SAP and Oracle stack modernization timelines often misalign with AI platform deployment cycles, creating middleware complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Logistics Market |
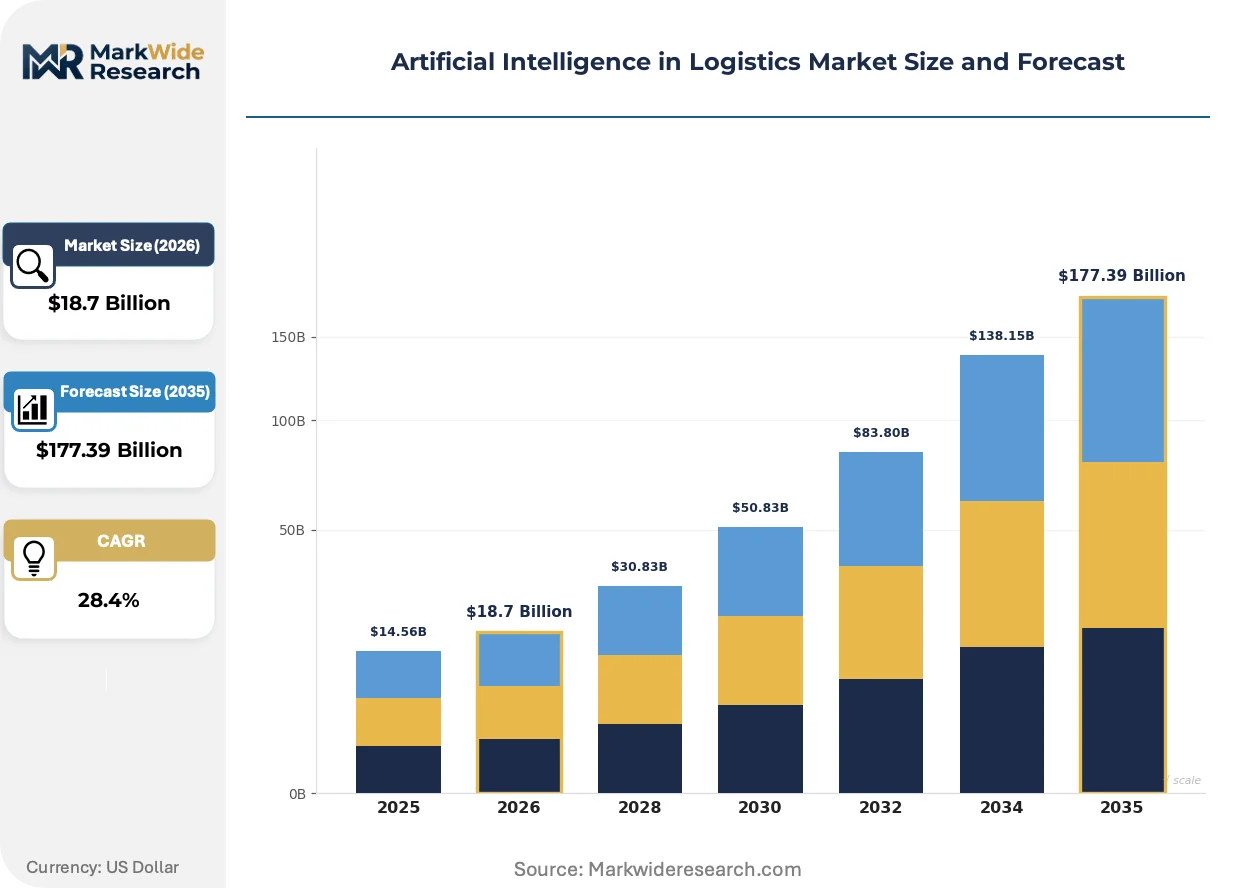
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $177.39 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Predictive Analytics, Natural Language Processing, Computer Vision Application: Supply Chain Optimization, Route Planning, Inventory Management, Demand Forecasting End User: E-commerce, Retail, Manufacturing, Transportation Solution: Warehouse Automation, Fleet Management, Tracking Systems, Freight Management |
| Companies Covered | Alphabet Inc., Amazon.com Inc., Microsoft Corporation, Oracle Corporation, SAP SE, Blue Yonder Group, Inc., Kinaxis Inc., Manhattan Associates, Inc., NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Logistics Market Trends and Innovations
Generative AI copilots are rewiring how logistics operators interact with supply chain software, compressing the gap between natural language queries and actionable dispatch instructions.
Transformer-based demand forecasting is supplanting ARIMA and exponential smoothing models in enterprise TMS deployments. Retailers operating seasonal inventory are adopting these architectures within 12-18 month refresh cycles. The shift is collapsing forecast error rates and enabling dynamic safety-stock repositioning across multi-echelon networks.
China's MIIT algorithmic recommendation provisions are imposing audit-trail requirements on freight-matching platforms that use AI to pair shippers with carriers. Domestic logistics aggregators must now document training data provenance and decision logic for regulator inspection. This is slowing model iteration cycles while favoring state-affiliated cloud providers with pre-cleared compliance architectures.
Shippers are unbundling transportation management from freight audit and payment services, creating procurement fragmentation that favors API-first AI platforms over monolithic TMS suites. Mid-market manufacturers are the primary adopters, stitching together best-of-breed routing, visibility, and settlement tools. The pattern is most pronounced in Germany and the Netherlands, where fragmented carrier markets reward modular procurement strategies.
Artificial Intelligence in Logistics Market Segmentation
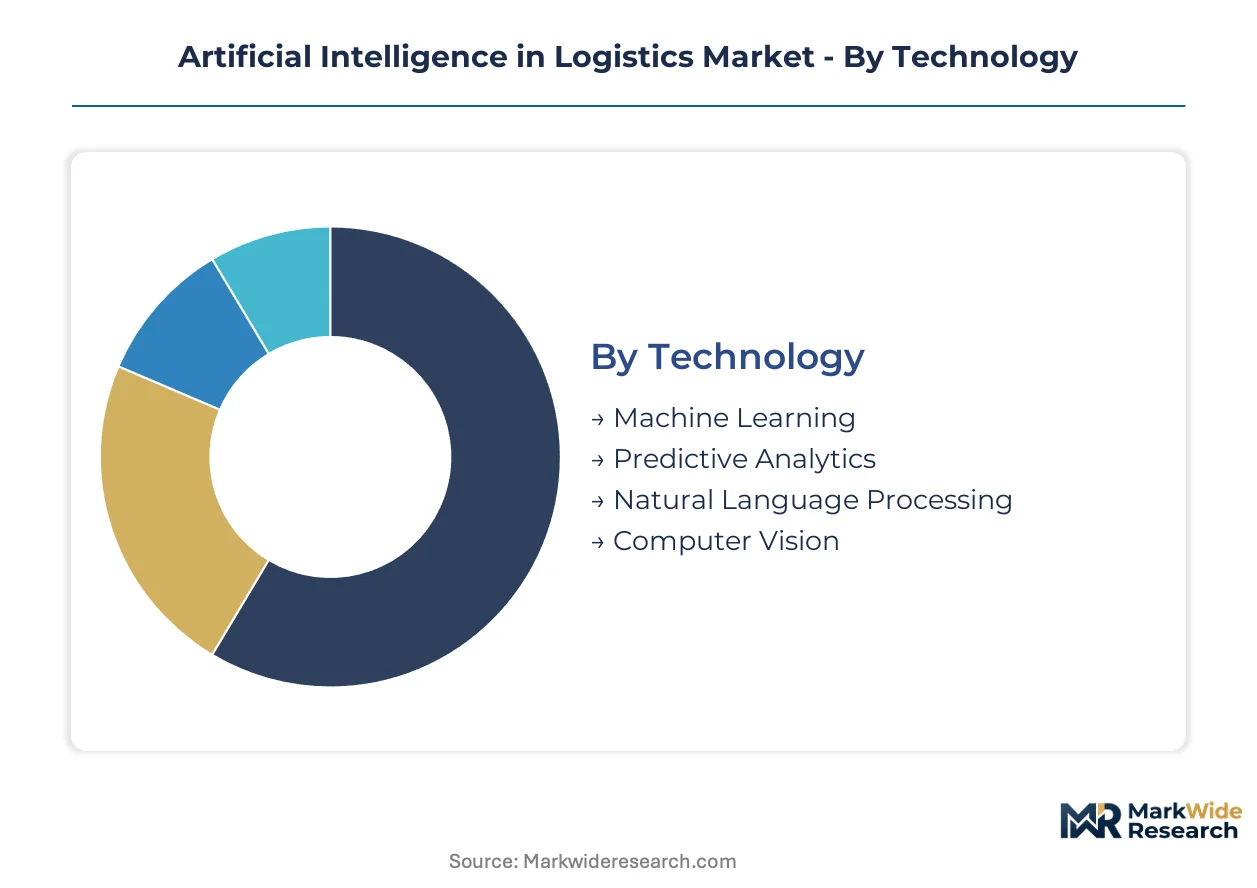
Segmentation in AI logistics reveals where substitution pressures concentrate across technology stacks and operational domains. Vendors must align solution architectures with the specific automation maturity and data infrastructure of each buyer category.
Technology:
Substitution pressure runs strongest against legacy statistical methods in segments where inference latency and model interpretability requirements clash.
- Machine Learning:Supervised and unsupervised algorithms process historical shipment patterns, carrier performance data, and demand signals to optimize network design. E-commerce fulfillment networks in the United States deploy these engines to compress safety stock levels across multi-node distribution architectures while maintaining service-level commitments.
- Computer Vision:Convolutional neural networks and transformer-based architectures enable real-time pallet recognition, damage classification, and autonomous navigation in high-throughput facilities. NVIDIA GPU clusters power training pipelines for these models, creating hardware dependency that shapes vendor procurement strategies in automated sortation centers.
- Predictive Analytics:Time-series forecasting and anomaly detection tools identify transit disruptions before they cascade through multimodal networks.
- Natural Language Processing:Large language models and semantic extraction tools automate document processing, customs clearance, and carrier communication workflows.
Machine Learning anchors the volume base while Computer Vision gains share at the steepest rate.
Application:
Cost tier differentiation separates enterprise deployments with dedicated data science teams from mid-market buyers seeking pre-configured modules.
- Route Planning:Dynamic routing engines ingest real-time traffic, weather, and capacity constraints to optimize last-mile delivery sequences. FedEx and UPS operate the largest proprietary deployments, forcing 3PLs to license comparable capabilities from software vendors to meet same-day delivery expectations in dense urban corridors.
- Warehouse Automation:Orchestration platforms coordinate robotic put-away, pick-to-light systems, and autonomous mobile robots in fulfillment centers. Labor scarcity in Japan's aging distribution workforce accelerates METI-subsidized adoption of these integrated control systems.
- Supply Chain Optimization:Network design and inventory positioning tools balance service levels against working capital requirements.
- Inventory Management:Real-time stock visibility and automated replenishment triggers reduce carrying costs and stockout incidence.
- Demand Forecasting:Transformer-based models supplant ARIMA architectures in seasonal retail environments, collapsing forecast error rates.
Route Planning commands the highest solution premiums while Warehouse Automation shows the steepest expansion trajectory among capital-intensive buyers.
End User:
Customer type determines data sovereignty requirements and integration complexity with existing ERP footprints.
- E-commerce:Pure-play and omnichannel retailers demand sub-second inventory visibility and predictive fulfillment positioning. Amazon's proprietary algorithms set the competitive baseline that shapes vendor RFP requirements across North American and European markets.
- Transportation:Asset-based carriers and freight brokers deploy AI for dynamic pricing, empty-mile reduction, and driver retention optimization. China's MIIT audit-trail mandates for freight-matching platforms slow model iteration cycles while favoring state-affiliated cloud providers with pre-cleared compliance architectures.
- Retail:Brick-and-mortar chains with omnichannel operations balance store fulfillment against distribution center throughput.
- Manufacturing:Industrial firms apply AI to inbound material scheduling and finished goods distribution coordination.
E-commerce anchors current procurement volumes while Transportation is climbing the fastest as regulatory pressure reshapes platform economics.
Solution:
Supply concentration in sensor hardware and edge computing silicon shapes margin structures across deployment modalities.
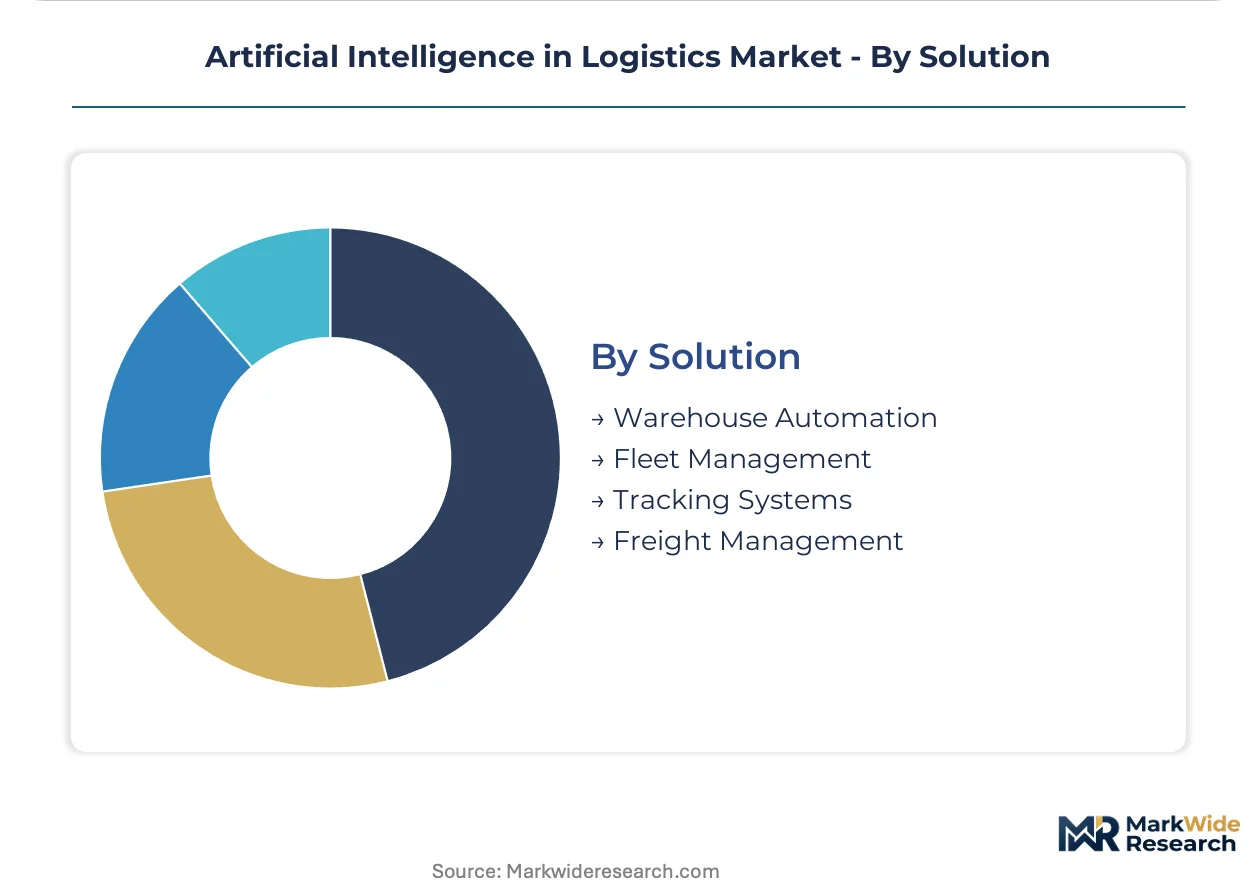
- Warehouse Automation:Integrated robotics control, vision-guided manipulation, and warehouse management system orchestration reduce labor dependency in high-throughput facilities. India's PLI scheme for warehousing infrastructure opens procurement channels for predictive demand forecasting platforms bundled with automation hardware.
- Fleet Management:Telematics aggregation, predictive maintenance, and driver behavior analytics optimize asset utilization in trucking and last-mile delivery operations. The EU AI Act's risk-classification framework imposes explainability requirements on autonomous dispatch decisions that carriers must architect into platform designs.
- Tracking Systems:IoT sensor networks and blockchain-anchored provenance tools provide shipment visibility and condition monitoring.
- Freight Management:Tender automation, carrier selection optimization, and freight audit platforms streamline procurement workflows.
Warehouse Automation dominates capital deployment while Fleet Management is gaining share fastest among asset-light logistics providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU fabrication and cloud infrastructure concentrate in the United States and China, creating dual-polar supply dependencies for logistics AI training workloads. Regulatory divergence between Brussels and Beijing fragments model deployment architectures. Demand clusters around e-commerce fulfillment corridors in North America, automated port networks in East Asia, and EU compliance-driven warehouse retrofits.
United States
Amazon and FedEx operate the densest AI-enabled fulfillment networks, compressing last-mile delivery windows through proprietary routing algorithms. The FAA and NHTSA impose operational safety standards on autonomous delivery vehicles and drone systems. Seattle and Memphis anchor cloud-based logistics AI development, with NVIDIA GPU clusters powering computer vision training for automated sortation facilities.
Germany
Automotive and industrial manufacturers deploy predictive supply chain platforms to synchronize just-in-time component flows. The EU AI Act's risk-classification framework mandates explainable AI architectures for safety-critical warehouse automation. The Rhine-Ruhr corridor concentrates logistics AI procurement, with Duisburg's inland port testing autonomous container handling systems under regulatory supervision.
China
E-commerce platforms and freight aggregators scale algorithmic dispatch systems across multimodal networks. MIIT audit-trail requirements for freight-matching platforms slow model iteration cycles while favoring state-affiliated cloud providers. The Yangtze River Delta logistics cluster—centered on Shanghai and Ningbo—integrates port automation with predictive demand forecasting for manufacturing supply chains.
Japan
Aging distribution workforces and labor scarcity accelerate METI-subsidized adoption of autonomous forklift fleets and robotic put-away systems. Pharmaceutical cold-chain traceability requirements from the PMDA impose sensor density costs on temperature-controlled freight AI. The Chubu region around Nagoya anchors automotive logistics AI deployment, with Toyota City testing predictive inbound material scheduling platforms.
India
The PLI scheme for warehousing and cold-chain infrastructure opens procurement channels for predictive demand forecasting platforms. BIS standards for IoT sensor interoperability shape data architecture requirements for multimodal visibility systems. Mumbai-Pune and Delhi-NCR logistics corridors concentrate e-commerce fulfillment AI adoption, with Bangalore emerging as a development hub for supply chain software exports.
Artificial Intelligence in Logistics Market Competitive Landscape
Concentration sits with hyperscale cloud providers and specialized supply chain software vendors that anchor enterprise adoption through ERP integration. The market structures around three tiers: infrastructure players controlling AI training hardware, platform vendors offering predictive analytics suites, and point-solution specialists in warehouse automation or freight optimization. Strategic moves center on API-first architectures that unbundle transportation management from legacy TMS suites, and partnerships that embed generative AI copilots into existing ERP stacks.
Within the infrastructure tier, NVIDIA Corporation anchors GPU supply chains that power computer vision training for automated logistics facilities. Among platform vendors, Microsoft Corporation and Amazon.com Inc. exemplify divergent strategies—Azure-based supply chain copilots versus proprietary fulfillment algorithms—each occupying positions that shape vendor RFP requirements across North American and European markets. These three names represent the dominant competitive archetypes: hardware infrastructure, enterprise cloud platforms, and vertically integrated operators.
| Leading Market Players |
|---|
| Alphabet Inc. |
| Amazon.com Inc. |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Blue Yonder Group, Inc. |
| Kinaxis Inc. |
| Manhattan Associates, Inc. |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Transformer-based demand forecasting displacing ARIMA models simultaneously redistributes supply chain value toward GPU infrastructure clusters in the United States and China while compressing pricing premiums for legacy statistical software tiers. This substitution dynamic concentrates procurement power with hyperscale cloud providers and fragments margin pools for point-solution vendors.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for safety-critical warehouse automation systems by mandating explainable AI architectures that add compliance overhead. Three-tier pricing structure across premium, standard, and economy levels separates enterprise deployments with dedicated data science teams from mid-market buyers seeking pre-configured modules. Cost compression in the standard tier intensifies because SAP and Oracle integration complexity extends implementation timelines. Mid-market manufacturers exhibit highest price sensitivity due to middleware budget constraints, while e-commerce fulfillment networks show lowest sensitivity given same-day delivery ROI thresholds.
Supply Chain Analysis
NVIDIA GPU fabrication chokepoints in Taiwan and South Korea underwrite supply security for computer vision training pipelines in automated sortation facilities. AI training hardware draws from TSMC foundry capacity, HBM memory from SK Hynix, and CUDA software ecosystems anchored in California. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through hyperscale cloud providers and specialized robotics integrators serving fulfillment center deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards organizations that command scarce mechatronics talent bridging robotics hardware and machine learning software, while penalizing vendors without ERP integration depth.
For Market Incumbents: Fortify proprietary fulfillment algorithm moats through backward integration into edge-AI silicon design, countering emerging API-first platforms that unbundle transportation management from legacy TMS suites. Prioritize Azure and Oracle ERP stack certification investments to defend against Microsoft supply chain copilot expansion. Channel control through 3PL partnership exclusivity represents the critical defensive lever. For New Entrants and Emerging Players: Mid-market freight audit and payment unbundling in Germany and Netherlands presents the most penetrable service-layer gap where incumbents under-serve fragmented carrier markets. Target API-first routing modules that stitch into best-of-breed procurement strategies. Go-to-market angle: pre-built SAP connectors that collapse integration timelines from 18 months to 90 days. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated operators with captive GPU supply agreements. Long-term viability hinges on regulatory portability across Brussels-Beijing-Washington compliance architectures. Acquisition target archetype: computer vision specialists with NVIDIA training infrastructure relationships. Watch EU AI Act enforcement intensity as inflection indicator for explainable AI valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chip Development | On-device inference reduces cloud dependency for millisecond-latency routing decisions in 5G private networks. |
| ERP Copilot Integration | Azure-based supply chain copilots embedded in SAP and Oracle stacks accelerate enterprise procurement velocity. |
| Explainable AI Certification | EU AI Act compliance architectures for safety-critical warehouse automation create vendor differentiation. |
| Freight-Matching Platform Audit | MIIT training data provenance documentation slows model iteration but favors state-affiliated cloud providers. |
| Robotics Talent Acquisition | Mechatronics skill concentration in automotive and semiconductor sectors requires targeted hiring pipelines. |
Research Methodology
The analysis maps machine learning deployment modes, computer vision training pipelines, predictive analytics engines, and natural language processing workflows, each validated through CTOs at 3PLs, warehouse operations directors, IT procurement officers at e-commerce platforms, and robotics integration specialists. Primary interview findings triangulated against SEC 10-K filings from hyperscale cloud providers, NVIDIA data center revenue disclosures, EU AI Act regulatory texts, and MIIT algorithmic governance circulars. Bottom-up segment sizing and top-down macro constraint checks ensured consistency.
Consistency checks validated volume and value outputs against hyperscaler capex trajectories and automotive logistics AI procurement patterns across the projection horizon. Segmentation dimensions modeled include technology type, application domain, end-user vertical, and solution deployment modality. CAGRs derived from logistic diffusion curves fitted to enterprise adoption timelines and regulatory compliance deadline clustering. Industry-specific inputs encompass GPU supply lead times and ERP modernization cycle frequencies.
Forecasts assume regulatory continuity in EU AI Act risk-classification enforcement and MIIT audit-trail mandates; material policy shifts would require re-modeling compliance cost burdens and model portability constraints. Practitioners should keep alternative scenarios live as divergence between Brussels, Beijing, and Washington algorithmic governance timelines evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Asia-Pacific AI Orchestration Market
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
North America Artificial Intelligence Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
MENA Artificial Intelligence Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market
Artificial Intelligence (AI)
AI Code Assistant Market
Artificial Intelligence (AI)
AI Platform Market
Artificial Intelligence (AI)
North America and Europe Chatbot Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Legal AI Software Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Manufacturing Market
Artificial Intelligence (AI)
Intelligent Virtual Assistant Market
Artificial Intelligence (AI)
AI in Medical Writing Market
Artificial Intelligence (AI)
Europe Decision Intelligence Market