
 Artificial Intelligence Systems Spending Market | 2026-2036
Artificial Intelligence Systems Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence Systems Spending Market Analysis
The capital-intensity divergence between hyperscalers and specialized research labs is unwinding competitive dynamics across AI infrastructure procurement. NVIDIA Corporation dominates GPU supply chains for training workloads, while Microsoft leverages its cloud distribution to anchor enterprise adoption. Alphabet Inc. sustains R&D intensity through DeepMind and Google Cloud integration, and OpenAI competes on frontier model capabilities without owning downstream infrastructure.
Artificial Intelligence Systems Spending encompasses enterprise and government expenditure on hardware, software, and services enabling machine perception, automated reasoning, and generative output, typically measured by compute cluster capacity, model parameter scale, and inference latency benchmarks. Cloud-based deployment captures the dominant share of new procurement as organizations prioritize elastic scaling over fixed on-premise infrastructure. Machine learning solutions within the solution-type category concentrate margin pools where proprietary training frameworks and fine-tuning services create switching costs.
The EU AI Act, alongside FDA guidance on AI-enabled medical devices and China's algorithmic recommendation provisions under SAMR, shapes product standards and market access thresholds across jurisdictions. Compliance costs redirect procurement toward vendors with established conformity assessment capabilities. Stakeholders must monitor how regulatory fragmentation between Brussels, Washington, and Beijing influences data localization requirements and cross-border model deployment strategies.
Market Dynamics
The concentration of GPU supply chains among a single semiconductor foundry is reshaping procurement timelines and pricing power across enterprise AI deployments.
Growth Catalysts
- EU AI Act Conformity Requirements:Healthcare providers accelerate procurement of clinical decision-support systems to meet high-risk application standards before enforcement deadlines.
- Federal Innovation Hubs:United States defense contractors channel procurement through designated clusters, concentrating demand and accelerating vendor qualification cycles.
- Elastic Cloud Scaling:Enterprise buyers prioritize cloud-based deployment models over fixed on-premise infrastructure, expanding addressable market for managed inference services.
Market Restraints
- Foundry Concentration Risk:Advanced GPU fabrication depends on Taiwan-based semiconductor manufacturing, exposing procurement timelines to geopolitical disruption.
- Energy Input Volatility:Data center power consumption faces escalating electricity costs and grid interconnection delays in Northern Virginia and Frankfurt clusters.
- Technical Talent Scarcity:Machine learning operations engineering skills concentrate among specialists in San Francisco and Beijing, constraining deployment velocity elsewhere.
Strategic Opportunities
- Edge AI Deployment:Manufacturing facilities in Germany and Japan adopt on-premise inference hardware for quality inspection, bypassing cloud latency constraints.
- Regulatory Tailwinds from FDA:AI-enabled medical device guidance creates procurement pathways for radiology and pathology automation vendors with established 510(k) clearance capabilities.
- Sovereign Cloud Mandates:French and German public sector buyers require data localization, opening market share for domestic cloud providers with certified infrastructure.
Industry Challenges
- Conformity Assessment Backlogs:EU AI Act notified body capacity limits delay high-risk system certifications, freezing procurement cycles for healthcare and transport applications.
- Integration Complexity:Enterprise buyers struggle to embed generative models into legacy ERP and CRM architectures without custom middleware development.
- IP Licensing Fragmentation:Training data provenance disputes and model weight licensing terms create legal uncertainty for commercial deployment at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence Systems Spending Market |
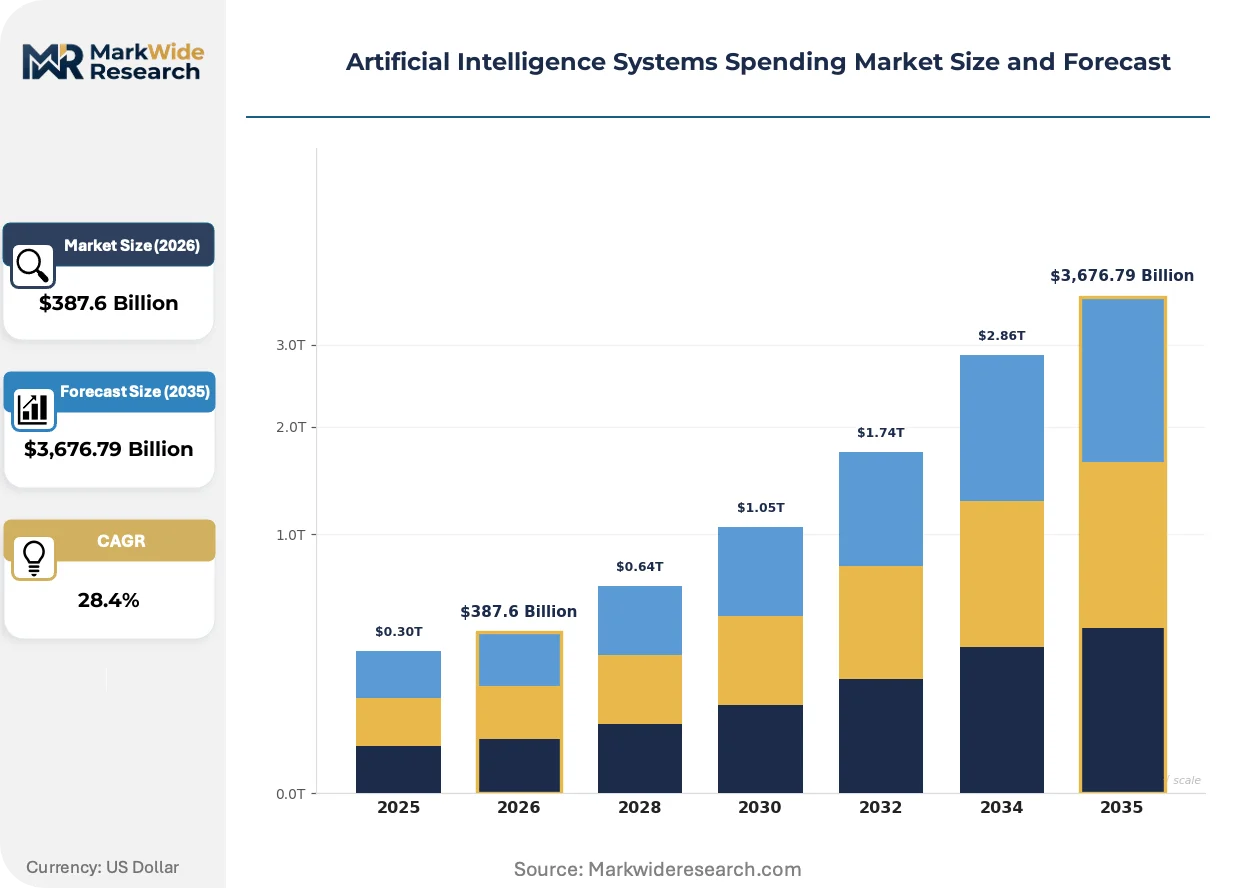
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $3,676.79 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Type: Machine Learning, Natural Language Processing, Computer Vision, Robotics End User: Healthcare, BFSI, Retail, Manufacturing Application Area: Fraud Detection, Predictive Analytics, Customer Support, Process Automation |
| Companies Covered | Alphabet Inc., Meta, OpenAI, IBM, Oracle, NVIDIA Corporation, Amazon, Anthropic, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence Systems Spending Market Emerging Trajectories
Foundation model architectures are compressing development cycles while regulatory frameworks harden compliance requirements across jurisdictions.
Retrieval-augmented generation is supplanting fine-tuning for enterprise knowledge management applications. Financial services and legal departments adopt RAG pipelines to ground outputs in proprietary document repositories without retraining base models. This architecture is supplanting custom model development, collapsing six-month build cycles into weeks and redirecting budgets toward vector database infrastructure.
The EU AI Act's risk-classification framework is mandating conformity assessments for high-risk applications including biometric identification and credit scoring. Vendors must maintain technical documentation and human oversight protocols, increasing compliance costs. Medical device manufacturers face overlapping obligations from EMA and notified bodies, consolidating procurement toward incumbents with established quality management systems.
Enterprise buyers now demand consumption-based pricing for inference workloads rather than fixed licensing. Retail and logistics operators prefer per-token billing aligned with seasonal demand fluctuations. This pattern is most visible among mid-market adopters in the United States, where finance teams resist multi-year commitments for unproven use cases.
Artificial Intelligence Systems Spending Market Segmentation
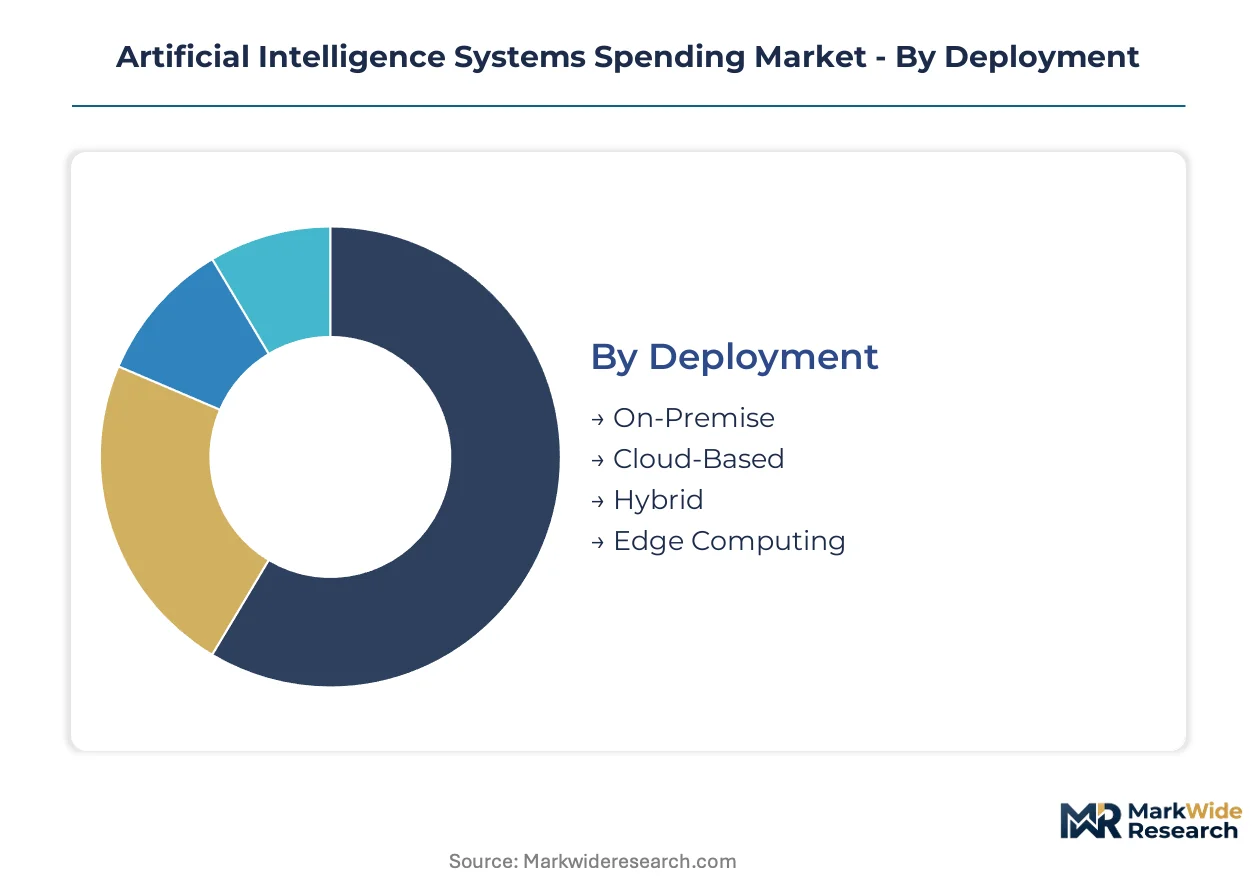
AI procurement patterns diverge sharply across deployment architectures and solution types, with regulatory pressure and latency requirements reshaping budget allocation. Organizations segment spending based on where inference occurs, what cognitive task is automated, and which industry compliance framework applies.
Deployment:
Geographic spread varies by deployment mode, with cloud-based procurement concentrating in the United States and Germany while edge computing expands through Japanese manufacturing corridors and German automotive zones.
- On-Premise:Dedicated server clusters within enterprise data centers host sensitive workloads subject to HIPAA, GDPR, or sector-specific data residency mandates. Financial institutions in Switzerland and defense contractors in the United States maintain on-premise inference for classified or proprietary model weights, absorbing higher capital expenditure to retain operational sovereignty.
- Cloud-Based:Elastic compute provisioning through hyperscale providers dominates new procurement across mid-market adopters. Healthcare systems in France and retail operators in the United Kingdom prioritize consumption-based billing aligned with seasonal demand fluctuations, avoiding fixed infrastructure commitments.
- Hybrid:Split architectures route training workloads to cloud infrastructure while retaining inference at the edge. Telecommunications providers in South Korea deploy hybrid stacks to balance model development velocity against subscriber data localization requirements under national cybersecurity frameworks.
- Edge Computing:On-device inference hardware addresses latency-critical applications. Quality inspection stations in Toyota manufacturing plants and predictive maintenance sensors in Siemens energy infrastructure embed specialized accelerators, bypassing round-trip delays to centralized data centers.
Cloud-based deployment commands the established base. The steepest expansion runs through edge computing.
Solution Type:
Cost tier stratification separates foundational platform investments from specialized application layers, with machine learning infrastructure absorbing the largest capital allocations while computer vision solutions command premium per-unit pricing.
- Machine Learning:Statistical modeling frameworks and automated feature engineering pipelines form the substrate for predictive applications. Banks in Singapore and logistics operators in the Netherlands deploy gradient-boosted ensembles for demand forecasting, with procurement budgets concentrating on managed training services and vector database infrastructure.
- Natural Language Processing:Transformer architectures for text generation, summarization, and semantic search drive enterprise knowledge management transformation. Legal departments in London and compliance functions in New York adopt retrieval-augmented generation pipelines, collapsing custom model development cycles from months to weeks.
- Computer Vision:Convolutional and vision-transformer architectures enable automated inspection and biometric analysis. Medical imaging vendors with FDA 510(k) clearance and EMA quality management certification capture procurement share in radiology automation, with pricing reflecting regulatory validation overhead.
- Robotics:Perception-action loops for physical manipulation integrate sensor fusion with motion planning. Warehouse automation in Amazon fulfillment centers and precision agriculture in Israeli kibbutzim deploy robotic systems combining computer vision with mechanical actuation, requiring synchronized hardware-software procurement.
Machine learning commands the established base. Natural language processing is climbing the fastest.
End User:
Application maturity varies by sector, with healthcare and BFSI operating under stringent regulatory oversight while manufacturing and retail prioritize operational efficiency metrics.
- Healthcare:Clinical decision-support systems and diagnostic automation face overlapping FDA and EU AI Act conformity requirements. Hospital procurement committees in Germany and integrated delivery networks in California accelerate vendor qualification for high-risk applications ahead of enforcement deadlines.
- BFSI:Algorithmic trading, credit scoring, and fraud detection deploy real-time inference on transaction streams. Swiss private banks and Singaporean sovereign wealth funds invest in explainable AI frameworks to satisfy prudential regulator scrutiny of automated lending decisions.
- Retail:Demand forecasting, dynamic pricing, and customer segmentation drive cloud-based procurement. Omnichannel operators in the United Kingdom and grocery chains in France prioritize seasonal elasticity over fixed infrastructure, aligning spending with revenue volatility.
- Manufacturing:Predictive maintenance and quality inspection anchor edge AI deployment. Automotive suppliers in Stuttgart and electronics assemblers in Shenzhen procure on-premise inference hardware to minimize production line latency and protect process intellectual property.
BFSI commands the established base. Healthcare is gaining share fastest.
Application Area:
Customer type differentiation separates enterprise-wide platforms from departmental point solutions, with fraud detection and process automation commanding the largest implementation budgets.
- Fraud Detection:Real-time transaction scoring and anomaly identification require sub-100-millisecond inference latency. Payment processors in India under RBI guidelines and card networks in the United States deploy specialized inference clusters to minimize false-positive rates while containing computational cost.
- Predictive Analytics:Demand forecasting, churn modeling, and risk scoring leverage historical data repositories. Energy traders in Denmark and crop insurers in the United States Midwest integrate satellite imagery with weather models, procuring GPU capacity for seasonal simulation workloads.
- Customer Support:Conversational agents and ticket routing automation reduce human agent headcount. Telecommunications operators in Brazil and e-commerce platforms in Southeast Asia deploy multilingual large language models, with procurement concentrating on fine-tuning services for regional dialect coverage.
- Process Automation:Document extraction, compliance checking, and workflow orchestration replace rules-based systems. Insurance claims processing in Australia and mortgage underwriting in Canada adopt cognitive automation, redirecting procurement from robotic process automation licenses to AI-native platforms.
Process automation commands the established base. Fraud detection shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense contractors concentrate procurement through federal innovation hubs, while German automotive suppliers and Japanese electronics manufacturers prioritize edge inference hardware to minimize production latency. This consumption-mix differential separates cloud-dominant markets from those embedding specialized accelerators on factory floors.
United States
Federal agencies and defense contractors channel AI procurement through designated innovation hubs in Northern Virginia and Austin. The FDA's guidance on AI-enabled medical devices shapes compliance pathways for clinical decision-support vendors. Hospital systems in California accelerate vendor qualification ahead of enforcement deadlines for high-risk applications.
Germany
Automotive suppliers in Stuttgart and manufacturing conglomerates deploy edge AI for quality inspection and predictive maintenance. The EU AI Act imposes conformity requirements on high-risk applications, redirecting procurement toward vendors with established notified body relationships. Bavarian industrial clusters embed specialized inference hardware to protect process intellectual property.
China
Domestic cloud providers and state-backed research institutes scale training clusters for foundation model development. SAMR's algorithmic recommendation provisions govern commercial deployment of consumer-facing AI services. Shenzhen electronics assemblers procure on-premise inference accelerators to bypass data localization constraints under national cybersecurity frameworks.
Japan
Precision manufacturers in Toyota production corridors and semiconductor equipment vendors adopt on-device inference for sub-millisecond quality control. METI's industrial digitalization incentives subsidize edge AI deployment in aging factory infrastructure. Nagoya-area automotive suppliers integrate vision transformers directly into welding and painting stations.
United Kingdom
Financial services firms in London deploy retrieval-augmented generation for compliance documentation and risk modeling. The Information Commissioner's Office guidance on automated decision-making shapes procurement criteria for credit scoring applications. Cambridge-based research labs commercialize specialized training frameworks for legal and pharmaceutical knowledge management.
Artificial Intelligence Systems Spending Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscalers controlling cloud distribution channels while semiconductor fabricators and frontier research labs occupy adjacent positions. The upper tier consolidates around entities combining compute infrastructure with model development capabilities. Three archetypes dominate: vertically integrated cloud platforms, specialized AI research organizations, and semiconductor supply chain anchors. Competitive moves concentrate on strategic partnerships between model developers and infrastructure providers, alongside geographic expansion of certified cloud regions to satisfy data localization mandates.
Within the integrated platform tier, Microsoft and Amazon exemplify cloud-dominant positioning through enterprise distribution networks and elastic compute provisioning. NVIDIA Corporation anchors semiconductor supply chain concentration for training workloads. Among frontier research specialists, OpenAI and Anthropic occupy positions defined by large-scale model capabilities without captive infrastructure ownership.
| Leading Market Players |
|---|
| Alphabet Inc. |
| Meta |
| OpenAI |
| IBM |
| Oracle |
| NVIDIA Corporation |
| Amazon |
| Anthropic |
| Microsoft |
| Others |
Supply Flow & Price Mechanics
Capacity reservation contracts with Taiwan Semiconductor Manufacturing anchor procurement timelines for GPU clusters, locking hyperscalers into multi-year pricing visibility while exposing buyers to foundry concentration risk. These arrangements transfer upfront capital burden to cloud providers who then meter consumption through token-based billing tiers.
Pricing Analysis
Long-term offtake agreements dominate procurement for training infrastructure, with hyperscalers securing wafer starts years ahead of silicon delivery. Price differentiation rests on certification tier—FDA-cleared medical AI commands premium multiples over uncertified enterprise tools—and volume scale, where petabyte-scale buyers extract steep discounts from inference providers. Pricing pressure stems from energy input volatility in Northern Virginia and Frankfurt data center clusters, compressing margins for operators without renewable power purchase agreements. Mid-market healthcare systems exhibit highest price sensitivity, resisting multi-year commitments for unproven clinical decision-support applications.
Supply Chain Analysis
Inventory lead times for advanced GPUs now stretch across eighteen to twenty-four month horizons, constraining deployment velocity for enterprise buyers without established foundry relationships. Geographic supply concentrates in Taiwan, South Korea, and the United States, with TSMC's N4 and N3 processes feeding NVIDIA and AMD accelerator designs. Raw material dependencies span high-purity silicon wafers, advanced packaging substrates from Japan, and rare earth elements for magnetic components in cooling systems. Single-source vulnerability at the foundry layer exposes procurement timelines to geopolitical disruption across the Taiwan Strait. Distribution runs through hyperscale cloud marketplaces and direct OEM channels to enterprise data centers and edge deployment sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model adoption sits in early-cycle expansion, with enterprise buyers shifting from pilot programs to production deployments at accelerating velocity. Regulatory tailwinds from the EU AI Act and FDA guidance on AI-enabled medical devices create compliance-driven procurement windows.
For Market Incumbents: Fortify cloud distribution dominance through deeper integration with enterprise SaaS stacks, embedding inference APIs directly into Microsoft 365 and Salesforce workflows. Accelerate certification investments for EU AI Act high-risk application categories before notified body capacity bottlenecks freeze vendor qualification cycles. Acquire specialized training framework providers to lock in switching costs around proprietary fine-tuning services.
For New Entrants and Emerging Players: Edge AI deployment gaps in German automotive and Japanese manufacturing corridors offer white-space entry points where hyperscaler cloud latency fails quality inspection requirements. Sovereign cloud mandates in France and Germany create procurement pathways for domestic providers with certified data localization infrastructure. Pursue vertical-specific conformity assessment pre-certification to bypass incumbent advantages in healthcare and transport applications.
For Investors and Strategic Acquirers: Specialized vector database and RAG infrastructure vendors represent compelling acquisition targets as retrieval-augmented generation displaces custom model development. Long-term viability hinges on differentiation through regulatory certification depth rather than raw model scale. Monitor EU AI Act notified body capacity expansion as the critical inflection signal for high-risk application market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding inference APIs into Microsoft 365 and Salesforce workflows locks in enterprise distribution. |
| Regulatory Certification | FDA 510(k) clearance and EU AI Act conformity assessment open procurement pathways in healthcare. |
| Edge Hardware Deployment | On-premise inference accelerators in Stuttgart and Nagoya bypass cloud latency for quality inspection. |
| Strategic Partnership | Foundry capacity reservations with TSMC secure GPU supply for training cluster expansion. |
| Geographic Expansion | Certified cloud regions in Paris and Frankfurt satisfy French and German data localization mandates. |
Methodological Framework
A spread of perspectives from hyperscaler procurement officers, hospital IT directors, semiconductor supply chain managers, and AI research lab operations leads converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against SEC filings, hyperscaler capex disclosures, FDA 510(k) clearance databases, and EU AI Act implementation guidance. Bottom-up triangulation across deployment model adoption curves and top-down cross-checks against aggregate infrastructure spending estimates anchored the market sizing.
Segmentation dimensions modeled include deployment architecture, solution type, end-user industry, and application area across the analysis window. Analytical framework projections incorporate elastic cloud scaling adoption patterns, edge computing penetration in manufacturing corridors, and regulatory compliance cost pass-through to vendor pricing. CAGRs derive from fitted curves on historical GPU shipment data and forward-looking enterprise survey responses on AI budget allocation.
Forecasts assume regulatory continuity in Brussels, Washington, and Beijing; material policy shifts in AI governance would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Model Validation and Automation Market
Artificial Intelligence (AI)
Artificial Neural Network Market
Artificial Intelligence (AI)
Global Voice Assistant Application Market
Artificial Intelligence (AI)
Edge AI Hardware Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Neural Network Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Global Natural Language Generation (NLG) Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Global Call Center AI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Automotive Market
Artificial Intelligence (AI)
AI Watermarking Market
Artificial Intelligence (AI)
Generative AI Market