
 Artificial Intelligence and Machine Learning Market | 2026-2036
Artificial Intelligence and Machine Learning Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence and Machine Learning Market Analysis
Enterprise buyers are unwinding the dominance of early adopter tech firms as legacy manufacturers and healthcare systems scale procurement. Microsoft Corporation leverages its cloud infrastructure to anchor generative AI services across institutional clients. NVIDIA Corporation dominates specialized silicon design for training workloads, sustaining pricing power through captive supply of advanced GPUs. IBM Corporation navigates hybrid deployment complexity, positioning its Watson platforms for regulated industries with strict data residency requirements.
Artificial intelligence and machine learning denote computational systems that learn patterns from structured and unstructured data using neural architectures, statistical optimization, and feedback loops to automate prediction, classification, and generation tasks. These systems typically operate on tensor-processing hardware with training clusters exceeding thousands of interconnected accelerators, enabling inference latencies measured in milliseconds for real-time applications. Platform and software segments capture the majority of current revenue as enterprises prioritize API-accessible model services over in-house framework development. Edge deployment is expanding fastest among manufacturing end users seeking to reduce transmission latency for quality-control vision systems. Predictive analytics applications retain mature margins in BFSI, where regulatory scrutiny slows replacement cycles but locks in long-term contracts.
The EU AI Act, FDA guidance on AI-enabled medical devices, and China's SAMR algorithmic recommendation provisions are fragmenting compliance requirements across jurisdictional boundaries. Product developers now face divergent testing protocols, documentation standards, and human oversight mandates that shape go-to-market sequencing and R&D allocation. Stakeholders must monitor enforcement patterns in the European Union and the United States to anticipate which conformity frameworks will propagate into de facto global standards.
Market Dynamics
Foundation model commoditization is compressing margins for general-purpose AI providers while concentrating value capture in specialized inference infrastructure and proprietary data pipelines. This structural force is reallocating capital from model development toward vertical-specific deployment tooling and regulatory compliance layers.
Growth Catalysts
- FDA AI/ML-Based SaMD Guidance:The FDA's predetermined change control plans accelerate clearance timelines for diagnostic algorithms, unlocking hospital procurement budgets for radiology and pathology workflows.
- Edge AI silicon cost curves:Taiwan Semiconductor Manufacturing's advanced packaging capacity expansion reduces unit economics for vision-based quality control in automotive assembly lines.
- EU AI Act high-risk system mandates:Conformity assessment requirements for credit scoring and recruitment algorithms create recurring revenue streams for audit and monitoring service providers.
Market Restraints
- Advanced GPU supply concentration:Taiwan-based foundry capacity constraints and US export controls on H100 and successor chips limit training cluster expansion for non-allied jurisdictions.
- Training energy cost volatility:Data center power purchase agreements in Texas and Arizona face basis risk from renewable intermittency and transmission congestion.
- Foundation model substitution threat:Open-weight releases from Meta's Llama family and Mistral compress pricing power for closed API providers in text generation and code completion.
Strategic Opportunities
- India's semiconductor PLI scheme:Design-linked incentives for AI chip development attract fabless startups targeting inference acceleration for Indic language models.
- Neuromorphic-optical convergence:Photonic tensor core architectures from Lightmatter and Ayar Labs enable sub-picosecond latency for high-frequency trading and autonomous vehicle sensor fusion.
- US CHIPS Act fabrication subsidies:Intel and TSMC Arizona facilities create captive advanced packaging ecosystems for domestic AI accelerator supply chains.
Industry Challenges
- MLOps talent scarcity:Production-grade model monitoring, drift detection, and automated retraining pipelines require hybrid software engineering and statistical expertise that outpaces graduate program output.
- EU AI Act documentation burden:Technical file assembly for high-risk system conformity assessments demands 12-18 month preparation cycles before notified body engagement.
- Legacy ERP integration complexity:SAP and Oracle environments in manufacturing and financial services resist real-time API connectivity for predictive maintenance and fraud detection deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence and Machine Learning Market |
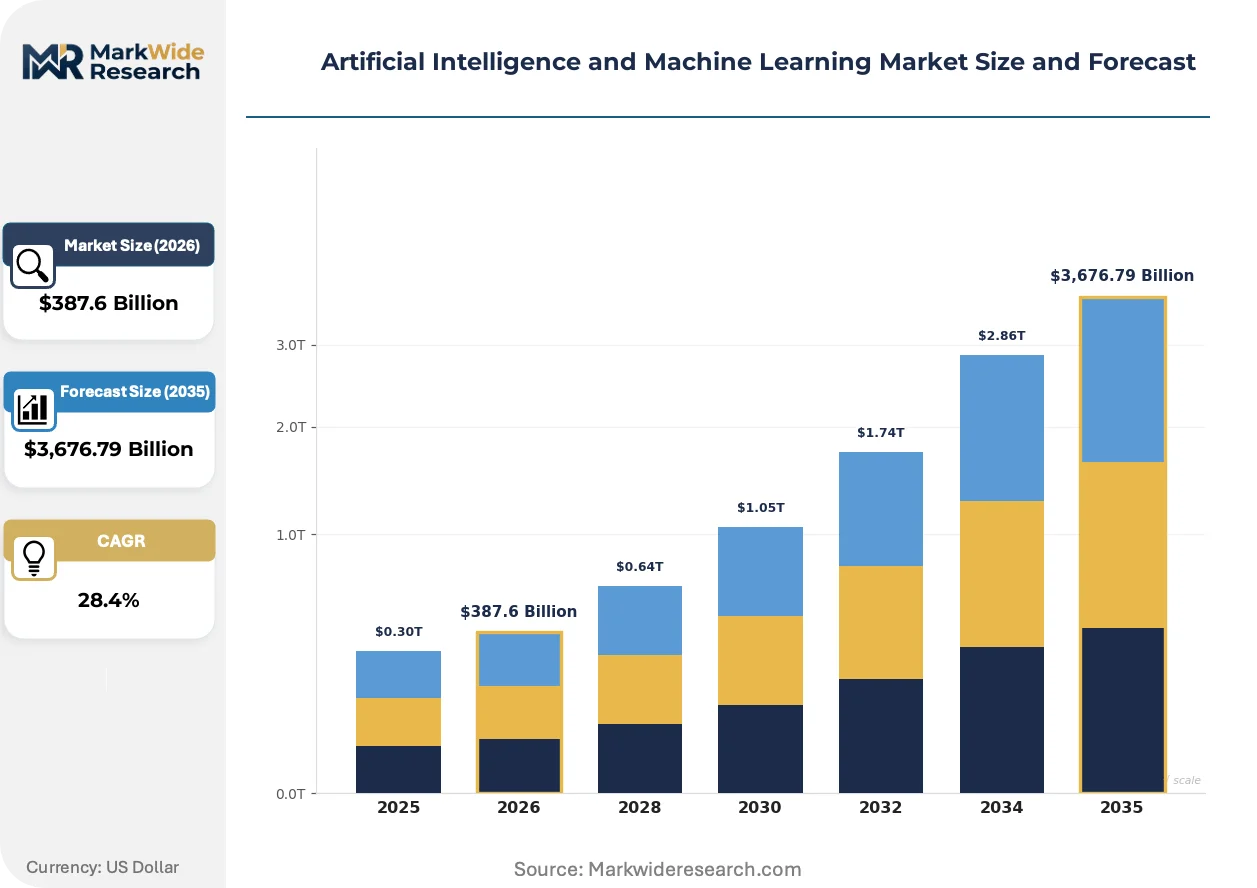
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $3,676.79 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Framework, Platform, Tool Application: Natural Language Processing, Image Recognition, Predictive Analytics, Robotics Deployment: Cloud, On-Premises, Hybrid, Edge End User: Healthcare, BFSI, Retail, Manufacturing |
| Companies Covered | Google LLC (Alphabet Inc.), Microsoft Corporation, IBM Corporation, Amazon Web Services (AWS), NVIDIA Corporation, Intel Corporation, H2O.ai, Inc., Oracle Corporation, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence and Machine Learning Market Emerging Trajectories
Model architecture innovation is fragmenting along task-specific efficiency axes, with sparse expert systems and quantization techniques displacing brute-force scaling as the dominant optimization path. This shift is redistributing competitive advantage from pure compute scale toward data curation and domain adaptation depth.
Mixture-of-experts routing is decomposing monolithic transformer architectures into conditional computation graphs that activate parameter subsets per input token. Google DeepMind's Gemini and Mistral's implementation demonstrate 3-5x inference cost reduction for long-context retrieval tasks. Manufacturing quality assurance teams in Germany and Japan are deploying these architectures for multi-modal defect detection that processes spectral, visual, and acoustic signals within unified embedding spaces.
The EU AI Act's risk classification framework is mandating conformity assessment procedures for biometric identification and critical infrastructure management systems. Notified bodies in Germany and France are developing sector-specific audit protocols that exceed baseline harmonized standards. Medical device manufacturers are bifurcating product roadmaps into EU-compliant and rest-of-world variants, with the European configuration prioritizing human-in-the-loop override mechanisms and training data provenance documentation.
Hospital procurement committees are consolidating vendor relationships around integrated diagnostic platforms that bundle imaging hardware, AI inference engines, and long-term service contracts. Radiology departments at Mass General Brigham and Mayo Clinic are negotiating enterprise-wide licenses that displace point-solution startups. This concentration pattern is most pronounced in the United States, where health system consolidation and centralized IT governance accelerate standardization around Microsoft and Epic-integrated workflows.
Artificial Intelligence and Machine Learning Market Segmentation
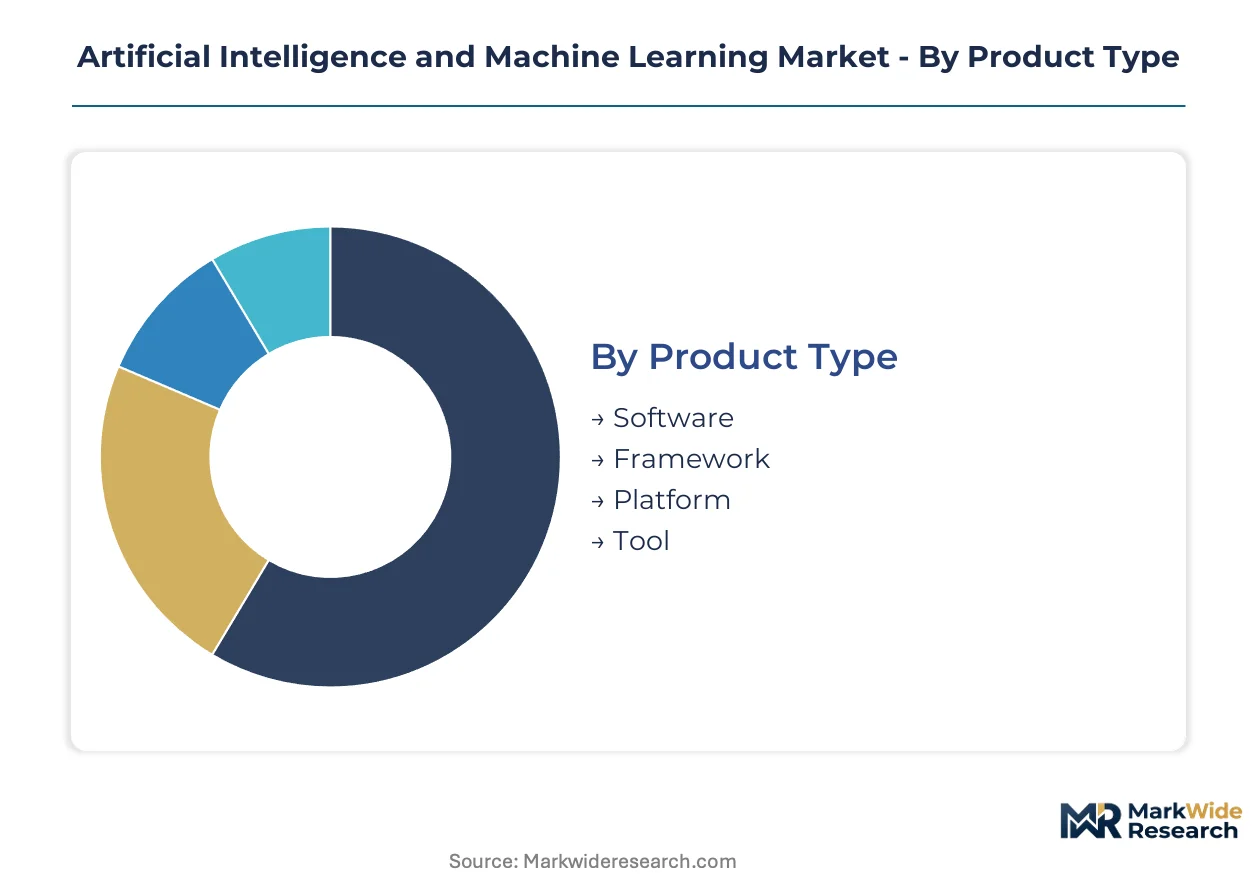
Segmentation reveals how AI/ML value capture fragments across infrastructure layers, use-case maturity, and regulatory exposure. Procurement patterns diverge sharply between cloud-native enterprises and regulated institutions with data residency constraints.
Product Type:
Software solutions dominate domestic procurement in the United States and European Union, while platform exports concentrate from cloud providers with multi-region availability zones. Framework and tool adoption spreads more evenly across development centers in India, Israel, and Singapore.
- Software:Pre-trained model APIs and managed inference endpoints eliminate infrastructure overhead for enterprise developers. Hospital systems in the United States and Germany prioritize software procurement for diagnostic imaging workflows, driven by FDA and EU AI Act conformity timelines that favor vendor-managed compliance.
- Platform:Integrated development environments bundle data pipelines, experiment tracking, and model registry services for MLOps teams. Demand clusters among financial services institutions in London, New York, and Singapore seeking unified governance for algorithmic trading and credit risk models.
- Framework:Open-source tensor computation libraries and neural architecture implementations.
- Tool:Specialized utilities for data annotation, model compression, and drift detection.
Software holds the largest share; momentum sits with Platform.
Application:
Natural Language Processing deployments scale fastest in customer service automation, while Predictive Analytics retains pricing power in regulated BFSI environments. Image Recognition and Robotics applications show divergent geographic concentration patterns.
- Natural Language Processing:Transformer-based text generation, summarization, and retrieval systems process billions of tokens across enterprise knowledge bases. Contact center operators in India and the Philippines deploy NLP for real-time agent assistance, constrained by Indic language model availability and GPU inference costs.
- Image Recognition:Convolutional and vision transformer architectures classify defects, radiological findings, and satellite imagery. Automotive assembly lines in Germany and Japan integrate vision systems for quality control, pressured by EU product liability directives and ISO 26262 functional safety requirements.
- Predictive Analytics:Statistical and neural forecasting for demand planning, fraud detection, and maintenance scheduling.
- Robotics:Perception and motion planning algorithms for industrial and service automation.
Predictive Analytics commands premium pricing; Image Recognition gains share fastest.
Deployment:
Cloud deployment concentrates in the United States among enterprises with elastic compute requirements, while Edge adoption accelerates in manufacturing corridors with strict latency constraints. Hybrid configurations expand in European financial services responding to GDPR data localization mandates.
- Cloud:Centralized training clusters and API-accessible inference scale with multi-tenant efficiency. Technology companies in Seattle, San Francisco, and Austin consume cloud AI for product features, exposed to renewable energy intermittency in Texas data center regions.
- Edge:On-device inference at manufacturing lines, autonomous vehicles, and medical instruments. German automotive suppliers deploy edge vision systems for weld inspection, enabled by TSMC advanced packaging cost reductions for low-power accelerators.
- On-Premises:Dedicated infrastructure for classified government workloads and proprietary model training.
- Hybrid:Split architectures training in cloud and inferring locally for sensitive data.
Cloud holds the largest share; Hybrid shows the steepest expansion trajectory.
End User:
Healthcare procurement concentrates in consolidated US hospital systems, while BFSI demand fragments across regulatory jurisdictions with divergent algorithmic accountability requirements. Manufacturing adoption spreads through industrial clusters in Germany, Japan, and South Korea.
- Healthcare:Diagnostic imaging, drug discovery, and clinical decision support systems. Radiology departments at Mass General Brigham and Mayo Clinic negotiate enterprise AI licenses, accelerated by FDA predetermined change control plans for software as medical devices.
- BFSI:Fraud detection, algorithmic trading, and credit underwriting automation. EU-based banks face EU AI Act high-risk system mandates for credit scoring, creating recurring audit and monitoring service procurement.
- Retail:Demand forecasting, recommendation engines, and inventory optimization.
- Manufacturing:Predictive maintenance, quality assurance, and supply chain optimization.
Healthcare holds the largest share; Manufacturing climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced GPU fabrication capacity concentrates in Taiwan and South Korea, while cloud infrastructure deployment and enterprise procurement gravitate toward the United States and select European hubs. This geographic split between silicon supply and algorithmic demand shapes regulatory compliance sequencing and R&D investment patterns across jurisdictions.
United States
Federal R&D budgets and health system consolidation accelerate diagnostic AI procurement at Mass General Brigham and Mayo Clinic. FDA predetermined change control plans for software as medical devices compress clearance timelines for radiology algorithms. Seattle, San Francisco, and Austin technology clusters consume cloud AI for product features, exposed to renewable intermittency in Texas data center regions.
Germany
Automotive assembly lines in Stuttgart and Munich deploy edge vision systems for weld inspection and quality control. EU AI Act high-risk system mandates for credit scoring and recruitment algorithms create recurring audit service procurement. Notified bodies in Berlin and Munich develop sector-specific conformity protocols exceeding baseline harmonized standards.
China
SAMR algorithmic recommendation provisions and dual carbon goals constrain data center expansion in the Yangtze River Delta. Domestic cloud providers scale model training for Mandarin and Cantonese natural language processing. Shenzhen and Hangzhou hardware clusters assemble inference accelerators for smart manufacturing and surveillance applications.
India
Semiconductor PLI scheme design-linked incentives attract fabless startups targeting Indic language model inference acceleration. Contact center operators in Bengaluru and Hyderabad deploy NLP for real-time agent assistance, constrained by GPU inference costs. National data localization requirements channel procurement toward domestic cloud regions.
Japan
METI industrial digitization programs subsidize predictive maintenance deployment at Toyota and Honda manufacturing networks. PMDA guidance on AI-enabled medical devices aligns with FDA timelines for software as medical device clearances. Nagoya and Osaka industrial corridors integrate vision systems for multi-modal defect detection processing spectral, visual, and acoustic signals.
Artificial Intelligence and Machine Learning Market Vendor Landscape
Concentration sits with hyperscale cloud providers and specialized silicon designers that control training infrastructure and API distribution channels. The vendor base stratifies into three tiers: infrastructure owners with captive hardware supply, platform intermediaries bundling MLOps tooling, and vertical specialists targeting regulated end-use cases. Dominant competitive moves include strategic partnerships binding enterprise clients to integrated cloud-AI stacks and capacity reservation agreements securing advanced packaging output from Taiwan-based foundries.
Within the infrastructure-owner tier, Microsoft Corporation and NVIDIA Corporation anchor opposing ends of the value chain—one controlling cloud distribution and enterprise relationships, the other dominating specialized GPU design for training workloads. Google LLC exemplifies vertical integration spanning tensor-processing hardware, foundation model development, and consumer-facing application deployment. IBM Corporation occupies a position serving regulated industries with hybrid deployment architectures that address strict data residency requirements.
| Leading Market Players |
|---|
| Google LLC (Alphabet Inc.) |
| Microsoft Corporation |
| IBM Corporation |
| Amazon Web Services (AWS) |
| NVIDIA Corporation |
| Intel Corporation |
| H2O.ai, Inc. |
| Oracle Corporation |
| SAP SE |
| Others |
Supply Flow & Price Mechanics
The EU AI Act's conformity assessment requirements gate both supplier qualification timelines and price differentiation across high-risk system tiers. This regulatory framework simultaneously extends vendor onboarding cycles and stratifies service premiums based on documentation depth and audit readiness.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for algorithmic systems deployed in credit scoring and recruitment workflows. Three-tier pricing structure across premium, standard, and economy levels separates vendors offering full notified-body documentation from those with self-certified baselines. Price differentiation hinges on certification level and after-sales compliance monitoring intensity. Cost compression in the standard tier is intensifying because open-weight model releases from Meta and Mistral reduce API pricing power. Healthcare systems in Germany and the United States show least price sensitivity due to locked procurement budgets, while contact center operators in India face acute GPU inference cost constraints.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for advanced AI accelerators, with TSMC's advanced packaging capacity feeding NVIDIA's H100 and successor chip supply. The supply chain draws from specialized silicon IP, high-bandwidth memory modules, and substrate materials. Single-source vulnerability concentrates in Taiwan-based foundry output subject to US export control restrictions. Distribution runs through hyperscale cloud providers with captive capacity reservation agreements, bypassing traditional channel intermediaries for enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundation model commoditization constitutes a high-growth disruption accelerated by the EU AI Act's enforcement timeline, which compresses vendor consolidation windows and redirects capital toward compliance-layer specialization.
For Market Incumbents: Compound cloud-AI stack stickiness through capacity reservation agreements with Taiwan-based foundries and embedded compliance tooling for EU AI Act high-risk system mandates. Foundation model substitution from open-weight releases threatens closed API pricing power; vertical integration into proprietary data pipelines and domain-specific fine-tuning infrastructure defends margin position. For New Entrants and Emerging Players: FDA predetermined change control plans for software as medical devices create the fastest certification fast-track for radiology algorithm vendors. Target underpenetrated manufacturing edge deployment in Germany and Japan, where TSMC packaging cost reductions enable vision system unit economics. Lead with MLOps tooling bundles that abstract GPU infrastructure complexity for mid-market manufacturers lacking in-house ML engineering. For Investors and Strategic Acquirers: The EU AI Act's full enforcement reshapes the acquisition landscape toward audit and monitoring service providers with recurring revenue streams. Long-term viability centers on vertical application depth rather than foundation model scale. Target specialist firms with proprietary training data in regulated healthcare and financial services workflows. Watch FDA clearance velocity for software as medical devices as the inflection indicator for hospital procurement budget release.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Layer Investment | EU AI Act mandates create recurring audit revenue streams for high-risk system vendors. |
| Edge AI Silicon Partnership | TSMC advanced packaging cost curves enable German automotive vision deployment at scale. |
| Hospital System Enterprise Licensing | Mass General Brigham and Mayo Clinic consolidation displaces point-solution startups. |
| Indic Language Model Development | India's semiconductor PLI scheme attracts fabless inference acceleration specialists. |
| Neuromorphic-Optical Convergence | Photonic tensor cores from Lightmatter enable sub-picosecond latency for autonomous vehicle fusion. |
Methodological Framework
Desk research of hyperscaler capex disclosures, FDA 510(k) filings, and EU notified-body audit protocols preceded structured interviews with MLOps engineering leads, hospital procurement committee members, and regulatory affairs specialists at medical device manufacturers. Primary fieldwork with cloud infrastructure planners and fabless semiconductor design teams validated secondary findings from SEC filings and foundry capacity announcements. Bottom-up segment sizing triangulated against top-down market aggregation across deployment models and end-use verticals.
Variance decomposition across product type, application, deployment architecture, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included GPU supply concentration indices, FDA software as medical device clearance velocity, and EU AI Act implementation timelines by member state.
Decision-makers should treat outputs as directional under assumptions of sustained Taiwan foundry capacity expansion and stable US-EU regulatory divergence; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in GPU export control policy and notified-body audit standard harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Machine Learning in Pharmaceutical Industry Market
Artificial Intelligence (AI)
Conversation Intelligence Software Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Construction Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Cognitive Services Platform Market
Artificial Intelligence (AI)
Global Legaltech Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Latin America Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence in Trading Market
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Global Computer Assisted Coding Market
Artificial Intelligence (AI)
AI Consulting Services Market
Artificial Intelligence (AI)
Artificial Intelligence Oven Market
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Asia-Pacific Synthetic Data Generation Market