
 North America Non-Dairy Milk Market | 2026-2036
North America Non-Dairy Milk Market Size, Share, and Industry Trends Forecast 2026-2036
North America Non-Dairy Milk Market Insights
Canada is reshaping North American non-dairy milk production capacity through expanded oat processing facilities in Saskatchewan and Manitoba. Califia Farms leverages its Los Angeles manufacturing base to dominate refrigerated plant-based beverage distribution across the United States. Blue Diamond Growers anchors almond milk supply through its cooperative grower network in California's Central Valley. Danone sustains competitive positioning through diversified sourcing across soy, almond, and oat platforms.
Non-dairy milk denotes plant-based liquid beverages formulated from aqueous extraction of oilseeds, cereals, or nuts, typically homogenized and fortified with calcium, vitamin D, and vitamin B12 to approximate dairy nutritional profiles. Industrial production employs enzymatic hydrolysis for starch-based substrates like oat, followed by ultra-high temperature processing or cold aseptic filling to achieve shelf stability without refrigeration. Almond milk retains the largest volume share within product type segmentation, though oat milk commands the fastest growth trajectory driven by foodservice frothability and neutral flavor compatibility. Supermarkets anchor distribution channel value, while online platforms capture the highest growth rate as direct-to-consumer subscription models proliferate among households.
The FDA oversees plant-based dairy alternative labeling standards, while Health Canada governs fortification limits and nutrient content claims under the Food and Drug Regulations. The USDA's National Organic Program shapes premium tier access through certification requirements that constrain ingredient sourcing and processing aids. Stakeholders must monitor evolving protein fortification thresholds and clean-label enforcement patterns as regulators on both sides of the border tighten compositional disclosure requirements.
Market Dynamics
Barista-grade frothability standards are compressing formulation diversity across North American foodservice channels, forcing processors to prioritize enzymatic hydrolysis investments over legacy extraction methods.
Growth Catalysts
- Specialty Coffee Foodservice:Third-wave coffee chains across the United States and Canada now specify oat milk with specific protein and fat thresholds for latte art performance.
- FDA Labeling Modernization:Updated guidance on plant-based dairy alternatives is clarifying compositional standards, reducing regulatory uncertainty for fortified beverage investments.
- Enzymatic Hydrolysis:Advanced starch-processing technology unlocks creamier mouthfeel in oat substrates without added oils or emulsifiers.
Market Restraints
- Almond Water Intensity:California Central Valley aquifer depletion raises input cost volatility for the region's dominant almond milk supply base.
- Single-Geography Oat Concentration:Prairie province processing capacity in Saskatchewan and Manitoba creates weather-dependent supply vulnerability.
- Protein Fortification Ceiling:Current extraction methods limit plant protein bioavailability compared to dairy benchmarks, constraining nutritional parity claims.
Strategic Opportunities
- Direct-to-Consumer Subscriptions:Online platforms bypass supermarket slotting fees while capturing recurring revenue from households in Los Angeles and Bay Area corridors.
- USDA Organic Certification:Premium tier access opens through constrained ingredient sourcing that competitors with conventional supply chains cannot easily replicate.
- Precision Fermentation Convergence:Integration with microbial protein production promises dairy-identical functional properties without agricultural land use.
Industry Challenges
- Clean-Label Enforcement:FDA disclosure requirements for processing aids and fortification carriers demand reformulation timelines that strain R&D bandwidth.
- Cold-Chain Capex:Refrigerated distribution infrastructure requires capital deployment that shelf-stable processors avoided historically.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Non-Dairy Milk Market |
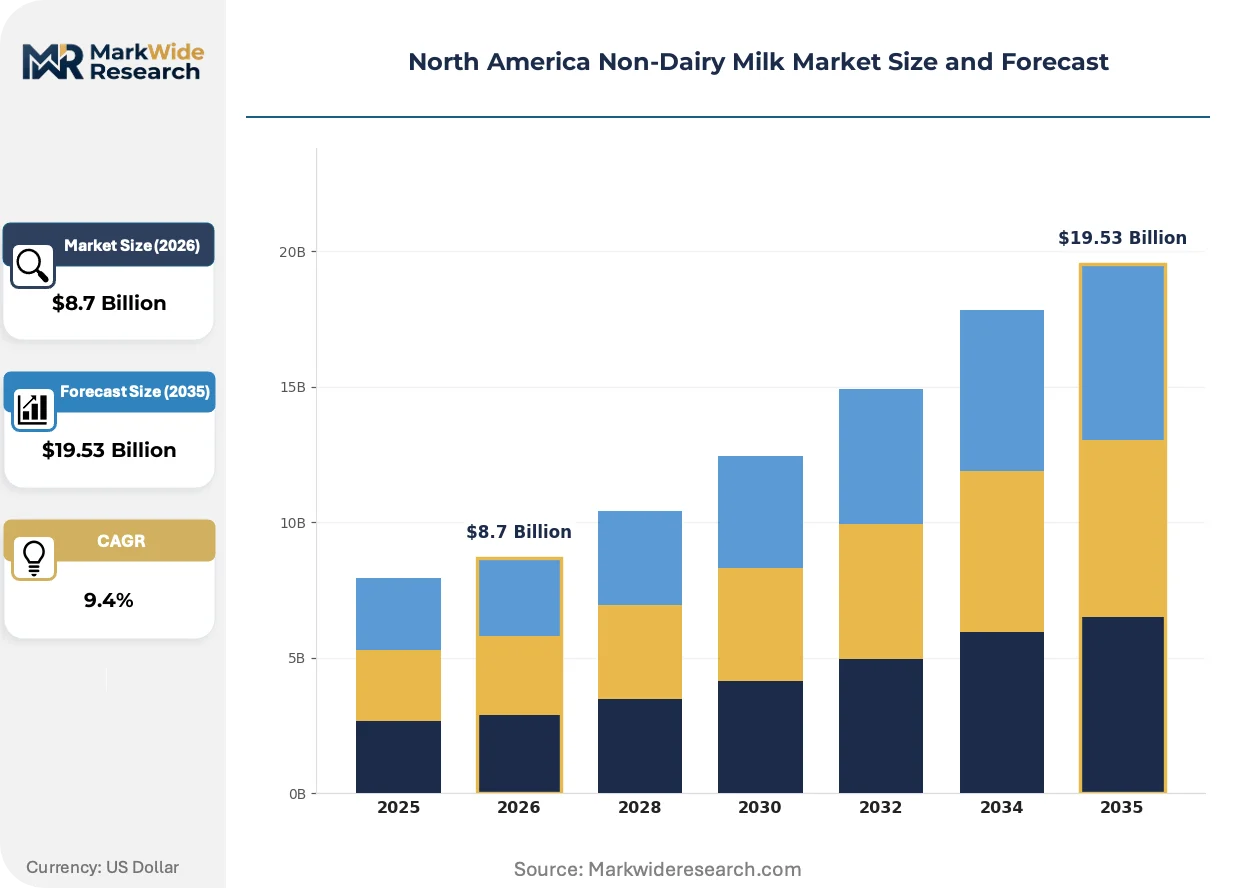
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Packaging Type: Tetra Packs, Glass Bottles, Plastic Bottles, Cartons End User: Households, Cafés, Restaurants, Food Manufacturers Distribution Channel: Online, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Silk, The Hain Celestial Group, Blue Diamond Growers, Good Karma Foods, Ripple Foods, Califia Farms, Danone, SunOpta, Oatly Group AB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Non-Dairy Milk Market Trends and Innovations
Formulation science and distribution infrastructure are converging to redefine competitive advantage in plant-based beverages. Three developments warrant particular attention.
Enzymatic hydrolysis technology is digitizing quality control across oat milk production lines. Mid-sized processors in Manitoba and California deploy real-time viscosity monitoring to standardize barista-grade performance batch-to-batch. This precision is compressing the gap between artisanal and industrial output consistency.
Health Canada's updated Food and Drug Regulations on nutrient content claims are tightening fortification disclosure thresholds. Manufacturers must now document vitamin D and calcium source origins with greater granularity. The regulatory friction falls heaviest on imported ingredient blends, advantaging domestic sourcing networks.
Foodservice procurement is consolidating around specification-driven contracts rather than brand loyalty. Major coffee chains now issue technical requirements for foam stability and neutral flavor compatibility that multiple suppliers can bid against. This shift is most visible in Los Angeles and Toronto metro corridors where plant-forward density supports supplier switching.
North America Non-Dairy Milk Market Segmentation
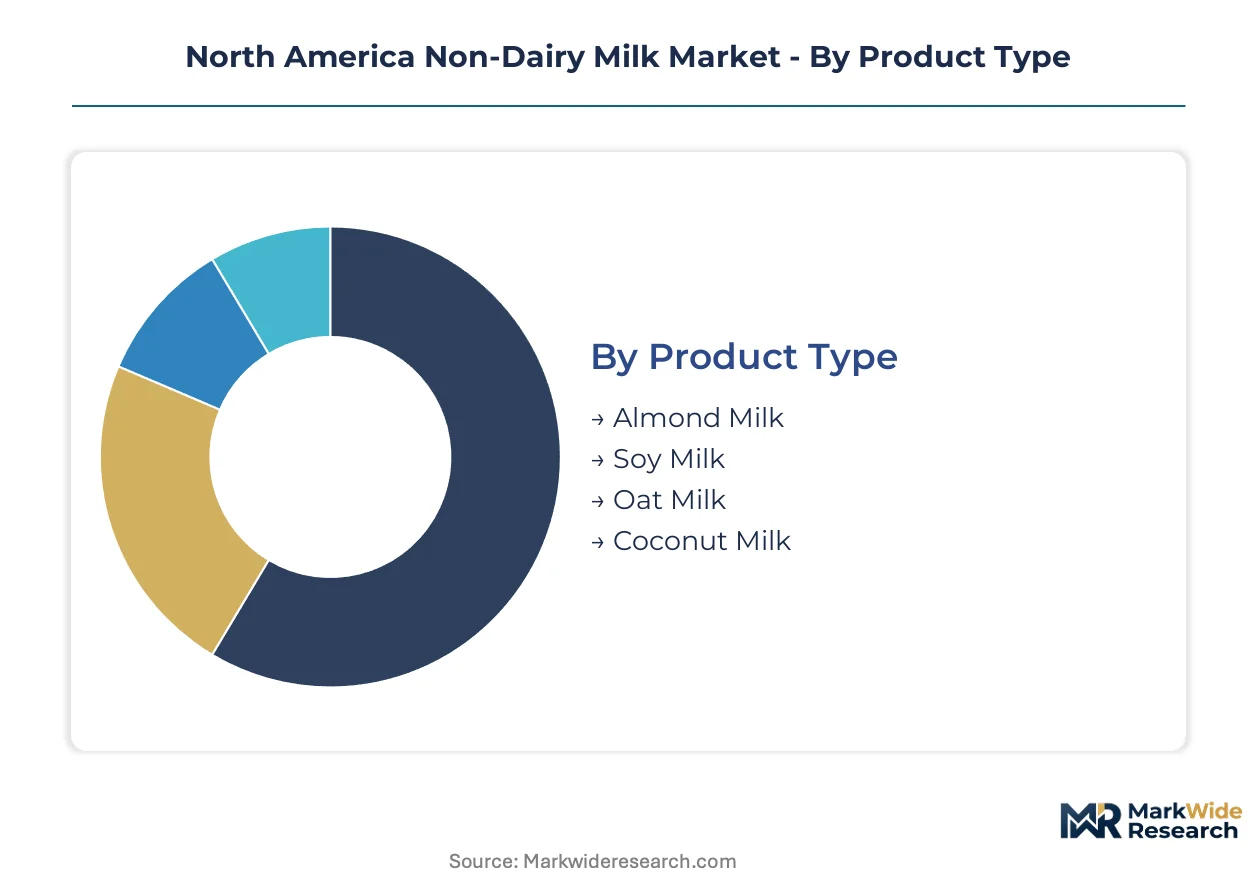
Segmentation in North American non-dairy milk reveals how formulation specifications, packaging durability requirements, and channel economics create distinct competitive arenas. Each dimension carries divergent margin profiles and regulatory exposure that reshape processor investment priorities.
Product Type:
Use-case spectrum spans nutritional fortification for direct consumption through industrial ingredient applications demanding functional performance.
- Almond Milk:Derived from California Central Valley almond processing, this segment carries the highest volume throughput in retail channels. Water intensity constraints in the Central Valley aquifer system create input cost volatility that processors hedge through long-term grower contracts.
- Oat Milk:Enzymatic hydrolysis of Prairie province oats yields superior barista-grade frothability that third-wave coffee chains now specify in procurement contracts. Saskatchewan and Manitoba processing capacity expansion is concentrating supply geography in weather-dependent regions.
- Soy Milk:Established fortification infrastructure and mature protein extraction economics sustain this segment's presence in conventional retail.
- Coconut Milk:Tropical sourcing requirements and lipid separation challenges limit this segment to ethnic foodservice and specialty baking applications.
Almond milk commands the dominant volume position, while oat milk is expanding most quickly through foodservice specification capture.
Packaging Type:
Cost tier differentiation separates premium positioning through material aesthetics from economy access via commodity formats.
- Tetra Packs:Aseptic carton technology enables shelf-stable distribution without refrigerated logistics, opening rural and institutional channels. California and Ontario processors leverage this format for export-adjacent production lines serving cross-border retail.
- Plastic Bottles:Lightweight PET and HDPE formats dominate refrigerated case placement in United States supermarkets. Cold-chain infrastructure requirements concentrate this format's economics around major metropolitan distribution hubs.
- Glass Bottles:Premium tier access through material recyclability and perceived purity, constrained by weight-driven freight economics.
- Cartons:Gable-top refrigerated cartons occupy mid-tier positioning with established filling equipment amortization across legacy dairy processing facilities.
Tetra packs retain the broadest geographic reach, though plastic bottles are gaining refrigerated channel penetration fastest.
End User:
Application maturity separates established household consumption from emerging foodservice specification markets.
- Households:Direct-to-consumer subscription models and supermarket procurement dominate this mature segment with price-sensitive volume.
- Cafés:Specialty coffee chains across Los Angeles, San Francisco, Toronto, and Vancouver now issue technical specifications for foam stability and neutral flavor compatibility. Barista-grade performance requirements are compressing supplier diversity to processors with enzymatic hydrolysis capabilities.
- Restaurants:Plant-forward menu density in Bay Area and Los Angeles corridors drives procurement consolidation around multi-location supply agreements.
- Food Manufacturers:Industrial ingredient applications in dairy-free frozen desserts and baked goods demand consistent viscosity and protein content for formulation stability.
Household consumption holds the largest absolute volume, yet cafés are climbing the fastest as specification-driven procurement reshapes competitive access.
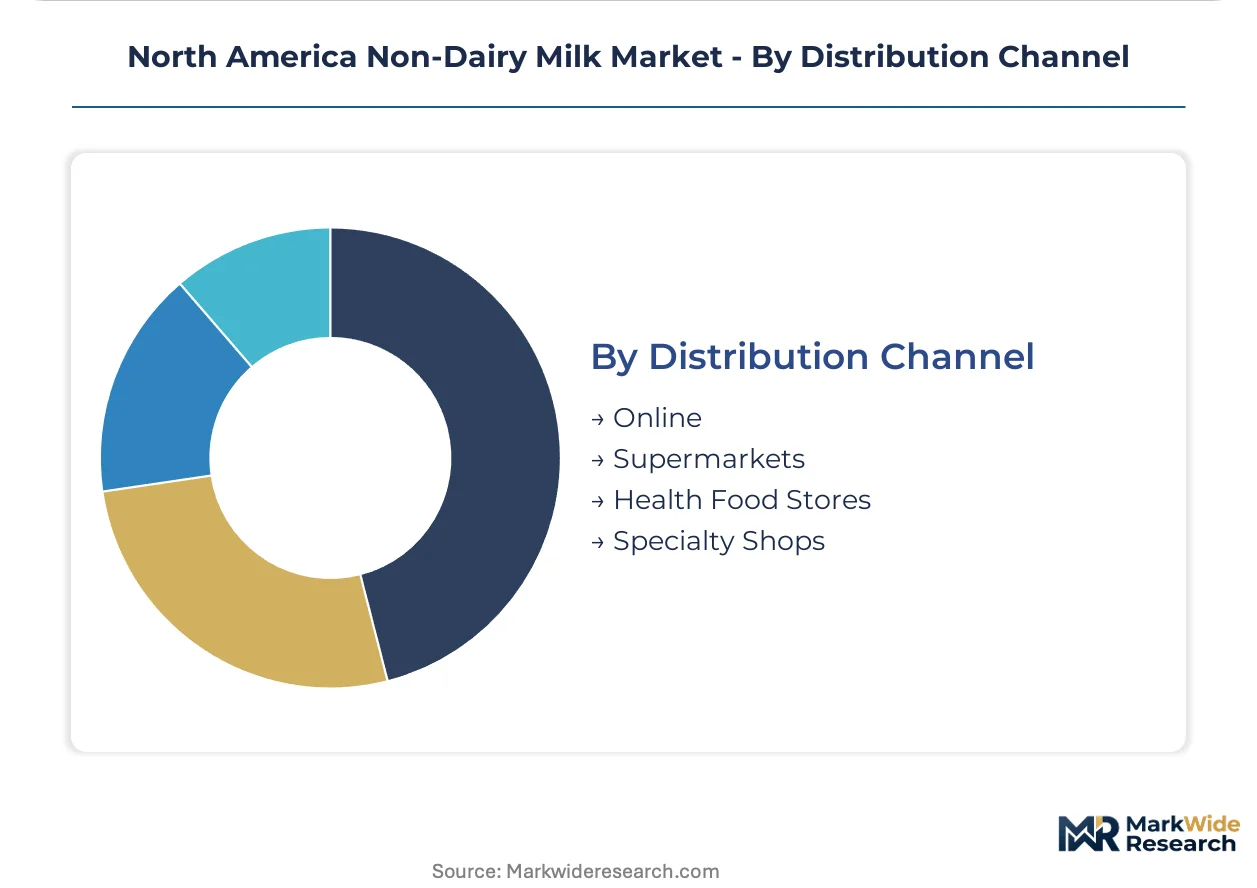
Distribution Channel:
Customer type fragmentation separates recurring subscription revenue from transactional retail economics.
- Supermarkets:Slotting fee structures and planogram placement competition concentrate this channel around processors with national refrigerated distribution networks. United States conventional retail and Canadian grocery banners anchor volume throughput.
- Online:Direct-to-consumer subscription platforms bypass retail margin stacking while capturing recurring revenue from households in California's Bay Area and Los Angeles corridors. Health Canada's fortification disclosure requirements create regulatory friction for cross-border e-commerce shipments.
- Health Food Stores:USDA Organic certification and clean-label positioning command premium pricing in this channel with educated consumer bases.
- Specialty Shops:Ethnic grocers and independent retailers serve niche coconut and heritage soy milk demand with limited geographic concentration.
Supermarkets retain the dominant transaction volume, while online platforms are gaining share fastest through subscription model proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles and Long Beach container complex anchors North American non-dairy milk trade flows, handling refrigerated plant-based beverage imports and California-processed export volumes. Cross-border rail links through the Detroit-Windsor corridor and Vancouver-Seattle corridor integrate Canadian oat processing with United States distribution networks.
United States
California's Central Valley almond cooperatives supply the dominant raw material base for retail almond milk, while Los Angeles and Bay Area metro corridors concentrate foodservice procurement density. FDA labeling modernization for plant-based dairy alternatives is tightening compositional disclosure requirements for protein and calcium fortification. Califia Farms leverages its Los Angeles manufacturing base to dominate refrigerated distribution across West Coast and national retail channels.
Canada
Prairie province oat processing expansion in Saskatchewan and Manitoba is reshaping North American production capacity for barista-grade applications. Health Canada's Food and Drug Regulations govern fortification limits and nutrient content claims with stricter disclosure thresholds than south of the border. Toronto and Vancouver metro areas anchor foodservice specification adoption where third-wave coffee chains issue technical requirements for foam stability.
Mexico
Central Mexico's emerging food processing corridor is attracting contract manufacturing investment for shelf-stable Tetra Pack formats serving Latin American export markets. Mexico's national health regulator COFEPRIS oversees labeling standards for plant-based beverages with evolving fortification guidelines. Guadalajara and Monterrey industrial zones are developing aseptic filling capacity to serve United States private-label demand.
North America Non-Dairy Milk Market Competitive Landscape
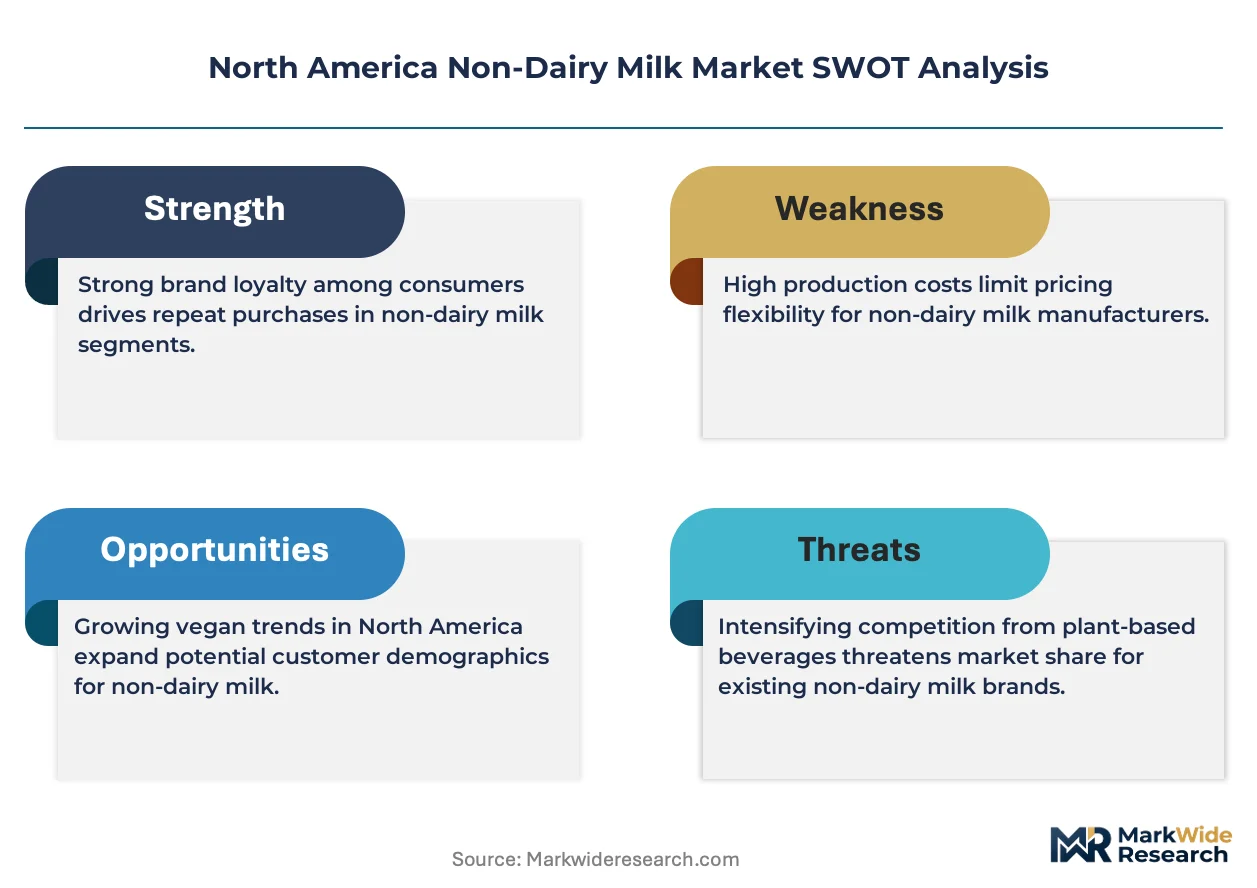
Platform integrators command the system tier; component specialists sit upstream in raw material and processing technology supply. The North American non-dairy milk market structures around diversified beverage conglomerates, cooperative agricultural networks, and focused plant-based specialists. Three archetypes dominate: legacy dairy diversifiers with refrigerated distribution infrastructure, agricultural cooperatives with captive ingredient supply, and venture-backed oat specialists with foodservice specification expertise. Competitive moves concentrate on enzymatic hydrolysis capacity expansion and direct-to-consumer subscription platform development.
Among United States-based specialists, Califia Farms and Ripple Foods exemplify distinct platform strategies—one anchored in West Coast refrigerated logistics, the other in novel protein extraction from legume substrates. Danone represents the diversified conglomerate archetype with multi-platform sourcing across soy, almond, and oat categories. Oatly Group AB occupies a position as the reference standard for barista-grade performance specifications that competitors benchmark against.
| Leading Market Players |
|---|
| Silk |
| The Hain Celestial Group |
| Blue Diamond Growers |
| Good Karma Foods |
| Ripple Foods |
| Califia Farms |
| Danone |
| SunOpta |
| Oatly Group AB |
| Others |
Pricing and Supply Chain Analysis
California Central Valley aquifer depletion risk determines both tiered pricing spreads across almond milk grades and the geographic reconfiguration of oat sourcing toward Prairie province processing. Buyers facing water-input volatility hedge through long-term grower contracts that compress margin elasticity for processors without diversified raw material bases.
Pricing Analysis
Volume-discount tiering structures separate USDA Organic certified premiums from conventional shelf-stable economy positioning. Price differentiation rests on enzymatic hydrolysis capability for barista-grade specifications and cold-chain logistics access for refrigerated placement. Pricing pressure stems from supermarket slotting fee escalation that squeezes mid-tier processors without direct-to-consumer subscription offsets. Household segments exhibit highest price sensitivity, while third-wave coffee chains prioritize performance specifications over per-unit cost.
Supply Chain Analysis
Export-control regime constraints on enzymatic processing equipment limit technology transfer to domestic oat hydrolysis capacity expansion. Geographic supply concentration centers on California almond cooperatives, Saskatchewan and Manitoba oat processing, and tropical coconut lipid sourcing. Raw material dependencies include Central Valley almond harvests, Prairie province grain flows, and calcium carbonate fortification inputs. Single-geography oat concentration creates weather-dependent supply vulnerability. Distribution runs through Port of Los Angeles container handling for cross-border retail integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through specification-driven procurement consolidation among specialty coffee chains, fragmenting supplier pricing leverage across North American foodservice channels.
For Market Incumbents: Insulate margin position through backward integration into Prairie province oat processing capacity and captive almond grower contract renewal ahead of water-input cost spikes. Priority lever: enzymatic hydrolysis R&D bandwidth expansion to meet FDA clean-label disclosure timelines without formulation disruption. For New Entrants and Emerging Players: Build out direct-to-consumer subscription platforms targeting Los Angeles and Bay Area corridor households with refrigerated delivery logistics partnerships. White-space target: precision fermentation-derived dairy-identical proteins for nutritional parity claims beyond current plant protein bioavailability ceilings. For Investors and Strategic Acquirers: The market sits at a specification-lock-in phase that favors processors with enzymatic hydrolysis capabilities and USDA Organic certification infrastructure. Long-term viability favors acquisition targets with foodservice contract concentration and refrigerated distribution network density. Signal to watch: Health Canada fortification disclosure enforcement patterns as indicator of regulatory compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Capacity Expansion | Unlocks barista-grade oat milk specifications that third-wave coffee chains now mandate in procurement contracts. |
| Direct-to-Consumer Subscription Platform | Bypasses supermarket slotting fees while capturing recurring revenue from plant-forward households in California corridors. |
| USDA Organic Certification Investment | Opens premium tier access through constrained ingredient sourcing that conventional supply chains cannot replicate. |
| Prairie Province Processing Footprint | Secures oat supply proximity to Saskatchewan and Manitoba grain production amid weather-dependent harvest volatility. |
| Precision Fermentation Partnership | Integrates microbial protein production promising dairy-identical functional properties without agricultural land use constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across plant-based beverage manufacturing, specialty coffee procurement, and retail category management functions. Primary interviews with enzymatic processing engineers, foodservice specification directors, and supermarket category buyers were cross-referenced against FDA labeling guidance documents, Health Canada Food and Drug Regulations, USDA National Organic Program standards, and trade flow data through Port of Los Angeles customs records. Bottom-up volume modeling from processor capacity utilization triangulated with top-down category expenditure estimates.
Calibration against historical pricing volatility in California almond inputs and Prairie province oat harvests anchored projection assumptions across the analysis window. Segmentation dimensions modeled include product type, packaging durability requirements, end-use application, and distribution channel economics. CAGRs were derived from growth driver elasticity coefficients applied to baseline penetration rates. Industry-specific forecast inputs incorporated barista-grade specification adoption curves and refrigerated logistics infrastructure deployment timelines.
Practitioners should monitor FDA protein fortification threshold revisions and Health Canada nutrient content claim enforcement patterns for early signals of regulatory compliance cost shifts. Forecasts reflect assumptions regarding specialty coffee chain procurement consolidation and enzymatic hydrolysis technology diffusion. Material shifts in California Central Valley water availability or Prairie province processing capacity expansion delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Coconut Milk Products Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Reduced Fat Coconut Milk Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Europe Non-Dairy Yogurt Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Low-Calorie Coconut Milk Market