
 Macadamia Market | 2026-2036
Macadamia Market Size, Share, and Industry Trends Forecast 2026-2036
Macadamia Market Intelligence
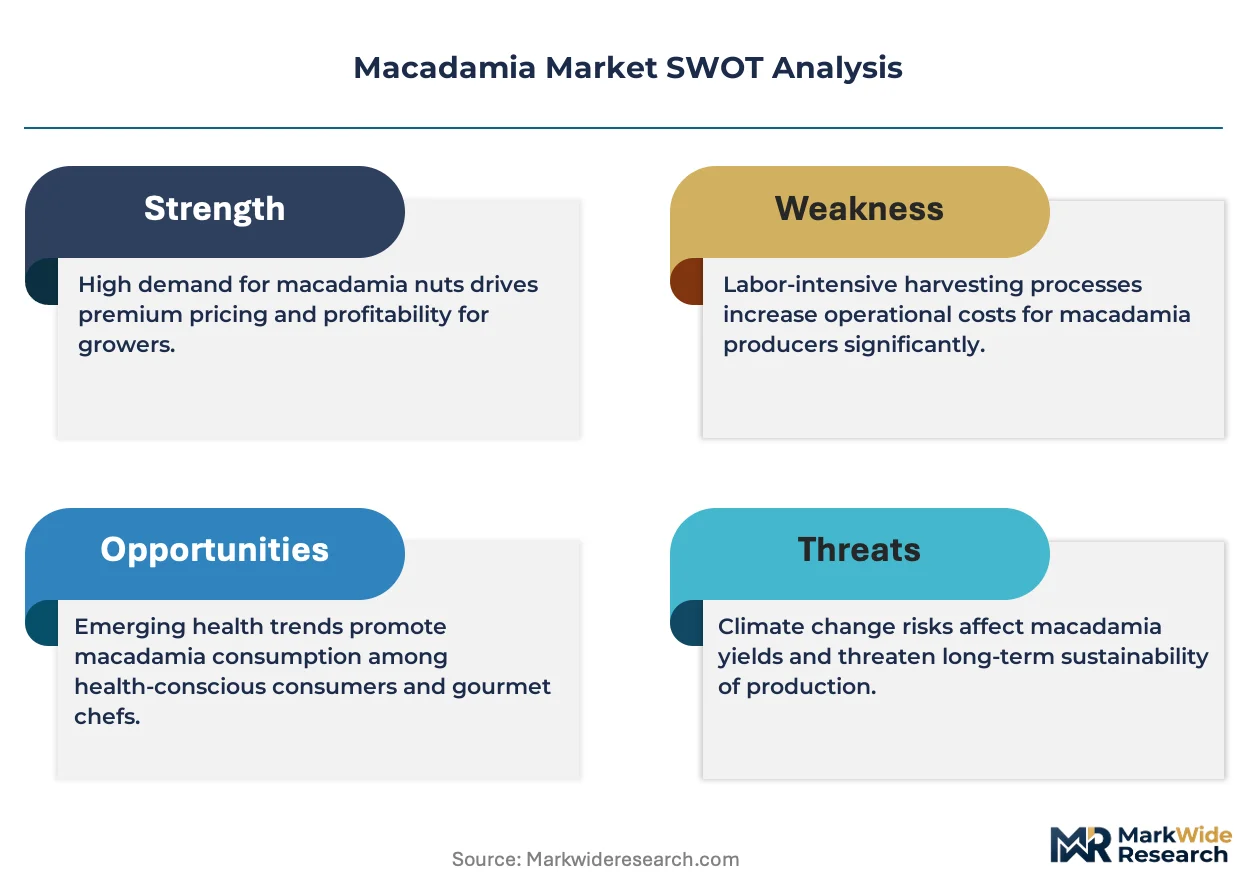
Multi-source procurement toward vertically integrated estate operations is recalibrating how processors secure kernel supply. Hawaiian Host Group leverages captive orchards in Hawaii to control raw nut quality from flowering through cracking. MacFarms LLC anchors its position through scale dominance across thousands of hectares in South Africa's Lowveld region. Marquis Macadamias differentiates via advanced sorting and pasteurization technology at its Queensland facilities.
Macadamia denotes the edible kernel of Macadamia integrifolia and Macadamia tetraphylla, typically containing 72-76% oil by weight and valued for its creamy texture, high monounsaturated fat profile, and 1.5% sugar content that resists caramelization during roasting. Kernel grades span style zero through style eight, with whole kernels commanding premium placement in gift assortments and confectionery applications. Raw nuts sustain the largest volume share across product types, though macadamia oil captures disproportionate margin in cosmetic and nutraceutical channels. Snacks and the food industry represent the twin demand poles within application segmentation, with bakery ingredient demand rising fastest among food manufacturers.
Australia's Department of Agriculture enforces strict biosecurity screening for imported propagation material under the Biosecurity Act, while South Africa's Department of Agriculture, Land Reform and Rural Development regulates phytosanitary certification for export consignments. The USDA's Agricultural Marketing Service administers grade standards for inshell and shelled macadamias entering the United States, directly shaping lot acceptance criteria at port. Stakeholders must monitor pollination labor costs and alternate-bearing cycle intensity when committing orchard expansion capital.
Market Dynamics
Processor consolidation around captive orchard supply is compressing spot-market liquidity for kernel procurement. Hawaiian Host Group's backward integration into Hawaii-based flowering-to-cracking control and Marquis Macadamias' pasteurization technology investments exemplify how quality assurance is becoming a capital-intensive barrier to mid-tier entrants.
Growth Catalysts
- Biosecurity-driven supply discipline:Australia's Biosecurity Act screening protocols for imported propagation material artificially constrain new orchard establishment. Mature tree stock in Queensland's Bundaberg corridor retains pricing power.
- Confectionery formulation demand:Whole kernel grades (style zero through style three) command placement in premium gift assortments. Bakery ingredient applications are expanding fastest among food manufacturers seeking clean-label fat sources.
- Cosmetic channel margin capture:Macadamia oil's 72-76% lipid concentration and high monounsaturated profile supports nutraceutical and dermal applications. Extraction facilities co-located with cracking plants reduce oxidation risk.
Market Restraints
- Alternate-bearing cycle intensity:Macadamia integrifolia exhibits biennial production swings of 30-40% between on-years and off-years. Revenue predictability suffers for non-vertically integrated processors.
- Pollination labor cost escalation:Commercial bee colony rental rates for orchard flowering periods have risen sharply in South Africa's Lowveld and Australia's Gympie corridor. Hand-pollination fallback is uneconomical at scale.
- Phytosanitary certification friction:South Africa's Department of Agriculture, Land Reform and Rural Development export documentation requirements create lot-release delays. Container detention costs accumulate at port.
Strategic Opportunities
- Underpenetrated Chinese retail:In-shell gifting traditions align with macadamia's premium positioning. Direct-to-consumer platforms bypass traditional nut-import wholesale layers.
- Regulatory tailwind from FDA nutrition labeling:The monounsaturated fat emphasis in USDA dietary guidance supports health-claim formulation. Snack manufacturers substitute macadamia for hydrogenated oils.
- Roasting technology convergence:Infrared dry-roasting combined with nitrogen-flush packaging extends shelf life without preservative addition. Equipment suppliers in Germany are deploying turnkey lines.
Industry Challenges
- Kernel grading technician scarcity:Style classification (zero through eight) requires visual discernment of chip, shrivel, and discoloration thresholds. Training pipelines lag processor expansion timelines.
- Pasteurization validation documentation:USDA Agricultural Marketing Service grade standards for shelled macadamias require lot-specific pathogen reduction certificates. Third-party audit backlogs extend commercialization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macadamia Market |
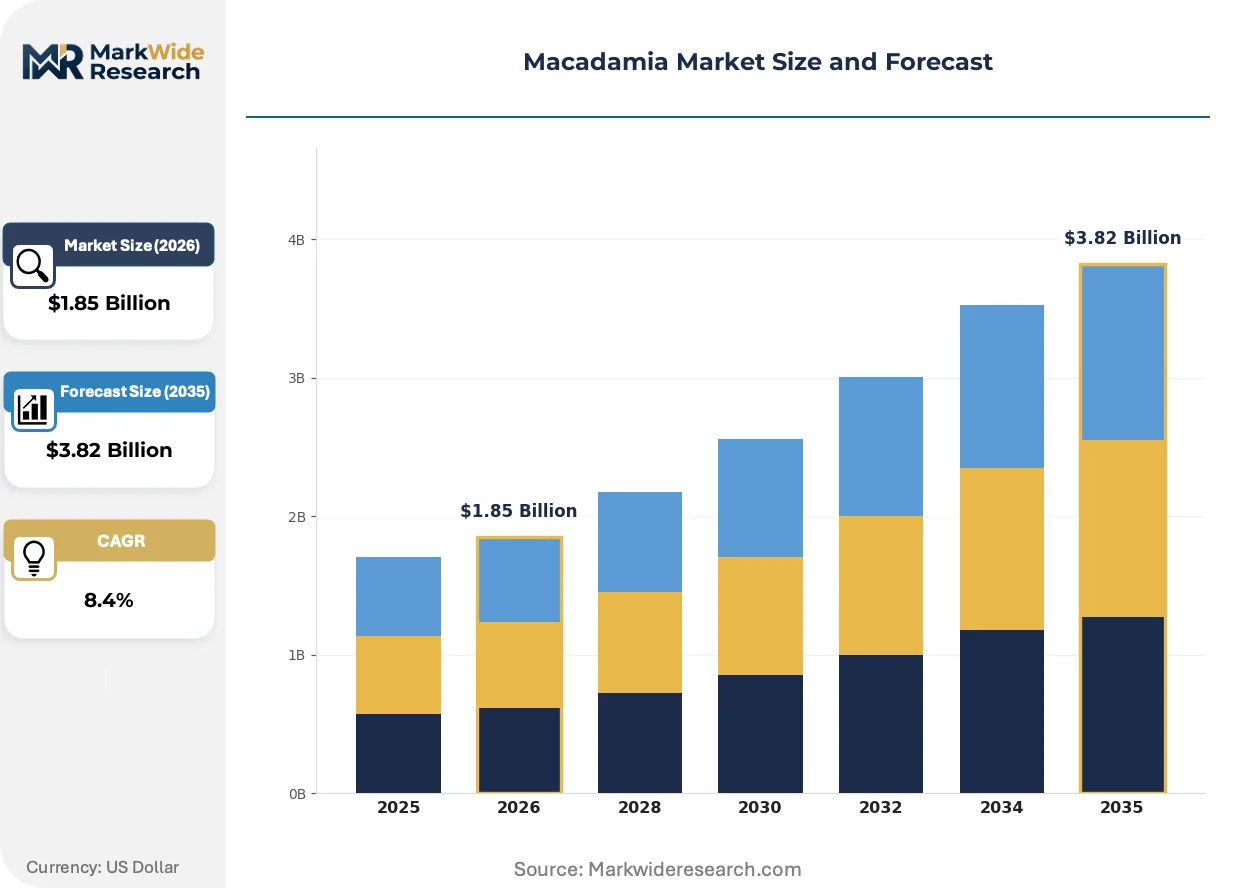
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Nuts, Roasted Nuts, Oil, Flour Application: Food Industry, Cosmetic Products, Nutraceuticals, Snacks Distribution Channel: Online Retail, Grocery Stores, Specialty Shops, Wholesalers End User: Consumers, Food Manufacturers, Bakeries, Restaurants |
| Companies Covered | Hawaiian Host Group, MacFarms LLC, Mauna Loa Macadamia Nut Corporation, Hamakua Macadamia Nut Company, Golden Macadamias, Marquis Macadamias, Buderim Group Limited, Alimentos Selectos S.A., Kenya Nut Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macadamia Market Strategic Shifts & Innovations
Processing automation and regulatory disclosure requirements are simultaneously elevating capital barriers and rewarding scale-advantaged operators. Technology deployment now separates contract manufacturers from integrated estate competitors.
Hyperspectral sorting systems is electrifying kernel classification accuracy. Marquis Macadamias and South African processors are retrofitting Queensland and Lowveld facilities with NIR-based defect detection. The technology compresses manual labor requirements while tightening style-zero yield recovery rates for whole-kernel gift channels.
REACH chemical registration thresholds in Europe are tightening extraction solvent specifications for cosmetic-grade oil. German and French refiners are migrating from hexane to supercritical CO2 processes. The shift elevates capex intensity but secures EU cosmetic ingredient dossier approvals.
Ingredient buyers in snack and confectionery verticals are consolidating supplier panels around vertically integrated estates with documented pollination and harvesting protocols. Direct contracting with Hawaiian Host Group or MacFarms LLC replaces spot kernel purchases. The pattern concentrates procurement leverage with processors controlling flowering-to-bag traceability.
Macadamia Market Segmentation
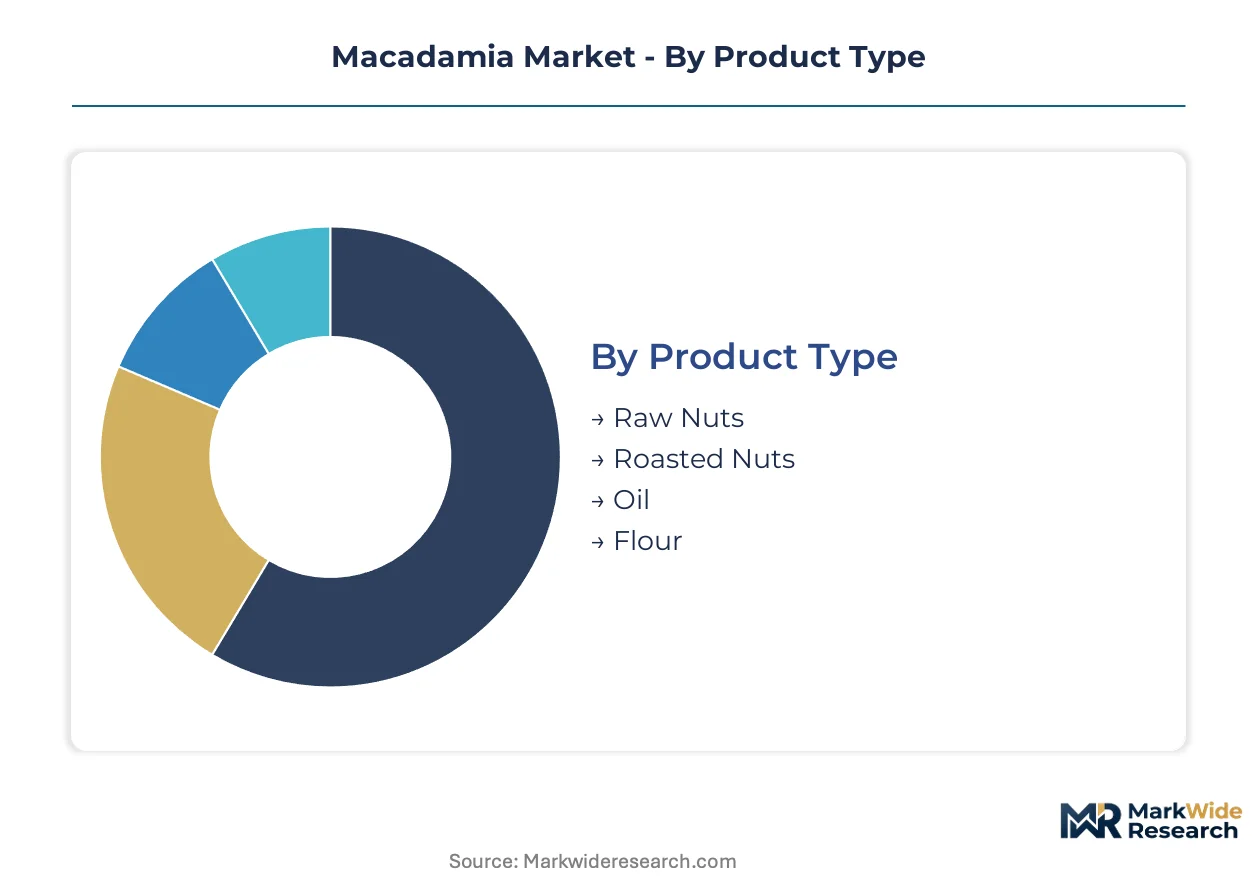
Kernel form and processing intensity determine margin capture across macadamia value chains. Product type splits reveal where volume commoditization ends and premium extraction begins. Application channels expose which end-users absorb price volatility and which lock in long-term contracting.
Product Type:
Volume concentrates in minimally processed formats. Premium extraction depends on downstream processing depth and lipid recovery efficiency.
- Raw Nuts:Inshell and shelled kernel in natural state retains the largest shipment volumes across export markets. Queensland's Bundaberg processors and South Africa's Lowveld operators move raw nuts through spot markets and annual contracts to Asian shelling facilities.
- Oil:Cold-pressed and solvent-extracted lipid fractions containing 72-76% monounsaturated fat by weight command disproportionate margin in dermal and nutraceutical channels. German refiners deploying supercritical CO2 extraction under REACH compliance secure EU cosmetic ingredient dossiers.
- Roasted Nuts:Dry-roasted kernel with nitrogen-flush packaging extends shelf life for snack manufacturers substituting macadamia for hydrogenated oils.
- Flour:Defatted meal from oil extraction provides gluten-free bakery input with clean-label positioning.
Mature deployment sits with Raw Nuts. Newer deployment is concentrated in Oil extraction facilities co-located with cracking plants.
Application:
Demand bifurcates between formulation input and finished goods consumption. Food manufacturers absorb volume; cosmetic and nutraceutical channels absorb price premiums.
- Snacks:Whole kernel grades style zero through style three dominate premium gift assortments and direct retail. Hawaiian Host Group's captive orchards supply confectionery manufacturers with documented flowering-to-bag traceability.
- Food Industry:Bakery ingredient demand is expanding most quickly among manufacturers seeking clean-label fat sources. Kernel chips and style four through six grades integrate into cookie, pastry, and chocolate formulations.
- Cosmetic Products:Macadamia oil's fatty acid profile supports dermal absorption formulations. French and German refiners prioritize cosmetic-grade extraction for skincare lines.
- Nutraceuticals:High monounsaturated concentration supports dietary supplement positioning under FDA nutrition labeling guidance.
Contracting intensity runs deepest through Food Industry procurement panels. Spot market liquidity persists in Nutraceuticals.
Distribution Channel:
Channel selection determines price realization and working capital requirements. Direct-to-consumer platforms bypass traditional wholesale margin stacking.
- Online Retail:E-commerce platforms enable in-shell gifting penetration into underdeveloped Chinese retail markets. Direct-to-consumer sales bypass import wholesale layers.
- Grocery Stores:Mass retail placement for roasted snack formats requires scale-advantaged processors with pasteurization validation documentation.
- Specialty Shops:Gourmet retailers in Germany and the United States source value-added products with style-zero whole kernel presentation.
- Wholesalers:Traditional nut-import channels aggregate raw kernel from Australian and South African origins for redistribution to shelling and roasting facilities.
Margin capture concentrates in Online Retail. Volume throughput remains anchored in Wholesalers.
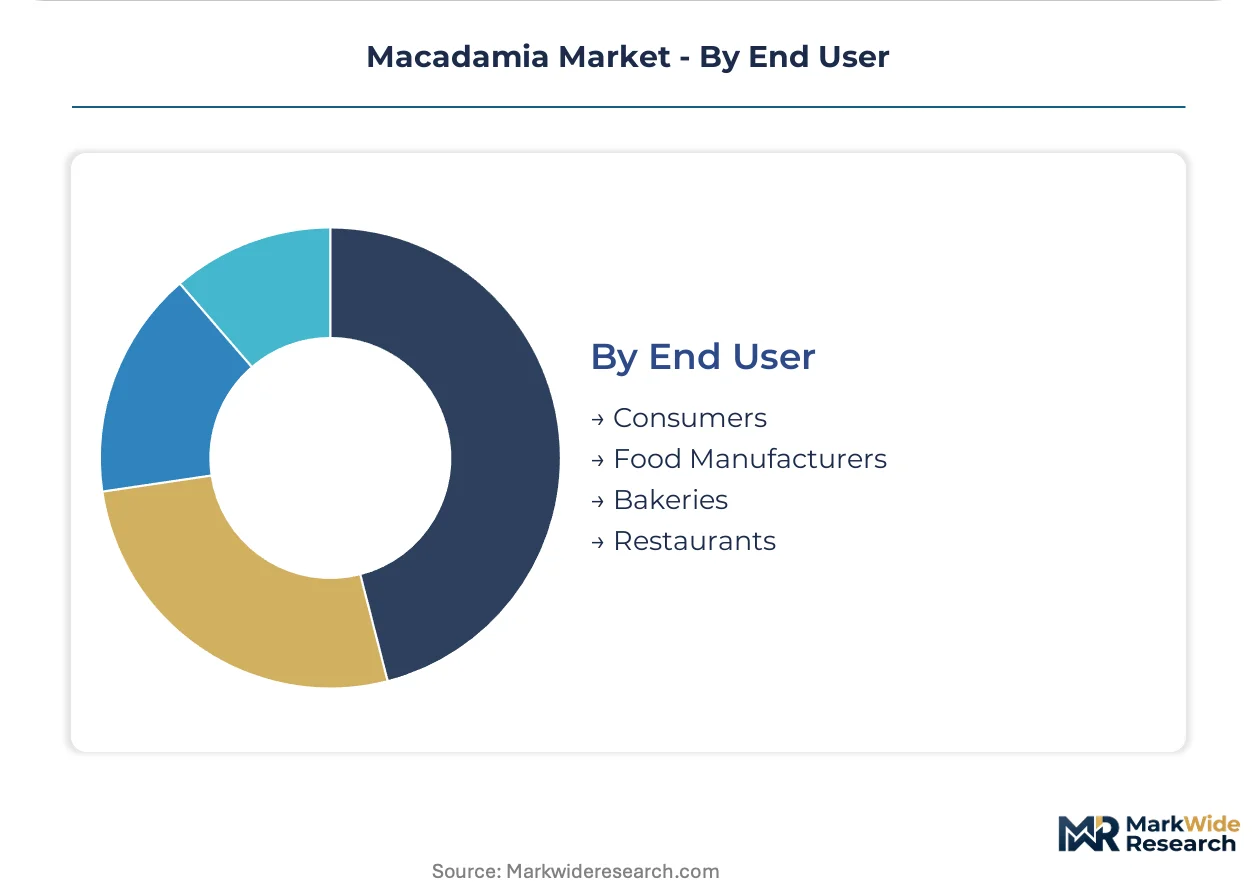
End User:
User type dictates specification stringency and certification burden. Industrial buyers impose traceability requirements; consumer-facing channels prioritize sensory attributes.
- Food Manufacturers:Industrial formulators consolidate supplier panels around vertically integrated estates with documented pollination and harvesting protocols. USDA Agricultural Marketing Service grade standards directly shape lot acceptance criteria.
- Bakeries:Clean-label ingredient demand drives defatted flour and chipped kernel procurement for gluten-free formulations.
- Consumers:Direct purchasers prioritize whole kernel aesthetics and roasting quality for gifting and home consumption.
- Restaurants:Foodservice channels absorb style five through eight grades for ingredient applications where visual presentation matters less.
Specification discipline is tightest among Food Manufacturers. Price elasticity is highest with Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland's Bundaberg and Gympie corridors anchor mature macadamia production with overlapping processing infrastructure and established tree stock. Australia's biosecurity protocols constrain new orchard establishment timelines across all import-dependent growing regions.
Australia
Gourmet snack manufacturers source value-added products from Queensland processors. The Biosecurity Act enforces strict screening protocols for imported propagation material. Bundaberg and Gympie growing corridors concentrate mature tree stock and cracking facilities.
United States
Confectionery formulators demand whole kernel grades for premium gift assortments. The USDA Agricultural Marketing Service administers grade standards for inshell and shelled macadamias entering port. Hawaiian orchards supply documented flowering-to-bag traceability for industrial buyers.
South Africa
Scale-dominant estate operations anchor kernel supply through the Lowveld region. The Department of Agriculture, Land Reform and Rural Development regulates phytosanitary certification for export consignments. Pollination labor costs escalate during commercial bee colony rental periods.
Germany
Gourmet retailers expand procurement of roasted snack formats and cosmetic-grade oil extracts. REACH chemical registration thresholds tighten extraction solvent specifications for European cosmetic ingredient approvals. German refiners deploy supercritical CO2 processing lines.
China
In-shell gifting traditions align with macadamia's premium positioning in underpenetrated retail channels. Direct-to-consumer e-commerce platforms bypass traditional nut-import wholesale layers. Processing facilities in coastal provinces handle raw kernel redistribution.
Macadamia Market Key Industry Players
Global majors compete with regional champions across estate scale and processing technology deployment. The vendor base clusters around vertically integrated orchard operators and specialized cracking facilities. Three archetypes dominate: captive estate controllers with backward integration into flowering-to-cracking operations, scale-driven processors leveraging thousand-hectare land positions, and technology-differentiated operators investing in hyperspectral sorting and pasteurization. Competitive moves concentrate on M&A for orchard consolidation and capacity expansion through co-located oil extraction facilities.
Among estate-integrated operators, Hawaiian Host Group exemplifies the captive orchard archetype with Hawaii-based production control. MacFarms LLC occupies a position within the scale-driven tier, leveraging extensive Lowveld landholdings. Marquis Macadamias represents the technology-differentiated vector through advanced Queensland processing infrastructure. These three anchors illustrate how quality assurance and supply security are becoming capital-intensive barriers to mid-tier market entry.
| Leading Market Players |
|---|
| Hawaiian Host Group |
| MacFarms LLC |
| Mauna Loa Macadamia Nut Corporation |
| Hamakua Macadamia Nut Company |
| Golden Macadamias |
| Marquis Macadamias |
| Buderim Group Limited |
| Alimentos Selectos S.A. |
| Kenya Nut Company |
| Others |
Cost & Logistics Intelligence
Pollination labor costs trace a direct path from South Africa's Lowveld commercial bee colony rental rates through to premium kernel grade pricing tiers in European and North American gift channels. Australian biosecurity screening under the Biosecurity Act compounds propagation material scarcity, concentrating mature tree stock pricing power in Queensland's Bundaberg corridor and compressing margins for non-integrated processors.
Pricing Analysis
Service-bundling separates pasteurization validation and phytosanitary certification documentation from raw kernel spot transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by kernel style grade and USDA Agricultural Marketing Service lot acceptance criteria. Pricing pressure stems from alternate-bearing cycle revenue unpredictability forcing processors to absorb inventory risk. Food manufacturers exhibit lowest price sensitivity due to traceability requirements, while restaurants absorb highest elasticity through style five through eight grade substitution.
Supply Chain Analysis
USDA Agricultural Marketing Service grade standards and South Africa's Department of Agriculture phytosanitary certification requirements gate lot release at port. Supply concentrates in Australia, South Africa, and Kenya as origin points, with cracking facilities drawing from mature orchard stock in Queensland's Bundaberg-Gympie corridor and the Lowveld region. Raw nut inputs, commercial bee pollination services, and nitrogen-flush packaging materials anchor upstream dependencies. Single-source vulnerability concentrates in Queensland's processing infrastructure cluster. Distribution runs through wholesaler aggregation for Asian shelling facilities and direct-to-consumer platforms for Chinese in-shell gifting penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where Australia's Biosecurity Act and USDA Agricultural Marketing Service grade standards erect capital-intensive barriers that reward documented traceability investments by incumbent estate operators.
For Market Incumbents: Deepen hyperspectral sorting technology deployment across Queensland and Lowveld cracking facilities to compress manual labor requirements and tighten style-zero yield recovery. Expand co-located oil extraction capacity under REACH-compliant supercritical CO2 processes to capture cosmetic channel margin premiums. Defensive positioning requires absorbing pollination labor cost escalation through captive orchard scale rather than spot-market kernel procurement exposure to alternate-bearing volatility. For New Entrants and Emerging Players: Capture underpenetrated Chinese direct-to-consumer in-shell gifting channels through e-commerce platform partnerships that bypass traditional nut-import wholesale margin stacking. Target bakery ingredient applications seeking clean-label fat sources as the most penetrable food industry segment with lower certification documentation burdens than confectionery whole-kernel placement. Go-to-market execution hinges on infrared dry-roasting equipment deployment from German turnkey line suppliers. For Investors and Strategic Acquirers: Consolidation of Lowveld estate acreage by scale-driven processors is the leading indicator that kernel supply security is becoming the dominant competitive moat. Five-to-ten year viability favors vertically integrated operators with backward integration into flowering-to-cracking control and documented pollination protocols. Acquisition screening should prioritize Queensland or South African estate operators with pasteurization validation infrastructure. Watch for phytosanitary certification backlogs extending commercialization schedules as the inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Orchards | Hawaiian Host Group's flowering-to-cracking control secures raw nut quality consistency for confectionery manufacturers. |
| Hyperspectral Sorting Technology Deployment | Marquis Macadamias' NIR-based defect detection compresses manual labor while tightening whole-kernel gift channel yields. |
| Co-located Oil Extraction Capacity | German supercritical CO2 processing under REACH compliance secures EU cosmetic ingredient dossier approvals for dermal applications. |
| Direct-to-Consumer Platform Launch | E-commerce penetration into Chinese retail bypasses traditional nut-import wholesale layers for in-shell gifting traditions. |
| Pasteurization Validation Infrastructure | USDA Agricultural Marketing Service grade standards require lot-specific pathogen reduction certificates that extend commercialization schedules. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs combining with primary interviews across orchard operations managers, kernel processing facility engineers, confectionery procurement directors, and cosmetic ingredient formulators. Australian Department of Agriculture biosecurity protocols, South African export documentation requirements, and USDA Agricultural Marketing Service grade standards provided regulatory validation layers. Bottom-up orchard stock assessments and top-down export volume triangulation calibrated supply-side estimates.
Granularity-level modeling deployed kernel style grade segmentation, processing intensity tiers, application channel differentiation, and geographic origin clustering across the analysis window. CAGRs derived from weighted average of historical shipment trajectories and forward capacity expansion announcements. Pollination labor cost indices and alternate-bearing cycle intensity assumptions shaped orchard revenue predictability inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biosecurity protocol amendments and bee colony health disruptions. Model outputs reflect assumptions around pollination service availability and phytosanitary certification processing timelines. A model refresh is warranted upon material change in Australia's Biosecurity Act screening protocols or USDA grade standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuts and Seeds
Nut Oil Market
Nuts and Seeds
Dry Fruits Market
Nuts and Seeds
Nut Butters Market
Nuts and Seeds
Nut Ingredients Market
Nuts and Seeds
Nuts Market
Nuts and Seeds
Almond Protein Market
Nuts and Seeds
Apricot Kernel Powder Market
Nuts and Seeds
Carob Market
Nuts and Seeds
Saudi Arabia Nuts Market
Nuts and Seeds
Dry Roasted Almonds Snack Market
Nuts and Seeds
North America Moringa Products Market
Nuts and Seeds
Nutmeg Market
Nuts and Seeds
Almond Oil Market
Nuts and Seeds
Fruit Kernel Products Market
Nuts and Seeds
India Cashew Market
Nuts and Seeds
Fox Nuts Market