
 Hard Surface Flooring Market | 2026-2036
Hard Surface Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Hard Surface Flooring Market Intelligence
Chinese rigid core vinyl producers is expanding manufacturing footprints across Zhejiang and Jiangsu provinces to serve export and domestic contract channels. Mohawk Industries leverages integrated resin compounding and print-film operations to control cost layers across laminate and LVT lines. Shaw Industries Group sustains domestic carpet-to-hard surface conversion through dedicated rigid flooring campuses in Georgia and Tennessee. Tarkett anchors European specification markets with phthalate-free formulation leadership and healthcare-sector certifications.
Hard surface flooring encompasses factory-finished plank, tile, and sheet materials manufactured from wood fibers, mineral cores, PVC resins, or fired clays, typically measuring 2–12 mm in thickness and rated for abrasion resistance under ASTM D4060 or EN 13329 protocols. These surfaces serve commercial and residential environments where moisture tolerance, load-bearing capacity, and design longevity outweigh carpet or soft flooring alternatives. Vinyl and laminate categories capture the fastest specification growth in residential renovation and multifamily construction, with waterproof rigid-core constructions displacing traditional glue-down sheet and thin-profile products. Ceramic tile retains margin concentration in hospitality and institutional channels where slip resistance, fire ratings, and lifecycle durability drive procurement decisions. Hardwood occupies premium residential positioning but faces volume pressure from engineered alternatives and imported tropical species restrictions.
EPA TSCA Title VI governs composite wood formaldehyde emissions in US residential applications, compelling laminate producers to certify core boards through third-party testing bodies. EU REACH restrictions on phthalate plasticizers and the F-Gas Regulation's indirect pressure on PVC supply chains reshape European vinyl formulation strategies. California Air Resources Board (CARB) Phase 2 standards extend de facto national compliance benchmarks for North American distribution. Stakeholders must monitor evolving state-level PFAS restrictions and EPD program adoption as specification gatekeepers in commercial and public-sector procurement tighten material disclosure requirements.
Market Dynamics
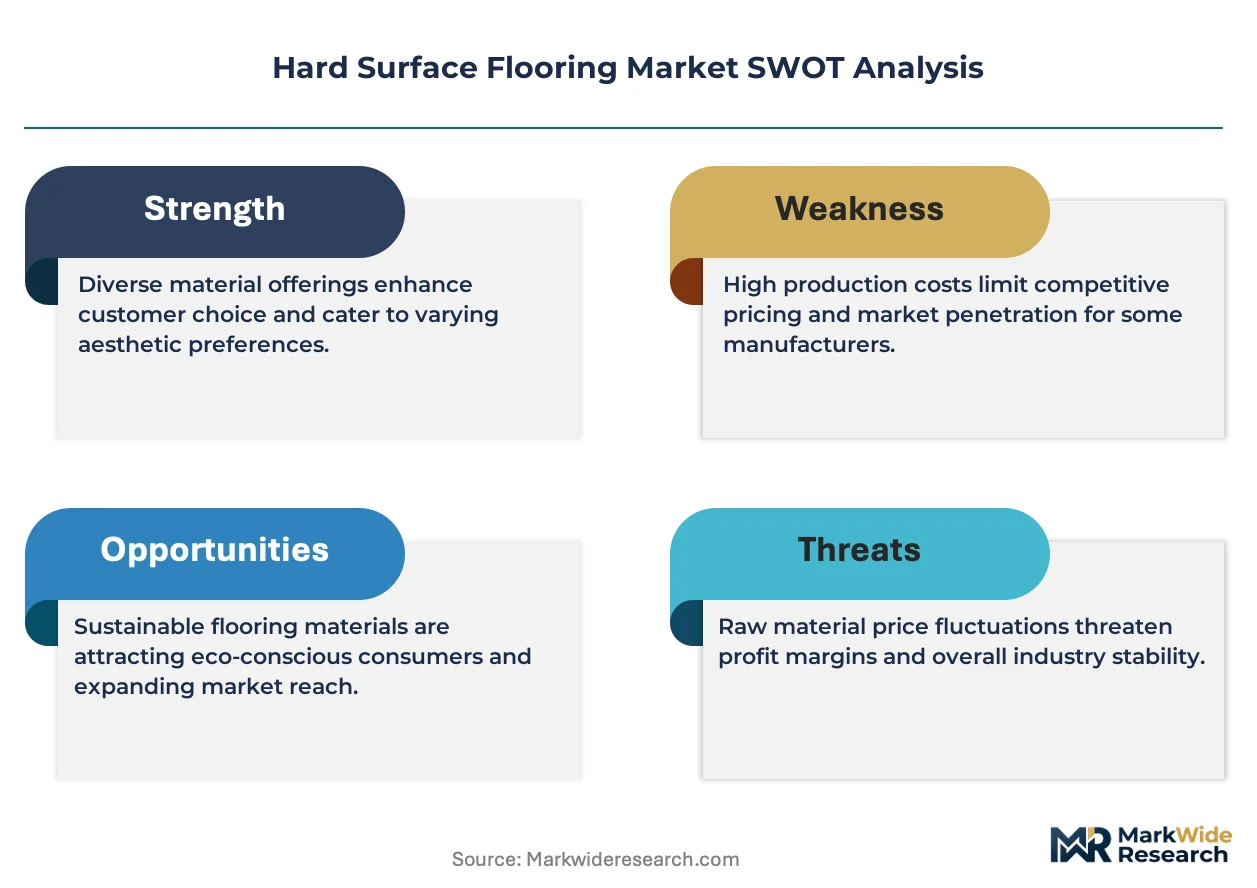
Waterproof rigid-core vinyl is electrifying residential renovation demand while formaldehyde emission standards compress laminate supply chains across North American and European distribution channels.
Growth Catalysts
- GB 18580-2017 standards:China's tightened formaldehyde limits for wood-based panels accelerate certified laminate production for export markets.
- Multifamily housing construction:US developers specify SPC and WPC rigid-core vinyl for moisture-prone unit interiors.
- Digital print-film technology:High-definition surface replication enables ceramic and stone aesthetics at reduced material cost.
Market Restraints
- Resin price volatility:PVC and plasticizer input costs fluctuate with petrochemical feedstock markets, compressing vinyl margins.
- Hardwood substitution threat:Engineered wood and imported tropical species retain premium residential positioning despite tropical timber restrictions.
- REACH phthalate restrictions:ECHA classification of DEHP and DBP limits formulation flexibility for European vinyl producers.
Strategic Opportunities
- Healthcare certification pathways:Phthalate-free and low-VOC formulations unlock specification in hospital and aged-care procurement.
- Direct-to-installer platforms:Digital ordering systems bypass traditional distributor layers in US residential renovation channels.
- India urban housing corridors:Commercial real estate development in Mumbai and Bangalore drives ceramic and laminate specification for retail and office footprints.
Industry Challenges
- Third-party certification timelines:EPA TSCA Title VI and CARB Phase 2 testing protocols extend product launch cycles for laminate producers.
- Print-film technical talent scarcity:Shortage of specialists in rotogravure and digital surface decoration limits production scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hard Surface Flooring Market |
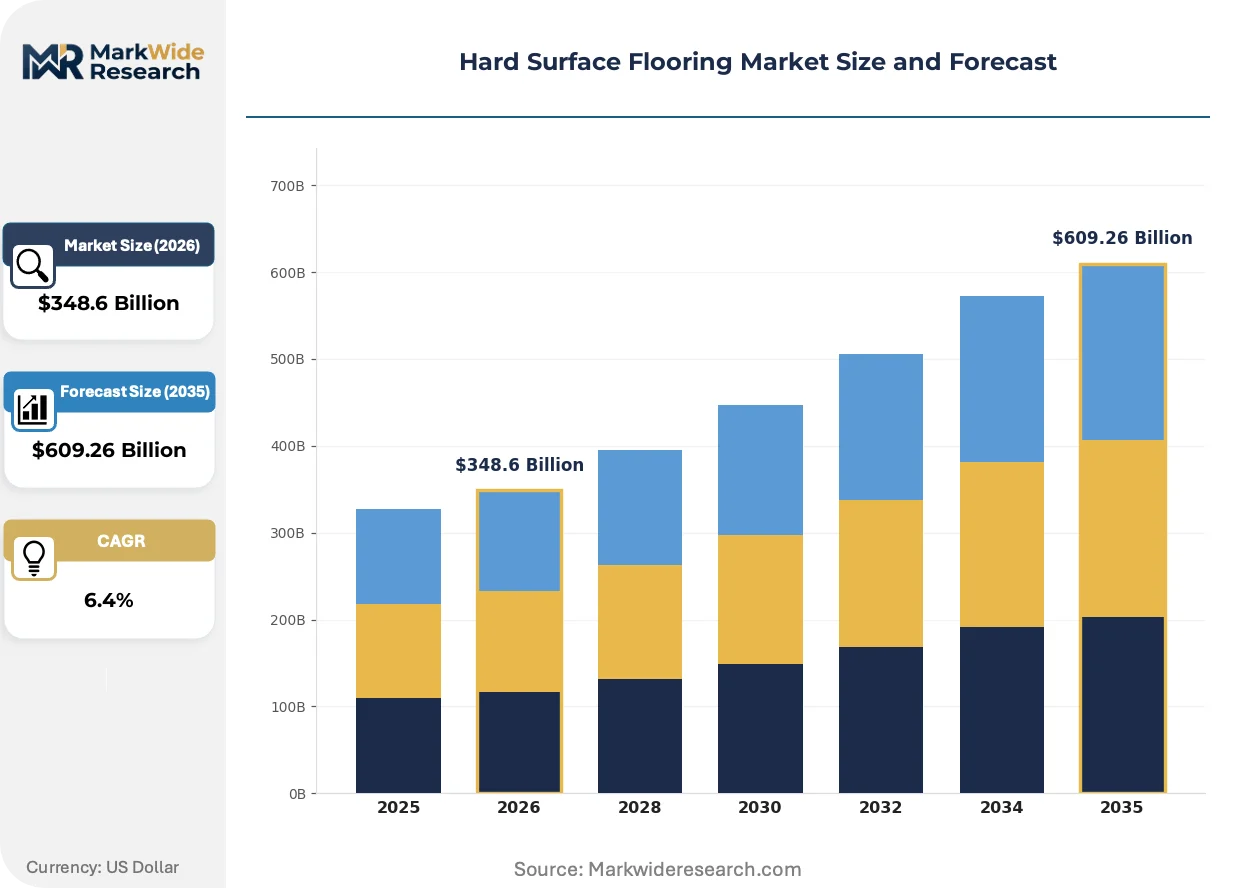
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $609.26 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminate, Vinyl, Hardwood, Ceramic Application: Residential, Commercial, Industrial, Hospitality Thickness: Thin, Standard, Thick, Extra Thick Installation Method: Glue Down, Floating, Nail Down, Click Lock |
| Companies Covered | Mohawk Industries, Shaw Industries Group, Tarkett, Armstrong Flooring, Gerflor Group, Forbo Holding AG, Mannington Mills, Beaulieu International Group, Interface, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hard Surface Flooring Market Strategic Shifts & Innovations
Surface replication fidelity and installation speed are reshaping competitive positioning across vinyl, laminate, and engineered wood categories. Material scientists and flooring architects are prioritizing click-lock mechanical systems over adhesive-dependent methods.
Photorealistic digital printing is electrifying rigid-core vinyl aesthetics. The technology embeds ceramic, stone, and exotic wood visuals into wear layers with 0.3mm resolution. US multifamily developers and renovation contractors specify these products for accelerated installation schedules. This capability is compressing demand for thin-profile glue-down sheet vinyl and traditional laminate in moisture-exposed residential zones.
EU F-Gas Regulation is reshaping PVC supply chain chemistry. The policy framework restricts hydrofluorocarbon use in foam expansion processes, compelling European vinyl producers to adopt physical foaming agents. Rigid-core SPC and WPC construction methods face reformulation pressure. German and Belgian manufacturers are accelerating mineral-core hybrid development to reduce polymer dependence.
Renovation contractors are consolidating material sourcing through specialized distributor platforms. These intermediaries bundle specification support, logistics, and installation training for independent flooring installers. The model displaces traditional two-step distribution through broadline building material wholesalers. This pattern concentrates in US metropolitan renovation corridors where project velocity demands single-source material and technical support.
Hard Surface Flooring Market Segmentation
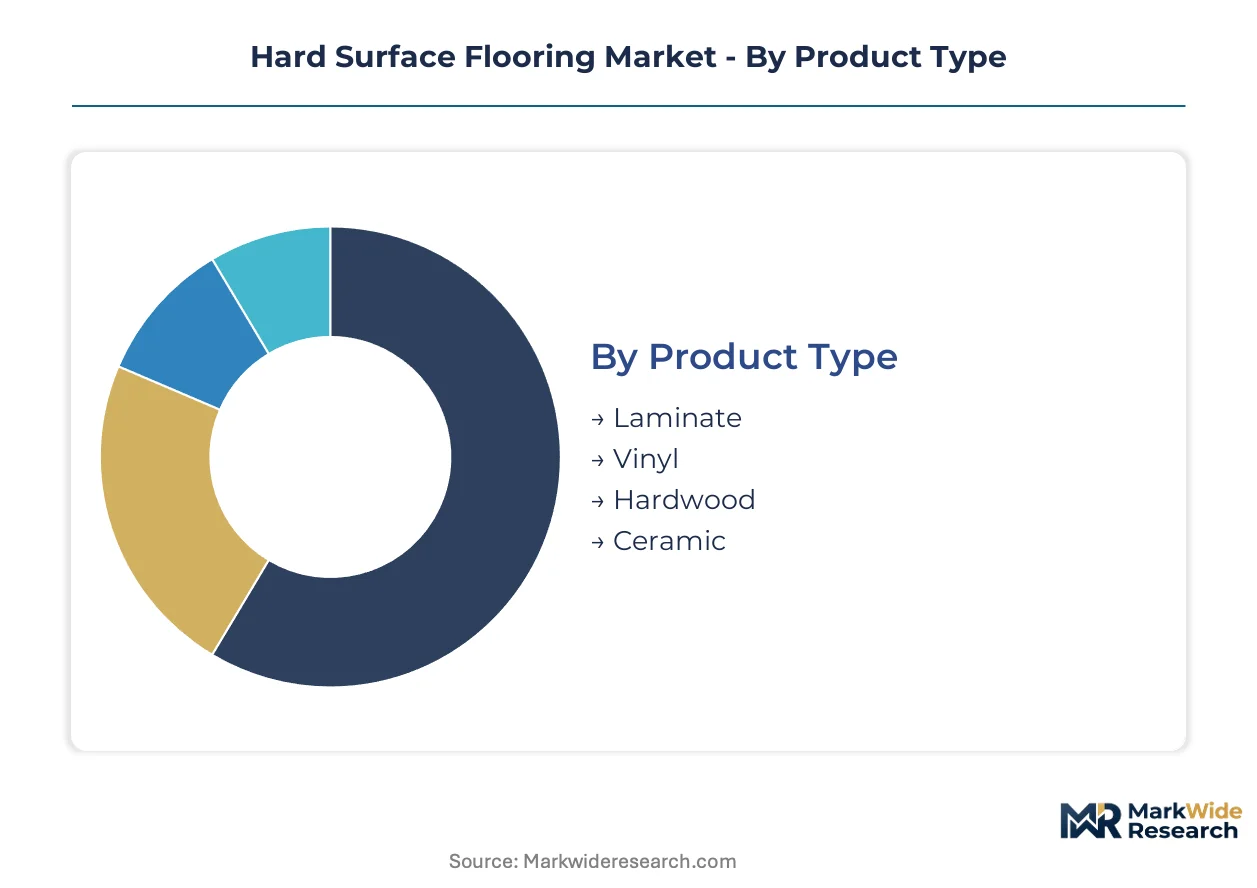
Hard surface flooring procurement hinges on moisture tolerance, load-bearing requirements, and installation speed. Specification patterns diverge sharply between residential renovation channels demanding waterproof rigid-core constructions and institutional buyers prioritizing lifecycle durability over upfront material cost.
Product Type:
Volume concentrates in vinyl and laminate categories where waterproof rigid-core constructions displace traditional glue-down sheet products. Premium positioning remains contested between engineered alternatives and certified low-emission hardwood.
- Vinyl:PVC resin and mineral composite cores form SPC and WPC constructions rated for continuous moisture exposure. US multifamily developers specify rigid-core vinyl for bathroom and kitchen installations where traditional laminate fails. Waterproof performance and click-lock installation accelerate specification in residential renovation corridors.
- Laminate:High-density fiberboard cores with aluminum oxide wear layers replicate hardwood aesthetics at reduced cost. China's GB 18580-2017 formaldehyde standards compress supply chains for North American and European export certification. Core board sourcing from certified mills extends product launch timelines.
- Hardwood:Solid and engineered constructions from oak, maple, and hickory species occupy premium residential positioning. Tropical timber restrictions and engineered substitution limit volume expansion.
- Ceramic:Fired clay bodies with glazed or unglazed surfaces deliver slip resistance and fire ratings for institutional procurement. Hospitality and healthcare sectors specify large-format porcelain for lobby and corridor applications.
Mature deployment sits with ceramic in hospitality and institutional channels. Newer deployment is concentrated in vinyl rigid-core constructions for moisture-prone residential interiors.
Application:
Cost tier stratification separates high-velocity residential renovation from specification-intensive commercial procurement. End-use requirements dictate abrasion resistance ratings and warranty terms.
- Residential:Single-family and multifamily housing drives volume for laminate and vinyl categories. Waterproof rigid-core products displace traditional sheet vinyl in bathroom and basement applications. Digital print-film technology enables stone and ceramic aesthetics at reduced installed cost.
- Commercial:Office and retail footprints specify ceramic and laminate surfaces for traffic density and design longevity. Procurement teams prioritize lifecycle cost over upfront material expense. EPD program adoption and material disclosure requirements tighten specification gatekeeping.
- Industrial:Manufacturing and warehouse environments demand load-bearing capacity and chemical resistance. Epoxy-modified concrete and heavy-duty vinyl sheet dominate where abrasion and impact resistance outweigh aesthetic considerations.
- Hospitality:Hotels and restaurants balance slip resistance, acoustic performance, and design flexibility. Luxury vinyl tile and large-format ceramic capture specification for lobby, corridor, and guest room applications.
Volume deployment concentrates in residential channels. Specification complexity and margin concentration sit with hospitality procurement teams.
Thickness:
Application durability requirements and subfloor conditions determine thickness selection. Standard and thick profiles dominate current specification.
- Thin:2–4 mm profiles serve overlay applications and budget-conscious renovation. Glue-down installation methods predominate.
- Standard:5–7 mm constructions balance material cost with structural stability. Floating and click-lock systems accommodate minor subfloor irregularities.
- Thick:8–10 mm cores deliver acoustic dampening and underfoot comfort. Premium residential and light commercial applications specify this tier.
- Extra Thick:11–12 mm constructions maximize dimensional stability and sound absorption. High-end residential and hospitality channels absorb material cost premiums.
Standard thickness represents the volume anchor across residential and commercial segments. Extra thick deployment climbs fastest in premium renovation and hospitality specification.
Installation Method:
Project velocity and labor cost structure determine method selection. Mechanical fastening systems displace adhesive-dependent approaches in time-sensitive applications.
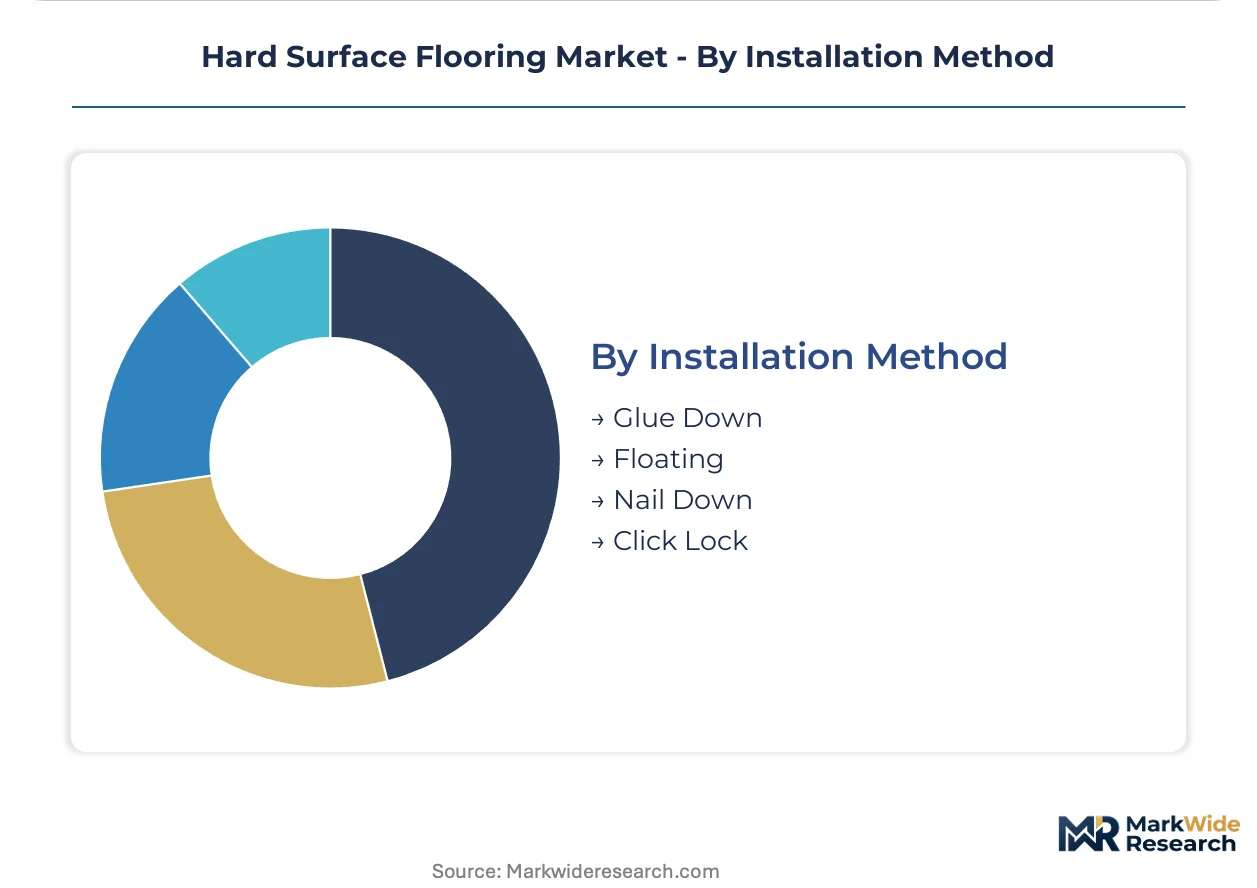
- Glue Down:Full-spread adhesive application delivers permanent bond for sheet vinyl and thin-profile luxury vinyl tile. Commercial settings with heavy rolling loads specify this method despite extended cure times and skilled labor requirements.
- Floating:Interlocking edges and foam underlayment create suspended floors without subfloor attachment. Laminate and engineered hardwood categories dominate this method for residential renovation speed.
- Nail Down:Solid and engineered hardwood planks secure through subfloor penetration. Traditional residential construction and premium renovation retain this method despite substrate limitations.
- Click Lock:Precision-milled mechanical joints enable tool-free assembly and disassembly. Rigid-core vinyl and laminate categories standardize this system for installer productivity and moisture resistance.
Click lock systems gain share fastest in residential renovation and multifamily construction. Glue down methods retain specification where permanent bond and load distribution outweigh installation speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clay deposits in Sassuolo, Italy anchor European ceramic tile production, while PVC resin corridors along the US Gulf Coast supply North American vinyl flooring manufacturers. Zhejiang and Jiangsu provinces in China concentrate rigid-core vinyl fabrication for export markets.
United States
Multifamily housing construction in Atlanta and Dallas drives rigid-core vinyl specification for moisture-prone unit interiors. EPA TSCA Title VI governs composite wood formaldehyde emissions, compelling laminate producers to certify core boards through third-party testing bodies. Georgia and Tennessee host dedicated rigid flooring campuses serving domestic carpet-to-hard surface conversion.
China
Urban housing corridors in Shanghai and Shenzhen generate ceramic and laminate demand for retail and office footprints. GB 18580-2017 standards tighten formaldehyde limits for wood-based panels, accelerating certified laminate production for export markets. Manufacturing clusters across Zhejiang and Jiangsu provinces expand rigid-core vinyl capacity to serve export and domestic contract channels.
Germany
Healthcare and hospitality procurement in Berlin and Munich prioritizes phthalate-free formulations and lifecycle durability. EU REACH restrictions on phthalate plasticizers and the F-Gas Regulation reshape vinyl formulation strategies across German production facilities. The country's flooring architects specify large-format porcelain for lobby and corridor applications.
India
Commercial real estate development in Mumbai and Bangalore drives ceramic and laminate specification for retail and office footprints. BIS certification requirements tighten material quality benchmarks for imported and domestically manufactured flooring products. Manufacturing corridors in Gujarat and Maharashtra expand production capacity to serve domestic urban housing demand.
Belgium
Healthcare-sector certifications in Brussels and Antwerp procurement channels prioritize low-VOC and phthalate-free formulations. ECHA classification of DEHP and DBP limits formulation flexibility for vinyl producers serving European specification markets. Belgian manufacturers accelerate mineral-core hybrid development to reduce polymer dependence under F-Gas Regulation pressure.
Hard Surface Flooring Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue waterproof rigid-core specializations and direct-to-installer distribution platforms. The vendor base stratifies across integrated resin compounders, print-film operators, and specification-focused certification leaders. Three archetypes dominate: multinational flooring conglomerates with captive raw material operations, regional specialists in healthcare and hospitality certification, and digital-native platforms bypassing traditional distributor layers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing backward integration into resin compounding and surface decoration technologies.
Among US-based integrated manufacturers, Mohawk Industries and Shaw Industries Group exemplify the conglomerate archetype with captive supply chain control. Tarkett anchors the European specification tier through phthalate-free formulation leadership. These three entities represent distinct geographic and strategic positioning within the competitive structure, spanning North American volume production and European regulatory compliance specialization.
| Leading Market Players |
|---|
| Mohawk Industries |
| Shaw Industries Group |
| Tarkett |
| Armstrong Flooring |
| Gerflor Group |
| Forbo Holding AG |
| Mannington Mills |
| Beaulieu International Group |
| Interface |
| Others |
Cost & Logistics Intelligence
EPA TSCA Title VI certification requirements gate qualified laminate supply and premium-tier pricing access for residential renovation channels. Compliance testing timelines compress product launch velocity while certified producers command material premiums over uncertified competitors.
Pricing Analysis
Warranty and installation-service bundling separates premium rigid-core vinyl offerings from unbundled economy-tier products. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales support depth. Price differentiation stems from waterproof performance ratings and click-lock system complexity. Cost compression in standard laminate tiers intensifies because Chinese GB 18580-2017 compliance extends core board sourcing timelines. Multifamily developers exhibit highest price sensitivity; hospitality procurement teams show lowest sensitivity due to lifecycle cost prioritization.
Supply Chain Analysis
Rotogravure and digital print-film specialist scarcity in Zhejiang and Jiangsu provinces constrains surface decoration capacity expansion. Manufacturing gravity centers on China, the United States, and Belgium for rigid-core vinyl fabrication. Raw material flows draw from PVC resin corridors along the US Gulf Coast, mineral core suppliers in Guangdong, and wear-layer film producers in Germany. Single-source vulnerability sits with phthalate-free plasticizer formulations under ECHA REACH restrictions. Distribution runs through specialized flooring distributor platforms that bundle specification support and logistics for independent installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as formaldehyde emission certification costs force sub-scale laminate producers toward exit or acquisition.
For Market Incumbents: Lock in backward integration into resin compounding and print-film operations to defend margin position against PVC price volatility. Secure EPA TSCA Title VI and CARB Phase 2 certification capacity before third-party testing bottlenecks worsen. Acquire regional healthcare-certification specialists in Germany and Belgium to anchor European specification markets. For New Entrants and Emerging Players: Direct-to-installer platforms offer the most penetrable channel for bypassing traditional distributor markups in US metropolitan renovation corridors. Target waterproof rigid-core vinyl specialization for multifamily bathroom and kitchen applications where laminate fails. Pursue white-label manufacturing partnerships with Zhejiang-based fabricators to compress capital requirements. For Investors and Strategic Acquirers: Mineral-core hybrid patent filings are the leading indicator that polymer-dependent producers face F-Gas Regulation reformulation pressure. The five-to-ten year viability window favors acquisition targets with captive resin supply and healthcare-sector certification depth. Watch for EPD program adoption acceleration in commercial procurement as the inflection signal for material disclosure gatekeeping.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Mohawk Industries and Shaw Industries Group control PVC input costs through captive Gulf Coast supply. |
| Healthcare Certification Investment | Tarkett anchors European hospital procurement through phthalate-free formulation leadership. |
| Direct-to-Installer Platform Launch | Digital ordering systems bypass traditional distributor layers in Atlanta and Dallas renovation corridors. |
| Mineral-Core Hybrid Development | Belgian manufacturers accelerate polymer reduction under EU F-Gas Regulation foam expansion restrictions. |
| GB 18580-2017 Compliance Scale-Up | Certified Chinese laminate producers capture North American export share as uncertified competitors exit. |
Research Approach
Independent corroboration across flooring plant managers, distributor procurement leads, contractor installation crews, and specification architects underwrites the qualitative findings. Primary interviews with resin compounding technical directors and print-film R&D heads combined with secondary validation from customs trade data, EPA certification registries, and SEC 10-K filings. Bottom-up volume triangulation across product thickness tiers and installation method categories cross-references top-down value aggregation across residential, commercial, and hospitality end-uses.
Comparable-period anchoring to pre-pandemic renovation velocity and post-2020 multifamily construction surge establishes the forecast baseline across the analysis window. Segmentation modeling incorporates product type, application durability requirements, thickness profile, and installation system complexity. CAGRs derive from fitted growth curves applied to certified laminate production capacity and rigid-core vinyl specification penetration. Forecast inputs include EPA enforcement intensity for TSCA Title VI and ECHA REACH phthalate restriction implementation pace.
Caveats apply where resin price volatility, state-level PFAS restriction expansion, or print-film technical talent scarcity could materially shift the outlook. Forecasts reflect documented assumptions about certification timeline normalization and healthcare procurement EPD adoption velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
Global Flooring and Carpet Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market